
 Global Display Market | 2026-2036
Global Display Market Size, Share, and Industry Trends Forecast 2026-2036
Global Display Market Analysis
MicroLED and tandem OLED stack architectures are fragmenting the traditional LCD-dominated supply chain into parallel technology lanes with divergent capital requirements. Samsung Display leverages its vertical integration across semiconductor backplanes and emitter deposition to sustain leadership in premium mobile panels. BOE Technology Group anchors massive Gen 10.5 LCD and emerging OLED capacity in mainland China, while Japan Display specializes in automotive-grade LTPS LCDs for tier-one cockpit suppliers.
A display is an optoelectronic output device comprising a matrix of pixels driven by thin-film transistors on glass or flexible polymer substrates, modulating emitted or transmitted light to render visual information for human-machine interfaces. LCD panels still dominate volume shipments for televisions and desktop monitors, though OLED captures the margin pool in smartphones and premium laptops due to self-emissive architecture and superior contrast ratios. Interactive and digital signage technologies are expanding fastest in enterprise and retail advertising applications, where touch integration and ambient-light adaptivity command pricing premiums over passive screens.
The U.S. FCC regulates electromagnetic emissions from display modules, while REACH and RoHS in Europe restrict hazardous substances in panel manufacturing and mandate recyclability disclosures. China's GB standards and MIIT directives enforce local content thresholds and energy-efficiency grades for domestic television sales. Stakeholders must monitor which regulatory jurisdiction's certification timeline becomes the binding constraint for next-generation product launches.
Market Dynamics
Technology lane fragmentation is splitting capital allocation between OLED, mini-LED, and MicroLED architectures, forcing display makers to place irreversible bets on divergent equipment sets and emitter chemistries.
Growth Catalysts
- Automotive cockpit digitization:OEMs are expanding OLED and mini-LED adoption for instrument clusters and infotainment systems, creating dedicated specification pipelines for curved and free-form panels.
- EU Ecodesign Directive tightening:Efficiency requirements for television and monitor panels are accelerating replacement cycles in European consumer markets.
- South Korean manufacturing concentration:Samsung Display and LG Display anchor advanced OLED capacity, drawing upstream material suppliers and equipment makers into clustered ecosystem investments.
Market Restraints
- Indium gallium zinc oxide (IGZO) sputtering targets:Supply volatility in rare earth refining constrains backplane scaling for high-resolution panels.
- Gen 8.5+ OLED deposition equipment:Canon Tokki's near-monopoly on vacuum thermal evaporation systems creates single-source vulnerability for new fab ramp schedules.
- Technical limitation in blue emitter lifetime:Tandem OLED stacks partially compensate but add 15-20% cost premium versus single-stack architectures.
Strategic Opportunities
- India display manufacturing incentives:PLI scheme subsidies for semiconductor and display fabs are attracting module assembly investments from East Asian supply chain players.
- Transparent OLED retail signage:Department stores and automotive showrooms are piloting see-through displays for immersive product presentation.
- MicroLED-AR convergence:Silicon-based micro-LED microdisplays are enabling waveguide-compatible near-eye projection for industrial training and surgical navigation.
Industry Challenges
- Quantum dot ink formulation chemists:Talent scarcity in colloidal synthesis and ligand engineering delays cadmium-free QD-LED commercialization timelines.
- FMM (fine metal mask) alignment tolerances:Sub-micron registration requirements for RGB side-by-side deposition drive yield loss in Gen 6 OLED fabs.
- Multi-jurisdiction certification overlap:Simultaneous FCC, REACH, and GB standard compliance creates sequential testing bottlenecks for new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Display Market |
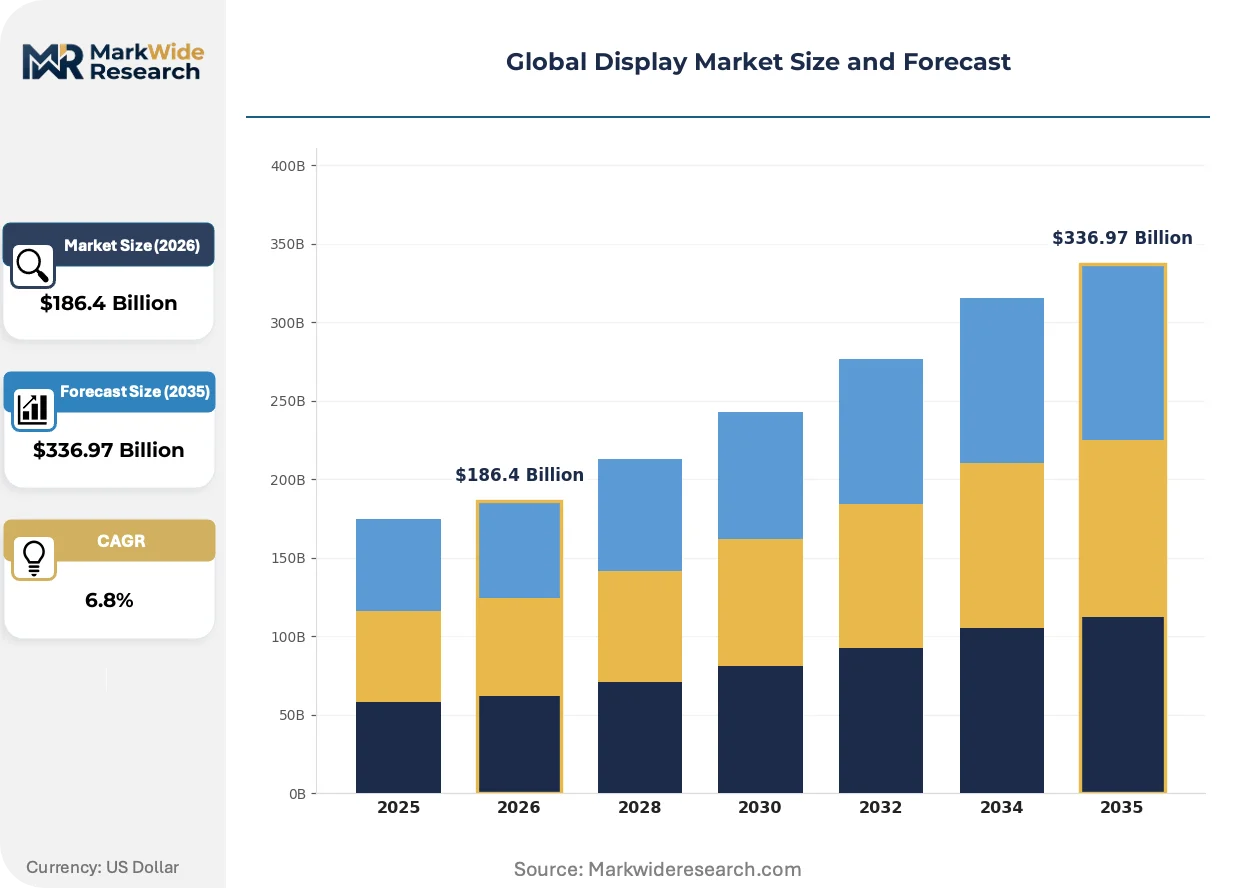
| Market Size in 2026 | $186.4 Billion |
| Market Size in 2035 | $336.97 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, LED, OLED, QLED Technology: Smart, Digital Signage, Interactive, Curved Application: Consumer Electronics, Automotive Displays, Retail Advertising, Industrial Monitors End User: Households, Enterprises, Government, Educational Institutions |
| Companies Covered | Samsung Display, LG Display, BOE Technology Group Co., Ltd., AUO Corporation, Innolux Corporation, Sharp Corporation, Japan Display Inc., Sony Corporation, TCL China Star Optoelectronics Technology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Display Market Emerging Trajectories
Display architecture is converging on self-emissive technologies while manufacturing processes adopt semiconductor-grade precision, compressing the traditional LCD-dominated supply chain into parallel technology lanes.
Tandem OLED stacks are collapsing the brightness-to-lifetime tradeoff that constrained single-stack architectures in premium mobile and notebook applications. Automotive HUD suppliers and flagship smartphone brands are adopting two-stack configurations for 2,000+ nit peak luminance. This compression is enabling OLED penetration into outdoor-readable applications previously reserved for high-brightness LCD with local dimming zones.
REACH substance restrictions and RoHS hazardous substance limits are tightening material qualification requirements for European-bound panels. ECHA's expanded candidate list now captures additional organometallic emitters and photoresist solvents, forcing reformulation of established supply chain chemistries. Panel makers serving EU markets are accelerating halogen-free substrate and barrier film validation programs to maintain market access.
Specification consolidation among hyperscale cloud service providers is reshaping procurement patterns for data center monitoring and control room video walls. Meta, Microsoft, and Amazon Web Services are issuing unified technical requirement documents that compress vendor qualification from dozens to handfuls of approved suppliers. This concentration is most visible in North American and Western European enterprise display deployments, where single-source agreements now cover multi-year refresh cycles.
Global Display Market Segmentation
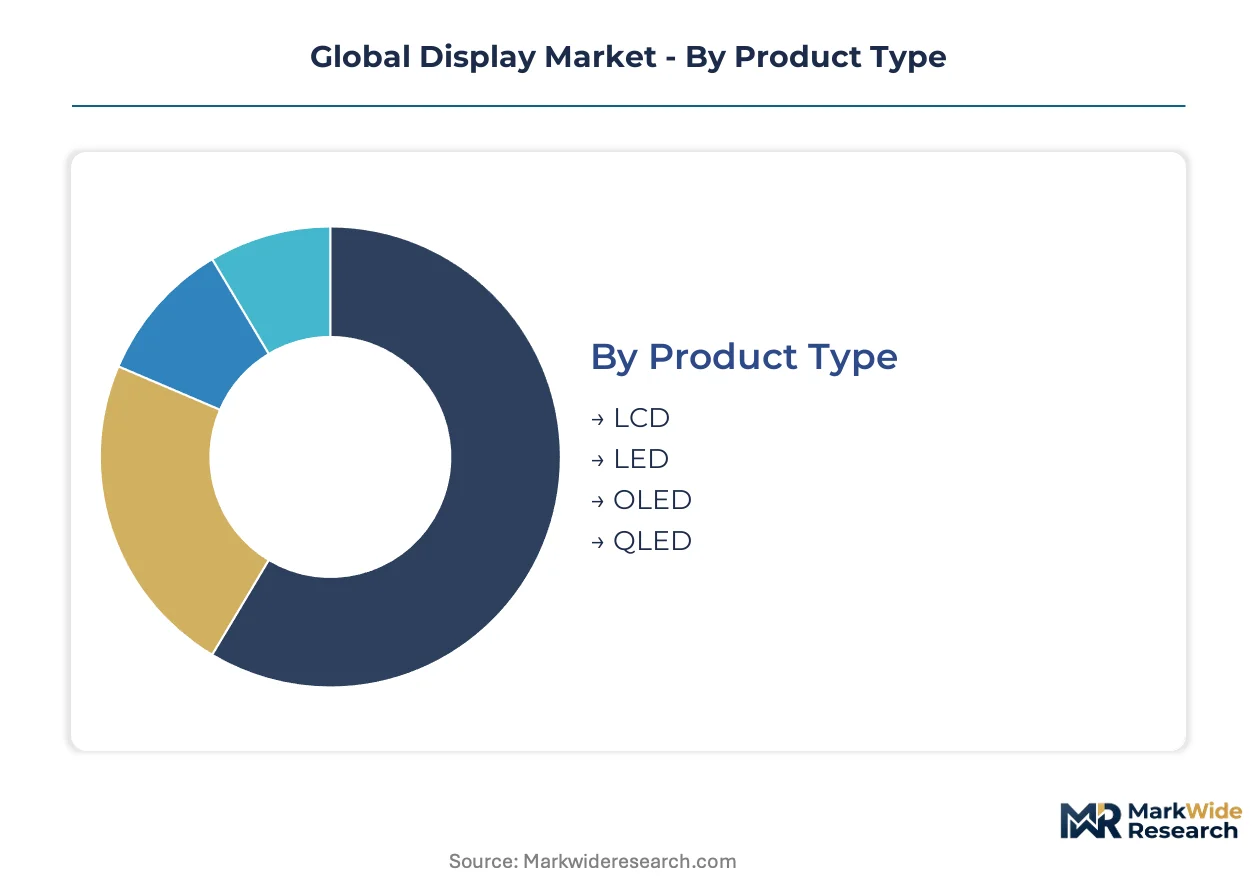
Display market segmentation reveals how technology architecture, deployment context, and buyer economics partition demand into discrete procurement channels with divergent specification requirements and margin structures.
Product Type:
Cost tier differentiates panel technologies by manufacturing complexity, material inputs, and end-use pricing power.
- LCD:Liquid crystal panels modulate backlight transmission through nematic crystal orientation on glass substrates. Household television demand in India and Southeast Asia sustains Gen 10.5 fab utilization, though ASP compression from Chinese overcapacity constrains margin recovery.
- OLED:Organic light-emitting diode stacks deposit red, green, and blue emissive layers through vacuum thermal evaporation, eliminating backlight assemblies. South Korean smartphone brands and premium notebook OEMs concentrate procurement for foldable and always-on display applications where contrast ratio and form factor flexibility command 40-60% premiums over LCD equivalents.
- LED:Direct-view LED arrays package discrete diodes for large-format commercial installations. Stadium and outdoor advertising deployments in Saudi Arabia and UAE drive pitch-density requirements below 1.2mm for close-viewing indoor applications.
- QLED:Quantum dot-enhanced LCD integrates photoluminescent nanocrystal films to expand color gamut coverage. Samsung and TCL anchor volume production for mid-premium television tiers where DCI-P3 coverage exceeds 90% without OLED burn-in risk.
LCD holds installed capacity across 15+ Gen 8.5+ fabs. OLED is rotating up the share rankings in mobile and premium compute segments.
Technology:
Application context determines integration depth, from passive playback surfaces to sensor-rich interactive systems.
- Smart:Network-connected panels embed SoC processors and streaming application frameworks. North American and Western European household replacement cycles compress as 4K HDR becomes baseline specification.
- Digital Signage:Commercial-grade displays with remote content management and scheduling software. Quick-service restaurant chains and airport operators in Germany, France, and UK consolidate procurement through multi-year managed service agreements.
- Interactive:Touch-integrated panels with projected capacitive or infrared sensing layers. Educational institutions across Japan and South Korea drive classroom whiteboard replacement, while healthcare facilities adopt antimicrobial surface treatments for surgical planning stations.
- Curved:Form-factor variants with 1800R to 3000R radii for immersive gaming and cockpit simulation. Esports venues and automotive design studios specify 21:9 ultrawide configurations with synchronized multi-panel arrays.
Digital signage holds installed capacity in enterprise and transit infrastructure. Interactive is climbing the fastest as touch penetration extends from consumer mobile into B2B collaboration endpoints.
Application:
End-use environment dictates durability, brightness, and certification requirements that fragment procurement specifications.
- Consumer Electronics:Smartphones, tablets, televisions, and wearables requiring high pixel density and low power consumption. Chinese and Vietnamese assembly plants channel 70%+ of global volume through integrated module suppliers.
- Automotive Displays:Instrument clusters, center-stack infotainment, and head-up projection systems. German and Japanese OEMs specify AEC-Q100 qualified panels with -40°C to 85°C operational ranges and anti-glare polarizers for direct sunlight readability.
- Retail Advertising:In-store digital posters, shelf-edge strips, and window-facing high-brightness installations. Department store renovation cycles in Milan, Paris, and New York prioritize 2500+ nit outdoor-readable specifications with ambient light sensors.
- Industrial Monitors:Ruggedized panels for factory automation, process control, and medical imaging. FDA and CE-MDR compliance requirements extend validation timelines for diagnostic radiology and surgical navigation displays.
Consumer electronics holds installed capacity across mobile and television fabs. Automotive displays are gaining share fastest as cockpit digitization accelerates model-year refresh specifications.
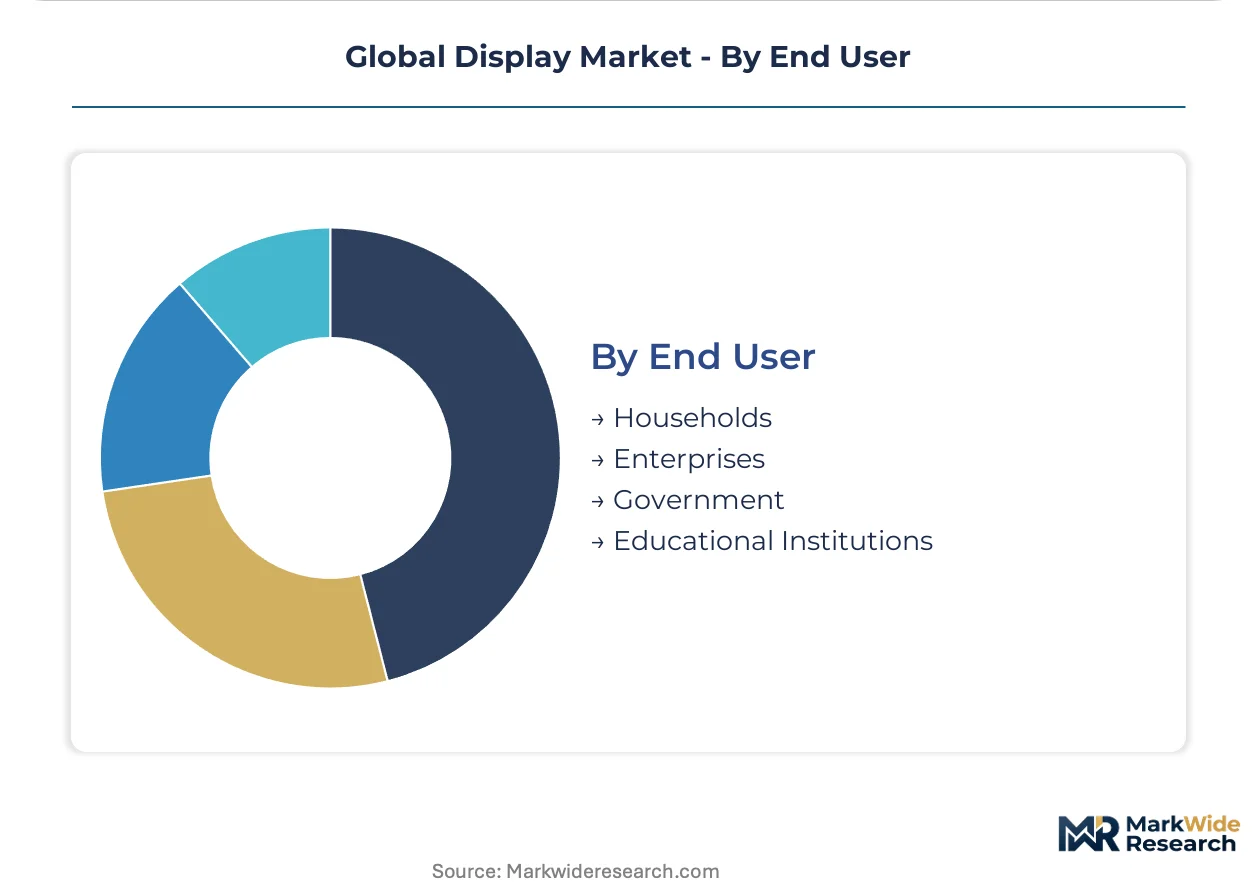
End User:
Customer type determines procurement scale, financing structure, and replacement cycle cadence.
- Households:Individual consumers purchasing through retail and e-commerce channels. Replacement cycles for primary televisions in US and UK households extend toward 7-8 years as panel reliability improves and 8K content scarcity dampens upgrade urgency.
- Enterprises:Corporate IT departments provisioning desktop monitors, conference room displays, and digital signage networks. Hybrid work normalization in Canada and Australia drives unified communications integration with video bars and touch-enabled huddle room panels.
- Government:Public sector procurement for administrative, defense, and infrastructure applications. EU CSRD disclosure requirements and green public procurement directives tighten energy-efficiency thresholds for municipal display deployments.
- Educational Institutions:K-12 and higher education technology budgets for classroom and campus-wide installations. India's PM SHRI schools scheme and Brazil's connected education programs channel federal funding toward interactive flat-panel replacements of legacy projector systems.
Households hold installed capacity across television and monitor installed base. Enterprises are climbing the fastest as return-to-office mandates and AV modernization budgets synchronize refresh cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean display exports flow predominantly to Chinese smartphone assembly plants and North American consumer electronics brands, establishing Seoul and Suwon as critical nodes in the global panel trade corridor.
South Korea
Samsung Display and LG Display anchor advanced OLED manufacturing for mobile and premium television applications. The Ministry of Trade, Industry and Energy (METI) coordinates semiconductor-display cluster investments under the K-Semiconductor Belt initiative. Gyeonggi Province concentrates Gen 6 and Gen 8.5 OLED deposition capacity, drawing Canon Tokki equipment suppliers and photoresist chemical formulators into tight supplier networks.
China
BOE Technology Group and TCL China Star Optoelectronics scale Gen 10.5 LCD and emerging OLED output for domestic television and monitor demand. MIIT enforces GB standards and energy-efficiency grades for domestic panel sales, tightening local content thresholds. The Yangtze River Delta clusters module assembly and driver IC packaging operations around Suzhou and Hefei.
Japan
Japan Display Inc. and Sharp Corporation specialize in automotive-grade LTPS LCDs for German and Japanese OEM cockpit suppliers. METI directs funding toward next-generation display manufacturing under the Society 5.0 technology roadmap. Chubu region around Nagoya hosts precision equipment makers and fine metal mask suppliers serving OLED deposition tool chains.
United States
Meta, Microsoft, and Amazon Web Services consolidate procurement for data center monitoring and enterprise video walls, compressing vendor qualification pools. The FCC regulates electromagnetic emissions from display modules imported for consumer and commercial deployment. Austin and Seattle anchor hyperscale cloud provider engineering teams that issue unified technical requirement documents.
Germany
BMW, Mercedes-Benz, and Volkswagen specify AEC-Q100 qualified panels for instrument clusters and center-stack infotainment. The EU Ecodesign Directive tightens efficiency requirements for television and monitor panels sold across member states. Bavaria hosts automotive Tier 1 suppliers integrating curved and free-form displays into cockpit architectures.
Global Display Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented technology lanes. Samsung Display and LG Display anchor premium OLED supply, while Chinese fabricators scale LCD volume. Three archetypes dominate: vertically integrated Korean majors, Chinese scale-driven producers, and Japanese automotive specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with firms placing irreversible bets on divergent emitter chemistries and deposition equipment.
Within the Korean major tier, Samsung Display Co., Ltd. and LG Display Co., Ltd. exemplify vertically integrated players controlling semiconductor backplane and emitter deposition capabilities. BOE Technology Group Co., Ltd. represents the Chinese scale-driven archetype, anchoring massive Gen 10.5 fab complexes. Japan Display Inc. occupies the automotive-specialist position, concentrating on AEC-Q100 qualified LTPS LCDs for cockpit applications.
| Leading Market Players |
|---|
| Samsung Display |
| LG Display |
| BOE Technology Group Co., Ltd. |
| AUO Corporation |
| Innolux Corporation |
| Sharp Corporation |
| Japan Display Inc. |
| Sony Corporation |
| TCL China Star Optoelectronics Technology Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Canon Tokki's monopoly on Gen 8.5+ OLED deposition equipment concentrates capital equipment pricing power in Chiba Prefecture, Japan, compressing margin pools for panel makers attempting to scale tandem OLED or MicroLED capacity while Korean and Chinese fabs absorb extended lead times and premium equipment markups.
Pricing Analysis
Gen 6 OLED versus Gen 8.5+ OLED versus MicroLED pricing gaps reflect divergent capital intensity and yield maturity. Three-tier pricing structure across premium mobile OLED, standard LCD television, and economy monitor panels stratifies procurement, with AEC-Q100 automotive certification and foldable form factors commanding 40-60% premiums. Pricing pressure stems from Chinese LCD overcapacity in Gen 10.5 fabs. Indian and Southeast Asian household buyers exhibit highest price sensitivity, while German automotive OEMs and hyperscale cloud providers demonstrate lowest.
Supply Chain Analysis
Extended payment terms from South Korean panel makers to Japanese and German equipment suppliers have normalized 180-day cycles, straining working capital for photoresist and fine metal mask vendors. Supply concentrates in South Korea for OLED emitters, China for LCD glass and driver ICs, and Japan for deposition equipment and precision optics. Indium gallium zinc oxide sputtering targets, quantum dot nanocrystals, and organic emitter precursors constitute critical input dependencies. Single-source vulnerability around Canon Tokki evaporation systems creates structural risk. Distribution runs through integrated module suppliers channeling 70% of volume into Chinese and Vietnamese assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Display procurement is converging on platform-economics dynamics as hyperscale cloud providers and automotive OEMs consolidate vendor pools through unified technical requirement documents, compressing qualification from dozens to handfuls of approved suppliers and raising interoperability premiums for ecosystem-integrated panel architectures.
For Market Incumbents: Harden captive supply of semiconductor backplanes and emitter deposition capabilities to defend against Chinese scale-driven entrants expanding Gen 10.5 OLED capacity. Accelerate halogen-free substrate validation to maintain EU market access under ECHA expanded substance restrictions. Prioritize certification investment in AEC-Q100 automotive tiers where replacement cycles synchronize with model-year refreshes. For New Entrants and Emerging Players: Build out module assembly operations in India under PLI scheme subsidies, targeting quick-service restaurant digital signage and educational interactive whiteboard segments where procurement consolidates through multi-year managed service agreements. Establish automotive Tier 2 relationships with German cockpit integrators as the most penetrable premium channel. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed automotive display specialists holding AEC-Q100 qualified LTPS LCD capacity and established OEM relationships. Five-to-ten year viability hinges on MicroLED transfer technology maturation and tandem OLED cost curves. Watch Canon Tokki equipment order backlogs as inflection signal for new fab ramp schedules and capital allocation shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Tandem OLED Stack Commercialization | Enables 2,000+ nit peak luminance for outdoor-readable automotive and mobile applications. |
| Gen 8.5+ OLED Deposition Equipment Securement | Canon Tokki vacuum thermal evaporation systems remain the binding constraint for new fab scaling. |
| India Module Assembly Investment | PLI scheme subsidies attract East Asian supply chain players to capture domestic television demand. |
| Automotive AEC-Q100 Certification | German and Japanese OEMs mandate qualified panels for instrument cluster and infotainment integration. |
| Halogen-Free Substrate Validation | ECHA REACH restrictions force reformulation to maintain EU market access for consumer and commercial panels. |
Methodological Framework
The analysis maps LCD, OLED, LED, and QLED technology lanes, each validated through deposition equipment specialists, panel procurement executives at automotive Tier 1s, semiconductor backplane engineers, and quantum dot material chemists. Primary interview insights triangulate against SEC filings from Samsung Display and LG Display, Canon Tokki equipment shipment disclosures, MIIT GB standard publications, and ECHA substance restriction updates. Bottom-up fab capacity modeling and top-down end-use demand aggregation cross-validate volume and value estimates.
Assumptions held fixed include current Ecodesign Directive efficiency trajectories, Canon Tokki equipment delivery schedules, and observed hyperscaler procurement consolidation patterns; variables include India PLI scheme uptake rates, MicroLED transfer yield improvement curves, and automotive OLED penetration timelines. Segmentation dimensions span product type, technology integration depth, application environment, and end-user procurement scale. CAGRs derive from installed base replacement cycles, content-per-vehicle trends, and cloud infrastructure capex patterns across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese scale-driven players or accelerated tandem OLED adoption by premium smartphone brands would shift outcomes. Macroeconomic contraction in consumer electronics, regulatory acceleration of substance restrictions, or breakthrough MicroLED cost reduction would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Display Technologies
Portable Video Wall Market
Display Technologies
Touch Screen Film Market
Display Technologies
3LCD Projector Market
Display Technologies
Touch and Display Integration IC for Tablet Market
Display Technologies
Multimedia Projectors Market
Display Technologies
Middle East and Africa Transparent Conductive Films Market
Display Technologies
Industrial Display Market
Display Technologies
Electronic Display Signs Market
Display Technologies
Global Display Panel Market
Display Technologies
Digital Holographic Display Market
Display Technologies
TPU Hydrogel Screen Protectors Market
Display Technologies
1440p Gaming Monitors Market
Display Technologies
Large Industrial Displays Market
Display Technologies
4K Drawing Tablet with Screen Market
Display Technologies
Flexible Display Market
Display Technologies
Foldable Display Market