
 Tissue and Hygiene Paper Packaging Market | 2026-2036
Tissue and Hygiene Paper Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tissue and Hygiene Paper Packaging Market Outlook
Multi-source procurement among consumer goods manufacturers is expanding as brands diversify away from single-supplier dependence for tissue and hygiene paper packaging. Georgia-Pacific leverages its integrated pulp-to-package infrastructure across North American mills. Essity sustains European supply leadership through specialized flat-pack and roll-pack lines for personal care customers. Kimberly-Clark competes on brand-controlled channel access, while Sofidel anchors Mediterranean production with recycled fiber specialization.
Tissue and hygiene paper packaging comprises engineered paper substrates—typically 18–35 gsm for napkins, 40–80 gsm for towels—manufactured through wet-laid creping or through-air drying processes, designed to protect, dispense, and present disposable absorbent products in food service, personal care, and healthcare settings. Virgin fiber commands premium positioning in healthcare and personal care applications where softness and purity specifications dominate margin pools, while recycled paper segments face cost compression but gain volume traction in European food service channels where Ecodesign packaging rules tighten material requirements. Biodegradable plastics occupy a narrow transitional niche as converters await scalable fiber alternatives for moisture-barrier wrappers.
EPA guidelines on recycled content claims and the EU Green Deal packaging waste framework shape material sourcing decisions, with REACH chemical compliance adding substrate certification burdens for exporters into European healthcare and personal care segments. FDA food-contact regulations govern napkin and towel substrates deployed in US food service, creating divergence in testing protocols between regional supply chains. Stakeholders must monitor how diverging national packaging EPR schemes reshape cost allocation between virgin and recycled fiber grades.
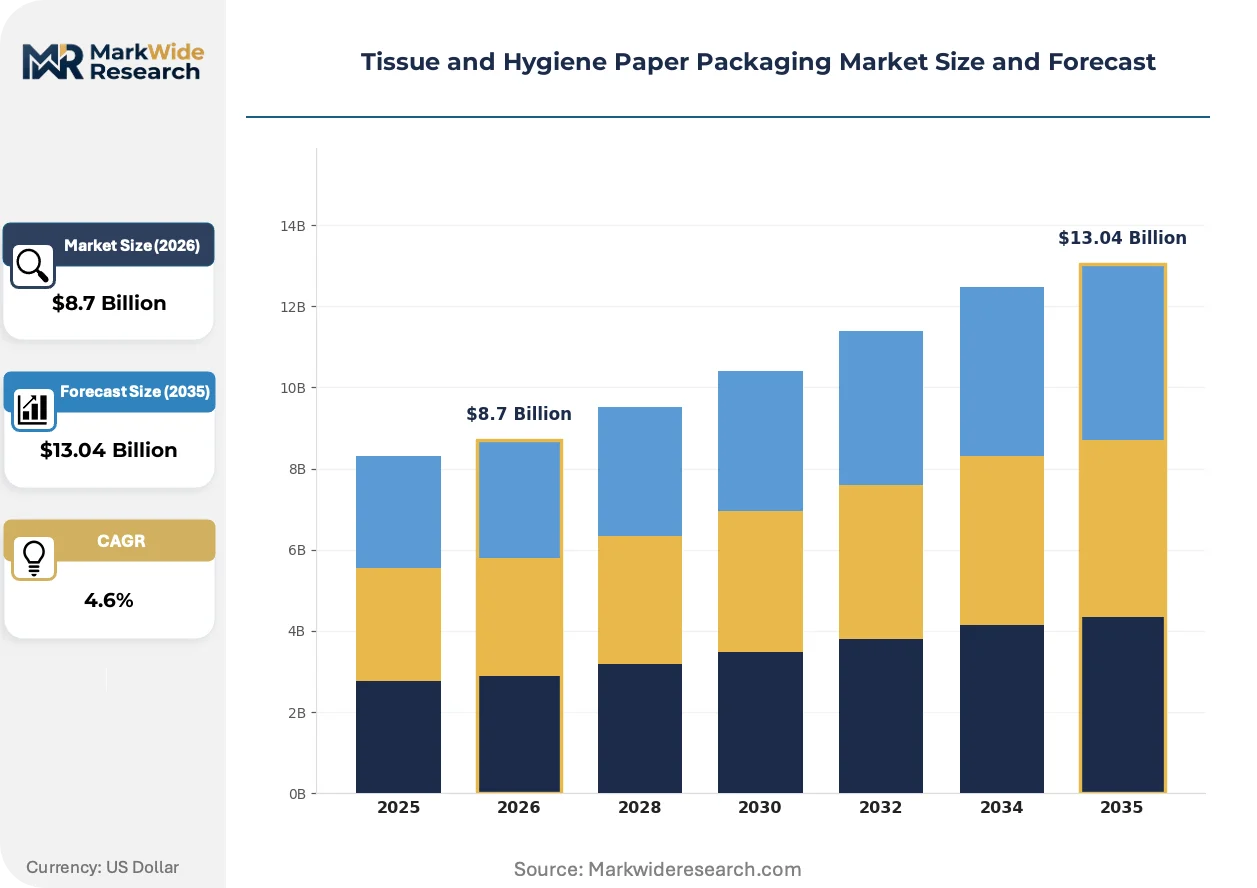
Market Dynamics
The EU Green Deal's packaging waste directives are forcing fiber-based material transitions across European supply chains, compressing demand for conventional plastic wrappers while expanding specifications for engineered paper substrates in food service and personal care channels.
Growth Catalysts
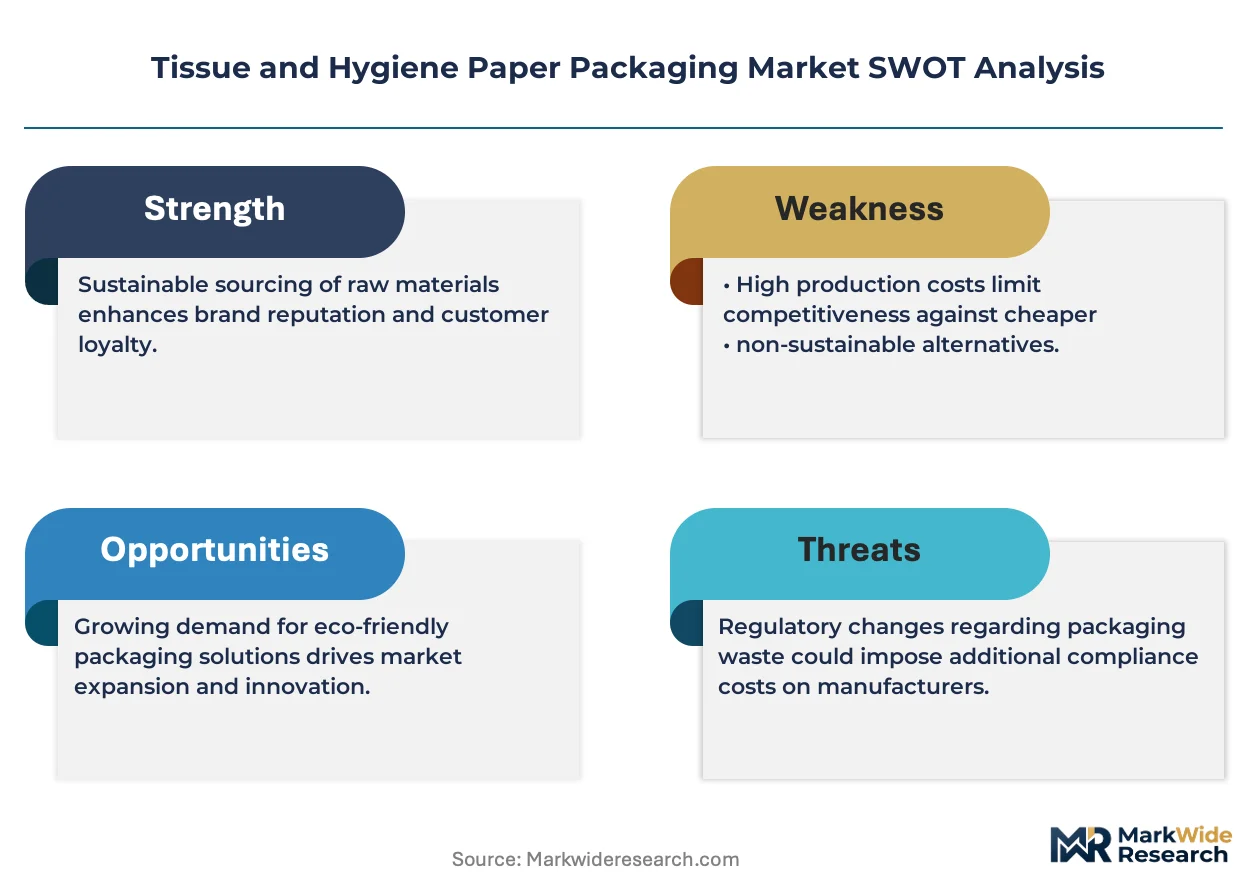
- EU Green Deal packaging mandates:The framework's waste reduction targets accelerate converter investments in recyclable fiber substrates for hygiene product wrappers.
- Food service channel expansion:European restaurant and catering operators are replacing plastic napkins with wet-strength paper alternatives certified under national composting schemes.
- Wet-laid creping process improvements:Advanced through-air drying technologies now deliver 18–35 gsm napkin grades with moisture barrier performance rivaling polyethylene laminates.
Market Restraints
- Virgin pulp cost volatility:Softwood fiber prices fluctuate with Nordic and Canadian harvest cycles, squeezing margin pools for premium healthcare towel specifications.
- REACH chemical compliance burdens:Substrate certification requirements for European healthcare exports create documentation bottlenecks extending procurement timelines.
- Biodegradable plastic substitution threat:PHA and PLA barrier films retain moisture protection advantages for high-humidity personal care applications.
Strategic Opportunities
- Indian food service penetration:Quick-service restaurant chains under FSSAI jurisdiction present untapped volume for flat-pack napkin formats.
- Healthcare dispensing system integration:Smart towel dispensers using RFID inventory tracking create pull-through demand for roll-pack specifications.
- Extended producer responsibility tailwinds:Germany's Verpackungsgesetz amendments incentivize post-consumer recycled fiber content in retail tissue overwrap.
Industry Challenges
- Skilled technician scarcity:Wet-end process engineers capable of optimizing creping chemistry for barrier coatings command premium compensation.
- ISO 17025 certification timelines:Third-party laboratory accreditation for FDA food-contact testing extends new product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tissue and Hygiene Paper Packaging Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Napkins, Tissues, Towels, Wrappers Material: Recycled Paper, Virgin Fiber, Biodegradable Plastics, Others Application: Food Service, Personal Care, Industrial Use, Healthcare Packaging Type: Flat Packs, Roll Packs, Bulk Packs, Pre-folded |
| Companies Covered | Georgia-Pacific, Hengan International Group, Procter & Gamble, WEPA Hygieneprodukte, Unicharm Corporation, Kimberly-Clark, Sofidel, Vinda International, Essity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tissue and Hygiene Paper Packaging Market Strategic Shifts
Material science advances and regulatory stringency are converging to restructure substrate specifications across food service, personal care, and healthcare end-uses. Converters must balance fiber purity requirements against compostability certifications.
Barrier-coated paper substrates incorporating plant-derived wax emulsions are modularizing moisture protection for hygiene product overwrap. Quick-service chains in Germany and France are specifying these grades for napkin and towel dispensers. The technology is modularizing converter product lines by enabling single-machine runs for both food-contact and personal care applications.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating oil-repellent chemistries from European tissue packaging. Mills serving healthcare and food service channels face reformulation investments. Personal care brands exporting into EU member states are accelerating certification transitions ahead of 2025 enforcement deadlines.
Direct mill-to-retailer contracting is compressing traditional distributor margins in European tissue packaging. German retail chains now specify recycled fiber content percentages in procurement tenders. Food service operators in Nordic markets are consolidating supplier panels to three approved mills per substrate category.
Tissue and Hygiene Paper Packaging Market Segmentation
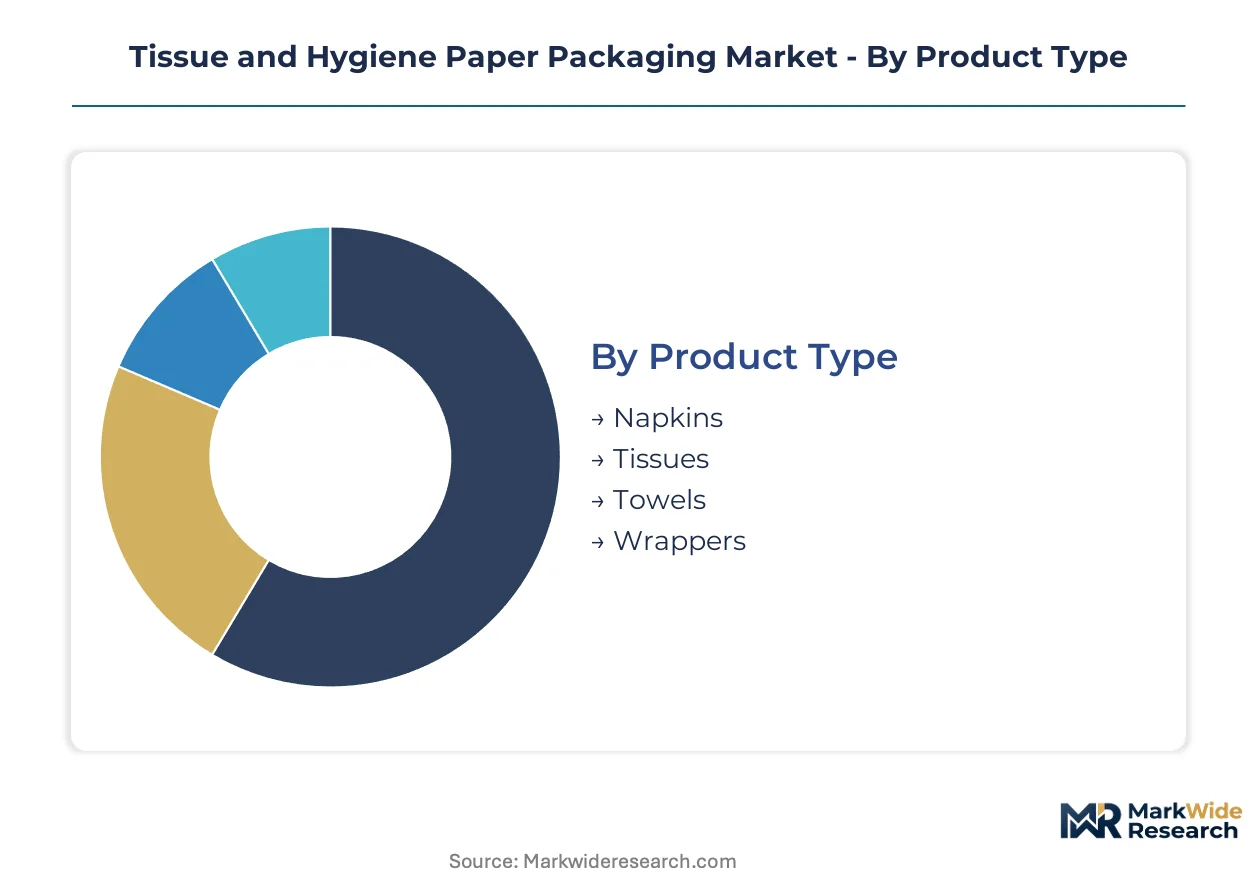
Substrate specifications and dispensing formats determine margin structures across tissue and hygiene paper packaging. Engineers calibrate wet-laid creping parameters to match end-use durability requirements. Procurement teams negotiate fiber grade contracts based on regulatory exposure in target export markets.
Product Type:
Wet-strength formation chemistry and basis weight specifications define performance tiers across absorbent product categories.
- Napkins:Wet-laid sheets at 18–35 gsm incorporate creping additives for food service dispenser compatibility. Quick-service operators in Germany specify compostable grades under national packaging ordinances.
- Towels:Through-air dried substrates at 40–80 gsm deliver absorbency for healthcare hand-drying stations. Nordic hospital procurement panels certify suppliers against EN 13432 composting standards.
- Tissues:Softwood pulp blends target facial care applications with lint-free surface characteristics.
- Wrappers:Barrier-coated papers protect personal care product integrity during distribution.
Towels lead on scale; napkins lead on momentum.
Material:
Cost tiers separate premium positioning from volume-driven recycled fiber procurement.
- Virgin Fiber:Bleached softwood kraft delivers purity specifications for healthcare and premium personal care. FDA food-contact certification requirements govern US-bound napkin exports.
- Recycled Paper:Post-consumer fiber grades face Ecodesign packaging rule compliance in European food service channels. German retail chains now mandate minimum recycled content percentages in tender specifications.
- Biodegradable Plastics:PHA and PLA films occupy transitional moisture-barrier applications pending scalable fiber alternatives.
- Others:Agricultural residue pulps and bamboo fibers serve niche sustainable positioning.
Virgin fiber leads on scale; recycled paper leads on momentum.
Application:
Volume concentration varies by channel access and regulatory certification burdens.
- Food Service:Quick-service chains and catering operators drive flat-pack napkin specifications. France and Germany enforce compostable packaging mandates through national implementation of EU Green Deal targets.
- Personal Care:Roll-pack formats dominate retail tissue overwrap with brand-controlled dispensing systems.
- Healthcare:Roll-towel specifications for electronic dispensers require RFID compatibility and infection control certification.
- Industrial Use:Heavy-duty wipers serve manufacturing maintenance with lower softness specifications.
Food service leads on scale; healthcare leads on momentum.
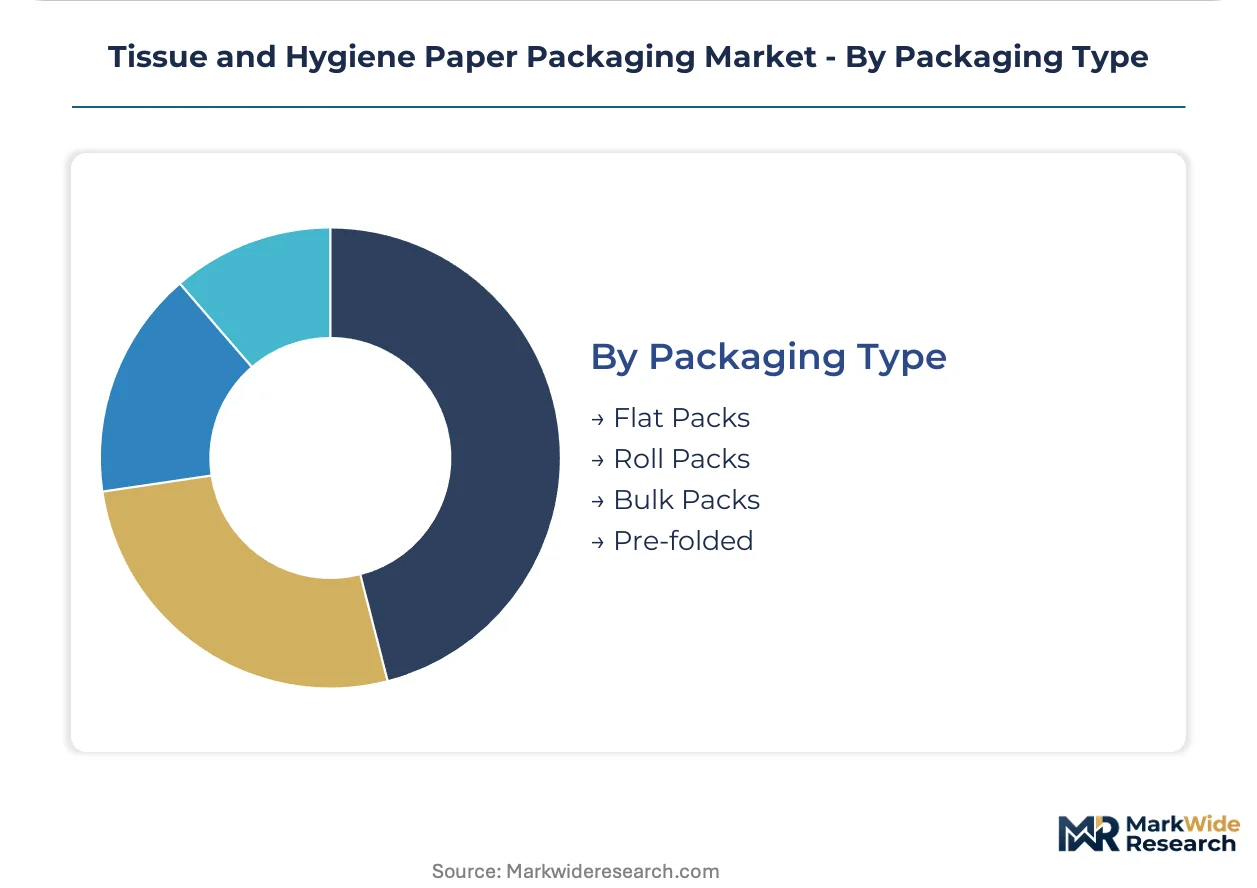
Packaging Type:
Dispensing mechanics and logistics efficiency determine converter line configurations.
- Flat Packs:Pre-folded napkin stacks optimize dispenser cube utilization for tabletop and wall-mounted units.
- Roll Packs:Continuous sheet formats integrate with automated towel dispensers in high-traffic restrooms.
- Bulk Packs:Institutional quantities reduce per-unit logistics costs for hospital and hotel procurement.
- Pre-folded:Multi-panel napkin constructions enable single-pull dispensing in quick-service environments.
Roll packs lead on scale; flat packs lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping production geography as converters relocate to jurisdictions with lower compliance costs for REACH chemical certification and EU Green Deal packaging mandates. Mills in Poland and Turkey attract investment from manufacturers seeking proximity to European demand without full regulatory burden. Asian producers leverage cost advantages in virgin pulp procurement to serve export markets.
Germany
WEPA Hygieneprodukte anchors volume procurement for sustainable tissue packaging through direct contracts with major retail chains. The Verpackungsgesetz amendments incentivize post-consumer recycled fiber content in retail tissue overwrap. The North Rhine-Westphalia industrial corridor concentrates wet-laid creping capacity serving food service and personal care channels.
United States
Georgia-Pacific leverages integrated pulp-to-package infrastructure across North American mills to serve quick-service restaurant chains. FDA food-contact regulations govern napkin and towel substrates deployed in US food service, creating testing protocol divergence from European supply chains. The Southeastern paper belt maintains hardwood and softwood pulp integration for premium healthcare specifications.
China
Hengan International Group and Vinda International drive domestic capacity expansion for facial tissue and personal care overwrap. The country's dual carbon goals pressure mills toward energy-efficient through-air drying technologies. The Yangtze River Delta cluster houses specialized converters exporting barrier-coated papers to Southeast Asian food service markets.
Italy
Sofidel anchors Mediterranean production with recycled fiber specialization for retail and institutional channels. National implementation of EU Ecodesign packaging rules tightens material requirements for compostable grades. The Lucca tissue district maintains historic concentration of creping expertise serving European personal care brands.
Japan
Unicharm Corporation competes on brand-controlled channel access for premium personal care dispensing systems. METI industrial standards shape moisture-barrier specifications for high-humidity applications. The Kanto region around Tokyo concentrates R&D investment in smart towel dispensers using RFID inventory tracking.
Tissue and Hygiene Paper Packaging Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue biodegradable barrier coatings and agricultural residue pulps. The market structure reflects moderate consolidation among integrated pulp-to-package operators alongside specialized regional converters. Three archetypes dominate: integrated multinationals with captive fiber supply, regional specialists with recycled fiber expertise, and technology-focused entrants developing plant-derived wax emulsions. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure raw material access and dispensing system integration.
Within the integrated multinational tier, Georgia-Pacific and Kimberly-Clark exemplify scale-driven positioning through North American pulp integration and brand-controlled distribution channels. Among European specialists, Essity and Sofidel occupy positions anchored by regional recycled fiber specialization and compliance leadership under EU Green Deal frameworks. WEPA Hygieneprodukte represents the procurement-consolidation archetype through direct mill-to-retailer contracting in German-speaking markets.
| Leading Market Players |
|---|
| Georgia-Pacific |
| Hengan International Group |
| Procter & Gamble |
| WEPA Hygieneprodukte |
| Unicharm Corporation |
| Kimberly-Clark |
| Sofidel |
| Vinda International |
| Essity |
| Others |
Value Chain & Pricing Dynamics
Through-air drying technology upgrades across Nordic and North American mills are compressing unit economics for wet-strength napkin grades while simultaneously concentrating supply leverage among integrated producers with captive pulp assets. This dual effect tightens margin pools for non-integrated converters competing on recycled fiber positioning.
Pricing Analysis
Retailer markup compression in German and French procurement tenders is reshaping contract structures. Three-tier pricing structure across premium, standard, and economy levels separates virgin fiber healthcare specifications from Ecodesign-compliant food service grades and bulk institutional volumes. Cost compression in recycled paper segments is intensifying because post-consumer fiber certification burdens extend qualification timelines. Quick-service restaurant chains exhibit highest price sensitivity; premium personal care brands demonstrate lowest.
Supply Chain Analysis
Post-consumer fiber collection and sorting infrastructure creates reverse-logistics complexity for mills seeking closed-loop recycled content claims. Geographic supply concentrates in Germany, the United States, and China, with the Lucca district in Italy and Poland emerging as secondary hubs. Production draws from softwood pulp, recycled fiber bales, and plant-derived wax emulsions for barrier coatings. Single-source vulnerability around Nordic softwood harvest cycles threatens fiber cost stability. Distribution runs through direct mill-to-retailer contracting in Europe and distributor networks in North American food service.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder anchored by EU Green Deal packaging mandates that institutionalize fiber-based material transitions across European supply chains.
For Market Incumbents: Extend wet-laid creping capacity into Poland and Turkey to capture regulatory arbitrage opportunities while REACH compliance costs concentrate in Western Europe. Defend against biodegradable plastic substitution threats by accelerating plant-derived wax emulsion R&D for moisture-barrier applications. Prioritize backward integration into post-consumer fiber collection infrastructure to secure recycled content percentages demanded by German retail tenders. For New Entrants and Emerging Players: Agricultural residue pulp processing technology offers entry leverage into European food service channels where Ecodesign rules tighten virgin fiber restrictions. White-space exists in Indian quick-service restaurant chains under FSSAI jurisdiction for flat-pack napkin formats. Target healthcare dispensing system integration partnerships with RFID-enabled smart towel manufacturers as the most penetrable application layer. For Investors and Strategic Acquirers: Roll-up economics work for regional recycled fiber specialists because EU EPR schemes fragment compliance costs across national implementations. Five-to-ten year viability rests on mills with dual certification capability for FDA food-contact and EN 13432 composting standards. Monitor enforcement timelines for REACH PFAS restrictions as the inflection signal for barrier-coated paper demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Post-Consumer Fiber Collection | Secures recycled content percentages mandated by Germany's Verpackungsgesetz amendments. |
| Plant-Derived Wax Emulsion R&D Investment | Replaces REACH-restricted PFAS chemistries in moisture-barrier coating formulations. |
| Direct Mill-to-Retailer Contracting Expansion | Compresses distributor margins while capturing volume procurement from major European retail chains. |
| RFID-Enabled Dispensing System Partnership | Creates pull-through demand for roll-pack specifications in healthcare and institutional channels. |
| Capacity Expansion in Poland and Turkey | Captures regulatory arbitrage by serving EU demand with reduced REACH certification burdens. |
Study Parameters
Direct dialogue with wet-end process engineers, procurement managers at quick-service restaurant chains, regulatory affairs specialists, and distribution channel partners grounded qualitative findings. Secondary validation drew from EU ECHA substance restriction databases, FDA food-contact guidance documents, German Verpackungsgesetz implementation records, and trade flow data for pulp and recovered paper. Bottom-up mill capacity assessments triangulated against top-down demand modeling by end-use channel.
Bottom-up volume builds aggregated individual substrate specifications across wet-laid creping and through-air drying process categories. Top-down cross-checks applied macro consumption patterns by food service, personal care, and healthcare application segments. CAGRs derived from regression analysis against regulatory enforcement timelines and fiber substitution elasticities. Forecast inputs incorporated EU Green Deal packaging waste directive implementation schedules and Nordic softwood harvest cycle projections.
The model holds under stable regulatory enforcement trajectories; deviation in REACH PFAS restriction timelines or Nordic pulp supply disruptions would shift fiber grade demand mix. Practitioners should monitor German retail tender specifications and FSSAI food-contact rule developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Wrapping Paper Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Non-Tacky Transfer Paper Market
Paper & Paperboard Packaging
Insulated Corrugated Boxes Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Middle East and Africa Paper Packaging Market
Paper & Paperboard Packaging
Paper Waste Strippers Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
Global Multi Depth Corrugated Boxes Market
Paper & Paperboard Packaging
Poly Coated Paperboard Market
Paper & Paperboard Packaging
Disposable Paper Cups Market
Paper & Paperboard Packaging
Industrial Paper Sacks Market
Paper & Paperboard Packaging
Decal Paper Market