
 Retail Press Dispenser Pump Market | 2026-2036
Retail Press Dispenser Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Retail Press Dispenser Pump Market Insights
Aftermarket service revenue for pump refurbishment and replacement programs is narrowing as manufacturers build longer-life polymer springs and corrosion-resistant closure systems. AptarGroup, Inc. leverages its global tooling network to sustain high-volume contracts with multinational personal care brands. Silgan Dispensing Systems anchors North American supply through captive injection-molding capacity and direct retail relationships. Albéa S.A. differentiates via integrated decoration capabilities that merge pump function with shelf aesthetics for prestige cosmetics.
A retail press dispenser pump is a mechanical or electromechanical fluid-dispensing closure that mounts to rigid or semi-rigid containers, typically employing a piston-chamber design with a return spring to meter discrete volumes per actuation cycle; common specifications include output volumes of 0.5–2.0 milliliters per stroke, dip tube lengths of 100–300 millimeters, and thread finishes of 24/410 or 28/400 for standard bottle necks. Plastic dominates material selection due to cost and colorability, though composite constructions incorporating post-consumer resin are gaining traction as sustainability mandates tighten. Manual pumps lead volume across retail stores and convenience channels where cost sensitivity prevails, while battery-operated variants represent the fastest-expanding segment in pharmaceutical outlets requiring precise dosing and tamper-evident features.
The FDA regulates pump dispensing systems for over-the-counter drug applications through container closure system guidance, while the EPA oversees volatile organic compound emissions from aerosol-alternative press systems in household products. REACH compliance in Europe restricts certain phthalates and heavy metals in pump components, forcing reformulation of traditional polypropylene and ABS blends. Stakeholders must monitor evolving extended producer responsibility frameworks that will increasingly assign collection and recycling costs directly to pump manufacturers rather than downstream brand owners.
Market Dynamics
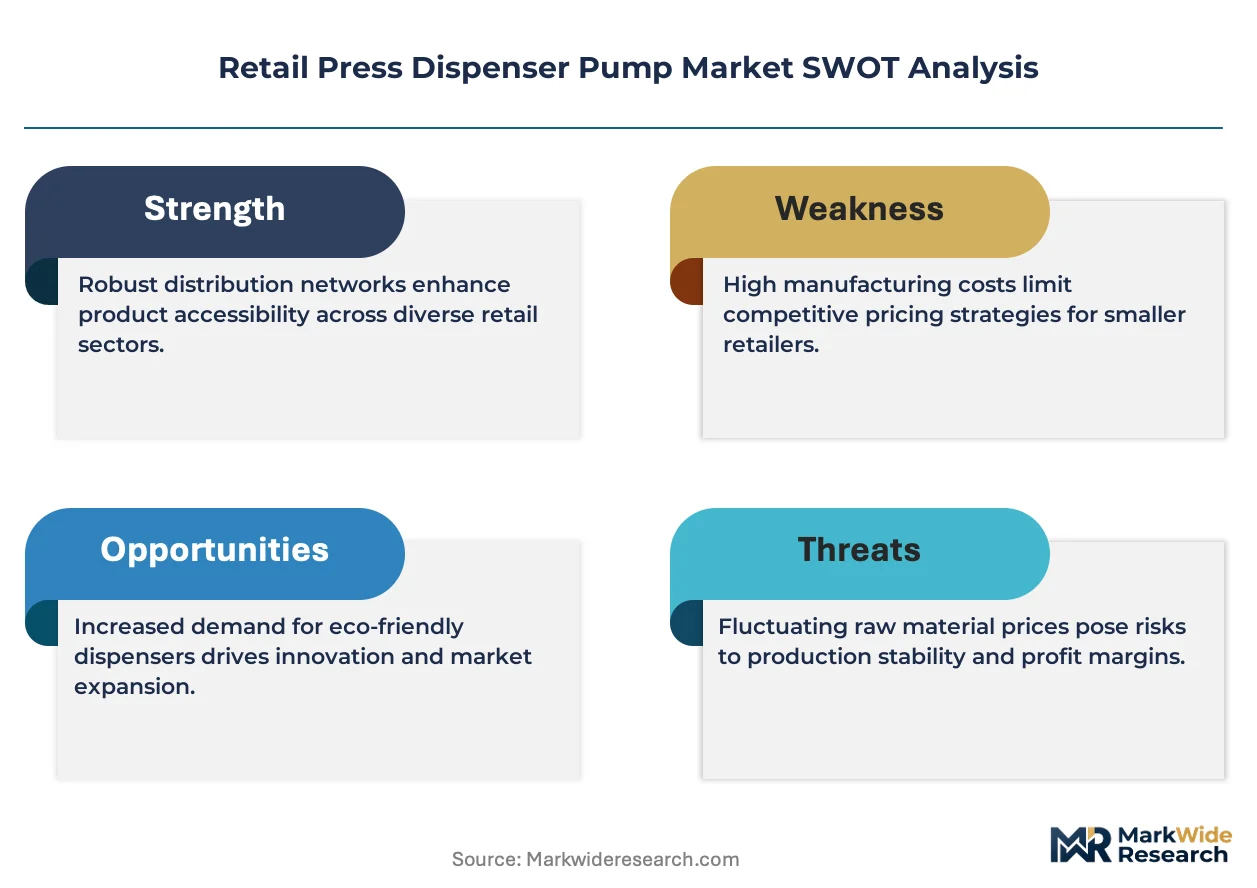
The EU's Single-Use Plastics Directive is compressing material substitution timelines, forcing polymer reformulation and bio-based adoption across European supply chains while precision manufacturing clusters in Germany absorb compliance costs through premium positioning.
Growth Catalysts
- Food Service Hygiene Mandates:Portion-controlled dispensing requirements from quick-service chains and institutional cafeterias are pulling high-cycle pump designs into commercial kitchens.
- REACH Compliance Deadlines:Phthalate and heavy metal restrictions are accelerating R&D into post-consumer resin blends and bio-polymer alternatives for piston chambers.
- Pharmaceutical Dosing Precision:Battery-operated variants with tamper-evident features are capturing shelf space in drugstore channels where OTC medication compliance demands exact volume delivery.
Market Restraints
- Petrochemical Input Volatility:Polypropylene and ABS resin prices swing with crude oil benchmarks, compressing margin stability for high-volume manual pump producers.
- Tooling Concentration Risk:Precision mold fabrication clusters in southern Germany and eastern China create single-source vulnerability for complex piston-chamber geometries.
- Mechanical Durability Ceiling:Return spring fatigue after 10,000+ actuation cycles limits warranty terms and refurbishment revenue potential in high-frequency food service deployments.
Strategic Opportunities
- Extended Producer Responsibility Expansion:France and Italy are piloting collection schemes that assign end-of-life costs directly to pump manufacturers, rewarding closed-loop design capabilities.
- Smart Dispensing Convergence:Integration of RFID-enabled usage tracking with electromechanical pumps creates data-monetization potential for pharmaceutical adherence programs.
- Direct-to-Brand E-Commerce:Bypassing traditional distribution layers, specialty chemical and cosmetics brands are procuring decorated pump-closure systems through digital specification platforms.
Industry Challenges
- Multi-Material Separation Complexity:Composite pump constructions combining polypropylene, stainless steel springs, and thermoplastic elastomer seals complicate automated recycling sortation and chemical depolymerization.
- FDA Container Closure Certification:OTC drug applications require 18-24 month stability testing protocols, freezing design iterations and delaying revenue recognition for new pump geometries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retail Press Dispenser Pump Market |
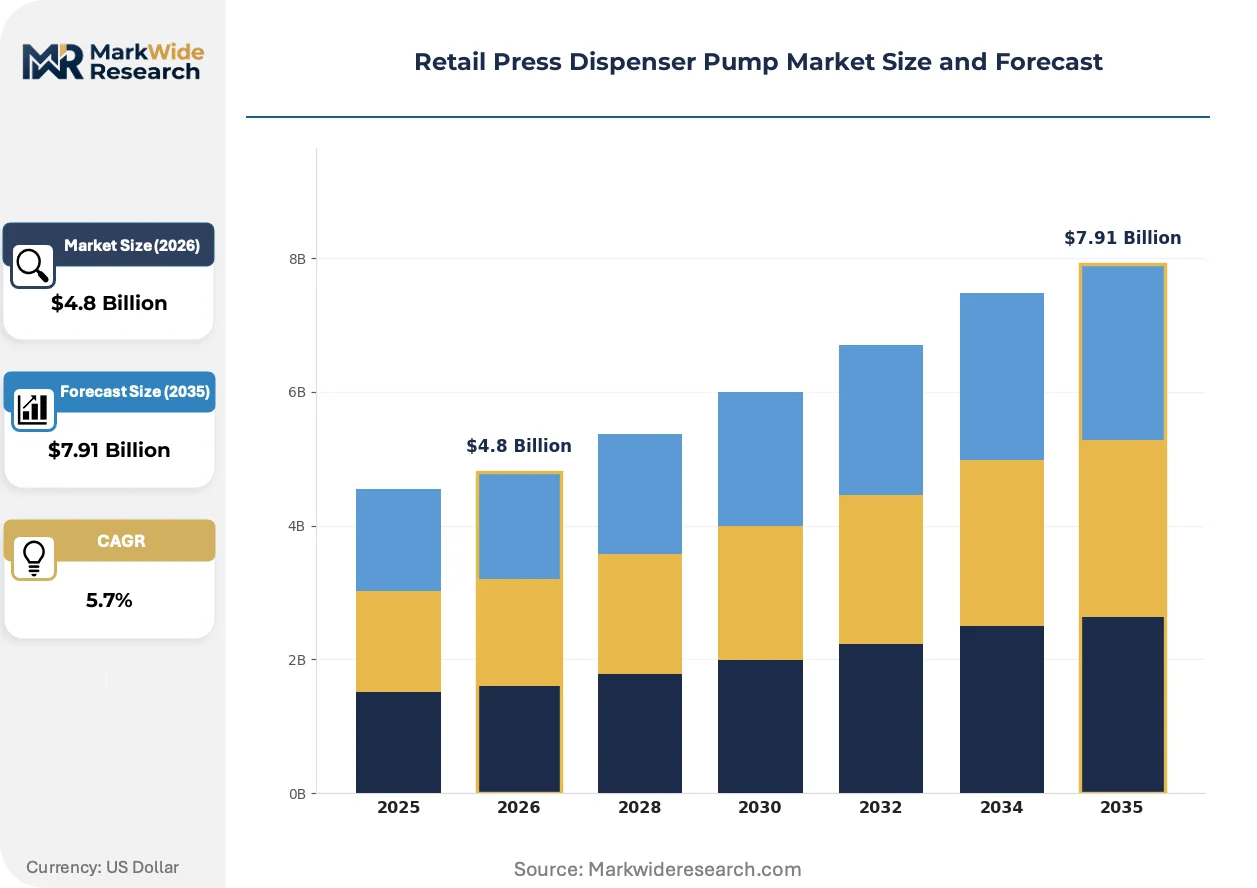
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Pump, Electric Pump, Pneumatic Pump, Battery-operated Pump Material: Plastic, Metal, Glass, Composite End User: Retail Stores, Pharmaceutical Outlets, Food Service, Convenience Stores Distribution Channel: Online Retail, Wholesale, Specialty Stores, Direct Sales |
| Companies Covered | AptarGroup, Inc., Silgan Dispensing Systems, Berry Global, Inc., Albéa S.A., Rieke Packaging Systems, Gerresheimer, Raepak Ltd., HCP Packaging, Cosmogen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retail Press Dispenser Pump Market Trends and Innovations
Digital specification tools and electromechanical convergence are rewriting how pump systems are designed, procured, and deployed across retail and pharmaceutical channels.
Digital twin modeling is virtualizing the traditional physical prototyping phase for pump mechanism validation. Cosmetics and personal care brands in France and Germany are compressing development cycles from 14 months to under 6 months. This acceleration is virtualizing the competitive advantage of incumbent manufacturers with legacy tooling libraries.
REACH Annex XVII updates are tightening restrictions on intentionally added microplastics in rinse-off cosmetics, directly impacting dip tube and piston seal material selection. Compounders are reformulating thermoplastic elastomers to exclude synthetic polymer microbeads and non-biodegradable additives. Prestige fragrance and skincare houses are responding by specifying bio-based alternatives despite 15-20% cost premiums.
Brand procurement teams are consolidating supplier panels from 12-15 vendors to 3-4 strategic partners with integrated decoration and logistics capabilities. Direct retail relationships are displacing traditional distribution intermediaries in North American mass-market channels. This concentration is most visible in Walmart and Target supplier ecosystems, where vendor scorecards now weight sustainability certification and domestic mold capacity equally with unit pricing.
Retail Press Dispenser Pump Market Segmentation
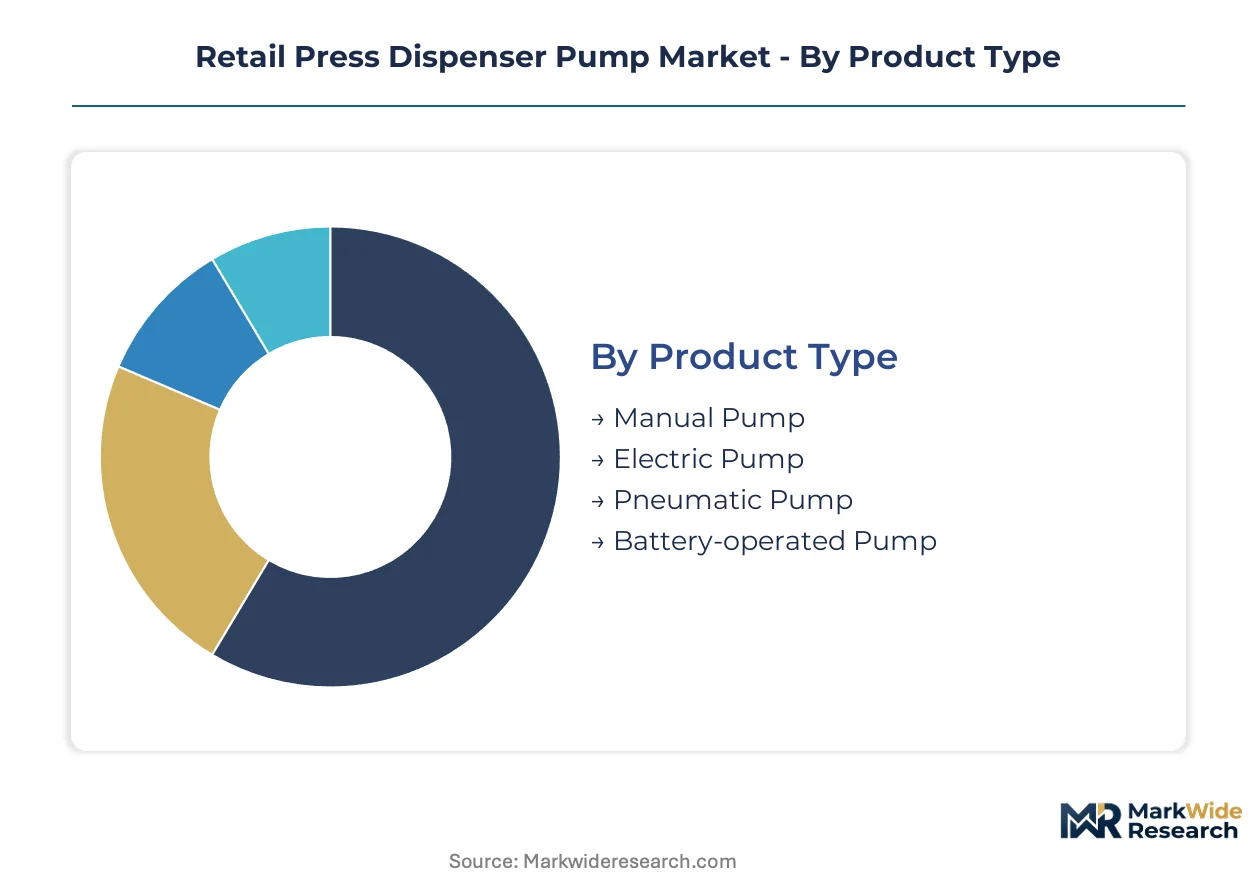
Dispenser pump segmentation reveals divergent engineering requirements across actuation mechanisms, material specifications, and channel economics. Each dimension carries distinct margin profiles and regulatory exposure that shape procurement strategies.
Product Type:
Actuation mechanism determines unit economics, durability specifications, and end-use compatibility across retail deployment scenarios.
- Manual Pump:Piston-chamber designs with polypropylene or ABS construction dominate mass-market personal care and household chemical applications. Food service operators in Germany and France specify high-cycle variants with stainless steel springs for institutional kitchen compliance with hygiene mandates.
- Battery-operated Pump:Electromechanical systems with precision stepper motors enable exact 0.5–2.0 milliliter dosing for pharmaceutical adherence programs. Drugstore chains in the United States are expanding shelf space for tamper-evident OTC medication formats.
- Electric Pump:Mains-powered dispensing systems serve high-volume commercial installations with continuous duty cycles.
- Pneumatic Pump:Compressed-air actuation supports industrial-scale filling operations and automated packaging lines.
Manual pumps command the established base. The steepest expansion runs through battery-operated systems.
Material:
Substrate selection balances chemical resistance, sustainability certification, and post-consumer recyclability against unit cost targets.
- Plastic:Polypropylene and ABS blends offer colorability and cost efficiency for standard 24/410 and 28/400 thread finishes. REACH Annex XVII restrictions on phthalates and heavy metals are accelerating reformulation toward post-consumer resin blends in European supply chains.
- Composite:Multi-layer constructions combining bio-based polymers with conventional resins address EU Single-Use Plastics Directive compliance. German precision manufacturing clusters absorb 15–20% cost premiums through premium positioning of sustainable dispenser systems.
- Metal:Stainless steel components provide corrosion resistance for high-frequency food service deployments.
- Glass:Borosilicate and soda-lime options serve prestige fragrance and pharmaceutical applications requiring inert contact surfaces.
Plastic formulations retain volume leadership. Composite materials are climbing the fastest as regulatory timelines compress.
End User:
Customer category shapes performance specifications, certification requirements, and replacement cycle economics.
- Retail Stores:Mass-market channels prioritize unit cost and color consistency across seasonal personal care launches. Walmart and Target supplier ecosystems now weight sustainability certification equally with domestic mold capacity in vendor scorecards.
- Pharmaceutical Outlets:OTC drug applications demand FDA container closure system compliance with 18–24 month stability testing protocols. Battery-operated precision dosing formats are capturing shelf space for medication adherence programs.
- Food Service:Quick-service chains and institutional cafeterias specify portion-controlled dispensing for hygiene compliance and waste reduction.
- Convenience Stores:Travel-size and impulse formats favor compact pump geometries with minimal shelf footprint.
Retail stores anchor current procurement volumes. Pharmaceutical outlets are gaining share fastest on dosing precision requirements.
Distribution Channel:
Channel structure determines specification control, margin capture, and supplier relationship intensity.
- Direct Sales:Brand-direct procurement through digital specification platforms enables integrated decoration and logistics consolidation. Specialty chemical and cosmetics brands are bypassing traditional distribution layers to capture design iteration speed.
- Online Retail:E-commerce specification tools compress development cycles from 14 months to under 6 months for cosmetics and personal care brands in France and Germany.
- Wholesale:Traditional distribution intermediaries retain relevance in North American mass-market replenishment.
- Specialty Stores:Prestige fragrance and skincare channels emphasize shelf aesthetics and tactile differentiation.
Direct sales relationships are displacing wholesale intermediaries. Online retail platforms are expanding most quickly through digital specification convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Mass-market buyers in the United States and China prioritize unit cost above sustainability certification. German and French purchasers absorb 15-20% premiums for REACH-compliant bio-based alternatives.
Germany
Precision manufacturing clusters in Baden-Württemberg and Bavaria supply high-cycle stainless steel spring variants for institutional food service. The EU Single-Use Plastics Directive accelerates material transitions toward recyclable pump components. Stuttgart-area mold fabricators absorb compliance costs through premium positioning of advanced dispenser systems.
United States
Walmart and Target supplier ecosystems drive consolidation toward vendors with domestic injection-molding capacity. FDA container closure system guidance governs OTC drug applications with 18-24 month stability testing protocols. Ohio and Illinois-based manufacturers capture mass-market replenishment contracts through direct retail relationships.
France
Prestige cosmetics houses in Île-de-France specify integrated decoration capabilities that merge pump function with shelf aesthetics. Extended producer responsibility pilot schemes assign end-of-life collection costs directly to pump manufacturers. Lyon-area compounders reformulate thermoplastic elastomers to exclude REACH-restricted additives.
China
Guangdong and Zhejiang provinces host high-volume manual pump production for export-oriented personal care brands. The country's national packaging regulator enforces evolving standards on food-contact materials and chemical migration limits. Shenzhen-based digital specification platforms compress development cycles for cosmetics brands seeking rapid design iteration.
India
Domestic personal care brands drive demand for cost-optimized 24/410 and 28/400 thread finish pumps. The Bureau of Indian Standards mandates compliance for food-contact packaging materials in quick-service chain deployments. Maharashtra and Gujarat-based injection molders scale capacity to serve both local retail chains and export markets.
Retail Press Dispenser Pump Market Competitive Landscape
Capability concentration sits with precision mold specialists; scale advantage sits with diversified packaging conglomerates. The market structures around three tiers: global closure system integrators with captive decoration networks, regional injection-molding specialists serving single-channel customers, and precision component fabricators focused on high-cycle food service variants. Dominant competitive moves include backward integration into polymer compounding and strategic partnerships with brand-direct e-commerce platforms.
Among diversified packaging conglomerates, AptarGroup, Inc. and Silgan Dispensing Systems occupy positions spanning global tooling networks and North American captive capacity respectively. Albéa S.A. exemplifies the integrated decoration tier where shelf aesthetics and pump function converge. These three anchors represent distinct strategic postures: tooling scale, regional supply security, and prestige brand alignment.
| Leading Market Players |
|---|
| AptarGroup, Inc. |
| Silgan Dispensing Systems |
| Berry Global, Inc. |
| Albéa S.A. |
| Rieke Packaging Systems |
| Gerresheimer |
| Raepak Ltd. |
| HCP Packaging |
| Cosmogen |
| Others |
Pricing and Supply Chain Analysis
Stuttgart-area mold fabricators absorb REACH compliance costs through premium positioning of stainless steel spring variants, translating regulatory burden into pricing power over institutional food service buyers in Germany and France. Their captive capacity in precision piston-chamber geometries limits alternative sourcing, compressing negotiation leverage for quick-service chains seeking high-cycle durability warranties.
Pricing Analysis
Aftermarket refurbishment revenue drives lifetime value differentiation between manual pump tiers. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel spring food service variants from polypropylene mass-market units and entry-level convenience store formats. Price differentiation rests on certification grade and volume scale, with FDA container closure system tiers commanding substantial premiums over uncertified household chemical applications. Cost compression in standard polypropylene manual pumps is intensifying because petrochemical input volatility swings with crude oil benchmarks. Mass-market retail buyers in the United States exhibit highest price sensitivity, while German institutional purchasers absorb 15-20% premiums for bio-based composite alternatives.
Supply Chain Analysis
Export-control regimes on precision molding equipment constrain technology transfer to emerging manufacturing bases, preserving capability concentration in southern Germany and eastern China. Geographic supply concentration centers on China, Germany, and the United States, with Guangdong and Zhejiang provinces hosting high-volume manual pump production and Baden-Württemberg clusters supplying precision food service variants. Raw material dependencies draw from polypropylene resin, ABS blends, and stainless steel spring wire. Single-source vulnerability in complex piston-chamber mold fabrication creates structural risk. Distribution runs through direct retail relationships displacing traditional wholesale intermediaries in North American mass-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from pouch-and-cap dispensing formats in travel-size personal care, requiring defensive positioning around precision dosing and hygiene compliance that flexible alternatives cannot replicate.
For Market Incumbents: Harden barrier positions through backward integration into polymer compounding for REACH-compliant bio-based resin blends, securing feedstock control as regulatory timelines compress. Fortify direct retail relationships with Walmart and Target supplier ecosystems, leveraging domestic injection-molding capacity as a vendor scorecard differentiator against offshore competitors facing tariff exposure. For New Entrants and Emerging Players: Pursue white-space opportunities in battery-operated pharmaceutical dispensing for drugstore adherence programs, where FDA container closure certification requirements deter commoditized competition. Target e-commerce specification platforms serving French and German cosmetics brands seeking compressed development cycles, using digital twin modeling capabilities as the primary go-to-market angle. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision mold specialists with captive stainless steel spring fabrication and established pharmaceutical certification pathways. Long-term viability hinges on closed-loop design capabilities as extended producer responsibility schemes assign end-of-life costs directly to manufacturers. Watch for inflection signals in EU Single-Use Plastics Directive enforcement intensity, which would accelerate material substitution timelines and reward early bio-polymer adopters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive supply of REACH-compliant bio-based resins insulates margin from petrochemical volatility and regulatory reformulation costs. |
| Direct-to-Brand E-Commerce Platform Launch | Bypassing wholesale intermediaries captures design iteration speed for cosmetics brands in France and Germany. |
| Pharmaceutical Certification Investment | FDA container closure system pathways open drugstore shelf space for battery-operated precision dosing formats. |
| Closed-Loop Collection Infrastructure | Extended producer responsibility pilots in France and Italy assign end-of-life costs directly to pump manufacturers. |
| Digital Twin Modeling Capability | Virtual prototyping compresses development cycles from 14 months to under 6 months for personal care brands. |
Research Methodology
A spread of perspectives from brand procurement managers, food service equipment specifiers, polymer compounders, and precision mold engineers converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation through customs records, SEC filings from diversified packaging conglomerates, FDA container closure system guidance documents, and EU REACH Annex XVII regulatory updates. Bottom-up pump shipment data triangulated against top-down personal care and pharmaceutical packaging expenditure trends.
Demand-supply balance modeling across the projection horizon incorporated actuation mechanism, material substrate, end-user channel, and geographic regulatory cluster as core segmentation dimensions. CAGRs derived from shipment volume trajectories, pricing trend analysis, and substitution elasticity estimates for pouch alternatives. Industry-specific forecast inputs included EU Single-Use Plastics Directive compliance timelines and FDA stability testing protocol durations for OTC drug applications.
Sensitivities concentrate around petrochemical input volatility, REACH enforcement intensity, and pharmaceutical certification approval timelines. Forecasts reflect documented assumptions on material substitution rates and direct retail channel penetration. Material shifts in extended producer responsibility scheme adoption or battery-operated pump technology cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Equipment
Strapping and Banding Equipment Market
Packaging Equipment
Coding and Marking Systems Market
Packaging Equipment
Vacuum Fillers Market
Packaging Equipment
Global Shrink Sleeve Applicator Market
Packaging Equipment
Powder Dispenser Market
Packaging Equipment
Hang Tag Applicators Market
Packaging Equipment
Diaper Packaging Machines Market
Packaging Equipment
Dispensing Booth Market
Packaging Equipment
Hot Fill Packaging Market
Packaging Equipment
Bespoke Dispenser Market
Packaging Equipment
Inflatable Void Fill System Market
Packaging Equipment
Label Converting Equipment Market
Packaging Equipment
Labeling Equipment Market
Packaging Equipment
Die-Cutter Market
Packaging Equipment
Plastic Waste Sorting Equipment Market
Packaging Equipment
Bagging Equipment Market