
 Non-Tacky Transfer Paper Market | 2026-2036
Non-Tacky Transfer Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Tacky Transfer Paper Market Analytics
ISO 14001 environmental management certification is collapsing the supplier base for European textile printers, forcing substrate vendors to rebuild their coating lines around audited solvent recovery systems. Felix Schoeller leverages captive pulp sourcing from its Bavarian mills to sustain margin control across inkjet and laser transfer grades. Neenah Paper anchors North American distribution through wholesale paper merchants that stock its digital transfer portfolio alongside specialty fine papers. Sappi Limited competes from its Maastricht technical paper mill, where it positions coated release papers for industrial heat-transfer applications.
Non-tacky transfer paper comprises a release-coated substrate—typically glassine, kraft, or clay-coated paper bearing silicone or polyvinyl alcohol barriers—that permits clean separation of printed images from carrier sheets under heat and pressure without residual adhesion. Its primary commercial purpose is to enable precise image transfer onto textiles, ceramics, and rigid substrates while eliminating post-press cleaning cycles. Laser transfer paper dominates volume among product types because apparel decorators prioritize toner compatibility and wash durability over watercolor flexibility. Online retail channels are capturing share from wholesale distributors as small businesses and craft enthusiasts bypass minimum-order requirements through direct-to-consumer platforms.
REACH and the EU Green Deal are reshaping coating chemistry across European supply chains, compelling reformulation of silicone release layers to eliminate perfluorinated compounds. The US EPA and OSHA jointly influence domestic manufacturing through volatile organic compound limits and workplace exposure standards for solvent-based coating operations. Stakeholders must monitor regulatory divergence between Brussels and Washington, as divergent substance restrictions threaten to fragment product specifications and complicate cross-border inventory management.
Market Dynamics
REACH compliance in Europe is collapsing the supplier base for coating formulations, forcing substrate vendors to rebuild solvent recovery systems and reformulate silicone release layers without perfluorinated compounds.
Growth Catalysts
- Laser transfer compatibility:Apparel decorators in Germany's Heidelberg and Munich clusters prioritize toner-based systems for wash durability, pulling demand toward premium substrate grades.
- REACH chemical disclosure mandates:The EU Green Deal is accelerating coating chemistry transparency, creating first-mover advantage for vendors with audited environmental management systems.
- On-demand textile decoration:Small-batch production models are spreading across European print shops, requiring transfer papers that eliminate post-press cleaning cycles.
Market Restraints
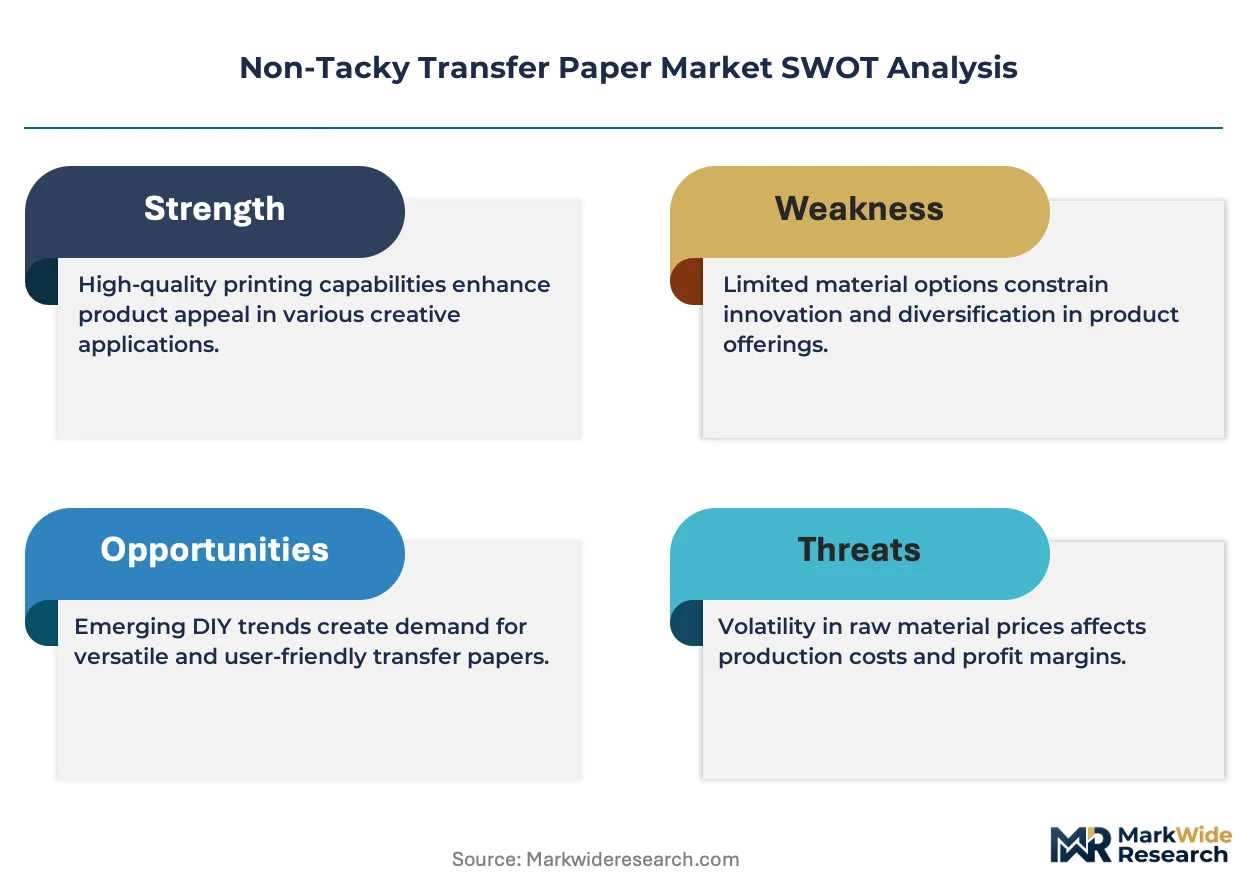
- Pulp cost volatility:Captive fiber sourcing remains limited to integrated producers like Felix Schoeller's Bavarian mills, leaving independent converters exposed to spot market fluctuations.
- Silicone supply concentration:Specialty release coating chemistries depend on a narrow base of European chemical suppliers, amplifying disruption risk from any single plant outage.
- Watercolor flexibility gap:Laser transfer papers sacrifice pigment versatility compared to inkjet alternatives, constraining adoption among fine art reproduction specialists.
Strategic Opportunities
- Direct-to-consumer channel expansion:Online retail platforms are capturing share from wholesale distributors as craft enthusiasts bypass minimum-order requirements.
- Industrial heat-transfer applications:Sappi's Maastricht technical paper mill positions coated release papers for ceramics and rigid substrates beyond textiles.
- ISO 14001 certification differentiation:Environmental management credentials are becoming a procurement filter for major European textile printers seeking supply chain auditability.
Industry Challenges
- Cross-border regulatory divergence:The US EPA and OSHA maintain volatile organic compound limits that conflict with EU solvent recovery standards, complicating inventory management for multinational vendors.
- Coating line reconfiguration timelines:Rebuilding production assets around audited solvent recovery systems requires 18-24 month capital cycles that strain mid-tier converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Tacky Transfer Paper Market |
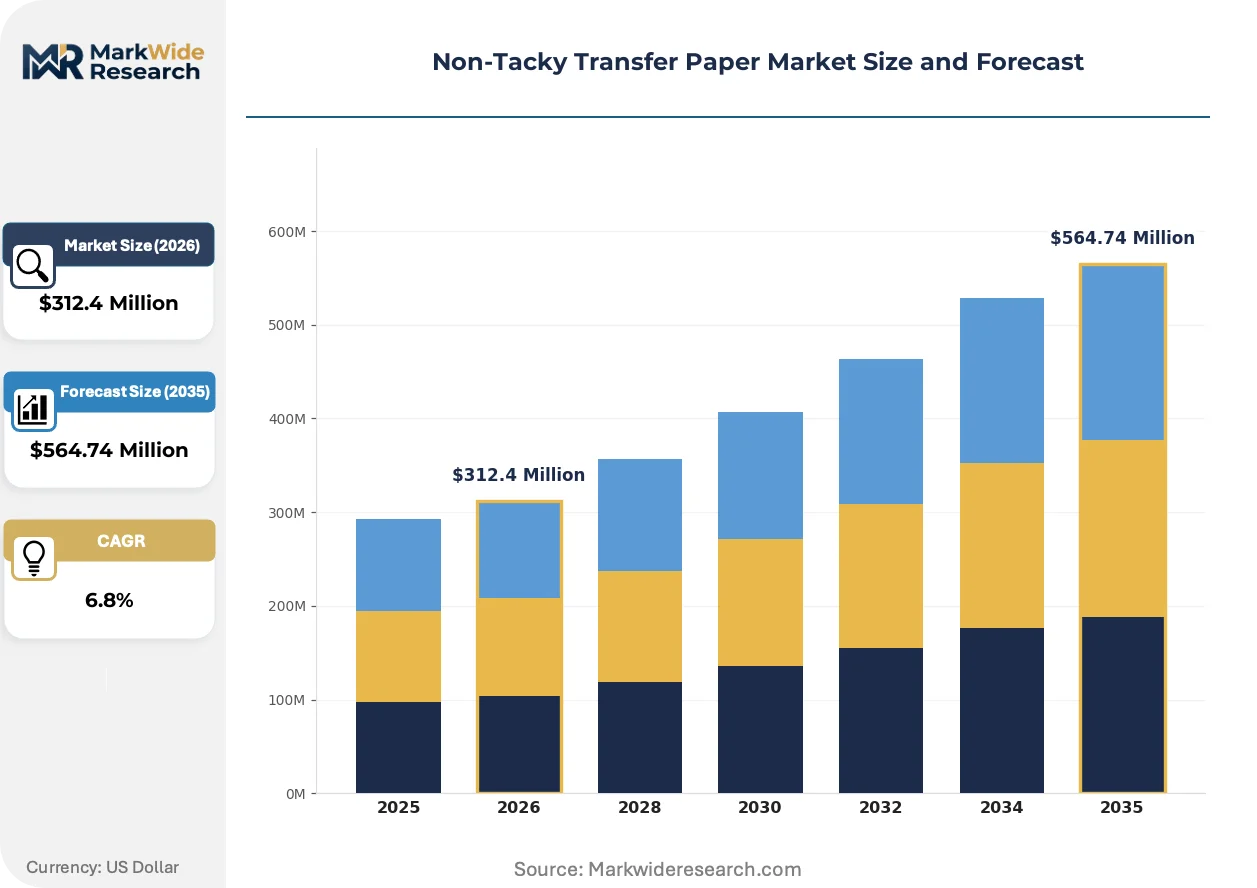
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Transfer Paper, Inkjet Transfer Paper, Watercolor Transfer Paper, Vinyl Transfer Paper Application: Textile Printing, Signage Creation, Craft Projects, Graphic Design End User: Small Businesses, Apparel Manufacturers, Craft Enthusiasts, Graphic Designers Distribution Channel: Online Retail, Wholesale Distributors, Specialty Stores, Supermarkets |
| Companies Covered | Felix Schoeller, Neenah Paper, Sappi Limited, Mondi Group, Ahlstrom-Munksjö, International Paper, Mitsubishi Paper Mills, Oji Paper, Itasa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Tacky Transfer Paper Market Evolving Landscape
Digital textile decoration is fragmenting procurement patterns across European supply chains, with technology convergence and regulatory chemistry mandates reshaping competitive positioning in coating formulations.
Laser-compatible transfer substrates now dominate volume among product types because toner adhesion and wash durability outperform aqueous alternatives in commercial apparel workflows. German industrial print clusters around Heidelberg and Munich are standardizing on these grades for on-demand production. Inkjet flexibility for watercolor and fine art reproduction is supplanting share only in niche decorator segments where pigment range outweighs throughput efficiency.
REACH and the EU Green Deal are tightening chemical disclosure requirements for silicone release layers, compelling elimination of perfluorinated compounds from coating formulations. Vendors with captive pulp sourcing and integrated chemical processing are absorbing compliance costs more efficiently than independent converters. The reformulation timeline is compressing most severely for mid-tier suppliers lacking environmental management certification.
Small businesses and craft enthusiasts are bypassing traditional wholesale distributors through direct-to-consumer platforms that eliminate minimum-order requirements. This channel disintermediation is visible most acutely in Germany and neighboring Benelux markets where online retail infrastructure supports rapid sample fulfillment. Wholesale paper merchants stocking digital transfer portfolios alongside specialty fine papers are losing volume to specialized e-commerce operators.
Non-Tacky Transfer Paper Market Segmentation
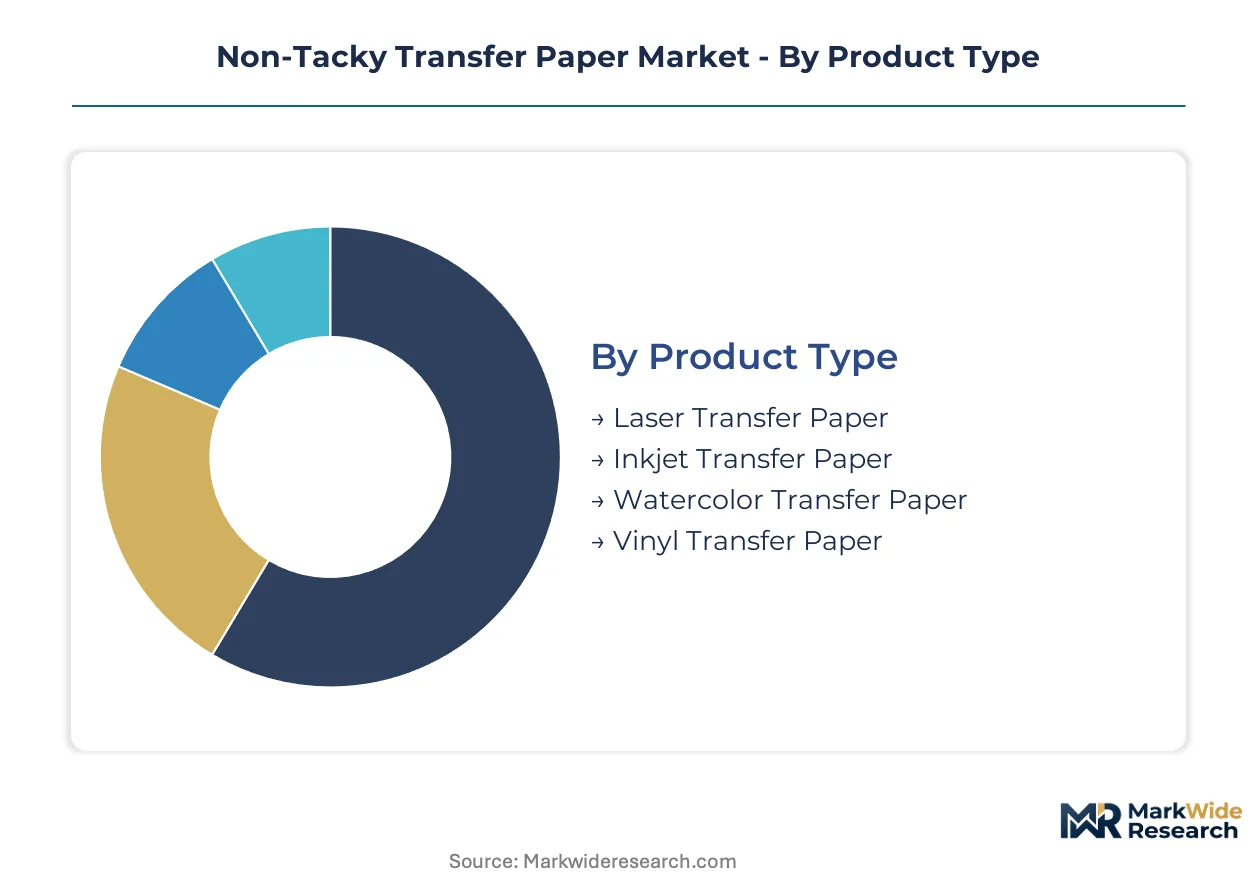
Non-tacky transfer paper segments fragment across toner compatibility, decoration substrate, and procurement channel. Each dimension carries distinct margin profiles and regulatory exposure that reshape vendor positioning.
Product Type:
REACH chemical disclosure mandates differentiate coating chemistry across substrate grades, with perfluorinated compound restrictions compressing reformulation timelines for silicone release layers.
- Laser Transfer Paper:Silicone-coated substrates engineered for toner adhesion and thermal transfer precision. Heidelberg and Munich industrial print clusters standardize on these grades for wash-durable apparel decoration, prioritizing throughput efficiency over pigment range.
- Inkjet Transfer Paper:PVA-barrier coatings optimized for aqueous ink absorption and color gamut expansion. Fine art reproduction specialists in Germany's decorator networks favor this grade where watercolor flexibility outweighs production speed constraints.
- Watercolor Transfer Paper:Clay-coated substrates with enhanced pigment receptivity for artistic applications.
- Vinyl Transfer Paper:Release-coated carriers for adhesive-backed film transfer in signage and vehicle wrap workflows.
Laser Transfer Paper handles the majority of throughput; Inkjet Transfer Paper is the fastest mover on share.
Application:
Cost tier stratification separates high-volume commercial workflows from low-batch craft consumption, with textile decoration commanding premium substrate specifications.
- Textile Printing:Heat-press transfer onto cotton, polyester, and blended fabrics requiring wash durability certification. German apparel manufacturers drive specification tightening for silicone purity and release consistency.
- Signage Creation:Rigid substrate decoration for retail displays and outdoor advertising. Sappi's Maastricht mill positions coated release papers for ceramic and metal transfer applications beyond textiles.
- Craft Projects:Small-batch personalization for hobbyist and DIY segments.
- Graphic Design:Professional proofing and prototype visualization workflows.
Textile Printing absorbs the dominant share of substrate volume; Signage Creation is expanding most quickly as industrial heat-transfer applications diversify.
End User:
Customer type determines order minimum tolerance and technical support requirements, with procurement patterns diverging between integrated manufacturers and fragmented craft segments.
- Small Businesses:On-demand decorators operating sub-500-unit production runs. Online retail platforms capture this segment by eliminating wholesale minimum-order thresholds through direct-to-consumer fulfillment.
- Apparel Manufacturers:Integrated textile producers with captive decoration lines. ISO 14001 certification filters procurement decisions for this segment, favoring vendors with audited environmental management systems.
- Craft Enthusiasts:Individual hobbyists purchasing sample quantities through specialized e-commerce operators.
- Graphic Designers:Creative professionals requiring color-accurate proofing substrates.
Apparel Manufacturers anchor substrate demand; Small Businesses are gaining share fastest as on-demand production models proliferate.
Distribution Channel:
Supply concentration in wholesale paper merchant networks is fragmenting under channel disintermediation pressure from digital retail infrastructure.
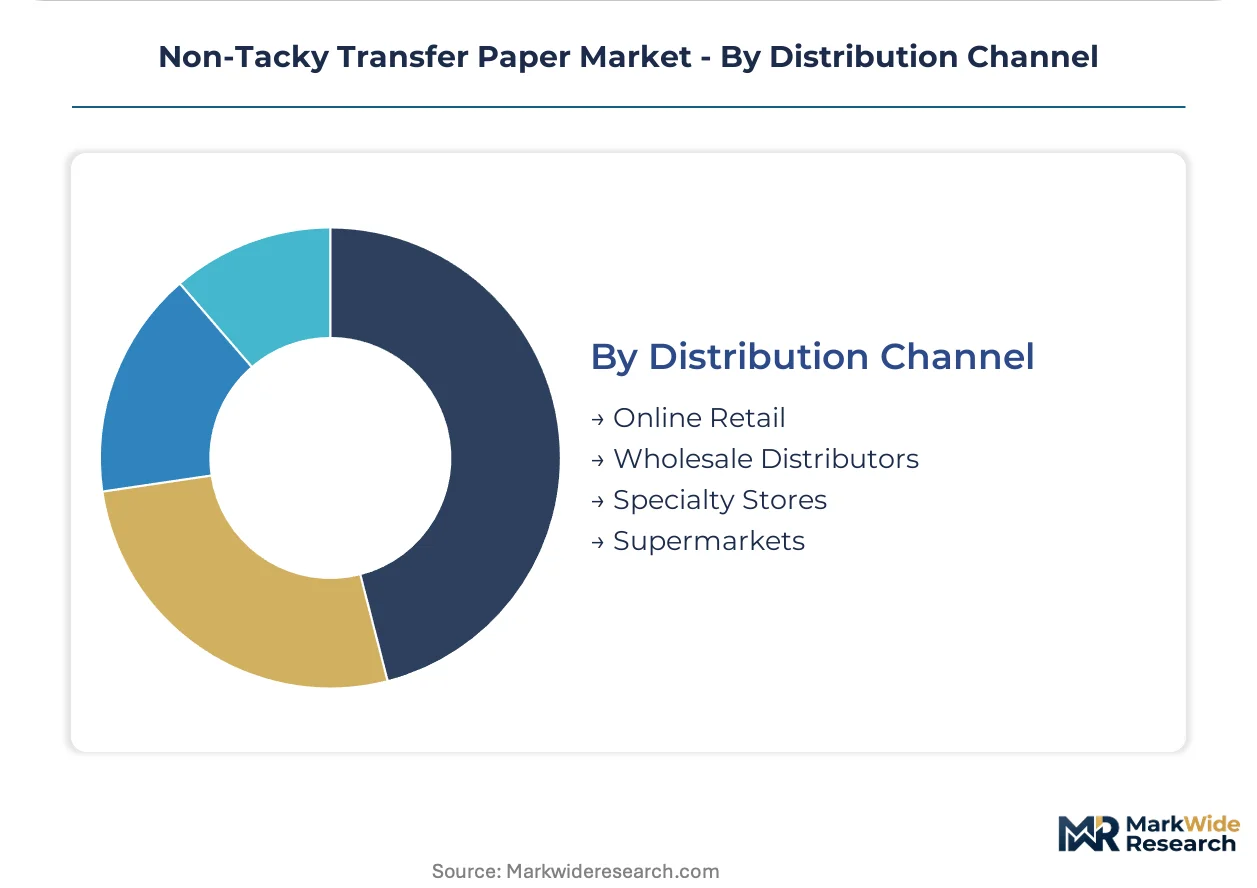
- Online Retail:Direct-to-consumer platforms enabling sample fulfillment and small-quantity procurement. Benelux and German markets show acute channel shift as craft enthusiasts bypass traditional distribution tiers.
- Wholesale Distributors:Paper merchants stocking digital transfer portfolios alongside specialty fine papers. Neenah Paper anchors North American volume through this channel, though share erosion to e-commerce operators accelerates.
- Specialty Stores:Local craft and art supply retailers serving immediate-need purchase occasions.
- Supermarkets:Mass-market retail with limited substrate grade availability.
Wholesale Distributors retain the largest volume position; Online Retail is climbing the fastest as procurement patterns digitize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH chemical disclosure mandates and the EU Green Deal are reshaping coating chemistry requirements across major manufacturing economies, with industrial print clusters driving substrate specification tightening in Germany, the United States, China, and Japan.
Germany
Heidelberg and Munich industrial print clusters prioritize laser transfer substrates for wash-durable apparel decoration. ECHA enforces perfluorinated compound restrictions under REACH, compelling coating reformulation across Bavarian production networks. Felix Schoeller leverages captive pulp sourcing from its Bavarian mills to sustain margin control amid compliance cost absorption.
United States
Apparel manufacturers in the Southeast and Pacific Northwest expand on-demand textile decoration capacity. EPA and OSHA jointly influence domestic manufacturing through volatile organic compound limits and workplace exposure standards for solvent-based coating operations. Neenah Paper anchors North American distribution through wholesale paper merchants stocking digital transfer portfolios.
China
Guangdong and Zhejiang provinces concentrate textile export manufacturing, pulling substrate demand toward high-volume laser-compatible grades. MEE implements dual carbon goals that tighten emissions standards for coating line operations. Yangtze River Delta industrial zones are standardizing on transfer papers that eliminate post-press cleaning cycles for small-batch production models.
Japan
Osaka and Tokyo metropolitan areas sustain demand for precision transfer substrates in technical textile applications. METI promotes environmental management certification adoption across paper processing supply chains. Mitsubishi Paper Mills and Oji Paper occupy positions within domestic substrate fabrication networks serving regional apparel decorators.
Netherlands
Benelux distribution infrastructure supports rapid sample fulfillment for craft enthusiasts bypassing wholesale minimum-order thresholds. EU Green Deal chemistry transparency requirements accelerate coating reformulation timelines for silicone release layers. Sappi's Maastricht technical paper mill positions coated release papers for industrial heat-transfer applications beyond textiles.
Non-Tacky Transfer Paper Market Competitive Landscape
Player mix skews toward integrated pulp-to-paper producers and specialty coating converters with environmental certification credentials. Market structure concentrates around vendors with captive fiber sourcing and audited solvent recovery systems. Three archetypes dominate: Bavarian-integrated producers controlling upstream pulp supply, North American wholesale-anchored distributors, and Asian mill-scale operators serving export textile manufacturing. Competitive moves center on coating line reconfiguration for REACH compliance and direct-to-consumer channel expansion to capture craft segment volume.
Within the integrated producer tier, Felix Schoeller exemplifies backward integration into captive pulp supply, while Sappi Limited occupies a position bridging European technical paper production with industrial heat-transfer applications. Among North American distributors, Neenah Paper anchors wholesale merchant relationships that stock digital transfer portfolios alongside specialty fine papers. These three companies represent the dominant competitive archetypes: upstream-integrated European specialists, mill-based technical paper producers with diversified application focus, and distribution-anchored North American substrate vendors.
| Leading Market Players |
|---|
| Felix Schoeller |
| Neenah Paper |
| Sappi Limited |
| Mondi Group |
| Ahlstrom-Munksjö |
| International Paper |
| Mitsubishi Paper Mills |
| Oji Paper |
| Itasa |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Bavarian pulp mills shapes both supply concentration and price floors for coating-grade substrates, with integrated producers commanding margin buffers that independent converters cannot replicate under REACH reformulation mandates.
Pricing Analysis
Certification level creates the primary spread across substrate tiers, with ISO 14001-audited environmental management systems commanding premium positioning over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by silicone purity grade and wash-durability certification. Cost compression in mid-tier grades is intensifying because independent converters absorb disproportionate compliance burdens without captive fiber sourcing. Small craft enthusiasts exhibit highest price sensitivity through direct-to-consumer channels, while apparel manufacturers prioritize auditability over unit cost.
Supply Chain Analysis
Germany and the Netherlands anchor European coating-grade substrate fabrication, with Bavarian mills feeding integrated producers and Maastricht technical paper operations serving industrial heat-transfer applications. Specialty release chemistries draw from a narrow base of European silicone suppliers, amplifying disruption risk from any single plant outage. Tariff exposure on pulp imports strains mid-tier converters lacking backward integration into captive fiber supply. Distribution runs through wholesale paper merchant networks, though channel disintermediation accelerates as craft enthusiasts bypass minimum-order thresholds through specialized e-commerce operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward apparel manufacturers consolidating procurement around ISO 14001-certified vendors, fragmenting volume across fewer substrate suppliers with audited environmental credentials.
For Market Incumbents: Consolidate coating line assets around REACH-compliant solvent recovery systems to defend share against emerging Asian mill-scale operators. Prioritize captive pulp sourcing integration to sustain margin control amid silicone supply concentration risks. Channel control through wholesale merchant relationships requires reinforcement as direct-to-consumer platforms erode traditional distribution tiers. For New Entrants and Emerging Players: Lead with online retail infrastructure targeting Benelux craft enthusiasts, the most penetrable segment where minimum-order elimination outweighs brand loyalty. Specialty coating converters without environmental certification face compressed timelines to capture share before regulatory barriers harden. Go-to-market positioning should emphasize rapid sample fulfillment and small-batch flexibility absent from wholesale distributor models. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors upstream-integrated European specialists with captive fiber supply and audited coating operations over distribution-anchored North American vendors. Long-term viability hinges on regulatory chemistry adaptation capacity rather than scale alone. Acquisition target archetype: mid-tier converters with reconfigurable coating lines and pending ISO 14001 certification. The signal to watch is ECHA enforcement intensity on perfluorinated compound restrictions as a margin compression trigger for non-compliant suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Line Reconfiguration | REACH compliance mandates 18-24 month capital cycles for solvent recovery system installation at Bavarian production facilities. |
| Captive Pulp Sourcing Integration | Felix Schoeller's Bavarian mills demonstrate margin resilience that independent converters cannot replicate under pulp cost volatility. |
| Direct-to-Consumer Channel Launch | Online retail platforms capture German craft enthusiasts bypassing wholesale minimum-order thresholds through rapid sample fulfillment. |
| ISO 14001 Certification Investment | Environmental management credentials become procurement filters for major European textile printers seeking supply chain auditability. |
| Industrial Heat-Transfer Diversification | Sappi's Maastricht mill positions coated release papers for ceramics and rigid substrates beyond textile decoration applications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with coating line managers, procurement leads at apparel manufacturers, wholesale paper merchant category buyers, and technical R&D directors at substrate converters; and secondary validation through REACH regulatory filings, ECHA substance restriction databases, customs trade data on pulp imports, and SEC disclosures from publicly traded paper producers. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and distribution channel dimensions.
Across the analysis window, projections incorporated toner compatibility segmentation, decoration substrate heat-transfer requirements, and procurement channel digitization patterns. CAGRs derived from historical volume trajectories adjusted for regulatory chemistry reformulation timelines and coating line reconfiguration cycles. Industry-specific forecast inputs included silicone release layer raw material cost indices and small-batch production model adoption rates among European print shops.
Forecasts assume regulatory continuity in EU REACH enforcement and US EPA volatile organic compound limits; material policy shifts in either jurisdiction would require re-modeling cross-border inventory management assumptions. Specific risk factors encompass ECHA perfluorinated compound restriction acceleration, pulp spot market volatility, and silicone supplier plant outages. Recalibration cycles align with material shifts in coating chemistry mandates and channel procurement digitization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
White Sack Kraft Paper Market
Paper & Paperboard Packaging
Paper Cone Cup Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Global Cooking and Baking Papers Market
Paper & Paperboard Packaging
Shredded Paper Filler Market
Paper & Paperboard Packaging
Display Paper Box Market
Paper & Paperboard Packaging
Asia-Pacific Coated Paper Market
Paper & Paperboard Packaging
GCC Paper Cup Market
Paper & Paperboard Packaging
Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Saudi Arabia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Transfer Paper Market