
 Industrial Paper Sacks Market | 2026-2036
Industrial Paper Sacks Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Paper Sacks Market Outlook
Buyer concentration among cement and chemical distributors is rebalancing toward multi-year supply contracts with tier-one converters. Mondi Group leverages integrated kraft paper capacity to secure volume commitments across Central European construction supply chains. Smurfit Kappa anchors its position through dedicated sack converting lines co-located with customer filling operations. WestRock competes by extending its containerboard expertise into high-performance industrial grades for abrasive material handling.
Industrial paper sacks are multi-wall containers manufactured from kraft paper plies, typically ranging from 2 to 6 layers with grammages between 70 and 400 gsm, designed to transport dry bulk solids under mechanical stress and moisture exposure. Valve sacks dominate filling-speed-sensitive applications where automated closing mechanisms reduce spillage rates below open-mouth alternatives. Recycled grade volumes expand fastest as European REACH-aligned circularity mandates tighten virgin fiber quotas, though virgin kraft retains margin concentration in food-contact and hazardous chemical segments where tensile strength specifications remain non-negotiable.
Germany's KBA enforces transport safety standards for industrial packaging containing hazardous chemicals, while the EU F-Gas Regulation indirectly pressures cement producers toward lower-carbon processes that alter sack specification requirements. The EU Green Deal's packaging waste targets compel sack converters to certify recyclability through ECHA-aligned testing protocols. Stakeholders must monitor how diverging national implementations of the EU Packaging and Packaging Waste Regulation reshape cross-border qualification requirements for recycled-content claims.
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing virgin fiber quotas while construction material distributors consolidate procurement volumes across North America, forcing sack converters to reconfigure supply agreements and certification pipelines simultaneously.
Growth Catalysts
- Rhine-Ruhr Industrial Corridor Concentration:Cement and chemical clusters in Germany maintain dense supplier networks that sustain high-volume valve sack demand for automated filling operations.
- EU Green Deal Packaging Targets:ECHA-aligned recyclability testing protocols compel converters to certify circular content claims, accelerating recycled grade adoption across European construction supply chains.
- REACH-Aligned Circularity Mandates:Tightening virgin fiber quotas in hazardous chemical segments preserve premium margins for high-tensile virgin kraft specifications in food-contact applications.
Market Restraints
- Kraft Pulp Input Volatility:Energy-intensive kraft pulping exposes converters to natural gas price swings that compress margin structures during heating season peaks.
- Valve Sack Technical Limitations:Automated closing mechanisms require precise grammage tolerances between 70-400 gsm that constrain material substitution flexibility in multi-wall configurations.
- F-Gas Regulation Friction:EU cement producer process modifications alter sack specification requirements mid-contract, forcing costly requalification cycles.
Strategic Opportunities
- Co-Located Converting Lines:Dedicated sack production facilities positioned adjacent to customer filling operations reduce logistics costs and lock in multi-year volume commitments.
- Recycled Content Certification:ECHA-aligned testing protocols create first-mover advantage for converters achieving mass-balance verification ahead of competitor compliance timelines.
- High-Performance Industrial Grades:Containerboard expertise extension into abrasive material handling captures share in specialty chemical and mineral segments.
Industry Challenges
- Multi-Wall Lamination Skill Gap:2-6 ply adhesive bonding and moisture barrier integration require specialized technicians that converters struggle to recruit in Central European labor markets.
- Cross-Border Qualification Complexity:Divergent national implementations of EU Packaging and Packaging Waste Regulation create redundant testing burdens for recycled-content claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Paper Sacks Market |
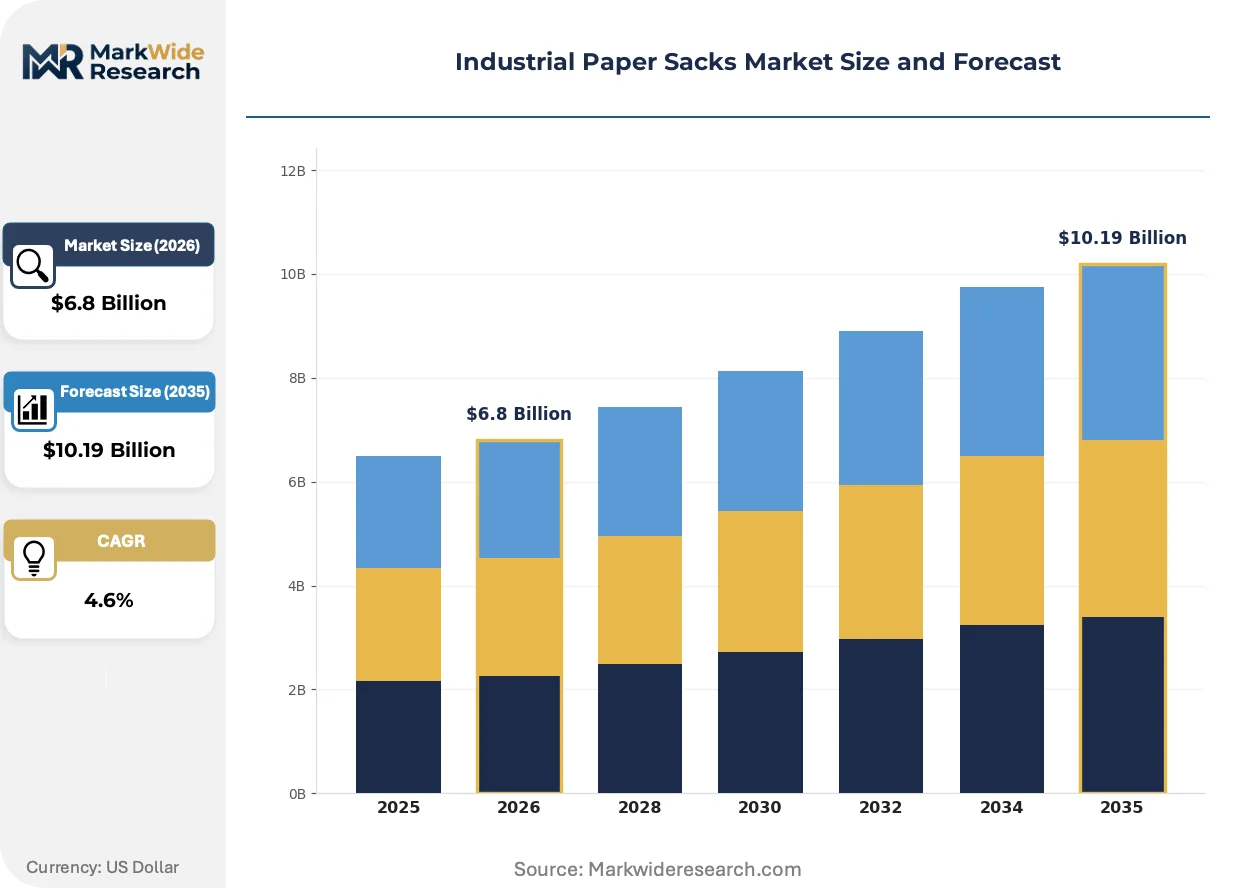
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Mouth Sacks, FIBCs, Valve Sacks, Flat Sacks End User: Cement Industry, Food Processing, Chemicals, Agriculture Mode: Manual, Automated, Semi-Automated, Bulk Grade: Recycled, Virgin, Eco-Friendly, Custom |
| Companies Covered | Mondi Group, Smurfit Kappa Group, WestRock Company, International Paper Company, Billerud, Segezha Group, DS Smith, Gascogne Group, Hood Packaging Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Paper Sacks Market Strategic Shifts
Material science advances and regulatory compliance automation are restructuring how industrial paper sacks achieve performance specifications while satisfying circular economy mandates.
Barrier coating technology is converging with bio-based polymer research to replace polyethylene moisture layers in multi-wall kraft constructions. Cement distributors in Germany's industrial corridors are piloting these formulations at scale. This convergence is compressing the timeline for fully recyclable sack certification under ECHA protocols.
REACH chemical safety data integration is mandating digital traceability from pulp source to end-use filling operation. EU F-Gas Regulation alignment requires converters to document carbon intensity across kraft paper plies. Hazardous chemical segments face the steepest compliance burden, with KBA transport safety standards now requiring batch-level QR coding.
Buyer concentration among North American construction material distributors is collapsing spot-market procurement into consolidated annual contracts with tier-one converters. Open-mouth sack specifications are losing share to valve configurations as automated filling lines displace manual operations. This pattern concentrates most visibly in cement packaging across the US Great Lakes industrial belt.
Industrial Paper Sacks Market Segmentation
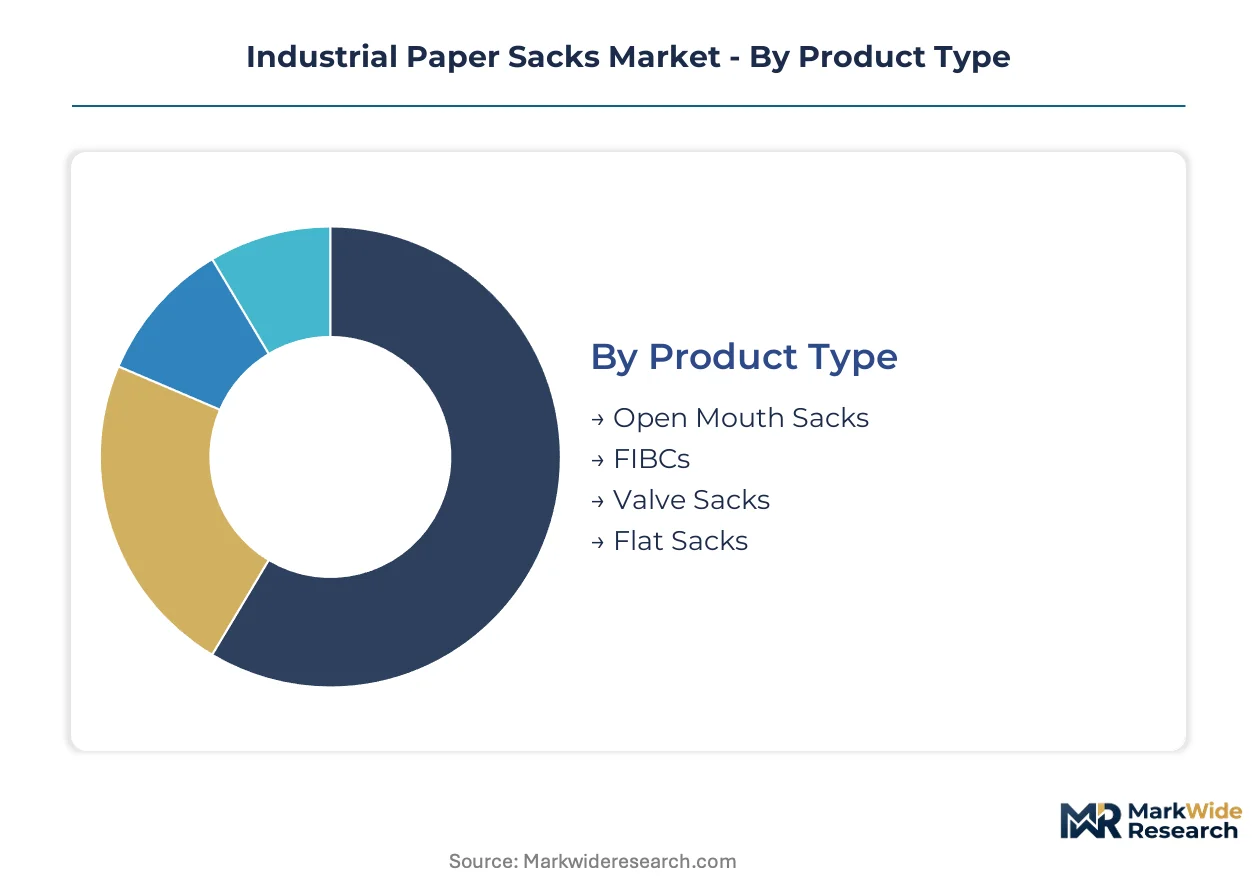
Industrial paper sack purchasing decisions pivot on filling speed requirements, chemical compatibility, and circularity certification. Each segmentation dimension carries distinct margin structures and technical qualification barriers that reshape converter capacity allocation.
Product Type:
Buyers select configurations based on automated line compatibility and spillage risk tolerance in high-speed operations.
- Valve Sacks:Multi-wall kraft constructions with integrated self-closing valves enable filling rates exceeding 2,000 units per hour. Cement distributors in Germany's Rhine-Ruhr corridor specify these for automated lines where spillage must stay below 0.3%.
- Open Mouth Sacks:Flat-folded kraft paper tubes require manual or mechanical stitching after filling. Food processors in Italy prefer these for specialty flour grades where batch traceability demands frequent line changeovers.
- FIBCs:Flexible intermediate bulk containers handle 500-2,000 kg mineral loads. Chemical clusters in Belgium deploy these for resin pellet transport where palletization efficiency outweighs unit cost premiums.
- Flat Sacks:Single-ply kraft sheets serve low-stress wrapping applications. Agricultural cooperatives in France utilize these for seed packaging where moisture exposure remains minimal.
Volume sits with Valve Sacks; growth tilts toward FIBCs as chemical distributors consolidate bulk procurement.
End User:
Application-specific tensile strength and barrier requirements fragment converter order books across industrial verticals.
- Cement Industry:Abrasion-resistant 4-ply kraft constructions withstand pneumatic filling pressures. German producers under KBA transport safety mandates require batch-level QR traceability for hazardous dust containment.
- Chemicals:REACH-aligned safety data integration drives multi-layer barrier specifications. Dutch petrochemical clusters demand ECHA-certified recyclability for polymer additive packaging.
- Food Processing:Virgin kraft maintains food-contact compliance despite recycled grade expansion. Italian pasta manufacturers specify 80 gsm inner plies to prevent fat migration.
- Agriculture:Cost-sensitive fertilizer distributors accept lower grammage tolerances. French agricultural supply chains prioritize unit economics over automated filling compatibility.
Revenue concentrates in Cement Industry; margin expansion favors Chemicals as hazardous material certification barriers rise.
Mode:
Capital intensity of filling infrastructure determines procurement contract duration and technical service requirements.
- Automated:High-speed rotary fillers demand precise valve alignment and grammage consistency. Belgian cement terminals specify 70-400 gsm tolerances within 2% variance for uninterrupted line operation.
- Semi-Automated:Hybrid systems balance throughput with changeover flexibility. Spanish construction material distributors favor these for seasonal demand fluctuations.
- Manual:Low-volume operations tolerate wider specification ranges. Portuguese agricultural packers accept open-mouth configurations for specialty seed lots.
- Bulk:Loose-fill transport eliminates unit packaging entirely. German chemical producers deploy these for captive intra-site material movements.
Procurement volume clusters in Automated; contract value expands fastest in Semi-Automated as mid-tier distributors upgrade legacy lines.
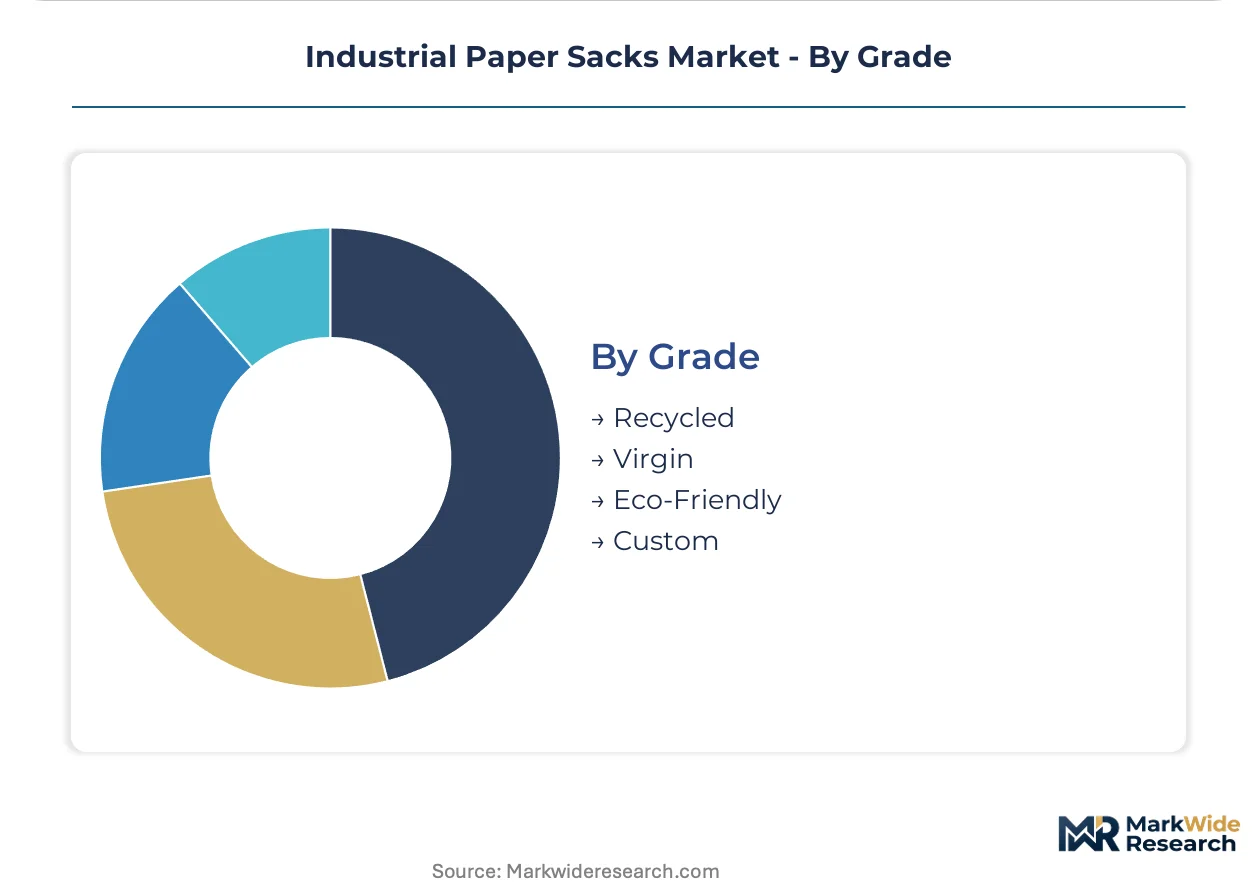
Grade:
Circularity mandates and performance specifications create divergent cost-quality tradeoffs across end-use segments.
- Recycled:Post-consumer kraft pulp blends satisfy EU Green Deal targets. French cement distributors pilot these formulations under ECHA-aligned mass-balance verification protocols.
- Virgin:Unbleached softwood kraft delivers tensile strength above 8 kN/m. Italian food-contact applications mandate these specifications despite 15-20% cost premiums.
- Eco-Friendly:Bio-based barrier coatings replace polyethylene moisture layers. German chemical clusters test these for fully recyclable sack certification.
- Custom:Engineered ply combinations address niche performance requirements. Belgian specialty mineral processors specify these for abrasive handling beyond standard grades.
Shipment volume favors Virgin; regulatory momentum pushes Recycled toward parity as REACH-aligned quotas tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for industrial paper sacks clusters in cement and chemical corridors where automated filling infrastructure concentrates procurement volumes. Germany's Rhine-Ruhr belt anchors European valve sack consumption. North American construction distributors are consolidating annual contracts away from spot markets.
Germany
Cement terminals along the Rhine-Ruhr corridor specify valve sacks with 70-400 gsm tolerances for high-speed rotary fillers. KBA transport safety standards mandate batch-level QR traceability for hazardous dust containment. Chemical clusters in Leverkusen and Ludwigshafen pilot bio-based barrier coatings under ECHA-aligned recyclability protocols.
United States
Construction material distributors across the Great Lakes industrial belt are collapsing spot procurement into multi-year supply agreements. EPA industrial waste guidelines indirectly shape sack specification requirements for cement producers. Michigan and Ohio cement terminals drive valve sack demand as automated filling lines displace manual operations.
France
Agricultural cooperatives in the Paris Basin utilize flat sacks for seed packaging where moisture exposure remains minimal. EU Green Deal packaging waste targets compel converters to certify circular content claims through national implementation frameworks. Cement distributors in Lille and Lyon pilot recycled-grade formulations under mass-balance verification.
Belgium
Petrochemical clusters in Antwerp deploy FIBCs for resin pellet transport where palletization efficiency outweighs unit cost premiums. REACH-aligned safety data integration drives multi-layer barrier specifications for polymer additive packaging. Belgian cement terminals specify precise grammage tolerances within 2% variance for uninterrupted automated line operation.
Italy
Food processors in the Po Valley prefer open-mouth sacks for specialty flour grades where batch traceability demands frequent line changeovers. Virgin kraft maintains food-contact compliance despite recycled grade expansion across construction segments. Pasta manufacturers in Emilia-Romagna specify 80 gsm inner plies to prevent fat migration.
Industrial Paper Sacks Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue adjacent flexible packaging segments with lower capital barriers. The market structures around integrated kraft paper manufacturers, dedicated sack converters, and containerboard specialists extending into industrial grades. Three archetypes dominate: pulp-integrated multinationals with captive fiber supply, regional converters co-located with customer filling operations, and diversified paperboard players leveraging existing mill infrastructure. Competitive moves center on co-location partnerships and recycled-content certification races.
Within the integrated pulp-to-sack tier, Mondi Group and Smurfit Kappa Group exemplify archetypes with captive kraft paper capacity. WestRock Company occupies a position among containerboard specialists extending expertise into high-performance industrial grades. These three represent the dominant competitive vectors: backward integration into fiber supply, geographic proximity to automated filling infrastructure, and portfolio extension from adjacent paperboard segments.
| Leading Market Players |
|---|
| Mondi Group |
| Smurfit Kappa Group |
| WestRock Company |
| International Paper Company |
| Billerud |
| Segezha Group |
| DS Smith |
| Gascogne Group |
| Hood Packaging Corporation |
| Others |
Value Chain & Pricing Dynamics
Buyer consolidation among North American construction material distributors is compressing spot-market premiums into multi-year contract rates, forcing sack converters to absorb kraft pulp volatility through captive fiber supply or risk margin erosion during heating season peaks.
Pricing Analysis
Volume concentrates in standard-grade valve sacks while margin expansion sits with virgin kraft specifications for hazardous chemical and food-contact applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Pricing pressure stems from natural gas price swings in energy-intensive kraft pulping, squeezing converter margins during winter demand spikes. Agricultural distributors exhibit highest price sensitivity, while cement terminals under KBA mandates accept premiums for batch-level traceability.
Supply Chain Analysis
Freight cost exposure runs through long-haul kraft paper shipments from Nordic pulp mills to Central European converting facilities, incentivizing co-location strategies. Supply concentrates in Sweden, Finland, and Germany for virgin kraft pulp, with recycled fiber sourcing fragmented across French and Italian collection networks. Raw material dependencies center on softwood pulp, natural gas for pulping energy, and bio-based barrier coatings under development. Single-source vulnerability sits with specialized multi-wall lamination technicians in tight Central European labor markets. Distribution runs through direct mill-to-filler pipelines for tier-one cement terminals, with regional distributors relying on converter warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over kraft pulp supply and downstream co-location with automated filling infrastructure determine competitive viability.
For Market Incumbents: Anchor market position through backward integration into Nordic kraft pulp capacity or long-term offtake agreements that lock in fiber supply during price volatility cycles. Invest in ECHA-aligned recyclability certification ahead of competitor compliance timelines to capture premium pricing for mass-balance verified recycled grades. Defend against emerging flexible packaging substitutes by extending high-performance industrial grade expertise into specialty chemical segments with non-negotiable tensile specifications. For New Entrants and Emerging Players: Begin with semi-automated filling infrastructure upgrades at mid-tier construction distributors in Spain and Portugal, where seasonal demand fluctuations create service gaps that agile converters can exploit. Target agricultural cooperatives in France with cost-optimized flat sack formulations where moisture exposure remains minimal and price sensitivity dominates procurement decisions. Pursue co-location partnerships with regional cement terminals seeking to reduce logistics costs through dedicated production lines. For Investors and Strategic Acquirers: The window for entry favors regional converters with established co-location relationships and pending ECHA certification that larger players can accelerate through capital injection. Long-term viability hinges on exposure to EU Green Deal packaging waste implementation timelines and REACH-aligned circularity mandate enforcement intensity. Monitor divergent national implementations of EU Packaging and Packaging Waste Regulation as the signal for which recycled-content claims will face redundant testing burdens versus streamlined qualification pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Kraft Pulp | Captive fiber supply insulates Mondi Group and Smurfit Kappa from natural gas price volatility in Nordic pulping. |
| Co-Located Converting Lines | Smurfit Kappa's dedicated sack production adjacent to Belgian cement terminals reduces logistics costs and locks volume. |
| ECHA-Aligned Recyclability Certification | First-mover mass-balance verification captures premium pricing as EU Green Deal targets tighten virgin fiber quotas. |
| High-Performance Industrial Grade Extension | WestRock's containerboard expertise expansion into abrasive material handling captures specialty chemical share. |
| Bio-Based Barrier Coating Development | German chemical clusters in Leverkusen pilot polyethylene replacements to achieve fully recyclable sack certification. |
Study Parameters
Multi-period observation of kraft pulp price indices, EU regulatory implementation timelines, and cement distributor procurement patterns anchored the trend analysis, supplemented by interviews with sack converter plant managers, procurement leads at construction material distributors, technical R&D directors at paper manufacturers, and channel partners in Central European logistics networks. Secondary validation drew from customs and trade data tracking kraft paper cross-border flows, SEC filings of integrated paper manufacturers, Cefic chemical industry reports, and ECHA regulatory guidance documents. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices mapped kraft pulp supply volumes through converting capacity to end-use demand by segment, with CAGRs derived from regression analysis against construction activity indices and chemical production forecasts. Segmentation dimensions modeled include product type, end-use industry, filling mode automation level, and grade certification tier. Industry-specific forecast inputs incorporated EU F-Gas Regulation implementation pace affecting cement process modifications and REACH-aligned circularity mandate enforcement intensity across member states.
Underlying measurement precision varies by segment; automated filling mode and cement end-use carry tighter precision due to consolidated procurement data availability, while manual operations and agricultural applications exhibit wider confidence intervals. Forecasts reflect assumptions about regulatory enforcement consistency and pulp price normalization that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Kitchen Oil Absorbing Paper Market
Paper & Paperboard Packaging
Global Sack Kraft Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paper Coaster Market
Paper & Paperboard Packaging
Waxed Paper Packaging Market
Paper & Paperboard Packaging
Kraft Paper Shopping Bag Market
Paper & Paperboard Packaging
Wax-Coated Paper Market
Paper & Paperboard Packaging
Bamboo Packaging Market
Paper & Paperboard Packaging
United States Corrugated Packaging Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Binder's Board Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Paperboard Container Market
Paper & Paperboard Packaging
China Corrugated Packaging Market
Paper & Paperboard Packaging
Coated Duplex Board Market