
 Heat Sealable Pulp Board Tray Market | 2026-2036
Heat Sealable Pulp Board Tray Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Sealable Pulp Board Tray Market Analytics
Plastic substitution is consolidating demand toward fiber-based formats across European and North American retail supply chains. Huhtamaki Oyj leverages its molded fiber manufacturing footprint to anchor production close to Nordic food processing clusters. Smurfit WestRock competes through backward integration into recycled pulp supply, securing feedstock cost stability. Mondi Group plc differentiates via barrier coating R&D, extending shelf-life performance without polymer films.
Heat sealable pulp board trays are rigid fiber containers manufactured from pressed wood pulp with thermoplastic or bio-based seal coatings, typically rated for temperatures between minus forty and one hundred twenty degrees Celsius and engineered for hermetic closure with lidding film. The primary purpose is to replace expanded polystyrene and PET trays in protein, produce, and prepared meal distribution where leak resistance and modified atmosphere compatibility are essential. Single compartment designs dominate volume due to standardized meat and poultry packaging formats, while multi compartment configurations capture premium positioning in ready meal and medical kit applications where separation integrity matters. Sustainable material grade segments attract disproportionate margin pools as brand owners certify circularity claims through third party chain of custody protocols.
The EU Packaging and Packaging Waste Regulation and FDA food contact substance notifications jointly determine barrier coating chemistries and migration limits permissible in direct food applications, effectively filtering which pulp board formulations achieve commercial scale. BIS certification requirements in India and GB standards in China add further compliance layers for exporters targeting those domestic markets. Stakeholders must monitor evolving extended producer responsibility fee structures and recyclability labeling mandates, as these mechanisms will determine which coating technologies retain cost competitiveness against emerging aluminum and molded starch alternatives.
Market Dynamics
Retail consolidation across Northern Europe is compressing supplier margins while simultaneously mandating uniform sustainable packaging standards across entire store networks. This structural pressure is forcing pulp board tray manufacturers to scale barrier coating capabilities or exit the category entirely.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Binding reduction targets for single-use plastics are accelerating retailer phase-out timelines for expanded polystyrene trays in fresh protein distribution.
- Modified atmosphere packaging:Heat sealable fiber trays with oxygen barrier coatings are capturing shelf-ready meat and poultry applications previously locked into multilayer plastic formats.
- German retail chain concentration:Centralized procurement by Aldi, Lidl, and REWE Group is creating volume anchors that justify dedicated pulp molding capacity investments.
Market Restraints
- Recycled pulp supply concentration:Nordic and Baltic states control the majority of food-grade recycled fiber supply, creating feedstock vulnerability for non-integrated converters.
- Barrier coating migration limits:FDA food contact substance notifications and EFSA evaluations restrict acceptable chemistries, extending product qualification timelines.
- Aluminum tray substitution:Infinitely recyclable aluminum formats are capturing premium ready-meal segments where microwave compatibility and extended shelf life justify higher unit costs.
Strategic Opportunities
- Indian domestic market expansion:BIS certification requirements and FSSAI food contact standards are creating compliant supply scarcity that early entrants can capture.
- Medical kit multi-compartment designs:Sterile separation requirements in pharmaceutical distribution represent a high-margin application with limited incumbent competition.
- Extended producer responsibility fee differentials:EU member state implementations of modulated EPR fees are structurally advantaging fiber-based formats over plastic alternatives.
Industry Challenges
- Barrier coating R&D talent scarcity:Polymer chemists with food packaging migration expertise command premium compensation, constraining mid-tier manufacturer innovation pipelines.
- Heat seal calibration complexity:Achieving hermetic closure across variable pulp density and moisture content requires precision engineering that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Sealable Pulp Board Tray Market |
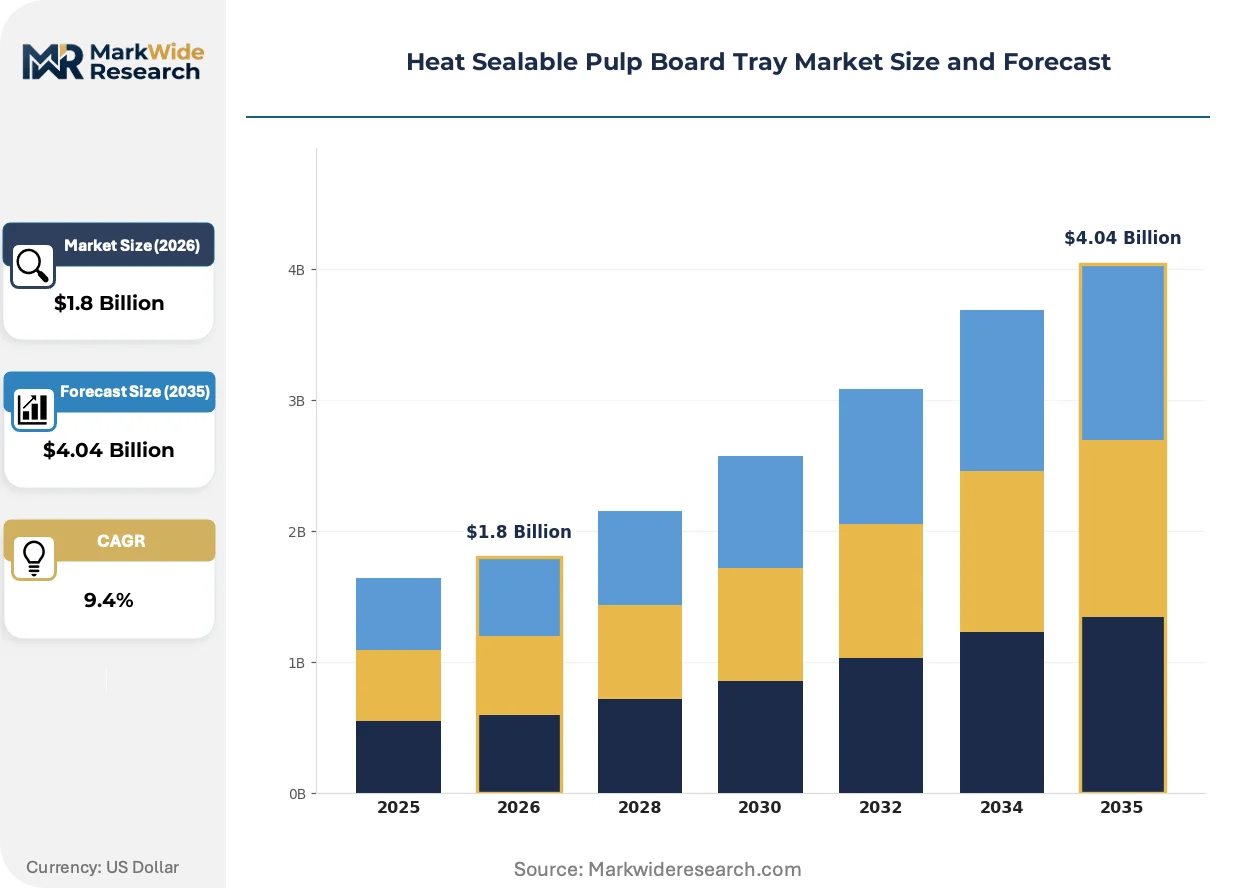
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Compartment, Multi Compartment, Custom Shapes, Stackable End Use Industry: Food Packaging, Medical Supplies, Electronics, Retail Packaging Material Grade: Recycled, Virgin, Sustainable, Composite Distribution Channel: Online Retail, Wholesale, Direct Sales, Specialty Stores |
| Companies Covered | Evesham Specialist Packaging Ltd, Sappi Limited, Huhtamaki Oyj, Smurfit WestRock, Mondi Group plc, International Paper Company, Graphic Packaging Holding Company, Brødrene Hartmann A/S, Amcor plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Sealable Pulp Board Tray Market Evolving Landscape
Barrier coating chemistry is undergoing rapid iteration as manufacturers seek to match polymer film performance without sacrificing end-of-life fiber recyclability. This technical race is compressing product development cycles and reshaping R&D investment priorities.
Water-based acrylic and bio-polyester hybrid coatings are absorbing moisture resistance and grease barrier functions previously requiring polyethylene lamination. Poultry processors in the Netherlands and Denmark are qualifying these formulations for high-fat content applications at accelerated pace. The technology is absorbing market share from conventional extrusion-coated alternatives by eliminating the plastic separation step in paper mill pulping lines.
REACH authorization requirements for per- and polyfluoroalkyl substances are eliminating fluorochemical barrier treatments from food contact applications by 2026. Industrial consequence includes forced reformulation of existing product lines and qualification of alternative oleophobic chemistries. Fresh produce packaging for Central European retail chains is most affected, with suppliers accelerating bio-wax and clay coating trials to maintain contract compliance.
Centralized sustainable packaging procurement offices are consolidating supplier relationships from regional fragmentation toward single-source national agreements. German and French retail buying cooperatives are displacing legacy distributor networks with direct manufacturer contracts audited for chain-of-custody certification. This concentration is most visible in the Nordic countries, where S Group and Coop Denmark have unified specifications across fresh meat and prepared meal categories.
Heat Sealable Pulp Board Tray Market Segmentation
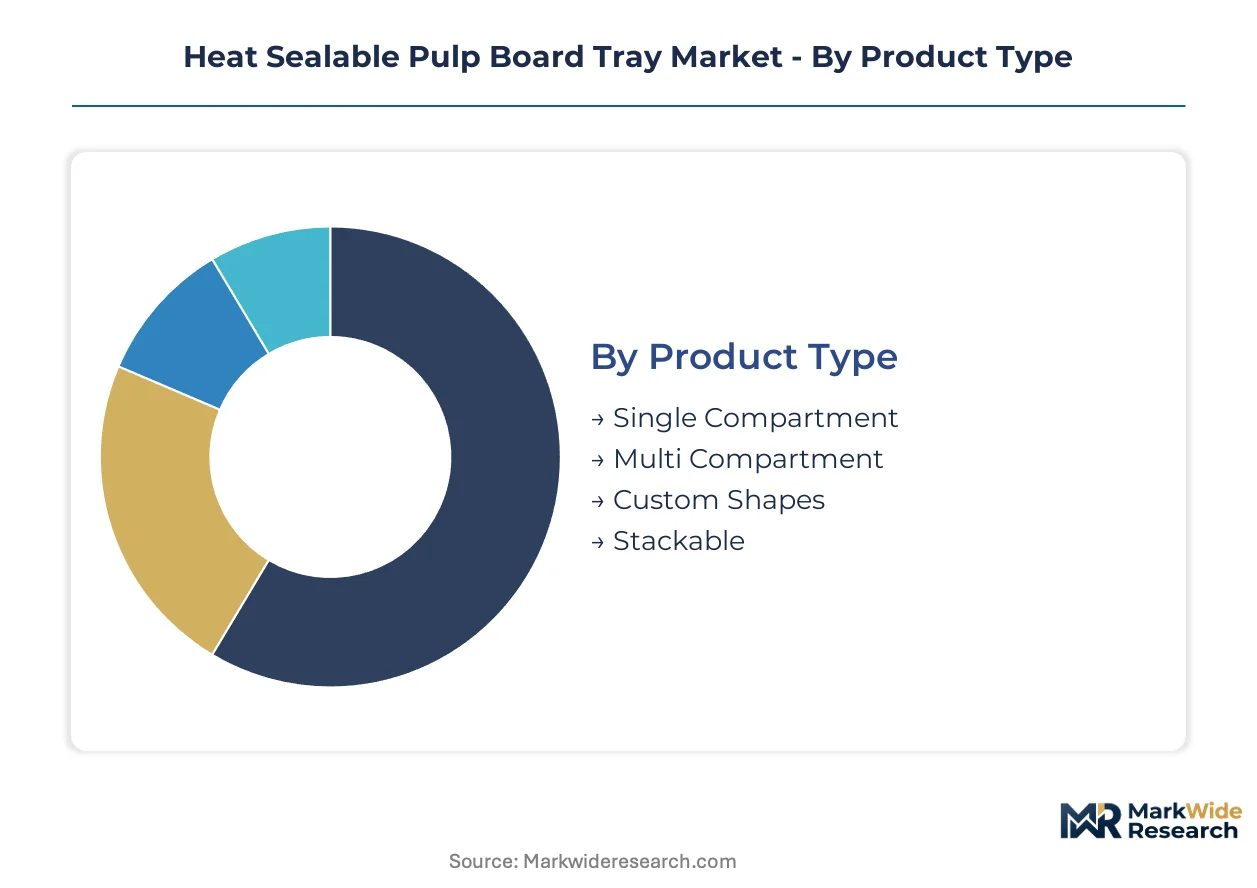
Segmentation in the heat sealable pulp board tray market reveals how technical specifications align with distinct value chains. Tray geometry, barrier requirements, and procurement channels each create separate competitive arenas with divergent margin structures and qualification barriers.
Product Type:
Single compartment designs function as standalone standardized units for high-volume protein packaging, while multi-compartment and custom configurations embed into specialized distribution systems requiring precise dimensional matching.
- Single Compartment:Pressed pulp trays with uniform cavity dimensions dominate fresh meat and poultry distribution across German retail chains. Aldi and Lidl procurement offices specify these formats for automated lidding line compatibility, locking in multi-year volume commitments.
- Multi Compartment:Segmented fiber structures with hermetic dividers capture ready-meal and medical kit applications where separation integrity prevents cross-contamination. Dutch meal kit distributors specify these for sauce-protein-starch combinations requiring modified atmosphere preservation in each zone.
- Custom Shapes:Die-cut pulp formations engineered for irregular produce contours or branded retail presentation.
- Stackable:Nesting tray designs with interlocking rim profiles for warehouse density optimization.
Volume placements concentrate in single compartment formats; the faster expansion belongs to multi compartment designs.
End Use Industry:
Application-driven demand splits between food contact systems governed by EFSA migration limits and non-food sectors with divergent sterility or static-control requirements.
- Food Packaging:Direct-contact fiber trays with oxygen barrier coatings absorb the majority of European pulp molding capacity. Danish poultry processors and Dutch produce distributors specify heat sealable formats for shelf-ready modified atmosphere packaging that replaces expanded polystyrene.
- Medical Supplies:Sterile-grade pulp trays with gamma-irradiation compatibility serve pharmaceutical kitting and surgical instrument packaging. German hospital supply chains specify these for single-use sterile field applications where fiber-based formats reduce waste processing costs.
- Electronics:Anti-static pulp formulations for component shipping and ESD-sensitive device protection.
- Retail Packaging:Display-ready trays for consumer goods presentation with print-grade surfaces.
Food packaging commands absolute volume leadership; medical supplies are climbing the fastest as sterility regulations tighten.
Material Grade:
Feedstock sourcing strategies separate cost-optimized recycled formulations from premium certified grades that command EPR fee advantages and chain-of-custody premiums.
- Recycled:Post-consumer fiber pulps processed to food-grade cleanliness standards dominate European tray production. Nordic paper mills supply this feedstock to converters serving centralized retail procurement offices with circularity certification requirements.
- Sustainable:FSC-certified or PEFC-tracked fiber grades with verified chain-of-custody documentation attract modulated EPR fee discounts in France and Germany. REWE Group and S Group specify these grades for private label meat packaging to meet corporate sustainability targets.
- Virgin:Unbleached kraft fiber for maximum structural integrity in deep-draw applications.
- Composite:Hybrid structures combining pulp with agricultural fiber residues for regional supply security.
Recycled fiber anchors current volume; sustainable certified grades are gaining share fastest as retailer EPR obligations intensify.
Distribution Channel:
Channel structure determines qualification depth and relationship economics, from transactional wholesale to embedded direct partnerships with technical integration requirements.
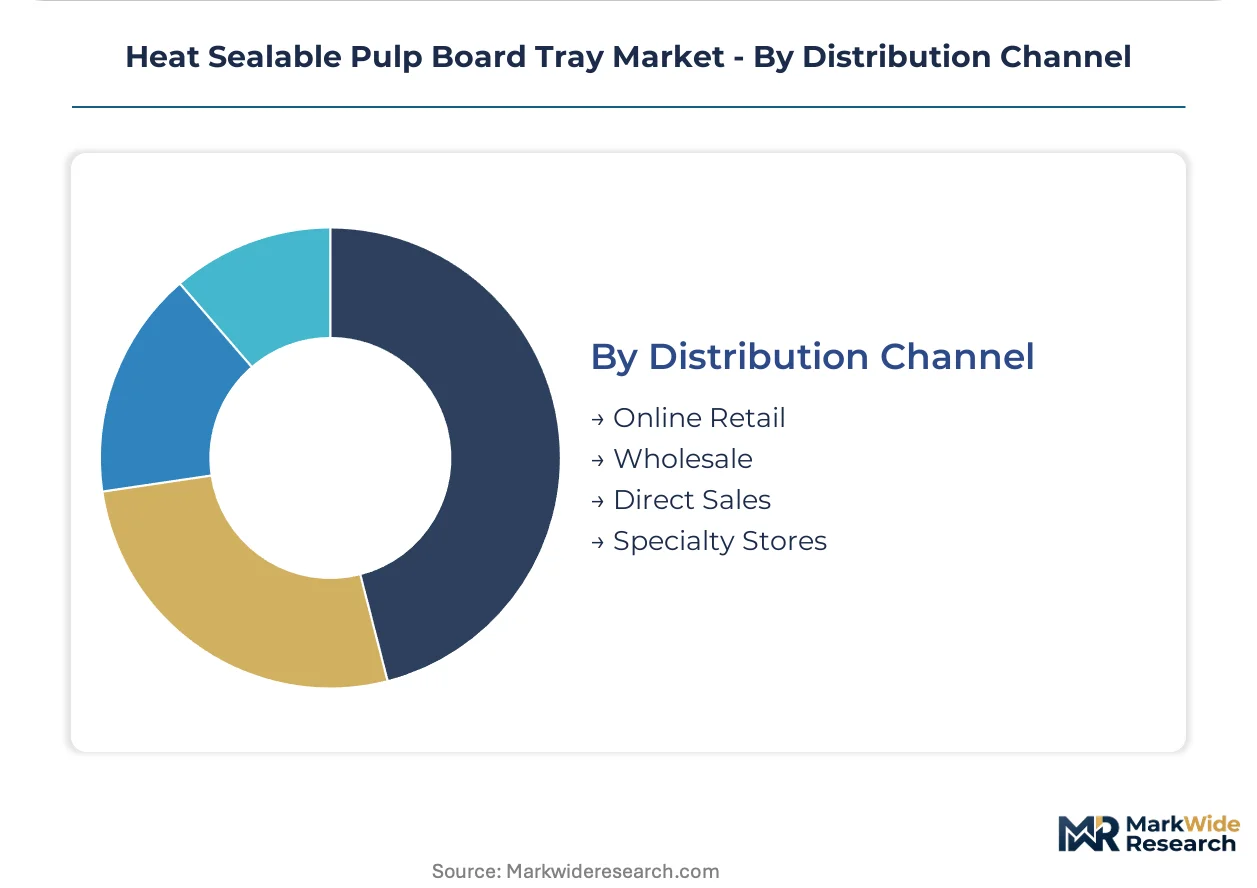
- Direct Sales:Manufacturer-to-retailer contracts with specification co-development and dedicated line qualification. French buying cooperatives and German discount chains prefer this channel for national account uniformity and audit transparency.
- Wholesale:Distributor-mediated supply to regional food processors and smaller retail networks lacking centralized procurement infrastructure.
- Online Retail:E-commerce platforms serving small-batch custom orders and rapid prototyping for niche applications.
- Specialty Stores:Premium channel for organic retailers and boutique food producers with specialized format requirements.
Direct sales capture the largest volume commitments; online retail is expanding most quickly for prototype-to-production workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Centralized retail procurement in Germany absorbs disproportionate volume, while Nordic fiber supply clusters and Asian certification barriers reshape competitive access across major economies.
Germany
Aldi, Lidl, and REWE Group enforce uniform sustainable packaging standards across national store networks. The EU Packaging and Packaging Waste Regulation accelerates expanded polystyrene phase-out timelines. The Rhine-Ruhr industrial corridor hosts dedicated pulp molding capacity investments serving centralized meat and poultry distribution.
Netherlands
Dutch poultry processors and produce distributors specify heat sealable fiber trays for modified atmosphere shelf-ready applications. EFSA migration limits govern barrier coating chemistries in direct food contact. The Rotterdam-Antwerp port cluster facilitates Nordic pulp feedstock import for converter operations.
Denmark
S Group and Coop Denmark unify specifications across fresh meat and prepared meal categories through centralized procurement. REACH authorization requirements eliminate fluorochemical barrier treatments by 2026. Copenhagen-based meal kit distributors drive multi-compartment tray qualification for sauce-protein-starch combinations.
India
BIS certification requirements and FSSAI food contact standards create compliant supply scarcity for early entrants. The country's national food safety regulator extends product qualification timelines for imported fiber formulations. Maharashtra and Gujarat industrial zones attract pulp board converter investments targeting domestic retail chain growth.
United States
FDA food contact substance notifications restrict acceptable barrier coating chemistries for protein and produce distribution. The Pacific Northwest and Southeast poultry processing belts specify heat sealable formats for retail-ready packaging. Midwest paper mill clusters supply food-grade recycled fiber to tray converters serving national protein processors.
Heat Sealable Pulp Board Tray Market Competitive Landscape
Capacity expansion dominates the current landscape as Nordic and North American manufacturers scale barrier coating capabilities to meet retailer sustainability mandates. The vendor base separates into integrated pulp-to-tray operators, specialized molded fiber converters, and diversified packaging conglomerates with fiber divisions. Tiered competitive positioning reflects R&D depth in oxygen barrier coatings and heat seal calibration precision. Strategic moves concentrate on backward integration into recycled pulp supply and geographic proximity to food processing clusters.
Among Nordic-based integrated operators, Huhtamaki Oyj and Brødrene Hartmann A/S exemplify the pulp-to-tray archetype with captive fiber supply and proximity to Baltic meat processing corridors. Mondi Group plc occupies a position within the diversified conglomerate tier, leveraging cross-divisional barrier coating expertise developed in flexible packaging applications. These three entities represent distinct strategic postures: geographic clustering for feedstock security, vertical integration for cost stability, and technology transfer from adjacent packaging segments.
| Leading Market Players |
|---|
| Evesham Specialist Packaging Ltd |
| Sappi Limited |
| Huhtamaki Oyj |
| Smurfit WestRock |
| Mondi Group plc |
| International Paper Company |
| Graphic Packaging Holding Company |
| Brødrene Hartmann A/S |
| Amcor plc |
| Others |
Value Network & Pricing Analysis
The EU Packaging and Packaging Waste Regulation gates qualified supply and premium-tier pricing access by mandating extended producer responsibility fee differentials that reward fiber-based formats. Retailers seeking EPR discounts specify certified sustainable grades, compressing margins for non-compliant converters while concentrating pricing power among integrated operators with chain-of-custody documentation.
Pricing Analysis
Volume placements anchor the commodity tier where per-unit transactional pricing dominates single-compartment meat trays for German discount chains. Three-tier pricing structure across premium, standard, and economy levels separates FSC-certified sustainable grades from recycled fiber and virgin kraft alternatives. Cost compression in the standard tier intensifies as Nordic pulp supply tightens and coating R&D costs escalate. Small regional converters exhibit highest price sensitivity due to feedstock vulnerability, while integrated operators with captive fiber supply maintain margin resilience.
Supply Chain Analysis
Domestic-content mandates in India and China are reshaping sourcing patterns as BIS certification and GB standards force local production partnerships for market access. Feedstock concentration centers on Sweden, Finland, and Estonia for food-grade recycled fiber, while barrier coating chemistries draw from German and Dutch specialty chemical clusters. Single-source vulnerability runs through Nordic pulp mill consolidation, where three integrated operators control majority food-grade supply. Distribution runs through direct manufacturer-to-retailer contracts audited for chain-of-custody compliance, displacing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into recycled pulp supply determines cost stability and EPR fee competitiveness. Players are pursuing upstream control over Nordic fiber clusters to secure feedstock access and qualify for premium-tier retailer contracts.
For Market Incumbents: Deepen barrier coating R&D capabilities to match polymer film oxygen barrier performance, or risk displacement by aluminum tray substitution in premium ready-meal segments. Acquire Nordic pulp mill capacity to eliminate feedstock margin volatility and qualify for French modulated EPR fee discounts. Consolidate multi-compartment tray production lines to capture medical kit applications where sterility requirements limit competition. For New Entrants and Emerging Players: Enter via BIS-certified production partnerships in Maharashtra and Gujarat to exploit compliant supply scarcity in India's domestic retail expansion. Target medical kit multi-compartment designs where sterile separation requirements and limited incumbent competition support premium positioning. Pursue direct sales channel qualification with Dutch meal kit distributors seeking sauce-protein-starch tray configurations. For Investors and Strategic Acquirers: REACH fluorochemical phase-out completion is the leading indicator that barrier coating chemistry leadership will consolidate among operators with qualified alternative formulations. Long-term viability across the analysis window favors integrated pulp-to-tray operators with geographic proximity to Baltic meat processing corridors. Acquisition target archetype: mid-tier converters with installed molding capacity but lacking coating R&D depth, where technology transfer from flexible packaging divisions unlocks shelf-ready meat applications. Watch EFSA migration limit updates as the signal for which coating technologies retain commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Pulp Supply | Captive Nordic fiber feedstock eliminates margin volatility from concentrated supplier base. |
| Barrier Coating R&D Partnership | Dutch poultry processor qualification accelerates oxygen barrier performance matching polymer films. |
| Direct Retail Contract Conversion | German buying cooperative audits displace distributor networks with national account uniformity. |
| Multi-Compartment Line Qualification | Copenhagen meal kit distributor specifications open sauce-protein-starch combination markets. |
| Chain-of-Custody Certification Investment | FSC and PEFC documentation unlocks REWE Group and S Group private label volume commitments. |
Research Methodology
Document review covered EU regulatory filings, FDA food contact substance notifications, and Nordic paper industry trade data, complemented by interviews with procurement directors at German retail chains, technical R&D leads at barrier coating suppliers, and plant managers at Baltic pulp molding facilities. Secondary validation drew from EFSA migration limit evaluations, BIS certification registries, and extended producer responsibility fee schedules across EU member states. Bottom-up tray volume estimates triangulated against top-down packaging consumption models.
Cross-referencing historical capacity expansion patterns with expert panel input on retailer phase-out timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type geometry, barrier performance tier, material certification grade, and distribution channel structure. CAGRs derived from fitted growth curves incorporating EPR implementation schedules and coating qualification timelines. Industry-specific inputs captured REACH fluorochemical substitution pace and centralized retail procurement consolidation rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated aluminum tray substitution or disrupted Nordic pulp supply. Forecasts reflect assumptions regarding regulatory enforcement consistency, coating migration limit stability, and retailer sustainability target adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Protective Paperboard Market
Paper & Paperboard Packaging
Paperboard Packaging Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Disposable Paper Plates Market
Paper & Paperboard Packaging
Tacky Transfer Paper Market
Paper & Paperboard Packaging
Corrugated Board Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Fast Food Wrapping Paper Market
Paper & Paperboard Packaging
Egypt Paper Packaging Market
Paper & Paperboard Packaging
Asia-Pacific Paper Cone Market
Paper & Paperboard Packaging
Schrenz Paper Market
Paper & Paperboard Packaging
United Kingdom (UK) Corrugated Board Packaging Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market