
 Disposable Paper Cups Market | 2026-2036
Disposable Paper Cups Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Paper Cups Market Analysis
Water-based barrier coatings is rewriting the manufacturing economics of disposable paper cups by eliminating the need for conventional polyethylene liners while maintaining liquid resistance. Georgia-Pacific LLC leverages its integrated pulp-to-cup supply chain to control raw material costs across North American production lines. Huhtamaki Oyj anchors its competitive position through specialized molded fiber technology for hot beverage applications in European foodservice channels.
Disposable paper cups are single-use vessels manufactured from wood pulp fiberboard, typically weighing 200-350 gsm, with interior barrier layers applied via extrusion or dispersion coating to prevent liquid saturation and structural failure. Their primary commercial purpose is to serve hot and cold beverages in away-from-home consumption settings where washing reusable alternatives proves operationally impractical. Hot cups and PLA-coated variants command premium positioning as coffee chains pursue plastic-reduction commitments, while cold cups face margin compression from competing bioplastic formats. The 12 oz and 16 oz size bands concentrate volume in quick-service coffee applications, whereas catering services and institutional buyers increasingly specify biodegradable cups to satisfy procurement sustainability criteria.
The FDA regulates food-contact substances in the United States, requiring migration testing for all barrier coatings, while the EU Green Deal and F-Gas Regulation indirectly pressure manufacturers toward fluorine-free and low-carbon production pathways. BIS certification in India and GB standards in China impose additional compositional and performance requirements for export-oriented suppliers. Stakeholders must monitor how fragmented national compostability standards reshape product design specifications and determine which coating technologies qualify for preferred vendor status in regulated procurement frameworks.
Market Dynamics
The EU Single-Use Plastics Directive is forcing a wholesale coating technology transition across European foodservice supply chains, while water-based barrier chemistry is compressing manufacturing costs for compliant cup formats.
Growth Catalysts
- Quick-service restaurant expansion:Coffee chains and convenience stores across the United States are scaling on-the-go beverage programs, concentrating procurement volume in 12 oz and 16 oz single-use formats.
- Compostability mandates:The EU Green Deal and national compostability standards in France, Italy, and Germany are accelerating PLA-coated and uncoated fiber cup adoption in institutional catering channels.
- Water-based barrier coatings:This dispersion technology eliminates polyethylene liner requirements while maintaining liquid resistance, reducing material costs and qualifying cups for preferred vendor status in regulated procurement frameworks.
Market Restraints
- Pulp fiber cost volatility:Wood pulp prices fluctuate with energy and logistics inputs, squeezing margins for non-integrated manufacturers lacking captive pulp supply.
- Competing bioplastic formats:Polylactic acid cups and bagasse alternatives are capturing cold beverage applications where paperboard faces structural performance limitations.
- Fragmented compostability standards:Divergent national certification requirements across EU member states, the United Kingdom, and North American jurisdictions complicate product design standardization and inventory management.
Strategic Opportunities
- Indian institutional catering:BIS certification requirements and food safety regulations are creating preferred supplier status for compliant fiber cup manufacturers serving quick-service chains and railway catering services.
- Fluorine-free barrier chemistry:The EU F-Gas Regulation and state-level restrictions in California and Washington are opening market share for per- and polyfluoroalkyl substance-free coating innovators.
- Direct-to-chain distribution:Bypassing traditional foodservice distributors to contract directly with coffee chain procurement teams allows customization of cup specifications and volume pricing structures.
Industry Challenges
- Migration testing timelines:FDA food-contact substance approvals and EU EFSA evaluations for novel barrier coatings extend product commercialization cycles by 18-36 months.
- Coating equipment retrofitting:Shifting from extrusion to dispersion coating lines requires capital expenditure on slot-die applicators and infrared drying systems at existing paperboard mills.
- Composting infrastructure gaps:Industrial composting facility availability varies dramatically between metropolitan and rural areas, limiting the practical end-of-life value proposition for certified biodegradable cups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Paper Cups Market |
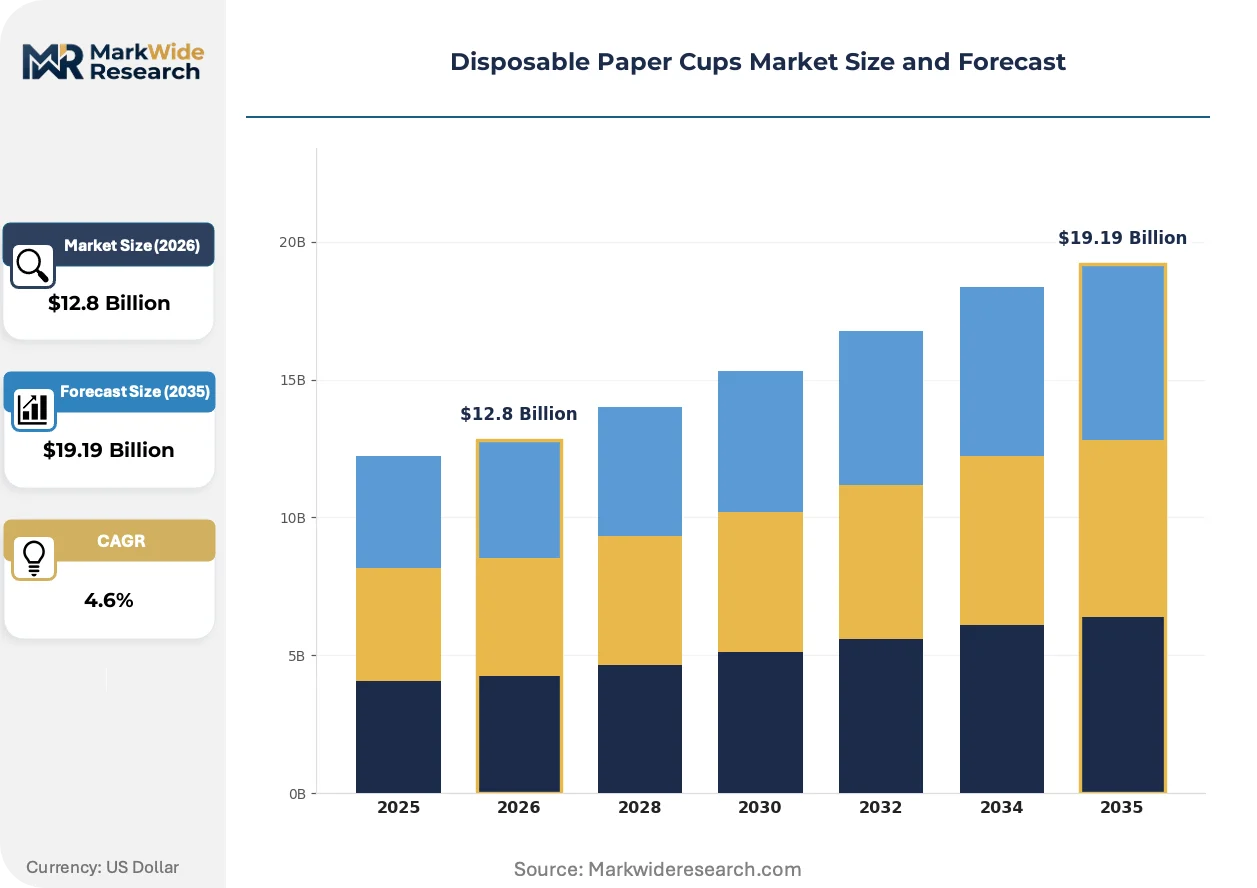
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hot Cups, Cold Cups, Biodegradable Cups, Insulated Cups Coating Type: Polyethylene Coated, PLA Coated, Wax Coated, Uncoated Size: 8 oz, 12 oz, 16 oz, 20 oz End User: Coffee Shops, Restaurants, Catering Services, Retail Chains |
| Companies Covered | Georgia-Pacific LLC, Pactiv Evergreen Inc., International Paper Company, Graphic Packaging International, SEDA International Packaging Group, Dart Container Corporation, Mondi Group, Stora Enso Oyj, Huhtamaki Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Paper Cups Market Emerging Trajectories
Barrier coating chemistry is the dominant axis of product differentiation, with dispersion technologies and bio-based polymers competing to displace conventional polyethylene while satisfying divergent regulatory frameworks.
Water-based acrylic and styrene-acrylic dispersion coatings are rendering obsolete the extrusion lamination lines that have dominated cup manufacturing for three decades. Major coffee chains in the United States and Germany are specifying these fluorine-free alternatives in procurement contracts to meet plastic-reduction commitments. The technology is compressing capital requirements for new market entrants while disqualifying legacy equipment-dependent manufacturers from premium contract bidding.
The EU F-Gas Regulation and national restrictions on per- and polyfluoroalkyl substances are prohibiting oil-and-grease-resistant fluorochemical coatings in food-contact applications. This regulatory pressure is redirecting R&D investment toward bio-wax and polysaccharide barrier formulations. Hot beverage cup segments in France, Italy, and the Nordic countries are experiencing the most acute formulation switching as existing inventory cycles out of compliance.
Corporate sustainability officers at institutional buyers are inserting compostability certification requirements into vendor scorecards, displacing price-only procurement evaluation. Quick-service chains and university foodservice operators are consolidating supplier relationships around dual-certified fiber cup providers. This pattern is most pronounced in California, Washington state, and the Netherlands where extended producer responsibility frameworks impose downstream waste management accountability on cup purchasers.
Disposable Paper Cups Market Segmentation
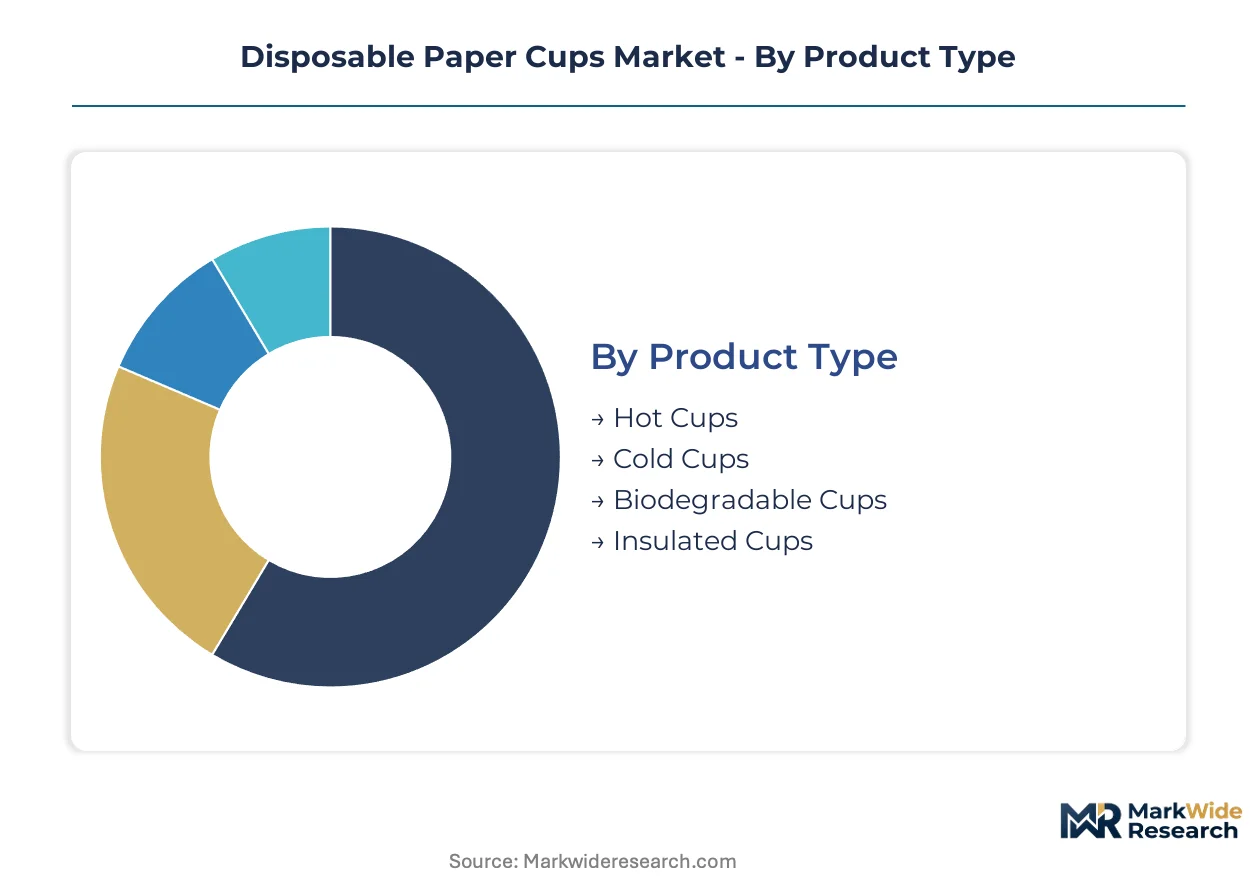
Product differentiation in disposable paper cups revolves around thermal performance requirements and regulatory compliance tiers. Segmentation strategy determines which coating technologies and size formats capture procurement contracts from quick-service chains versus institutional buyers.
Product Type:
Inventory velocity varies sharply across formats, with cold cups turning fastest in convenience channels while insulated cups sit longest in distributor warehouses awaiting premium coffee chain orders.
- Hot Cups:Double-walled construction with air-gap insulation maintains beverage temperatures above 60°C for 15-20 minutes. United States coffee chains specify these for espresso-based drinks, driving procurement concentration in 12 oz and 16 oz formats where premium pricing offsets fiberboard costs.
- Biodegradable Cups:PLA-lined or uncoated fiberboard vessels certified to EN 13432 or ASTM D6400 standards. French and Italian institutional catering channels mandate these for public sector contracts, creating preferred supplier status for certified manufacturers.
- Cold Cups:Single-ply bleached board with polyethylene or dispersion coating for iced beverages. Convenience store fountain drink programs in the United States rotate these rapidly through high-volume, low-margin procurement.
- Insulated Cups:Triple-layer construction with embossed outer walls for enhanced grip and thermal protection. Premium positioning in specialty coffee channels commands higher unit economics despite slower inventory turns.
Hot cups dominate installed base. Biodegradable cups are where expansion concentrates.
Coating Type:
Material cost tiers separate commodity producers from compliance-positioned suppliers, with dispersion-coated variants capturing margin premiums in regulated European markets.
- Polyethylene Coated:Extruded PE liners at 15-30 gsm provide liquid resistance across hot and cold applications. Legacy production lines in Asia-Pacific and North American mills still output these for price-sensitive foodservice distributors.
- PLA Coated:Polylactic acid derived from corn starch or sugarcane offers compostable end-of-life pathways. German and Dutch quick-service chains specify these to satisfy extended producer responsibility frameworks.
- Wax Coated:Paraffin or vegetable-based wax barriers for cold beverage applications. Limited to niche catering segments where refrigeration infrastructure supports slower biodegradation timelines.
- Uncoated:Virgin or recycled fiberboard without barrier treatment, suitable for dry goods or double-cupping configurations. Lowest material cost positions these for budget institutional procurement.
Polyethylene coated holds volume leadership. PLA coated is climbing the fastest.
Size:
Procurement scale concentrates in mid-range formats where beverage margin economics align with operational throughput.
- 12 oz:Standard espresso drink capacity with optimized fiberboard-to-liquid ratio. United States specialty coffee chains specify this as their default single-serve format.
- 16 oz:Grande-equivalent volume capturing cold brew and blended beverage applications. Quick-service restaurant value meal bundling drives consistent demand.
- 8 oz:Demi-size for cortado and macchiato service. Premium positioning in European café culture limits volume scale.
- 20 oz:Venti-equivalent for fountain soda and iced tea programs. Convenience store channels absorb volume despite higher per-unit material costs.
12 oz dominates installed base. 16 oz is gaining share fastest.
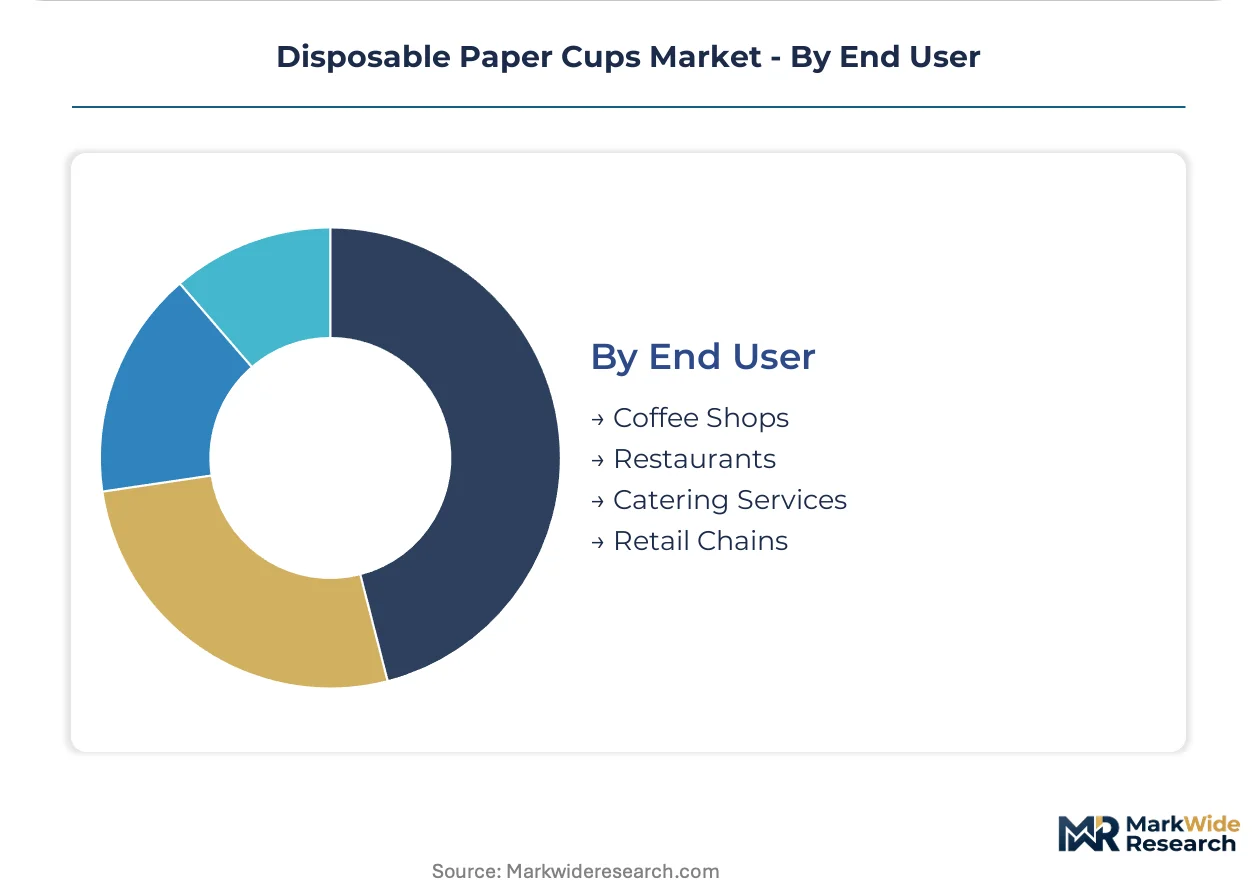
End User:
Customer type determines specification complexity, with direct chain contracts demanding customization that distributor-served segments cannot justify.
- Coffee Shops:Branded cup programs requiring consistent color matching and seasonal design flexibility. United States and German chains source through direct manufacturer relationships.
- Catering Services:Event-based procurement with biodegradable certification requirements. French and Italian public tenders mandate compostable formats.
- Restaurants:Full-service and quick-service operators balancing cost control with brand presentation. Mid-tier positioning favors standard hot cup formats.
- Retail Chains:Grocery and convenience store private-label programs. Volume pricing structures prioritize polyethylene-coated cold cups.
Coffee shops dominate installed base. Catering services are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Quick-service restaurant chains and institutional buyers concentrate procurement in markets with stringent single-use plastic regulations and established coffee culture. Major coffee chains in the United States, Germany, and France drive specification standards that cascade through global supply chains.
United States
Specialty coffee chains and convenience stores dominate procurement volume, with 12 oz and 16 oz formats absorbing the majority of shipments. FDA food-contact substance regulations govern barrier coating approvals, extending commercialization timelines for novel chemistries. Georgia-Pacific operates integrated pulp-to-cup production lines across the Southeast, controlling raw material costs for quick-service distributor contracts.
Germany
Extended producer responsibility frameworks and the EU Single-Use Plastics Directive accelerate PLA-coated and uncoated fiber cup adoption in institutional catering. The national packaging ordinance mandates deposit-return systems for beverage containers, pressuring single-use alternatives toward certified compostable formats. Berlin and Hamburg foodservice clusters specify EN 13432-certified cups for municipal procurement contracts.
France
Public sector catering tenders mandate biodegradable cup formats under national anti-waste legislation, creating preferred supplier status for certified manufacturers. The French Agency for Food, Environmental and Occupational Health & Safety enforces strict migration limits on food-contact substances. Lyon and Marseille quick-service chains consolidate procurement around dual-certified fiber cup providers to satisfy corporate sustainability scorecards.
India
Railway catering services and quick-service chains drive institutional demand for BIS-certified fiber cups compliant with food safety regulations. The Bureau of Indian Standards imposes compositional and performance requirements that filter export-oriented suppliers from domestic market access. Maharashtra and Gujarat manufacturing clusters supply fiberboard substrates to converters serving Mumbai and Delhi-NCR foodservice channels.
China
GB standards for food-contact paper and board shape export-oriented production specifications, with dual carbon goals pressuring manufacturers toward low-carbon coating technologies. Yangtze River Delta converters supply cold cup formats to North American and European distributors. Shanghai and Zhejiang industrial zones concentrate extrusion and dispersion coating capacity for international quick-service chain contracts.
Disposable Paper Cups Market Vendor Landscape
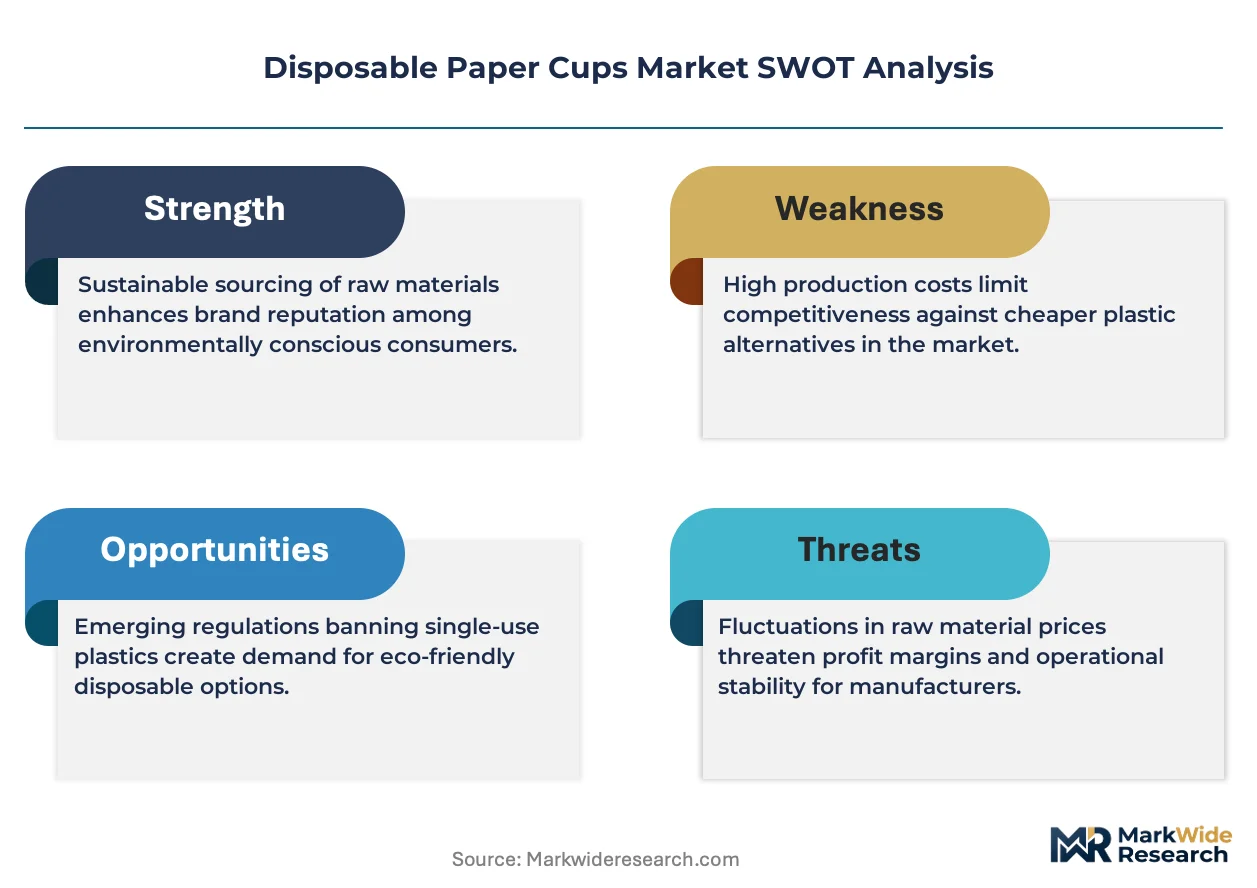
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure consolidates around integrated pulp producers with captive fiber supply and specialized converters with coating technology differentiation. Three archetypes dominate: backward-integrated forest products conglomerates, European molded fiber specialists, and Asian contract manufacturers with scale-driven cost positions. Competitive moves center on direct-to-chain distribution bypassing traditional foodservice distributors and coating equipment retrofitting to qualify for regulated procurement frameworks.
Among North American forest products conglomerates, Georgia-Pacific LLC and International Paper Company exemplify the backward-integrated archetype with captive pulp supply chains. European molded fiber positioning is represented by Huhtamaki Oyj, which anchors specialized technology for hot beverage applications. These three companies occupy distinct competitive territories based on geographic production footprint and coating chemistry capabilities, with each representing a strategic response to regulatory fragmentation across FDA, EFSA, and BIS jurisdictions.
| Leading Market Players |
|---|
| Georgia-Pacific LLC |
| Pactiv Evergreen Inc. |
| International Paper Company |
| Graphic Packaging International |
| SEDA International Packaging Group |
| Dart Container Corporation |
| Mondi Group |
| Stora Enso Oyj |
| Huhtamaki Oyj |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese dispersion coating lines is compressing global export pricing while forcing European mills to accelerate equipment retrofitting or exit commodity segments entirely. This utilization asymmetry between Asian contract manufacturers and integrated North American pulp producers is reshaping procurement leverage across quick-service chain negotiations.
Pricing Analysis
Cost-plus contracts with NBSK pulp indexation dominate long-term agreements between integrated producers and United States coffee chains, insulating margin structures from spot fiber volatility. Three-tier pricing structure across premium, standard, and economy levels separates PLA-certified biodegradable cups from polyethylene-coated commodity formats and uncoated institutional grades. Cost compression in cold cup segments is intensifying because bagasse and polylactic acid alternatives are capturing fountain beverage applications. Retail chain procurement teams exhibit the highest price sensitivity, while German municipal catering contracts prioritize certification compliance over unit cost.
Supply Chain Analysis
Export-control regimes on fluorochemical barrier precursors under the EU F-Gas Regulation are constraining coating chemistry flows to Asian contract manufacturers, forcing formulation sourcing shifts toward domestic European suppliers. Geographic supply concentration centers on China for dispersion coating equipment, the United States for virgin pulp fiber, and Germany for PLA resin compounding. Raw material dependencies rest on wood pulp pricing, corn starch feedstocks for biopolymer liners, and acrylic dispersion polymers. Single-source vulnerability in slot-die applicator manufacturing creates equipment procurement bottlenecks. Distribution runs through foodservice distributors for mid-tier institutional buyers and direct manufacturer relationships for major coffee chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment story where FDA and EFSA food-contact approvals create 18-36 month switching costs that protect compliant incumbents from rapid private-label displacement.
For Market Incumbents: Pre-empt coating technology obsolescence by retrofitting extrusion lines to dispersion capability before EU Single-Use Plastics Directive enforcement hardens procurement specifications against polyethylene-lined inventory. Secure captive pulp supply through backward integration into Southeastern United States timberlands or long-term fiber offtake agreements with Brazilian eucalyptus plantations. Water-based barrier patent filings by Asian equipment suppliers represent the most acute emerging threat to European molded fiber positioning. For New Entrants and Emerging Players: Build out fluorine-free barrier chemistry capabilities to capture share in California and Washington state markets where per- and polyfluoroalkyl substance restrictions are advancing ahead of federal timelines. Target Indian railway catering and quick-service chain segments where BIS certification requirements filter out unqualified export competitors. Lead with direct-to-chain distribution models that bypass legacy foodservice distributor markups and enable custom specification development with procurement teams. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across dispersion coating technology as slot-die applicator costs decline and infrared drying systems achieve energy efficiency improvements. Acquisition targets should prioritize European converters with EN 13432 certification infrastructure and established relationships with French and Italian institutional catering channels. Monitor PLA resin price spreads against petroleum-based polyethylene as the critical inflection signal for biodegradable cup margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Georgia-Pacific's captive timberland access insulates margin structures from NBSK spot volatility. |
| Coating Equipment Retrofitting | Slot-die applicator installation qualifies legacy mills for EU Single-Use Plastics Directive procurement. |
| Fluorine-Free Barrier Certification | California SB 1044 compliance opens preferred vendor status with state university foodservice systems. |
| Direct-to-Chain Distribution | Bypassing foodservice distributors enables volume pricing structures with major United States coffee chains. |
| Dual Certification Investment | EN 13432 and ASTM D6400 certification consolidates supplier relationships with Dutch extended producer responsibility frameworks. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with coating technology directors, quick-service procurement leads, and foodservice distributor category managers; and secondary validation through FDA food-contact substance filings, EU EFSA scientific opinions, BIS certification registries, and trade flow data from pulp and paper industry associations. Bottom-up triangulation across manufacturer shipment data and top-down reconciliation against end-user procurement volumes anchored market size estimates.
Forecast inputs considered coating technology transition timelines, regulatory enforcement schedules across FDA, EFSA, and BIS jurisdictions, and quick-service chain plastic-reduction commitment disclosures. Segmentation dimensions modeled include product type, coating chemistry, size format, and end-user channel across the analysis window. CAGRs were derived from regression analysis of historical volume data against explanatory variables including pulp pricing indices, coffee chain outlet expansion rates, and composting infrastructure development.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian dispersion coating equipment manufacturers to bypass European patent positions would shift outcomes. Material shifts in EU member state compostability standard harmonization or abrupt FDA barrier coating approval timeline acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Dunnage Paper Bags Market
Paper & Paperboard Packaging
Retail Paper Bags Market
Paper & Paperboard Packaging
GCC Paper Bags Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Morocco Corrugated Board Market
Paper & Paperboard Packaging
Converting Paper Market
Paper & Paperboard Packaging
Corrugated Boxes Market
Paper & Paperboard Packaging
Paper Carrier Bags Market
Paper & Paperboard Packaging
Global Fanfold Corrugated Market
Paper & Paperboard Packaging
Heat Sealable Pulp Board Tray Market
Paper & Paperboard Packaging
United Kingdom Corrugated Packaging Market
Paper & Paperboard Packaging
Stationery Films Packaging Market
Paper & Paperboard Packaging
Postal Tubes Market
Paper & Paperboard Packaging
Wall Mounted Paper Napkin Dispensers Market
Paper & Paperboard Packaging
Clear Envelopes and Mailing Supplies Market