
 Pre-Fabricated Glass Block Market | 2026-2036
Pre-Fabricated Glass Block Market Size, Share, and Industry Trends Forecast 2026-2036
Pre-Fabricated Glass Block Market Analysis
Commercial facade installations are rebalancing toward high-performance building envelopes as architects specify prefabricated glass block for daylighting and thermal control. Seves Glassblock leverages vertical integration across European manufacturing to sustain consistent output for institutional projects. J. E. Berkowitz anchors North American supply through specialized fabrication capabilities for custom dimensions. Nippon Electric Glass competes on advanced coating technologies that improve solar heat gain coefficients in exterior applications.
Pre-fabricated glass block consists of hollow or solid glass units, typically 80-100mm thick, formed through pressed or cast manufacturing and assembled into modular panels for structural or non-structural applications. These units deliver light transmission, thermal insulation, and acoustic dampening in commercial and residential envelopes. Clear blocks dominate volume shipments for standard interior partitions, while textured and frosted variants command premium positioning in architectural facade systems where privacy and diffuse daylighting converge. Laminated finishing types are gaining specification share in hurricane-prone coastal zones where impact resistance codes have tightened.
ASTM C1499 governs structural performance testing in the United States, while the EU Construction Products Regulation mandates CE marking for glass block used in load-bearing exterior walls. Germany's KBA and federal building codes enforce stringent U-value thresholds that favor insulated glass block over single-pane alternatives. China's GB standards and MIIT directives shape domestic product certification for both local consumption and export qualification. Stakeholders must monitor evolving energy performance benchmarks across these jurisdictions to align R&D pipelines with code-compliant product configurations.
Market Dynamics
Building envelope energy codes across Germany, the United States, and Japan are compressing specification windows for glazing assemblies, forcing manufacturers to prioritize thermal performance over legacy aesthetics in product development pipelines.
Growth Catalysts
- Stringent U-value mandates:Germany's KBA and federal building codes enforce thermal thresholds that favor insulated glass block over single-pane alternatives in exterior wall applications.
- Urban redevelopment concentration:China's municipal authorities specify prefabricated glass block for interior partitions and exterior cladding in large-scale renovation projects.
- Impact resistance requirements:Laminated finishing types gain specification share in hurricane-prone coastal zones where building codes have tightened for structural glazing.
Market Restraints
- Raw material cost volatility:Soda ash and silica sand price fluctuations compress margin structures for pressed and cast manufacturing processes.
- Supply concentration risk:European manufacturing clusters dominate high-performance insulated glass block output, creating geographic vulnerability for North American project timelines.
- Technical thickness limitations:Standard 80-100mm units face specification ceilings in deep-wall assemblies requiring higher load-bearing capacity.
Strategic Opportunities
- Underpenetrated seismic zones:Japan's commercial construction sector offers expansion potential for laminated glass block systems meeting JIS structural standards.
- Daylighting mandates:The EU Green Deal's building renovation wave creates regulatory tailwind for diffuse light transmission products in institutional retrofits.
- Modular construction convergence:Prefabricated panel systems integrating glass block with steel framing capture share from conventional curtain wall installation.
Industry Challenges
- Certification timeline compression:CE marking requirements under EU Construction Products Regulation extend product validation cycles for load-bearing exterior wall applications.
- Specialized fabrication capacity:Custom dimension production demands capital-intensive tooling investments that strain mid-scale manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pre-Fabricated Glass Block Market |
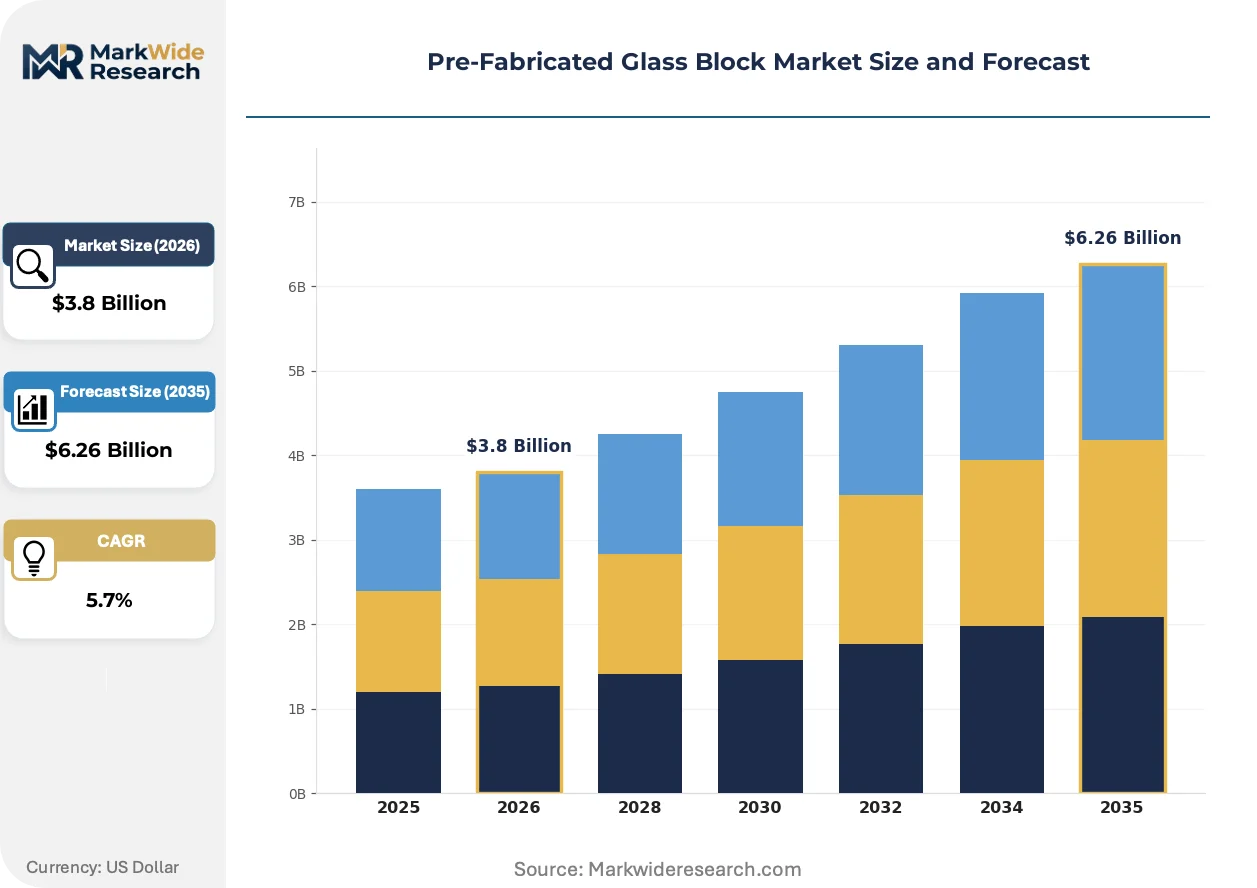
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Blocks, Frosted Blocks, Tinted Blocks, Textured Blocks Installation Type: Interior, Exterior, Facade, Partition End User: Residential, Commercial, Industrial, Institutional Finishing Type: Polished, Sealed, Painted, Laminated |
| Companies Covered | Vetroarredo, J. E. Berkowitz, Seves Glassblock, Nippon Electric Glass, Glass Blocks Unlimited, Pittsburgh Corning, Bormioli Rocco, Shandong Demax Group, Mulia Industrindo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pre-Fabricated Glass Block Market Emerging Trajectories
Performance-driven specification is compressing the gap between structural and aesthetic functions in glazing assemblies. Three converging developments are redefining competitive positioning.
Vacuum-insulated glass block technology is integrating silica aerogel cores to achieve U-values below 0.5 W/m²K. Institutional buyers in Germany and Scandinavia are specifying these units for net-zero envelope targets. The technology is integrating thermal performance benchmarks previously reserved for triple-pane fenestration into monolithic block assemblies.
ASTM C1499 testing protocols in the United States are expanding to include cyclic loading simulations for seismic applications. This regulatory expansion forces manufacturers to revalidate existing product lines for high-risk zones. California and Pacific Northwest projects now require supplemental structural calculations that extend pre-bid engineering timelines.
Architects are bundling acoustic dampening specifications with daylighting requirements in healthcare and education verticals. This dual-criteria selection compresses the vendor pool to suppliers offering certified STC ratings alongside light transmission data. The behavior shift is most visible in German hospital new-builds and US university science facilities.
Pre-Fabricated Glass Block Market Segmentation
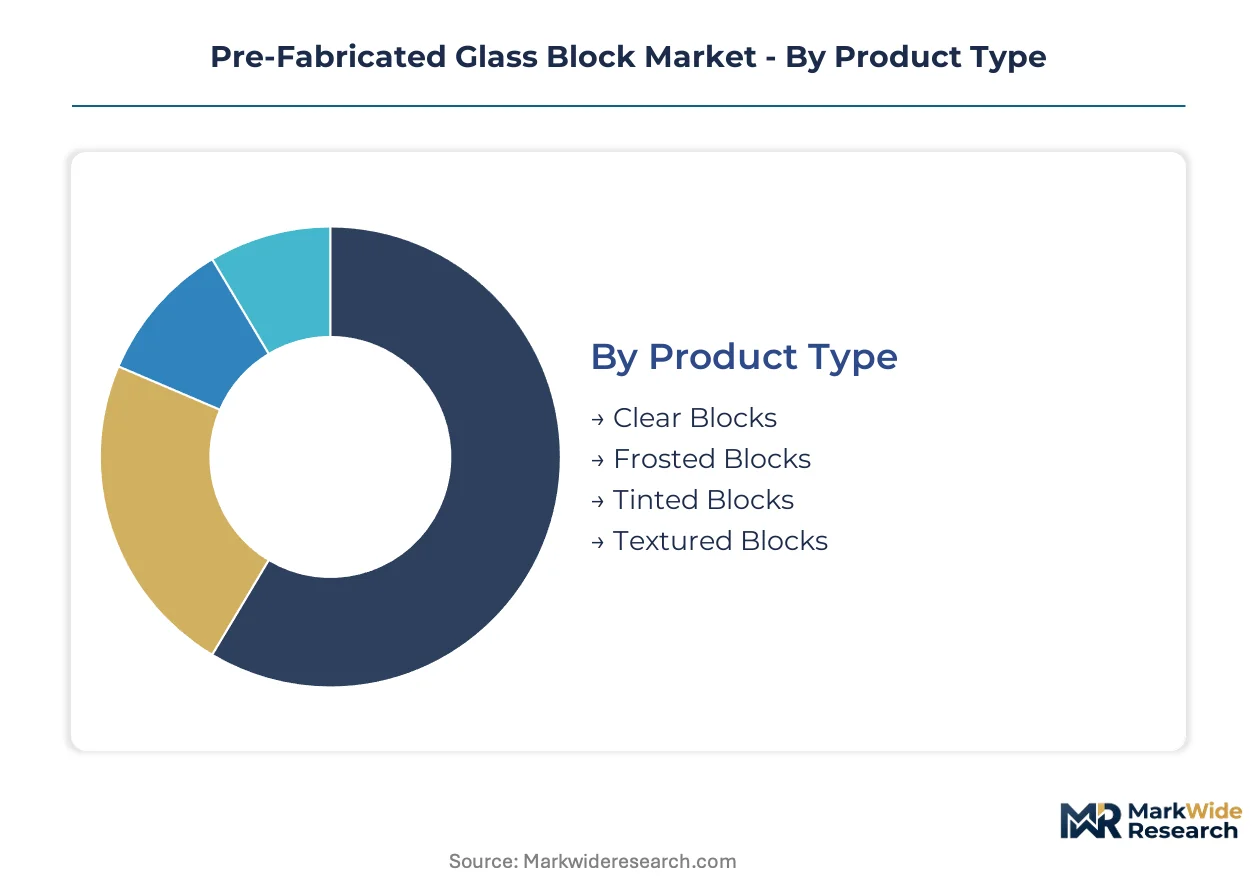
Pre-fabricated glass block markets fragment across optical performance, structural application, and surface treatment specifications. Each segmentation axis carries distinct certification requirements and margin structures that shape manufacturer portfolio priorities.
Product Type:
Optical transmission characteristics and surface diffusion properties define specification hierarchies across architectural glazing projects.
- Clear Blocks:Standard soda-lime silica composition delivers maximum visible light transmission for interior daylighting corridors. Volume concentrates in Chinese urban redevelopment projects where municipal codes mandate minimum daylight factors in residential tower retrofits.
- Frosted Blocks:Acid-etched or sandblasted surfaces scatter incident light to eliminate glare while maintaining privacy. German hospital new-builds and US university science facilities specify these units for dual-criteria acoustic and daylighting performance.
- Tinted Blocks:Iron oxide or metal salt additives reduce solar heat gain coefficients for southern exposure facades.
- Textured Blocks:Patterned surfaces refract light directionally for decorative architectural effects in commercial lobbies.
Mature deployment sits with clear blocks in standard partition applications. Newer deployment is concentrated in frosted variants meeting healthcare and education sector dual-performance specifications.
Installation Type:
Load-bearing requirements and weather exposure levels determine structural engineering validation and installation cost structures.
- Interior:Non-structural partition walls in commercial and residential spaces dominate shipment volumes.
- Exterior:Load-bearing wall assemblies require CE marking under EU Construction Products Regulation and ASTM C1499 compliance in the United States.
- Facade:Curtain wall integration demands thermal break engineering and pressure-equalized rainscreen detailing for high-performance building envelopes.
- Partition:Modular room-dividing systems in open-plan offices and healthcare facilities specify quick-install panel configurations.
Facade installation commands premium engineering margins. Partition systems are climbing fastest as modular construction methods gain specification share.
End User:
Project scale and procurement authority concentration vary sharply across buyer categories.
- Residential:Single-family and multi-family housing specify glass block for bathrooms, basements, and accent walls.
- Commercial:Office towers, retail centers, and hospitality projects drive demand for high-transmission facade systems.
- Industrial:Manufacturing facilities and warehouses prioritize security and natural illumination in perimeter walls.
- Institutional:Government buildings, schools, and hospitals mandate certified acoustic and thermal performance in public procurement.
Commercial buyers concentrate volume in facade applications. Institutional procurement is expanding most quickly under EU Green Deal renovation mandates.
Finishing Type:
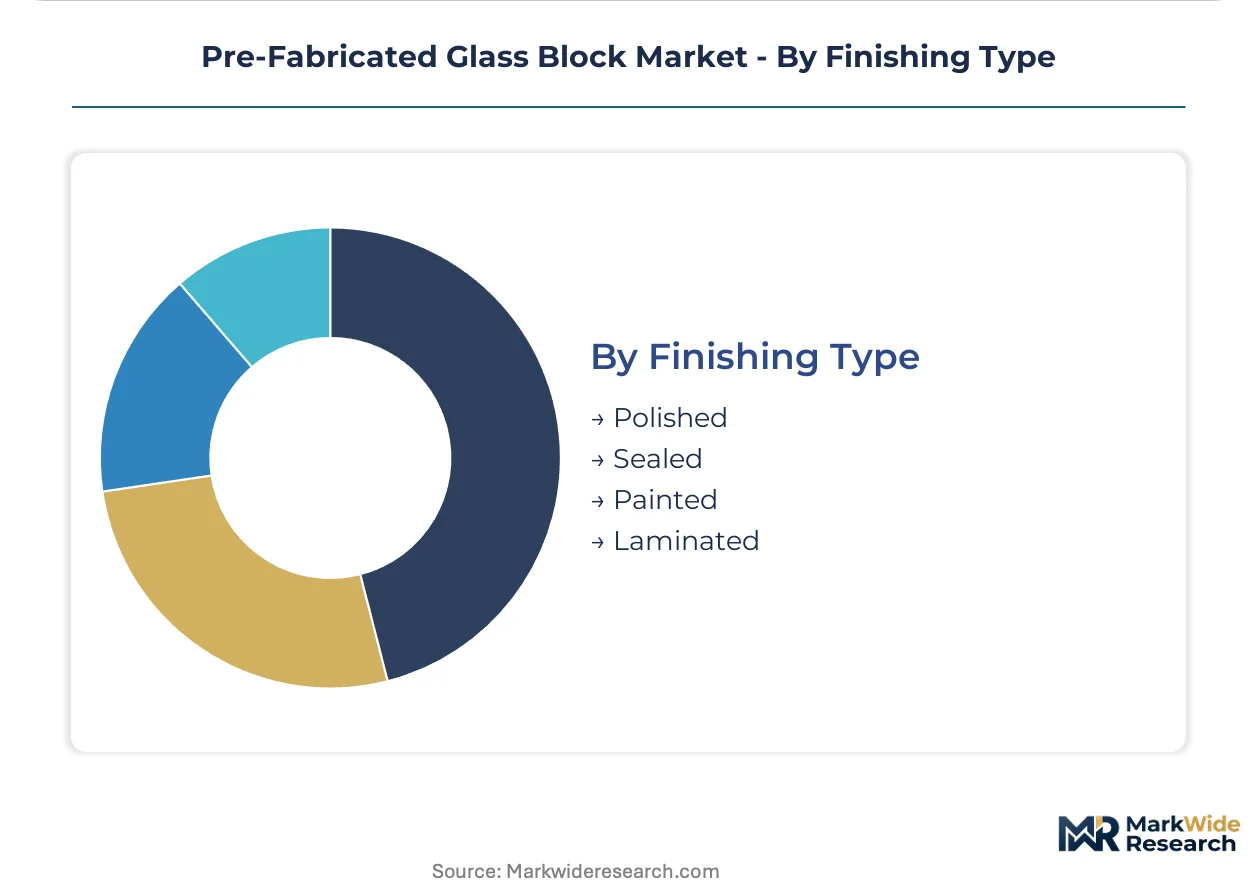
Surface treatments determine durability, maintenance cycles, and code compliance in specialized environments.
- Polished:Fire-polished surfaces maximize light transmission for standard interior applications.
- Sealed:Protective coatings extend service life in high-humidity environments such as pools and spas.
- Painted:Custom color matching serves branded commercial interiors and wayfinding applications.
- Laminated:Polyvinyl butyral interlayers provide impact resistance for hurricane-prone coastal zones and seismic requirements.
Polished finishes dominate standard interior specifications. Laminated treatments are gaining share fastest under tightened impact resistance codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European manufacturing clusters supply high-performance insulated units while Chinese urban redevelopment drives consumption growth. Germany anchors production capacity for thermal-efficient assemblies. Regulatory fragmentation across jurisdictions shapes regional competitive positioning.
Germany
KBA thermal mandates and federal building codes enforce U-value thresholds below single-pane alternatives. The country's national construction regulator mandates CE marking for load-bearing exterior wall applications. Manufacturing concentrates in Bavaria and North Rhine-Westphalia where Seves Glassblock maintains integrated production for institutional export markets.
United States
ASTM C1499 compliance requirements expand to cyclic loading simulations for seismic zones. The EPA and federal building standards tighten energy performance benchmarks for commercial envelopes. Fabrication clusters in the Northeast and Midwest serve hurricane-prone coastal demand for laminated finishing types.
China
Municipal urban redevelopment projects specify prefabricated glass block for residential tower retrofits and daylighting corridors. MIIT directives and GB standards shape domestic certification for both local consumption and export qualification. Production gravity sits in Shandong and the Yangtze River Delta where state-backed developers source for large-scale renovation programs.
Japan
Commercial construction in seismic zones creates specification demand for laminated systems meeting JIS structural standards. METI building efficiency programs incentivize high-performance envelope retrofits in institutional facilities. Tokyo and Osaka metropolitan authorities specify certified acoustic and thermal performance in public procurement.
Pre-Fabricated Glass Block Market Vendor Landscape
Top-tier vendors anchor European manufacturing capacity, while mid-scale fabricators compete on custom dimension capabilities. The vendor base stratifies across integrated manufacturers with captive raw material supply and specialized processors serving regional project timelines. Two strategic archetypes dominate: vertically integrated European producers controlling pressed and cast manufacturing, and North American fabricators leveraging specialized tooling for architectural specifications. Competitive moves concentrate on capacity rationalization in high-cost jurisdictions and technology licensing for vacuum-insulated product lines.
Among European-integrated manufacturers, Seves Glassblock and Bormioli Rocco exemplify the backward-integrated archetype with in-house silica processing and pressed manufacturing. J. E. Berkowitz occupies a position within the North American specialist tier, representing fabricators that anchor regional supply through custom dimension production. Nippon Electric Glass sits within the technology-driven segment, exemplifying competitors that differentiate through advanced coating capabilities for solar heat gain control.
| Leading Market Players |
|---|
| Vetroarredo |
| J. E. Berkowitz |
| Seves Glassblock |
| Nippon Electric Glass |
| Glass Blocks Unlimited |
| Pittsburgh Corning |
| Bormioli Rocco |
| Shandong Demax Group |
| Mulia Industrindo |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-caps in Italian and German manufacturing clusters anchor supply discipline through generational capital allocation, insulating pricing from short-term raw material swings while constraining capacity expansion that might erode margin structures. This ownership pattern concentrates pricing power with established European producers serving institutional procurement channels.
Pricing Analysis
Margin tightening in standard clear blocks reflects soda ash cost volatility and silica sand freight surcharges compressing pressed manufacturing economics. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-insulated units with silica aerogel cores from conventional hollow blocks and commodity-grade interior partitions. Price differentiation hinges on CE marking tier for load-bearing applications and thermal performance certification grade. Municipal buyers in Chinese urban redevelopment programs exhibit highest price sensitivity, while German hospital procurement committees prioritize certified acoustic ratings over unit cost.
Supply Chain Analysis
CE marking requirements and ASTM C1499 compliance timelines gate supply access for exterior wall applications, extending validation cycles that deter speculative capacity additions. Manufacturing concentrates in Germany, Italy, and China, with Bavarian and North Rhine-Westphalian clusters feeding European institutional demand and Shandong Province serving domestic Chinese renovation programs. Raw material sourcing draws from Ukrainian soda ash, Brazilian silica sand, and domestic cullet recycling streams. Single-source vulnerability sits with European gas-fired furnace operations exposed to energy price volatility. Distribution runs through specialized glazing distributors and direct specification sales to architectural firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics favor incumbents controlling captive furnace capacity, as technical thickness limitations and certification bottlenecks prevent rapid competitor scale-up. This capacity scarcity props pricing discipline across high-performance building envelope segments.
For Market Incumbents: Anchor regional supply relationships through long-term offtake agreements with municipal procurement authorities in China's urban redevelopment corridors. Defend against laminated glass block substitutes by accelerating vacuum-insulated product line certification under Germany's KBA thermal mandates. Prioritize backward integration into silica sand processing to secure margin against raw material volatility.
For New Entrants and Emerging Players: Seismic-rated laminated systems meeting JIS standards offer technology-first entry into Japan's underpenetrated commercial construction sector. White-space concentration sits with modular panel configurations integrating glass block with steel framing for quick-install healthcare and education partitions. Target specification architects in Pacific Northwest seismic zones through engineering-led sales support.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale fabricators with custom dimension tooling in North American Northeast and Midwest clusters. Long-term viability centers on acquisition of CE-marking capabilities and captive furnace assets rather than trading-oriented distributors. Watch laminated finishing type specification share in Florida and Gulf Coast building codes as inflection signal for impact-resistant product cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Insulated Product Line Expansion | Captures German net-zero envelope procurement under KBA thermal mandates. |
| Seismic Certification Investment | Unlocks Japanese commercial construction specifying JIS structural standards. |
| Modular Panel System Development | Integrates glass block with steel framing for EU Green Deal institutional retrofits. |
| Laminated Finishing Capacity Addition | Serves hurricane-prone coastal zones with tightened impact resistance codes. |
| Custom Dimension Fabrication Scale-Up | Addresses architectural specification demand for non-standard block geometries. |
Methodological Framework
Document review covered customs and trade databases, SEC and European company filings, and national building code repositories, complemented by interviews with plant managers at pressed and cast manufacturing facilities, procurement leads at architectural glazing distributors, technical R&D directors developing aerogel core technologies, and specification sales teams serving institutional buyers. Secondary validation drew from ASTM standards documentation, EU Construction Products Regulation guidance, MIIT directive circulars, and hospital procurement database records. Bottom-up shipment estimates triangulated against top-down construction spending allocations across the analysis window.
Cross-referencing historical volume patterns with panel input from manufacturing executives and municipal procurement officers shaped the analytical framework across product type, installation configuration, end-use vertical, and surface treatment specifications. CAGRs derived from regression against construction output indices and energy code adoption timelines. Industry-specific forecast inputs included urban redevelopment project pipelines in Chinese municipal planning documents and EU Green Deal renovation wave implementation schedules.
Several conditions sit outside the modeled scope, including geopolitical disruption to Ukrainian soda ash supply corridors and abrupt shifts in federal building code adoption timelines. Forecasts reflect assumptions about continued KBA thermal mandate enforcement and sustained Chinese state-backed developer procurement. A model refresh is warranted upon material change in silica sand freight cost structures or laminated glass block code adoption in additional US coastal jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Facade Gasket Market
Building Materials
Global Metal Cladding Market
Building Materials
Iron and Steel Slag Market
Building Materials
North America Construction Aggregates Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Foam Bricks Market
Building Materials
Cement Tiles Market
Building Materials
China Cement Market
Building Materials
United States White Cement Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Geocells Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Concrete Market