
 United States White Cement Market | 2026-2036
United States White Cement Market Size, Share, and Industry Trends Forecast 2026-2036
United States White Cement Market Insights
Limestone is decoupling from traditional gray cement formulations in select high-value applications, altering the raw-material calculus for white cement producers. Lehigh White Cement Co. LLC leverages captive limestone quarries in Florida to sustain cost discipline across its southeastern footprint. Federal White Cement anchors its position through specialized kiln operations in Alabama, while Royal White Cement Inc. differentiates via import-linked distribution along the Gulf Coast.
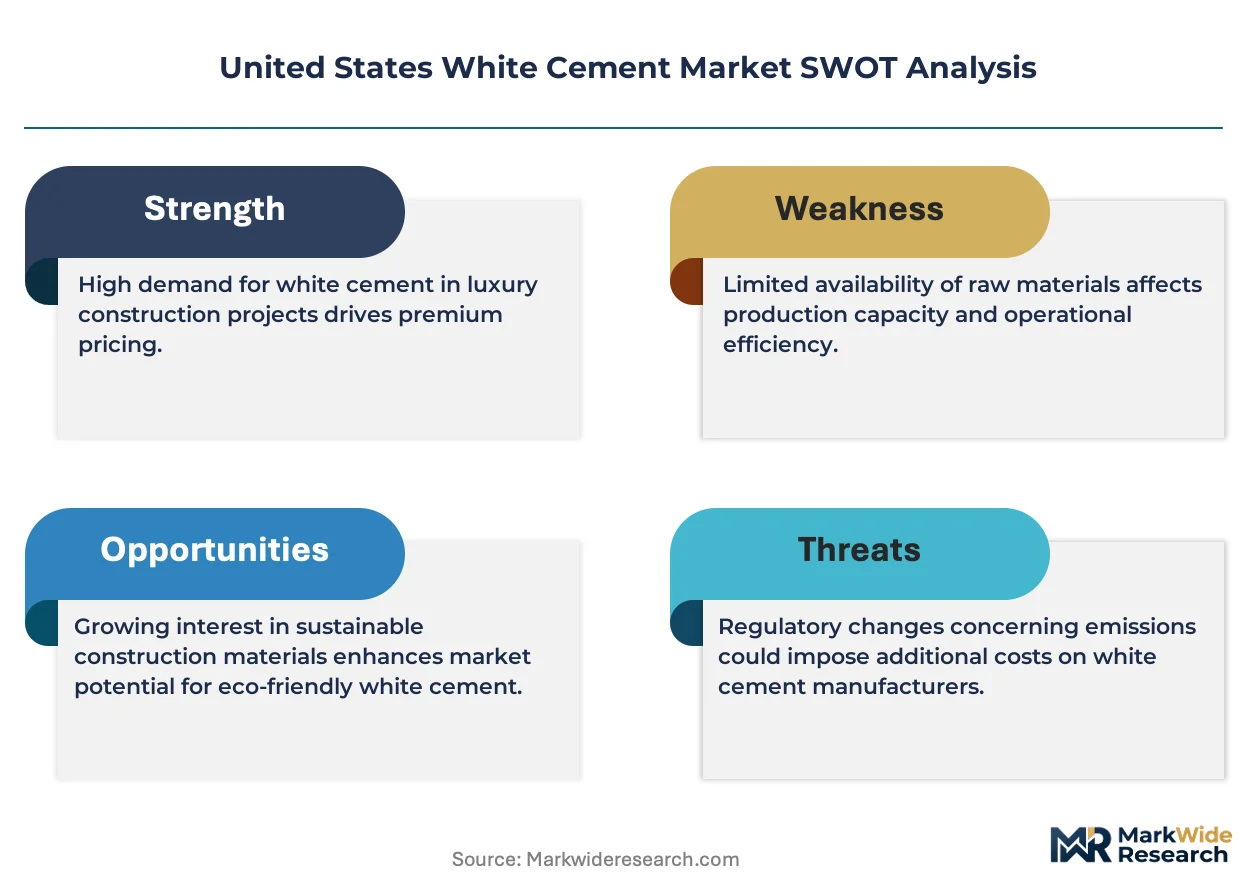
White cement is a hydraulic binder produced from raw materials with low iron content, typically below 0.5% ferric oxide, yielding a reflectance value exceeding 80% on the L* scale for architectural brightness. Its primary purpose centers on decorative and aesthetic concrete applications where surface color consistency and light reflectance determine project acceptance. Portland White Cement dominates volume flows across residential and commercial construction channels, while Specialty Cement commands premium positioning in precast architectural elements where pigment compatibility and early strength development justify higher price points. Decorative Concrete applications within the Application dimension represent the fastest-expanding margin pool, driven by custom flooring and facade treatments in high-end developments.
Federal standards from EPA and OSHA govern particulate emissions and workplace exposure limits at white cement kilns and grinding facilities nationwide. ASTM International maintains C150 specifications for Portland cement types, including physical and chemical requirements that directly constrain product formulation and market access. State-level building codes in California and Florida incorporate CALGreen and Miami-Dade wind-load provisions that shape specification behavior for exterior architectural elements. Stakeholders must monitor evolving Buy America provisions in federal infrastructure spending, as domestic content thresholds for construction materials could redirect procurement patterns across public works channels.
Market Dynamics
EPA emissions standards under the National Emission Standards for Hazardous Air Pollutants are forcing white cement producers to retrofit kilns with advanced particulate control systems, compressing operating margins while accelerating consolidation among smaller regional players.
Growth Catalysts
- ASTM C150 specification alignment:Tightened physical and chemical requirements for Portland White Cement are filtering out low-grade imports, tightening supply discipline and protecting domestic producer margins across the Southeast.
- Decorative concrete specification:Luxury residential developers in Florida and California are mandating white cement for custom flooring and facade treatments, pulling volume through premium distribution channels.
- Sun Belt construction concentration:Warm-climate building activity in Texas and Arizona sustains year-round demand for architectural brightness applications, insulating the market from seasonal demand swings affecting northern states.
Market Restraints
- Low-iron limestone scarcity:Raw material deposits meeting sub-0.5% ferric oxide requirements concentrate in specific geological formations, limiting greenfield plant siting options and inflating quarry acquisition costs.
- Kiln energy intensity:White cement production requires 15-20% higher thermal input than gray cement due to lower iron content reducing heat transfer efficiency, exposing margins to natural gas price volatility.
- Import dependency in coastal markets:Gulf Coast and Pacific Northwest regions rely on seaborne white cement from Middle Eastern and Asian suppliers, creating inventory risk from port congestion and currency fluctuation.
Strategic Opportunities
- Buy America provision leverage:Federal infrastructure spending mandates for domestic construction materials create procurement preference for US-produced white cement in public works channels, redirecting volume from import-reliant competitors.
- Carbon capture retrofit integration:Emerging amine-based capture systems at Alabama and Florida kiln sites could qualify for IRA tax credits while positioning output for low-carbon concrete certification premiums.
- Precast architectural specialization:Pigment-compatible Specialty Cement grades for custom facade elements command price multiples over standard Portland White, offering margin expansion through formulation expertise rather than volume scale.
Industry Challenges
- CALGreen compliance complexity:California's tiered green building standards require extensive documentation of embodied carbon and regional materials sourcing, extending project approval timelines and increasing specification risk for non-compliant suppliers.
- Kiln operator skill scarcity:White cement production demands precise temperature control and raw material blending expertise distinct from gray cement operations, constraining output expansion at facilities lacking experienced technical staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States White Cement Market |
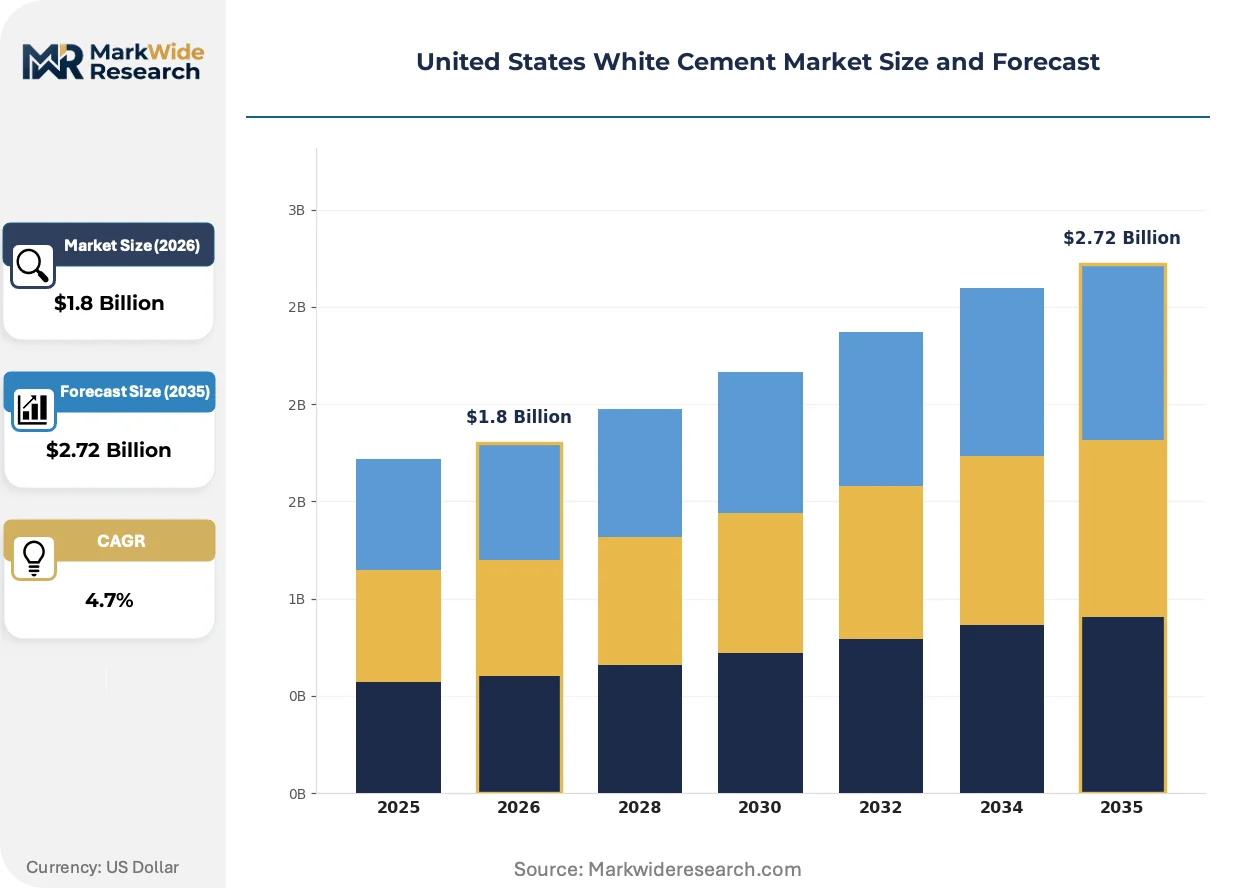
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portland White Cement, Calcium Aluminate Cement, Specialty Cement, Others End Use Industry: Residential Construction, Commercial Construction, Infrastructure, Precast Concrete Distribution Channel: Direct Sales, Distributors, Retail, Online Application: Flooring, Decorative Concrete, Architectural Elements, Repair Works |
| Companies Covered | Lehigh White Cement Co. LLC, Federal White Cement, Argos USA LLC, Almaty's GmbH, Royal White Cement Inc., Holcim, CEMEX SAB De CV, Heidelberg Materials, Suwannee American Cement, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States White Cement Market Trends and Innovations
Digital color-matching systems and low-carbon kiln technologies are converging to reshape how white cement specifications are developed, tested, and validated across architectural and structural applications.
Photocatalytic white cement formulations incorporating titanium dioxide nanoparticles are expanding into vertical facade and infrastructure tunnel applications where air-purifying surface properties justify material premiums. Municipal transit authorities in Arizona and Texas are specifying these grades for station platforms and retaining walls. The technology is expanding into specification regimes previously dominated by conventional architectural coatings, compressing the addressable market for aftermarket surface treatments.
OSHA's updated respirable crystalline silica standard is tightening workplace exposure monitoring requirements at grinding and bagging facilities nationwide. White cement producers must implement continuous personal dust monitoring and engineered ventilation controls, adding fixed compliance costs that disadvantage smaller regional operations. The rule most affects precast and ready-mix channels where bulk handling intensity exceeds packaged retail distribution.
Architects and developers are consolidating specification authority through centralized procurement platforms that standardize material performance databases across multi-project portfolios. Large Florida and California-based design-build firms now mandate third-party reflectance certification and batch-to-batch color consistency guarantees before contract award. This behavior concentrates demand among producers with in-house metrology laboratories and documented quality management systems, marginalizing commodity suppliers lacking technical service depth.
United States White Cement Market Segmentation
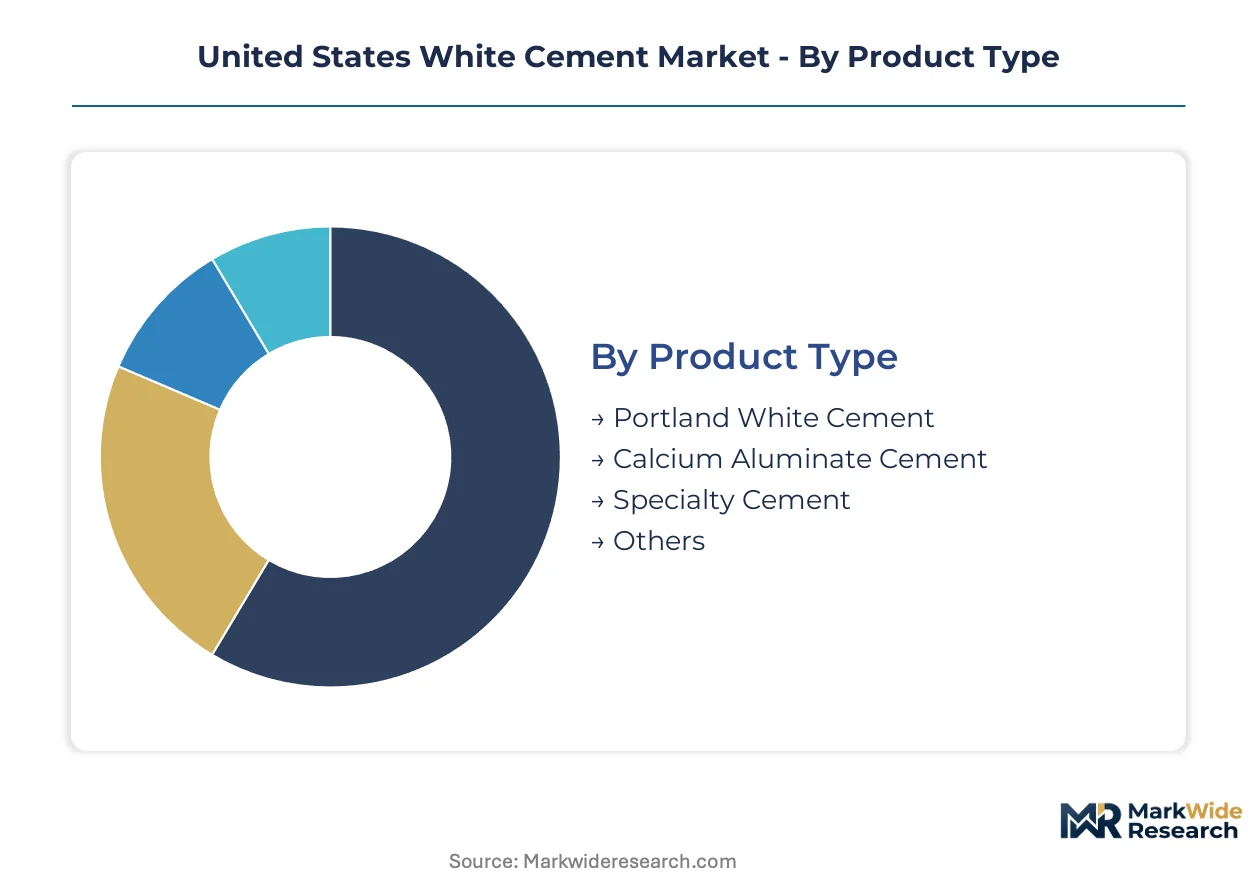
White cement producers allocate capital across distinct product grades and distribution pathways that carry divergent margin profiles. Segment-specific kiln configurations and raw material specifications determine where investment returns concentrate most favorably.
Product Type:
Capital intensity peaks for segments requiring specialized pyroprocessing equipment and controlled iron-content feedstocks.
- Portland White Cement:Standardized hydraulic binder manufactured from low-iron limestone and clay, achieving L* reflectance above 80%. Volume concentrates in Florida and California residential developments where ASTM C150 compliance gates market access. Federal infrastructure Buy America provisions are redirecting procurement toward domestic kiln output.
- Specialty Cement:Formulation-grade material engineered for pigment compatibility and accelerated early strength in precast architectural elements. Texas and Arizona facade contractors specify these grades for custom color-matching requirements. Premium positioning justifies dedicated grinding capacity at Alabama and Florida facilities.
- Calcium Aluminate Cement:High-alumina clinker product for refractory and rapid-setting applications.
- Others:Niche hydraulic binders including magnesium oxychloride and regulated set cements for specialized repair formulations.
Most installed capacity flows through Portland White Cement. Expansion is steepest in Specialty Cement.
End Use Industry:
Customer procurement patterns split between project-scale bulk contracting and specification-driven architect relationships.
- Residential Construction:Luxury single-family and multi-family developments in Sun Belt states specifying white cement for decorative driveways, pool decks, and interior flooring. Florida developers mandate reflectance certification for coastal properties facing salt-air exposure. Volume scales with custom home permitting in Austin, Phoenix, and Miami metropolitan corridors.
- Commercial Construction:High-visibility retail, hospitality, and office facades requiring consistent surface brightness. California CALGreen tiered standards impose embodied carbon documentation that extends project timelines for non-compliant suppliers.
- Infrastructure:Transit stations, highway sound barriers, and municipal buildings where photocatalytic grades gain specification traction.
- Precast Concrete:Off-site manufactured architectural panels and structural elements demanding batch-to-batch color consistency.
Residential Construction commands the largest volume share. Precast Concrete is climbing the fastest specification trajectory.
Distribution Channel:
Channel economics reflect freight radius constraints and technical service requirements for color-critical applications.
- Direct Sales:Bulk contractual relationships between producers and ready-mix operators or precast manufacturers. Lehigh White Cement and Federal White Cement deploy dedicated technical service teams for large Florida and Texas accounts. Margin protection depends on freight optimization from captive quarry-kiln networks.
- Distributors:Regional material wholesalers stocking packaged white cement for mid-scale contractors. Gulf Coast import-dependent markets rely on distributor inventory buffers against seaborne supply disruption.
- Retail:Big-box home improvement and specialty masonry suppliers serving renovation and small-project demand.
- Online:Emerging procurement platforms for specification data and sample ordering, not yet significant for bulk volume.
Distributors handle the broadest geographic coverage. Direct Sales is gaining share fastest among volume accounts.
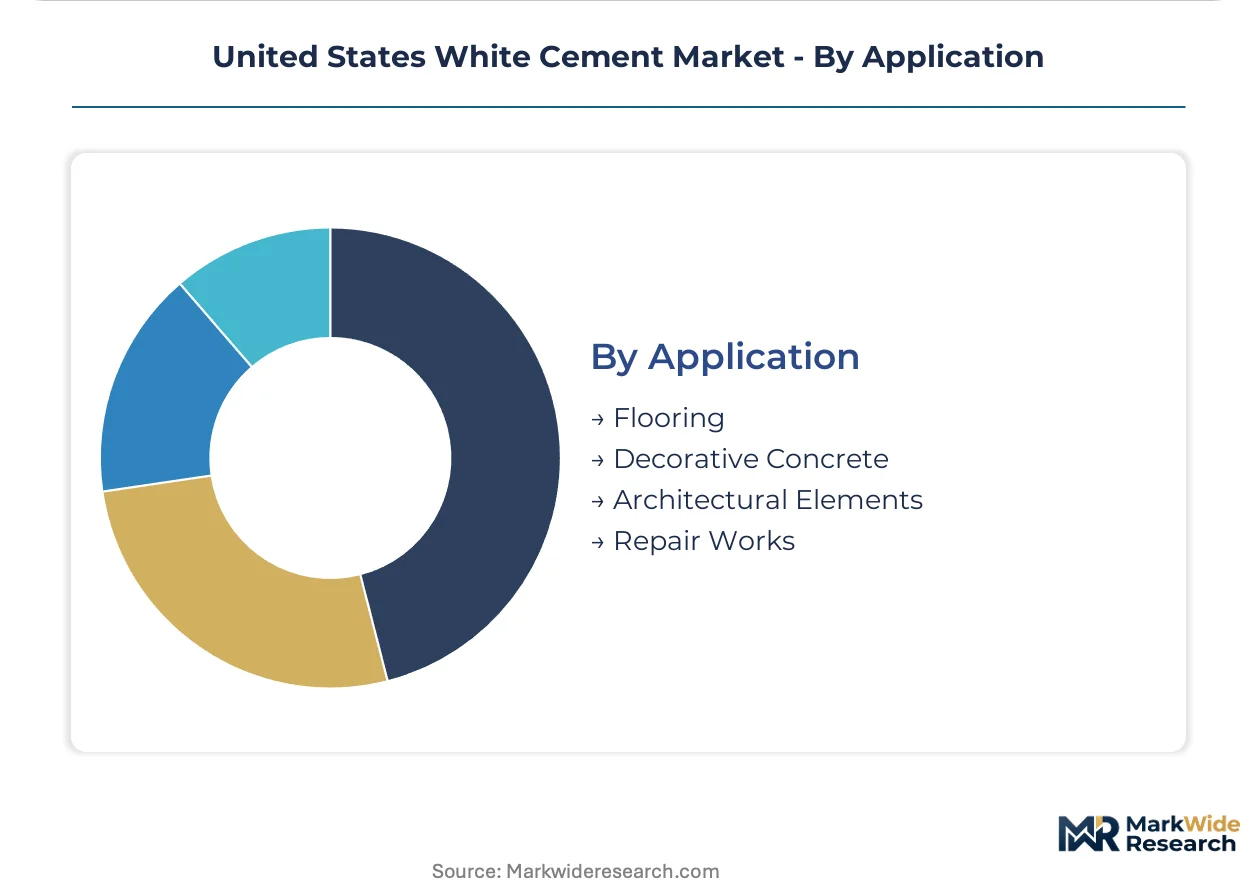
Application:
Application-level specifications determine raw material blending precision and quality assurance investment levels.
- Decorative Concrete:Custom flooring, countertops, and vertical treatments where pigment integration and surface finish determine project acceptance. Arizona and Texas luxury developers specify these applications for outdoor living spaces in warm-climate zones. Digital color-matching systems are compressing specification timelines and raising technical service barriers.
- Architectural Elements:Facade panels, cornices, and ornamental precast requiring dimensional stability and weathering resistance. Miami-Dade wind-load provisions shape exterior attachment specifications for Florida coastal projects.
- Flooring:Polished and stamped concrete surfaces in residential and commercial interiors.
- Repair Works:Structural restoration and cosmetic patching where color matching to existing substrate is critical.
Flooring absorbs the most tonnage. Decorative Concrete is expanding most quickly on a value basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Sun Belt corridor anchors white cement consumption across the United States, with Florida and California metropolitan clusters driving specification intensity for decorative architectural applications.
Southeast (Florida/Georgia)
Luxury residential developments in Miami-Dade and Palm Beach counties mandate white cement for salt-air-resistant decorative facades and pool decks. EPA NESHAP emissions standards govern kiln operations at Alabama and Florida production sites. Lehigh White Cement operates captive limestone quarries across the Florida peninsula to supply southeastern ready-mix channels.
Southwest (Texas/Arizona)
Warm-climate construction sustains year-round demand for architectural brightness in Austin, Phoenix, and Dallas-Fort Worth luxury housing. OSHA respirable crystalline silica standards tighten workplace exposure monitoring at regional grinding facilities. Photocatalytic white cement grades gain specification traction with municipal transit authorities for station platforms and retaining walls.
West Coast (California)
High-end commercial and residential projects in Los Angeles and San Francisco specify white cement for CALGreen-compliant facade systems and interior polished flooring. California's tiered green building standards require embodied carbon documentation that extends project approval timelines. Import-dependent coastal markets rely on seaborne supply from Middle Eastern producers through Long Beach and Oakland port terminals.
Gulf Coast (Louisiana/Mississippi/Alabama)
Federal White Cement anchors production through specialized kiln operations in Alabama serving southeastern precast and architectural concrete channels. Buy America provisions in federal infrastructure spending redirect procurement toward domestic output for public works projects. Royal White Cement Inc. maintains import-linked distribution networks along coastal port systems to buffer inventory risk.
Mid-Atlantic (New York/Pennsylvania/Virginia)
Historic restoration and high-visibility commercial facades in New York City and Philadelphia drive specification demand for color-matched repair applications. ASTM C150 physical and chemical requirements filter low-grade imports from northeastern distribution channels. Regional ready-mix operators consolidate procurement through distributor relationships with limited domestic kiln access.
United States White Cement Market Competitive Landscape
Capacity expansion dominates the current landscape as producers retrofit kilns with advanced particulate control systems to meet EPA NESHAP standards. The market structure concentrates around vertically integrated quarry-to-kiln operators and import-dependent coastal distributors. Three archetypes define competitive positioning: captive limestone producers with southeastern footprints, Gulf Coast import specialists, and multinational construction material conglomerates with diversified cement portfolios. M&A activity and carbon capture retrofit integration represent the dominant competitive moves reshaping asset configurations.
Among domestic kiln operators, Lehigh White Cement Co. LLC and Federal White Cement exemplify the captive-resource archetype through southeastern quarry-kiln integration, while Royal White Cement Inc. occupies a position within the import-linked distribution tier serving Gulf Coast markets. Holcim and CEMEX SAB De CV represent multinational scale players with diversified construction material portfolios that span multiple regional cement categories. These groupings illustrate how raw material access, production asset location, and distribution channel structure determine competitive positioning across specification-driven architectural cement segments.
| Leading Market Players |
|---|
| Lehigh White Cement Co. LLC |
| Federal White Cement |
| Argos USA LLC |
| Almaty's GmbH |
| Royal White Cement Inc. |
| Holcim |
| CEMEX SAB De CV |
| Heidelberg Materials |
| Suwannee American Cement |
| Others |
Pricing and Supply Chain Analysis
Captive quarry-kiln integration across the southeastern United States anchors both supply security and pricing power for domestic white cement producers, insulating them from import volatility while compressing cost pass-through flexibility for coastal competitors dependent on seaborne supply.
Pricing Analysis
Natural gas and low-iron limestone cost pass-through dominates white cement pricing dynamics, with Specialty Cement grades commanding premiums based on ASTM C150 certification tier and pigment compatibility guarantees. Project-based contract structures govern bulk procurement between kiln operators and ready-mix channels, while packaged retail flows through distributor markups. Price erosion runs through import-dependent Gulf Coast markets where currency fluctuation and port congestion compress margins. Residential developers in Florida exhibit highest price sensitivity due to volume scale, whereas precast architectural contractors absorb premiums for batch-to-batch color consistency assurances.
Supply Chain Analysis
Single-source vulnerability sits with Middle Eastern and Asian seaborne suppliers serving Pacific Northwest and Gulf Coast markets through Long Beach and Oakland terminals. Domestic production draws from captive limestone deposits in Florida and Alabama, while imports rest on UAE, Saudi, and Turkish kiln output. Tariff exposure threatens coastal distribution networks should Buy America provisions tighten domestic content thresholds. Distribution runs through vertically integrated bulk contracting for volume accounts and regional wholesalers for mid-scale contractor access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States white cement market functions as a stable compounder where Sun Belt construction concentration and tightening EPA emissions standards sustain disciplined supply growth and protected margin pools.
For Market Incumbents: Acquire low-iron limestone quarry assets in Florida and Alabama to deepen captive resource control against import-dependent competitors. Retrofit Alabama kiln operations with amine-based carbon capture systems to qualify for IRA tax credits and position output for low-carbon concrete certification premiums. Defensive consolidation targets regional grinding facilities lacking EPA NESHAP compliance capital, compressing competitor supply options. For New Entrants and Emerging Players: Capture specification authority through digital color-matching platform deployment serving Arizona and Texas luxury residential developers. Target precast architectural channels in Miami-Dade and Palm Beach counties where wind-load provisions and reflectance certification requirements raise technical service barriers. Partner with municipal transit authorities in Phoenix and Austin for photocatalytic grade trials, establishing specification footholds before volume scale. For Investors and Strategic Acquirers: Consolidation pressure builds where smaller regional players face stranded asset risk from EPA emissions retrofit requirements and OSHA silica compliance costs. Five-to-ten year viability favors vertically integrated quarry-kiln operators with southeastern footprints and documented quality management systems. Monitor Buy America provision enforcement intensity in federal infrastructure spending as the signal for import displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit | IRA tax credit qualification positions Alabama kiln output for low-carbon concrete premiums. |
| Captive Quarry Acquisition | Florida limestone deposit control insulates Lehigh White Cement from raw material cost volatility. |
| Photocatalytic Grade Development | Titanium dioxide nanoparticle integration opens municipal transit specification channels in Arizona and Texas. |
| Direct Sales Channel Expansion | Technical service teams for Texas ready-mix operators compress distributor margin capture. |
| Specialty Cement Grinding Capacity | Dedicated Alabama and Florida facilities serve pigment-compatible precast architectural demand. |
Research Methodology
Direct dialogue with white cement plant managers, ready-mix procurement directors, precast architectural contractors, and Florida luxury residential developers grounded qualitative findings in operational reality. Secondary validation drew from EPA NESHAP emissions filings, ASTM International standard revisions, EIA natural gas price data, and SEC 10-K disclosures from construction material conglomerates. Bottom-up volume modeling across kiln output records and top-down demand estimation from construction permitting databases were triangulated for cross-verification.
Segment-level CAGRs emerged from correlated regression against construction spending indices, kiln capacity utilization rates, and specification trend trajectories across the projection horizon. Product type segmentation modeled Portland White Cement and Specialty Cement grade flows; end-use industry segmentation tracked Residential Construction, Commercial Construction, Infrastructure, and Precast Concrete channels; application-level modeling separated Decorative Concrete, Architectural Elements, Flooring, and Repair Works demand patterns.
Natural gas price volatility, EPA enforcement intensity on particulate emissions, and Buy America provision scope expansion are the dominant revision risks that could compress or extend forecast ranges. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Ireland Cement Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
North America Construction Aggregates Market
Building Materials
Global Metal Cladding Market
Building Materials
GCC Concealed Cistern Market
Building Materials
India Concrete Admixtures Market
Building Materials
Facade Gasket Market
Building Materials
China Architectural Coatings Market
Building Materials
North America Building and Construction Sheets Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Engineered Wood Product Market
Building Materials
Global Commercial Paving Slabs Market
Building Materials
Cement Market