
 Thermography Condition Monitoring Equipment Market | 2026-2036
Thermography Condition Monitoring Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Thermography Condition Monitoring Equipment Market Analytics
Germany's industrial automation corridor is fragmenting as regional manufacturers build dedicated thermal imaging assembly lines to serve European predictive maintenance demand. Fluke Corporation leverages its handheld instrument heritage to dominate portable camera channels across automotive plants. Teledyne FLIR LLC sustains technology leadership through cooled-detector R&D intensity in defense-adjacent thermal cores. SKF anchors its position by integrating infrared monitoring into bearing lifecycle services for rotating machinery clients.
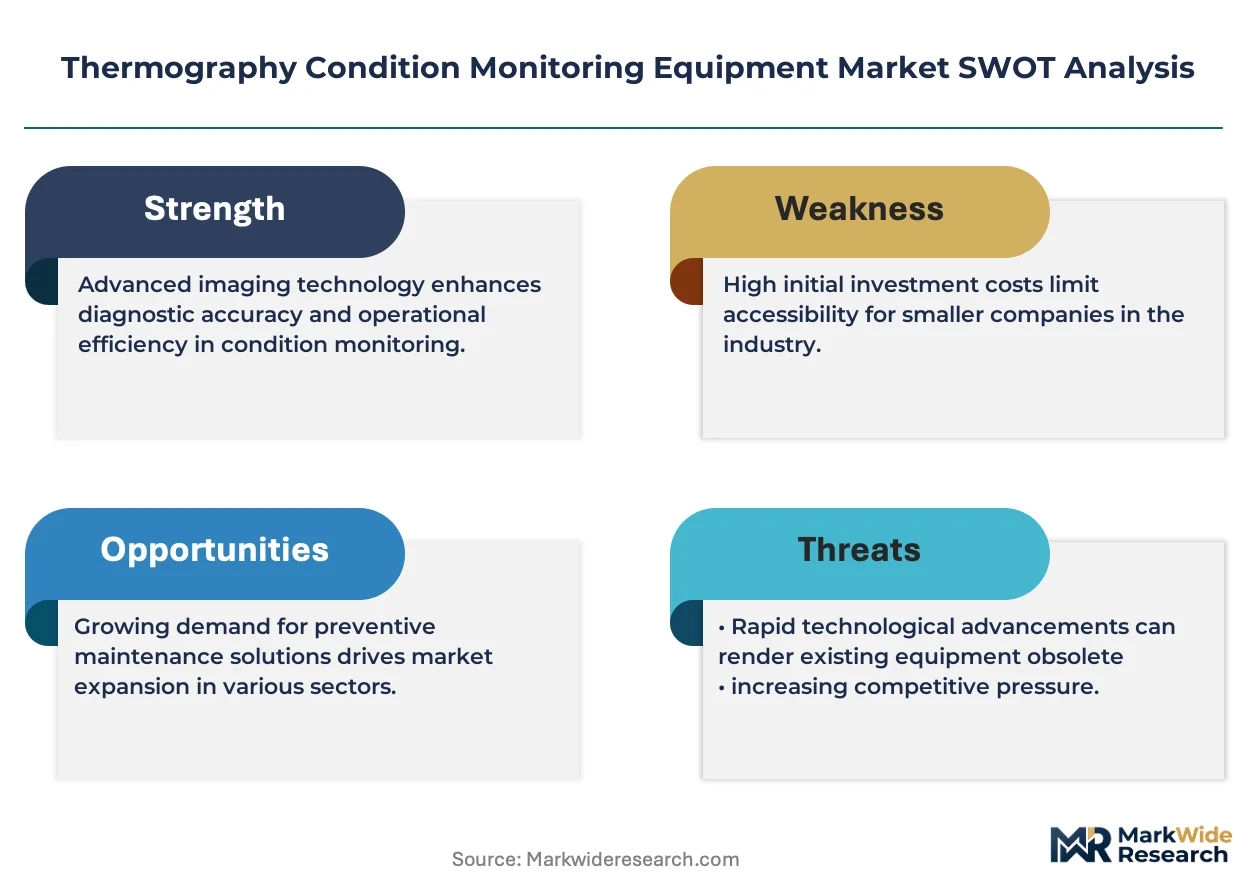
Thermography condition monitoring equipment encompasses thermal imaging systems, infrared sensors, and analytics platforms that detect surface temperature anomalies to predict equipment failure before it occurs. These systems typically operate across spectral bands from 7.5 to 14 micrometers, capturing radiometric data processed through IoT-connected software to flag degradation in motors, transformers, and process vessels. Portable cameras command the largest revenue pool due to flexibility across multi-site industrial operations, while fixed camera installations are gaining traction in continuous-process environments where unmanned monitoring reduces labor exposure. Software solutions represent the fastest-expanding margin segment as vendors bundle AI-driven pattern recognition with hardware sales to lock in recurring analytics subscriptions.
OSHA electrical safety standards and the EU F-Gas Regulation are tightening inspection mandates for energized equipment and refrigerant leakage detection, directly expanding thermography deployment scopes. The EPA's greenhouse gas reporting rules and REACH chemical compliance frameworks further compel facilities to document thermal efficiency and emissions profiles with auditable sensor data. Stakeholders must weigh captive sensor development against platform partnerships as regulatory granularity intensifies and end-users demand unified dashboards spanning vibration, thermal, and oil analysis inputs.
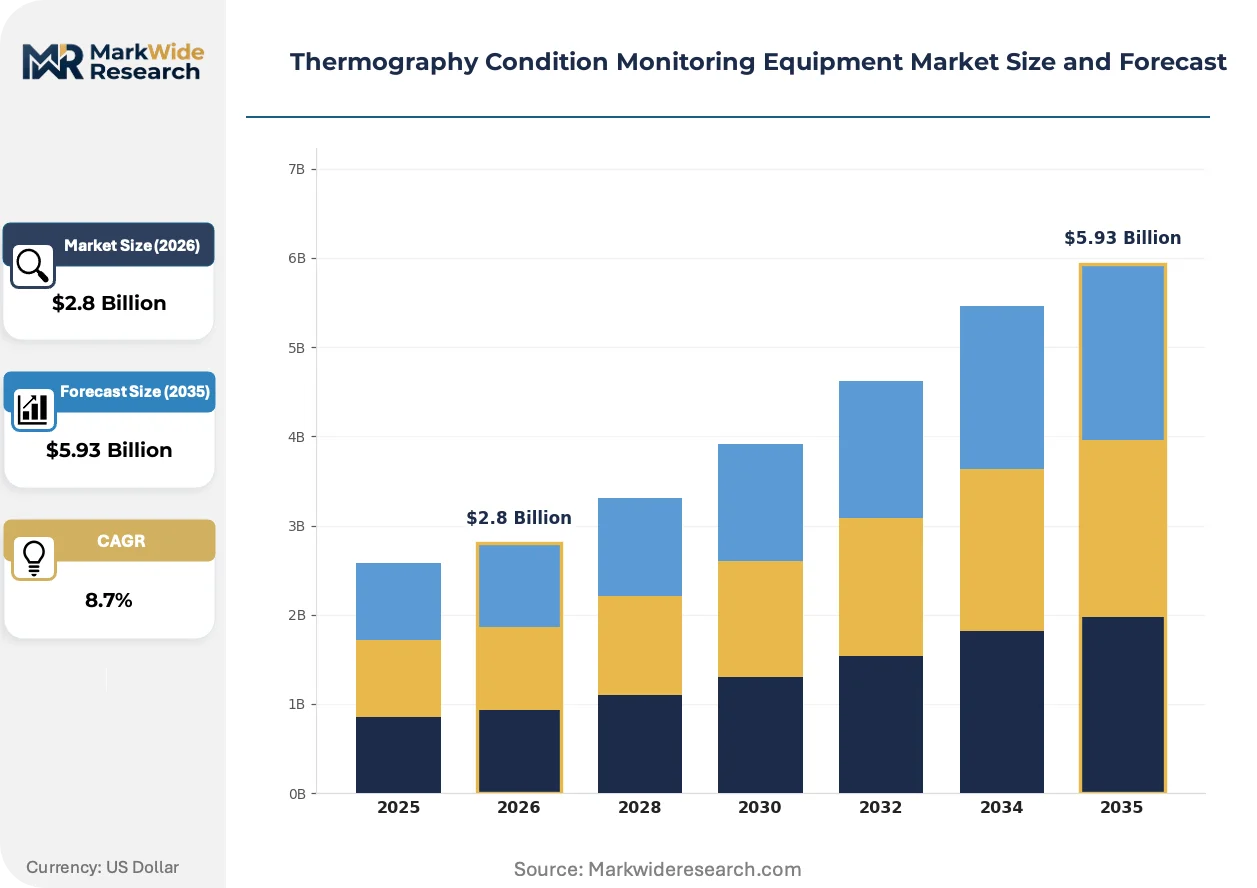
Market Dynamics
Manufacturing plants are consolidating predictive maintenance budgets around thermal diagnostics as unplanned downtime costs escalate, with the EU F-Gas Regulation and OSHA electrical safety standards mandating infrared inspection protocols for energized equipment and refrigerant systems.
Growth Catalysts
- EU F-Gas Regulation:Tightened emissions monitoring requirements for industrial refrigeration and HVAC systems are expanding mandatory thermography inspection scopes across European process plants.
- Predictive maintenance budget expansion:Automotive and heavy machinery manufacturers are reallocating capital from reactive repair programs toward continuous thermal monitoring of critical rotating assets.
- Uncooled microbolometer advances:Reduced sensor manufacturing costs are democratizing thermal camera deployment to mid-tier industrial facilities previously priced out of radiometric diagnostics.
Market Restraints
- Detector material concentration:Germanium and vanadium oxide supply chains concentrate in East Asian refineries, exposing camera manufacturers to input volatility and geopolitical supply disruptions.
- Calibration infrastructure scarcity:Accurate radiometric measurement requires traceable blackbody reference standards that remain limited to metrology laboratories in industrialized economies.
- Vibration analysis substitution:Lower-cost accelerometer networks compete for rotating machinery monitoring budgets, particularly in cost-sensitive process industries with mature vibration programs.
Strategic Opportunities
- India industrial corridor penetration:PLI scheme incentives for domestic manufacturing are creating first-mover advantages for thermal monitoring vendors establishing local calibration and service presence.
- AI-driven pattern recognition:Machine learning convergence with edge-computing thermal cameras enables automated anomaly detection without cloud dependency, opening unmanned continuous monitoring applications.
- EU Green Deal thermal efficiency mandates:Building renovation wave requirements for heat loss documentation are extending thermography from industrial plants into commercial property assessment workflows.
Industry Challenges
- Thermographer certification bottlenecks:ISO 18434-1 and ASNT standards require specialized training hours that outpace workforce development programs, constraining inspection service scalability.
- Multi-physics integration complexity:End-users demand unified dashboards combining thermal, vibration, and oil analysis data, forcing vendors to navigate incompatible data protocols and legacy SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermography Condition Monitoring Equipment Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Cameras, Fixed Cameras, Software Solutions, Accessories End User: Manufacturing, HVAC, Electrical, Oil & Gas Technology: Thermal Imaging, Infrared Sensors, IoT Integration, Data Analytics Application: Predictive Maintenance, Safety Inspections, Quality Control, Energy Audits |
| Companies Covered | Fluke Corporation, Teledyne FLIR LLC, SKF, Emerson Electric Co., Honeywell International Inc., Rockwell Automation, Inc., National Instruments Corp, Siemens AG, JENOPTIK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermography Condition Monitoring Equipment Market Evolving Landscape
Thermal imaging technology is undergoing rapid capability expansion as sensor miniaturization, on-device processing, and regulatory compliance requirements reshape hardware specifications and software bundling strategies across industrial buyer segments.
Uncooled vanadium oxide microbolometer arrays are achieving NETD performance below 40 millikelvin at mainstream price points. Automotive battery manufacturers and semiconductor fabs are adopting these sensors for continuous process monitoring. Manual periodic inspection rounds with higher-end cooled cameras are rendering obsolete in continuous-process environments where thermal runaway risks demand sub-minute detection latency.
OSHA electrical safety standards now explicitly reference infrared thermography for energized equipment inspection in lieu of physical contact methods. Industrial facilities face citation exposure for arc flash incidents where thermal pre-screening was omitted. US utilities and heavy manufacturing plants are responding by mandating thermal qualification for maintenance electricians and integrating radiometric documentation into lockout-tagout workflows.
Buyer organizations are unbundling hardware procurement from analytics subscriptions, treating thermal cameras as capital equipment while negotiating software access separately. Distributor channels face margin compression as direct vendor sales teams engage large multi-site accounts with enterprise licensing. Germany's automotive supplier network exhibits this pattern most acutely, with plant engineering groups centralizing thermal camera fleets and demanding API access for integration into proprietary reliability platforms.
Thermography Condition Monitoring Equipment Market Segmentation
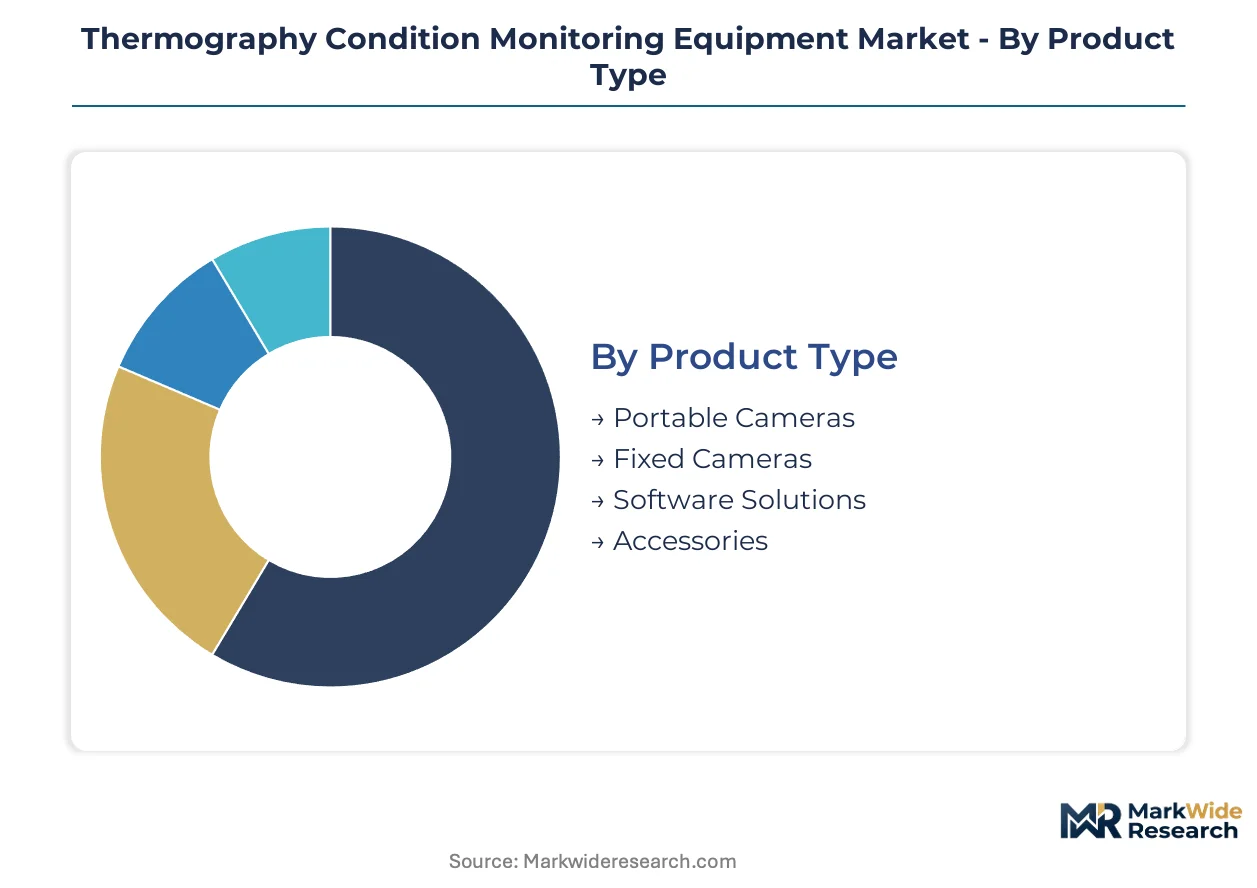
Thermography condition monitoring equipment segments along four critical dimensions: hardware mobility, industrial vertical, sensing architecture, and operational purpose. Each axis reveals distinct procurement patterns, margin profiles, and technology substitution risks that vendors must navigate.
Product Type:
Use-case spectrum spans handheld troubleshooting to unmanned continuous monitoring, with software bundling emerging as the primary margin lever.
- Portable Cameras:Handheld thermal imaging systems with uncooled microbolometer detectors operating across 7.5-14 micrometer spectral bands. Demand concentrates in German automotive plants where maintenance crews perform multi-site rotating asset inspections; flexibility commands premium pricing despite lower resolution than fixed installations.
- Fixed Cameras:Permanently mounted thermal monitoring systems with Ethernet connectivity and edge-computing capabilities for unmanned surveillance. Process industries in the US Gulf Coast deploy these for transformer and reactor vessel monitoring where OSHA electrical safety standards mandate continuous energized equipment oversight.
- Software Solutions:AI-driven analytics platforms with pattern recognition algorithms and IoT dashboard integration.
- Accessories:Calibration blackbodies, protective enclosures, and thermal reference targets.
Established volume favors Portable Cameras; emerging adoption favors Software Solutions.
End User:
Customer type determines specification rigor, with regulated industries demanding certified radiometric accuracy and audit trails.
- Manufacturing:Automotive, machinery, and process plant operators integrating thermal diagnostics into predictive maintenance workflows. Heavy industry clusters in Germany's Ruhr region and US Midwest machine tool corridors drive specification standards for vibration-thermal correlation analytics.
- HVAC:Commercial and industrial refrigeration contractors performing EU F-Gas Regulation-mandated leak detection and thermal efficiency verification. Service fleets across France and Italy require lightweight, smartphone-connected cameras for rooftop and ductwork assessments.
- Electrical:Utilities and industrial facilities conducting energized equipment inspection per OSHA and national electrical codes.
- Oil & Gas:Upstream and downstream operators monitoring flare stacks, storage tanks, and pipeline integrity.
Procurement scale tilts toward Manufacturing; regulatory compliance intensity peaks in HVAC.
Technology:
Architecture choices trade off detection sensitivity against deployment cost, with convergence toward on-device intelligence reducing cloud dependency.
- Thermal Imaging:Radiometric camera systems capturing two-dimensional temperature maps with spatial resolution down to sub-millikelvin NETD performance. Semiconductor fabrication facilities in Japan and South Korea specify these for process chamber thermal uniformity verification.
- Infrared Sensors:Single-point or linear-array pyrometers and thermopiles for discrete temperature measurement. Cost-sensitive packaging lines in India's industrial corridors adopt these for heat-seal verification where imaging resolution exceeds operational requirements.
- IoT Integration:Wireless connectivity protocols enabling edge-to-cloud data transmission and SCADA system interfacing.
- Data Analytics:Machine learning algorithms for anomaly detection and degradation trend forecasting.
Hardware margins concentrate in Thermal Imaging; recurring revenue potential concentrates in Data Analytics.
Application:
Purpose-driven deployment shapes camera specification, inspection frequency, and documentation requirements across operational workflows.
- Predictive Maintenance:Scheduled thermal monitoring of motors, bearings, and transformers to intercept failure before functional degradation. German automotive supplier networks mandate monthly thermal rounds for critical rotating assets, with radiometric data archived for warranty traceability.
- Safety Inspections:Energized electrical equipment assessment and fire-risk identification per OSHA and EU occupational safety frameworks. US utility maintenance crews integrate thermal qualification into arc flash prevention programs.
- Quality Control:Non-contact temperature verification in manufacturing processes including welding, molding, and coating operations.
- Energy Audits:Building envelope and industrial system thermal efficiency assessment for EU Green Deal compliance and utility rebate documentation.
Inspection frequency is highest in Safety Inspections; margin expansion is steepest in Predictive Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector fabrication concentrates in East Asian refineries, yet equipment assembly and demand generation cluster in industrialized manufacturing corridors across three continents. End-user procurement patterns diverge sharply between regulatory-driven replacement cycles and first-time automation investments.
United States
OSHA electrical safety standards mandate infrared thermography for energized equipment inspection, compelling utilities and Gulf Coast process plants to deploy fixed camera networks for continuous transformer monitoring. The EPA's greenhouse gas reporting rules further require thermal efficiency documentation with auditable sensor data. Houston's petrochemical corridor leads unmanned deployment density.
Germany
The EU F-Gas Regulation tightens refrigerant leak detection requirements across industrial refrigeration and HVAC systems, expanding mandatory inspection scopes for service fleets. EU Green Deal thermal efficiency mandates extend thermography into building renovation workflows. The Ruhr industrial belt and Baden-Württemberg automotive supplier networks standardize monthly thermal rounds for rotating assets.
China
Dual carbon goals and MIIT industrial efficiency directives accelerate thermal monitoring adoption in steel, cement, and chemical sectors. Domestic uncooled microbolometer manufacturing reduces import dependency for mid-tier facilities. The Yangtze River Delta semiconductor fabrication cluster specifies radiometric cameras for process chamber thermal uniformity verification.
India
PLI scheme incentives for domestic manufacturing create first-mover advantages for vendors establishing local calibration infrastructure. CEA electrical safety notifications strengthen inspection protocols for grid infrastructure. Maharashtra and Gujarat industrial corridors drive initial adoption among cost-sensitive packaging and automotive component manufacturers.
Japan
METI energy efficiency standards and JIS certification requirements elevate specification rigor for thermal monitoring in precision manufacturing. Semiconductor and battery fabrication facilities in Kyushu and the Kanto region deploy high-sensitivity cooled detectors for sub-millikelvin process control. Workforce aging accelerates unmanned continuous monitoring substitution for manual inspection rounds.
Thermography Condition Monitoring Equipment Market Competitive Landscape
Handheld instrument heritage and defense-adjacent thermal core development split the market between portable camera channels and fixed installation systems. The vendor base organizes around three strategic archetypes: diversified industrial conglomerates bundling thermal monitoring into automation portfolios, specialized sensor manufacturers defending radiometric accuracy leadership, and predictive maintenance service providers integrating hardware into lifecycle contracts. Competitive moves concentrate on AI-driven software bundling and calibration service network expansion.
Within the diversified industrial tier, Fluke Corporation and Emerson Electric Co. anchor positions through handheld instrument distribution channels and multi-physics monitoring integration. Teledyne FLIR LLC exemplifies the specialized sensor archetype with cooled-detector technology concentration. SKF occupies a distinct position by embedding infrared monitoring within rotating machinery lifecycle services for bearing-dependent industrial clients.
| Leading Market Players |
|---|
| Fluke Corporation |
| Teledyne FLIR LLC |
| SKF |
| Emerson Electric Co. |
| Honeywell International Inc. |
| Rockwell Automation, Inc. |
| National Instruments Corp |
| Siemens AG |
| JENOPTIK AG |
| Others |
Value Network & Pricing Analysis
Geopolitical exposure in germanium and vanadium oxide refining determines both pricing tier spreads and supply chain shape across thermal camera manufacturing. East Asian concentrate processing bottlenecks force European and North American assemblers into premium sourcing contracts or captive detector development, fragmenting procurement strategies between cost-optimized and resilience-focused buyers.
Pricing Analysis
The EU F-Gas Regulation dictates the pricing tier structure through mandated inspection frequencies that separate certified radiometric systems from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects NETD performance, calibration traceability, and software bundling depth. Cost compression in mid-tier uncooled cameras is intensifying because Chinese microbolometer foundries are expanding wafer capacity. Automotive plant engineering groups exhibit lowest price sensitivity due to unplanned downtime cost exposure, while Indian packaging manufacturers anchor the economy tier with basic pyrometer deployments.
Supply Chain Analysis
Contract manufacturing concentrates in Foxconn and Jabil facilities across Shenzhen and Suzhou for final camera assembly, with detector module integration resting on Teledyne FLIR's US and Estonia sites. Germanium substrate supply draws from China and Russia, while vanadium oxide thin-film deposition feeds from Japanese and South Korean materials specialists. Single-source vulnerability in cooled detector indium antimonide supply threatens high-sensitivity camera lead times. Distribution runs through Fluke and SKF direct sales teams for enterprise accounts, with regional distributors serving HVAC service fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive supplier networks that centralize thermal camera fleet procurement across multi-site operations. This concentration fragments vendor pricing power and forces unbundled software negotiations.
For Market Incumbents: Harden calibration service network density in Germany and the US Gulf Coast to defend against emerging AI-native analytics vendors. Vertical integration into uncooled microbolometer wafer production reduces exposure to East Asian substrate volatility. Lock in multi-year enterprise licensing with automotive plant engineering groups before API unbundling accelerates.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat industrial corridors offer the most penetrable entry point for cost-optimized thermal sensor bundles. Target packaging and automotive component manufacturers with smartphone-connected cameras bypassing traditional distribution markups. Lead with PLI scheme-aligned local assembly to undercut import duty burdens on finished cameras.
For Investors and Strategic Acquirers: The market sits at a software-unbundling phase that favors predictive maintenance platform consolidators over pure hardware manufacturers. Acquisition targets with AI-driven pattern recognition IP and existing SCADA integration contracts offer strongest long-term viability. Watch for ISO 18434-1 certification bottlenecks forcing consolidation among inspection service providers as workforce development lags demand.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Driven Pattern Recognition Development | Edge-computing thermal cameras with on-device anomaly detection reduce cloud dependency for unmanned monitoring. |
| Calibration Infrastructure Expansion | Local blackbody reference standards in India and Southeast Asia overcome metrology laboratory scarcity constraints. |
| Multi-Physics Platform Integration | Unified dashboards combining thermal, vibration, and oil analysis data capture enterprise reliability platform budgets. |
| EU Green Deal Thermal Efficiency Certification | Building renovation wave mandates extend thermography from industrial plants into commercial property assessment workflows. |
| Uncooled Microbolometer Cost Reduction | Domestic Chinese wafer capacity expansion democratizes thermal camera deployment to mid-tier industrial facilities. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, customs trade data, and equipment vendor SEC disclosures across the analysis window. Plant maintenance directors, predictive maintenance platform engineers, thermal camera OEM procurement teams, and HVAC service fleet operators provided operational deployment data. Bottom-up triangulation against top-down macroeconomic indicators validated segment-level demand estimates.
Forecast inputs span hardware mobility, industrial vertical, sensing architecture, and operational purpose segmentation dimensions across the projection horizon. CAGRs derive from installed base growth, replacement cycle acceleration, and regulatory mandate expansion rates. Model sensitivity tests incorporate uncooled microbolometer cost curves, thermographer certification throughput constraints, and multi-physics integration adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by AI-native analytics entrants or Chinese detector foundries would shift outcomes. Quarterly review of PLI scheme disbursement rates, EU F-Gas enforcement intensity, and OSHA electrical safety citation volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Inductive and LVDT Sensors Market
Sensors and Controls
Variable Reluctance Sensor Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Fingerprint Sensor Market
Sensors and Controls
Smart Control Socket Market