
 Inductive and LVDT Sensors Market | 2026-2036
Inductive and LVDT Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Inductive and LVDT Sensors Market Foresight
ISO 13849 functional safety certification for machinery control systems is unwinding competitive access across European and North American industrial automation sectors. TE Connectivity Ltd. leverages its broad portfolio of certified position sensors to anchor supply relationships with tier-one automotive OEMs. Balluff GmbH specializes in inductive proximity platforms for factory automation, while SICK AG competes through its integrated safety and sensing architectures for robotic cells.
Inductive and LVDT sensors detect metallic target proximity and linear displacement through electromagnetic coupling, with LVDT variants achieving sub-micron resolution across stroke lengths from millimeters to meters for precision feedback in hydraulic actuators and turbine governors. Analog technology still dominates installed bases in heavy machinery, though digital output formats are displacing legacy interfaces in new aerospace and robotics designs. Position feedback applications command the widest deployment footprint, while displacement measurement for structural health monitoring in civil infrastructure represents an emerging margin pool.
FDA 21 CFR Part 820 quality system regulations govern sensor integration into medical device actuators in the United States, while the EU Machinery Directive and CE marking requirements enforce functional safety validation for industrial deployments across Europe. China's GB standards and NMPA device regulations add parallel compliance layers for suppliers targeting domestic automation and medical equipment manufacturers. Stakeholders must decide whether to pursue dual-certification strategies or prioritize single-geometry dominance as regional technical barriers diverge.
Market Dynamics
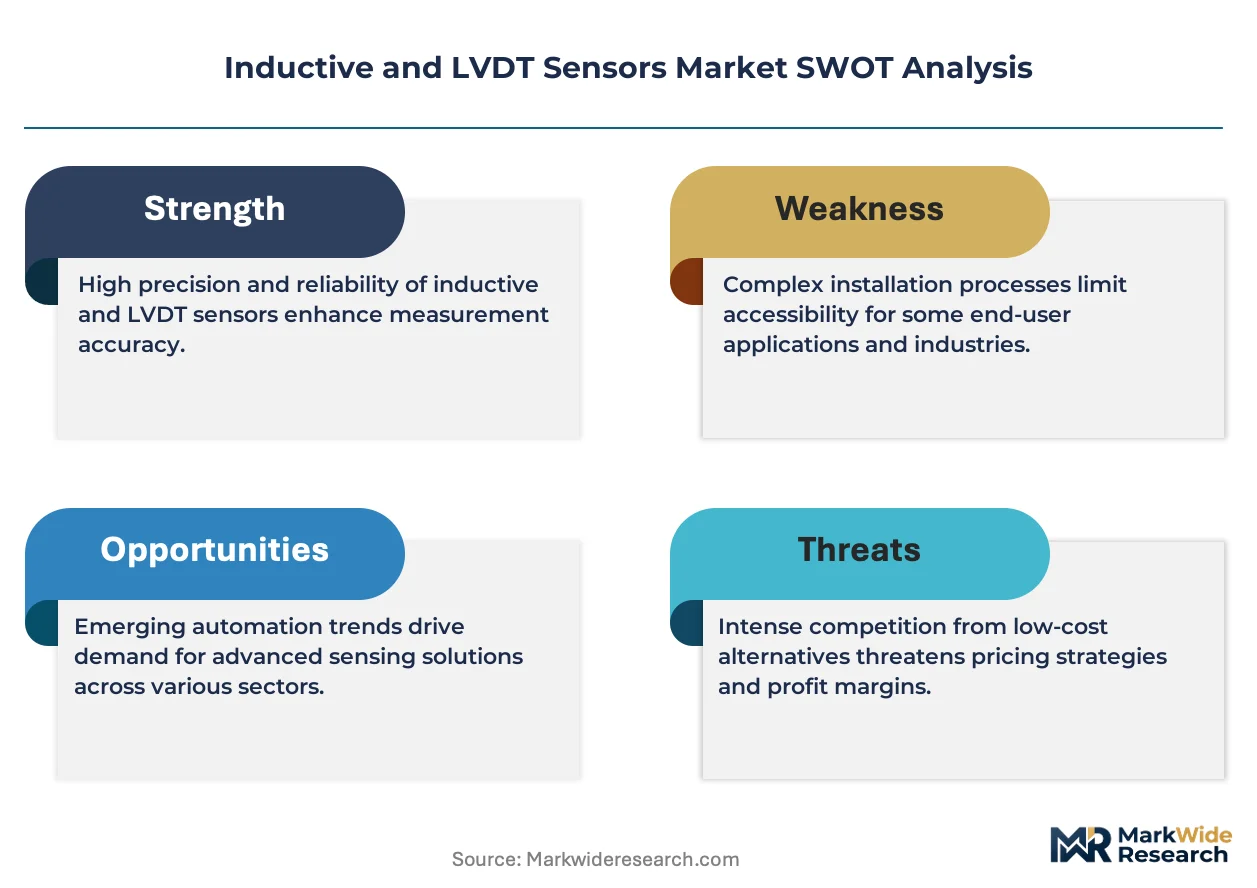
Digital output interfaces are compressing analog sensor architectures across aerospace and robotics supply chains, forcing incumbent suppliers to recertify legacy platforms while new entrants capture design wins in next-generation actuator systems.
Growth Catalysts
- EU Green Deal machinery efficiency mandates:Industrial OEMs in Germany and France are retrofitting hydraulic systems with high-precision LVDT feedback loops to meet tightened energy consumption benchmarks for factory automation equipment.
- Aerospace fly-by-wire proliferation:Flight control system manufacturers are expanding redundant position sensing architectures across commercial and defense platforms, creating specification pull for sub-micron resolution inductive platforms.
- China's dual carbon goals:Domestic turbine governor and power generation equipment producers are accelerating sensor procurement to modernize thermal and hydroelectric plant control systems under national decarbonization timelines.
Market Restraints
- Copper and nickel price volatility:Electromagnetic coil raw material costs swing with commodity markets, compressing margin stability for mid-volume sensor producers without captive metallurgical supply.
- ISO 13849 certification concentration:Functional safety validation capabilities cluster among a handful of European test houses, creating bottleneck risk for suppliers seeking machinery directive compliance.
- Optical encoder substitution:Photoelectric position sensing achieves comparable precision in clean environments, eroding inductive sensor addressable market in laboratory and semiconductor fabrication settings.
Strategic Opportunities
- India PLI scheme for automation:Domestic manufacturing incentives are attracting sensor suppliers to establish local production for automotive and industrial robotics integrators in Pune and Chennai corridors.
- Civil infrastructure structural health monitoring:Bridge and building displacement measurement applications remain underpenetrated, offering margin expansion for ruggedized LVDT platforms with wireless telemetry integration.
- EU AI Act safety-critical system classification:Machinery incorporating autonomous decision loops will require enhanced sensor redundancy, expanding specification scope for certified inductive proximity platforms in robotic cells.
Industry Challenges
- Embedded firmware security certification:IEC 62443 cybersecurity standards for industrial automation devices extend validation timelines and engineering headcount requirements for sensor suppliers adding digital communication stacks.
- Legacy system integration complexity:Brownfield manufacturing facilities in heavy machinery sectors operate mixed-vintage control architectures, forcing sensor vendors to maintain obsolete analog interface production alongside digital platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inductive and LVDT Sensors Market |
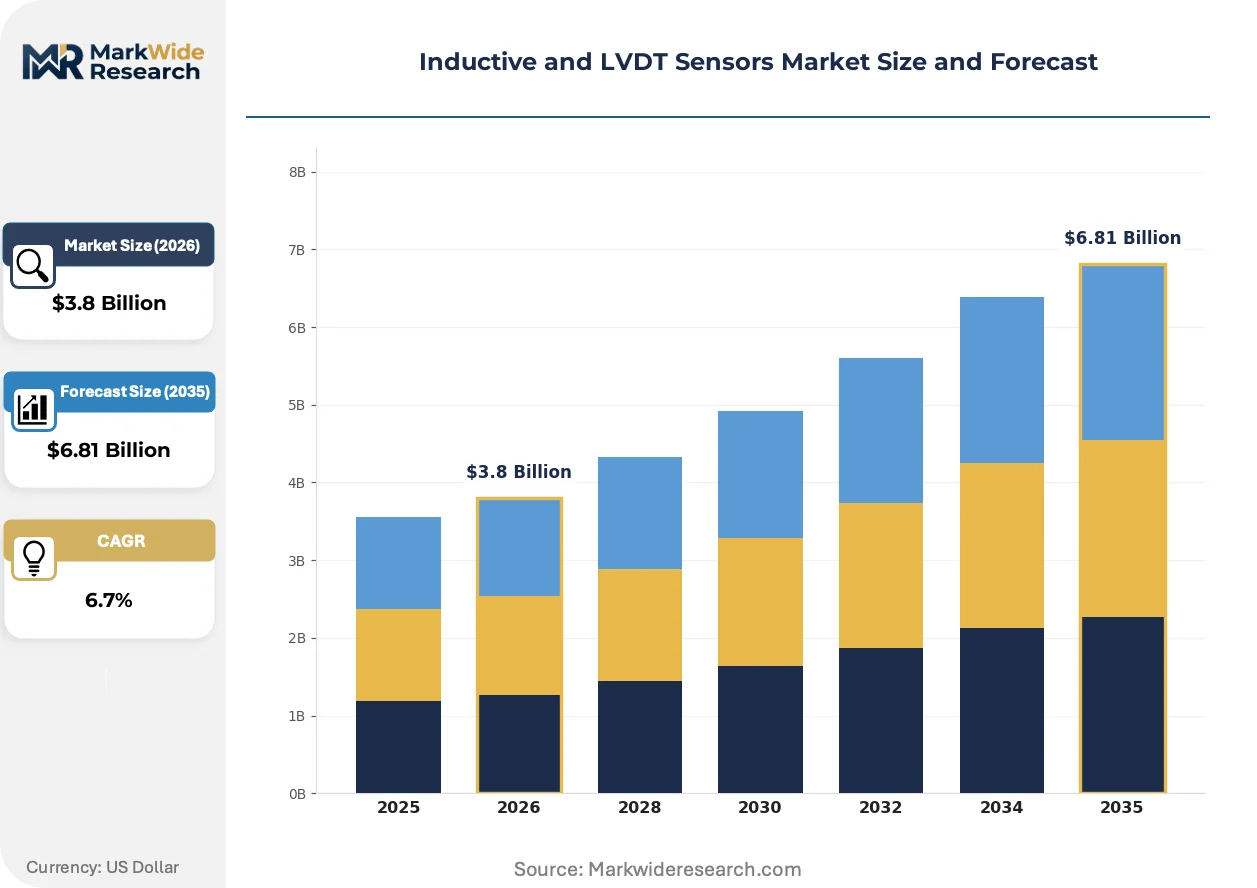
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inductive Sensors, LVDT Sensors, Capacitive Sensors, Optical Sensors Technology: Analog, Digital, Wireless, Hybrid End User: Aerospace, Automotive, Industrial Automation, Robotics Application: Position Feedback, Displacement Measurement, Force Sensing, Pressure Monitoring |
| Companies Covered | Honeywell International Inc., TE Connectivity Ltd., AMETEK Inc., Keyence Corporation, Balluff GmbH, SICK AG, Omega Engineering Inc., MTI Instruments, RDP Electrosense Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inductive and LVDT Sensors Market Shifts & Advancements
Electromagnetic sensing architectures are bifurcating between ultra-miniaturized inductive platforms for collaborative robotics and extended-stroke LVDT designs for energy infrastructure, with interface standardization emerging as the critical competitive variable.
IO-Link digital communication protocols are supplanting 4-20mA and 0-10V analog outputs in new industrial automation deployments. Automotive tier-one suppliers and semiconductor equipment OEMs are specifying IO-Link inductive proximity sensors for real-time diagnostics and predictive maintenance integration. This shift is compressing demand for legacy analog-only sensor portfolios while expanding addressable market for suppliers with certified digital platforms.
REACH substance restrictions on nickel compounds are forcing coil metallurgy reformulation across European sensor manufacturing. Suppliers are migrating toward silver-plated copper and specialized alloys to maintain electromagnetic performance while achieving chemical compliance. Medical device actuator and food-grade machinery segments are most affected, with certification timelines extending six to twelve months for redesigned platforms.
Specification consolidation among German automotive OEMs and automation integrators is concentrating procurement authority with fewer buyer entities. Tier-one suppliers now mandate unified sensor platforms across multiple plant locations, displacing fragmented regional sourcing patterns. This concentration is most visible in Stuttgart and Munich industrial corridors, where Balluff and SICK maintain entrenched supply relationships through integrated safety architectures.
Inductive and LVDT Sensors Market Segmentation
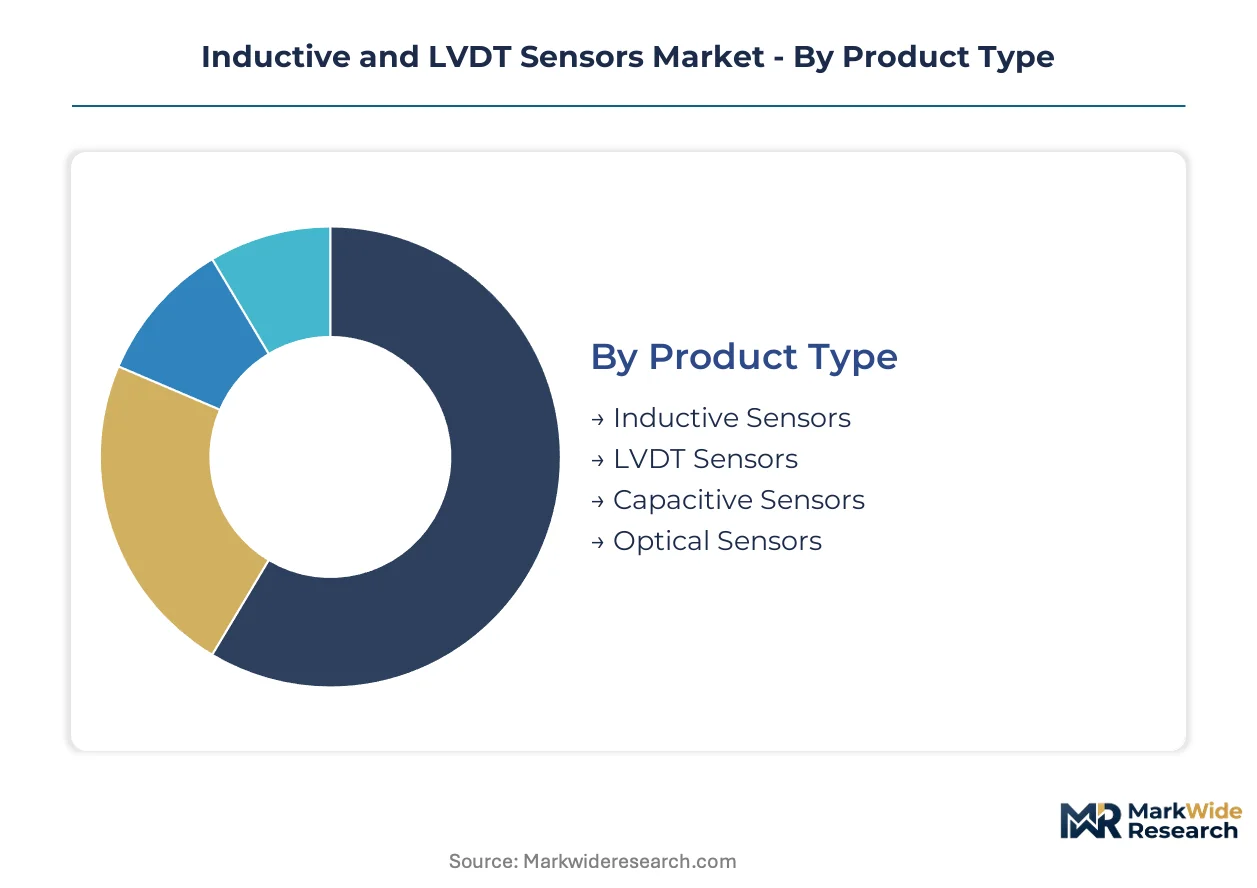
Segmentation in the inductive and LVDT sensors market reveals how electromagnetic sensing architectures align with distinct procurement channels. Aerospace and automotive OEMs route high-precision LVDT procurement through tier-one system integrators, while factory automation buyers source inductive proximity sensors via distributor networks.
Product Type:
Channel mix varies sharply by product category, with inductive sensors flowing through broad industrial distributors and LVDT platforms moving via direct OEM contracts.
- Inductive Sensors:Electromagnetic proximity detection devices operating on eddy current principles, typically housed in cylindrical or rectangular form factors. Demand clusters around Stuttgart and Munich automotive corridors where Balluff and SICK anchor supply relationships through integrated safety architectures. By volume, inductive sensors lead. By growth pace, LVDT sensors are ahead.
- LVDT Sensors:Linear Variable Differential Transformers delivering sub-micron displacement resolution across stroke lengths from millimeters to meters. Flight control system manufacturers in the United States and Germany are expanding redundant position sensing architectures, creating specification pull for certified platforms.
- Capacitive Sensors:Non-contact proximity devices detecting dielectric target changes, deployed in semiconductor fabrication and food-grade machinery where metallic contamination risks exclude inductive alternatives.
- Optical Sensors:Photoelectric position sensing achieving comparable precision in clean environments, eroding inductive sensor addressable market in laboratory and controlled manufacturing settings.
Margin structures favor LVDT platforms in aerospace channels, while inductive sensors compete on volume throughput in automation distribution.
Technology:
Cost tier stratification separates legacy analog deployments from premium digital platforms commanding certification premiums.
- Analog:4-20mA and 0-10V output formats dominating installed bases in heavy machinery and brownfield manufacturing facilities. India's PLI scheme for automation is attracting suppliers to establish local production for cost-sensitive analog platforms serving Pune and Chennai integrators.
- Digital:IO-Link communication protocols supplanting legacy interfaces in new industrial automation deployments, enabling real-time diagnostics and predictive maintenance integration. Automotive tier-one suppliers and semiconductor equipment OEMs are mandating digital specifications for next-generation actuator systems.
- Wireless:Battery-powered or energy-harvesting architectures for civil infrastructure structural health monitoring, where bridge and building displacement measurement applications remain underpenetrated.
- Hybrid:Dual-output platforms bridging analog legacy systems with digital upgrade paths, addressing mixed-vintage control architectures in heavy machinery sectors.
Digital platforms claim the steepest expansion trajectory as IO-Link certification becomes mandatory for German automotive procurement.
End User:
Application intensity determines customer segmentation, with aerospace and robotics demanding highest precision specifications.
- Aerospace:Commercial and defense flight control systems requiring redundant position sensing with sub-micron resolution. FAA certification timelines and EU Aviation Safety Agency validation create dual-compliance burdens for suppliers.
- Automotive:Tier-one OEMs in Germany specifying unified sensor platforms across multiple plant locations, displacing fragmented regional sourcing patterns.
- Industrial Automation:Factory equipment OEMs retrofitting hydraulic systems with high-precision feedback loops to meet EU Green Deal machinery efficiency mandates.
- Robotics:Collaborative robot manufacturers specifying ultra-miniaturized inductive platforms with integrated safety architectures for human-machine interaction zones.
Aerospace commands premium pricing tiers; industrial automation drives absolute volume absorption.
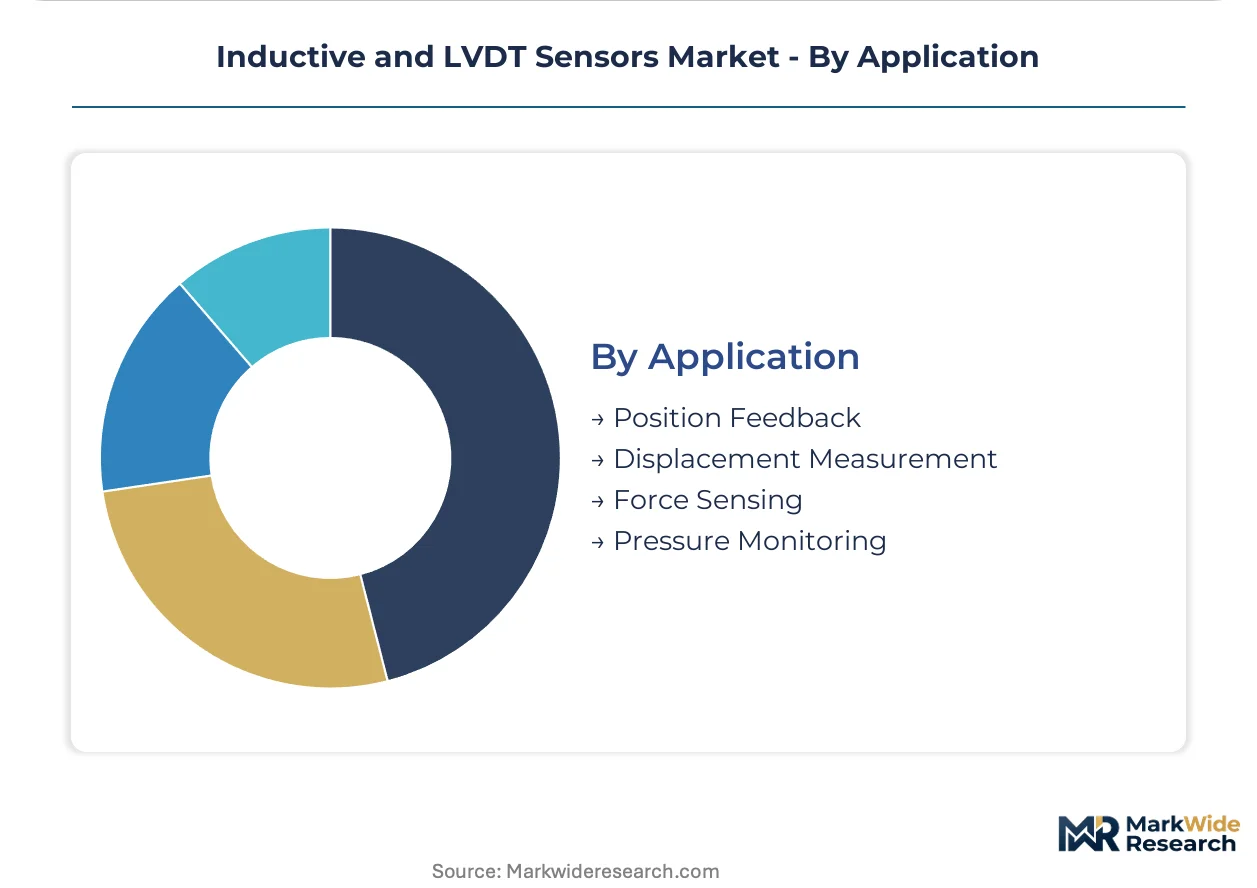
Application:
Volume concentration sits with position feedback, while displacement measurement offers margin expansion in emerging infrastructure monitoring.
- Position Feedback:Dominant deployment footprint across hydraulic actuators, valve positioning, and machine tool axis control. China's dual carbon goals are accelerating sensor procurement for turbine governor modernization in thermal and hydroelectric plants.
- Displacement Measurement:Structural health monitoring for bridges, buildings, and energy infrastructure with wireless telemetry integration. REACH substance restrictions on nickel compounds are forcing coil metallurgy reformulation for European civil engineering deployments.
- Force Sensing:Load cell integration and material testing applications requiring strain-to-displacement conversion through specialized LVDT configurations.
- Pressure Monitoring:Process industry applications in oil and gas, power generation, and chemical processing where pressure-to-displacement transduction meets hazardous area certification requirements.
Position feedback maintains volume leadership; displacement measurement is gaining share fastest in infrastructure channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal machinery efficiency mandates and China's dual carbon goals are redirecting procurement toward precision feedback systems. Aerospace fly-by-wire proliferation in the United States and Germany sustains demand for sub-micron resolution platforms. Industrial automation corridors in Stuttgart, Munich, and Detroit anchor sensor deployment density.
United States
Commercial and defense flight control manufacturers are expanding redundant position sensing architectures across next-generation platforms. FAA certification timelines govern sensor integration into fly-by-wire systems, creating compliance barriers for uncertified suppliers. Aerospace clusters in Seattle and Wichita concentrate specification authority with tier-one system integrators.
Germany
Automotive OEMs and automation integrators are retrofitting hydraulic systems with high-precision LVDT feedback loops to meet tightened energy consumption benchmarks. EU Machinery Directive and ISO 13849 functional safety requirements enforce validation protocols for industrial deployments. Stuttgart and Munich industrial corridors concentrate procurement authority with unified sensor platform mandates across multiple plant locations.
China
Domestic turbine governor and power generation equipment producers are accelerating sensor procurement to modernize thermal and hydroelectric plant control systems. GB standards and NMPA device regulations add parallel compliance layers for suppliers targeting automation and medical equipment manufacturers. Yangtze River Delta manufacturing bases concentrate demand from state-owned power generation enterprises.
India
Domestic manufacturing incentives under the PLI scheme for automation are attracting sensor suppliers to establish local production for automotive and industrial robotics integrators. BIS certification requirements govern industrial equipment safety standards for factory deployments. Pune and Chennai corridors concentrate emerging demand from automotive tier-one suppliers and automation integrators.
Japan
Collaborative robot manufacturers are specifying ultra-miniaturized inductive platforms with integrated safety architectures for human-machine interaction zones. METI industrial policy and JIS standards shape precision equipment procurement requirements. Kanto and Kansai manufacturing belts concentrate demand from semiconductor equipment OEMs and precision machinery producers.
Inductive and LVDT Sensors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with certified safety portfolios alongside specialized proximity sensor fabricators. Market structure concentrates specification authority among tier-one automotive and aerospace OEMs, compressing viable supplier pools to ISO 13849-certified entities. Two dominant archetypes emerge: integrated safety architecture providers and component-focused proximity specialists. Competitive moves center on IO-Link digital platform certification and REACH-compliant coil metallurgy reformulation.
Within the integrated safety tier, TE Connectivity Ltd. and SICK AG occupy positions anchoring supply relationships with German automotive OEMs through certified position sensor portfolios. Balluff GmbH exemplifies the proximity specialist archetype, with its Baden-Württemberg base aligning with Stuttgart corridor demand concentration. Honeywell International Inc. represents the diversified conglomerate model spanning aerospace and industrial automation certification requirements.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| TE Connectivity Ltd. |
| AMETEK Inc. |
| Keyence Corporation |
| Balluff GmbH |
| SICK AG |
| Omega Engineering Inc. |
| MTI Instruments |
| RDP Electrosense Inc. |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts with German automotive OEMs lock in both electromagnetic coil supply access and multi-year price visibility for tier-one sensor suppliers. These arrangements concentrate procurement leverage among Stuttgart and Munich corridor buyers while insulating certified producers from spot copper and nickel volatility.
Pricing Analysis
Certification level (ISO 13849/CE/FDA-grade) creates the primary spread between premium and standard tiers. Three-tier pricing structure across certified, compliant, and uncertified levels dominates, with aerospace channels absorbing the steepest premiums for dual FAA-EASA validation. Cost compression in mid-volume analog platforms is intensifying because Indian PLI scheme entrants are undercutting legacy European producers on price. Factory automation distributors exhibit highest price sensitivity; aerospace tier-one integrators show least.
Supply Chain Analysis
Germany and China anchor electromagnetic coil winding and sensor assembly, with Japan supplying precision ferrite cores and specialty alloys. Raw material dependencies center on copper wire from Chilean smelters, nickel plating from Indonesian refineries, and rare-earth ferrite from Chinese processors. Single-source vulnerability runs through REACH-compliant nickel compound alternatives, where European reformulation timelines lag Asian supply. Distribution runs through integrated safety architecture providers for automotive OEMs and broad industrial distributors for factory automation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The inductive and LVDT sensors market sits in a cyclical recovery phase as aerospace fly-by-wire procurement rebounds from pandemic-delayed platform certifications. Commercial and defense flight control modernization programs provide the cyclical driver justifying medium-term capacity planning.
For Market Incumbents: Compound certification moats by accelerating IO-Link platform validation across multiple regulatory jurisdictions simultaneously. Optical encoder substitution in semiconductor fabrication settings threatens inductive sensor incumbency in clean-room precision applications. Backward integration into captive copper wire drawing secures margin stability against commodity volatility. For New Entrants and Emerging Players: Differentiate on civil infrastructure wireless telemetry integration, where bridge and building displacement measurement remains underpenetrated. India's PLI scheme corridors offer the most penetrable geography for cost-competitive analog platform entry. Pursue BIS certification early to unlock Pune and Chennai automotive integrator procurement committees. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated safety architecture providers with multi-year automotive OEM contracts. The five-to-ten year viability window favors suppliers with dual aerospace-industrial certification portfolios. Target acquisition archetype: mid-cap LVDT specialists with FAA-EASA validation and dormant medical device actuator channels. The signal to watch is IO-Link specification adoption velocity in German automotive RFQs as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| IO-Link Platform Certification | TE Connectivity and SICK AG anchor German automotive supply relationships through certified digital architectures. |
| REACH-Compliant Coil Metallurgy Reformulation | Silver-plated copper migration extends certification timelines six to twelve months for European medical device suppliers. |
| India PLI Local Production Establishment | Pune and Chennai corridors attract sensor suppliers for cost-competitive analog platform manufacturing. |
| Civil Infrastructure Wireless Telemetry Integration | Ruggedized LVDT platforms with battery-powered architectures unlock bridge displacement measurement margin pools. |
| Dual FAA-EASA Certification Investment | Aerospace fly-by-wire proliferation creates specification pull for redundant position sensing platforms. |
Research Methodology
A spread of perspectives from OEM procurement directors, tier-one system integrators, electromagnetic component suppliers, and industrial automation distributors converged on the working assumptions. Primary interviews with flight control system engineers, factory automation specifiers, and sensor test house validation specialists combined with secondary validation from FAA certification databases, EASA type certificate records, EU Machinery Directive implementation reports, and SEC filings from diversified industrial conglomerates. Bottom-up unit demand modeling and top-down market sizing triangulation anchored volume and value estimates.
Segmentation dimensions modeled include product type (inductive, LVDT, capacitive, optical), technology (analog, digital, wireless, hybrid), end user (aerospace, automotive, industrial automation, robotics), and application (position feedback, displacement measurement, force sensing, pressure monitoring). CAGRs were derived from regression analysis of historical procurement patterns and projected specification adoption curves. Industry-specific forecast inputs incorporated EU Green Deal machinery efficiency mandate implementation timelines and China's dual carbon goals for power generation modernization.
The analysis sits within stated boundaries; outcomes outside sustained aerospace platform certification velocity or abrupt REACH substance restriction expansion would require recalibration. Forecasts reflect documented assumptions regarding copper price stability and ISO 13849 test house capacity expansion. Recalibration cycles align with material shifts in EU AI Act safety-critical system classification implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Heart Beat Sensor Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Europe Fingerprint Sensor Market
Sensors and Controls
IoT Sensor Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Global Signal Conditioning Modules Market