
 United States Sensor Market | 2026-2036
United States Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
United States Sensor Market Insights
Photonics and MEMS engineering talent scarcity is bifurcating the United States sensor market into capital-rich incumbents with captive fabrication and mid-tier players dependent on external foundries. Texas Instruments Incorporated leverages vertical integration across analog and MEMS fabrication to sustain pricing power in industrial temperature sensing. TE Connectivity Ltd. anchors automotive and aerospace channel relationships through specialized pressure and proximity sensor portfolios. Honeywell International Inc. dominates building automation and environmental monitoring applications with hardened sensor platforms certified for critical infrastructure.
United States sensors are transducer devices that convert physical phenomena—temperature, pressure, light, displacement, or electromagnetic fields—into measurable electrical signals, typically operating across ranges from millivolt outputs to digital protocols with precision thresholds measured in fractions of a degree or pascal. These devices serve as the foundational input layer for closed-loop control systems in automated manufacturing, vehicle safety networks, and connected healthcare diagnostics. Temperature and pressure sensors occupy mature, high-volume positions where margin compression forces suppliers toward value-added packaging and calibration services. Image sensors and MEMS-based proximity devices represent faster-expanding revenue pools as automotive ADAS deployment and smart manufacturing adoption deepen sensor density per system. Optical sensing technology captures premium positioning in medical imaging and precision agriculture where wavelength specificity determines performance.
FDA device regulations, NHTSA automotive safety mandates, and EPA emissions monitoring standards collectively shape sensor accuracy requirements, calibration protocols, and product liability exposure across healthcare, transportation, and environmental end markets. The CHIPS and Science Act funding streams are conditioning market access on domestic wafer fabrication content, pressuring foreign-headquartered suppliers to qualify US-based foundry partnerships. Stakeholders must monitor how BIS export control expansions on advanced semiconductor manufacturing equipment affect MEMS and photonics process technology availability for defense-adjacent sensor programs.
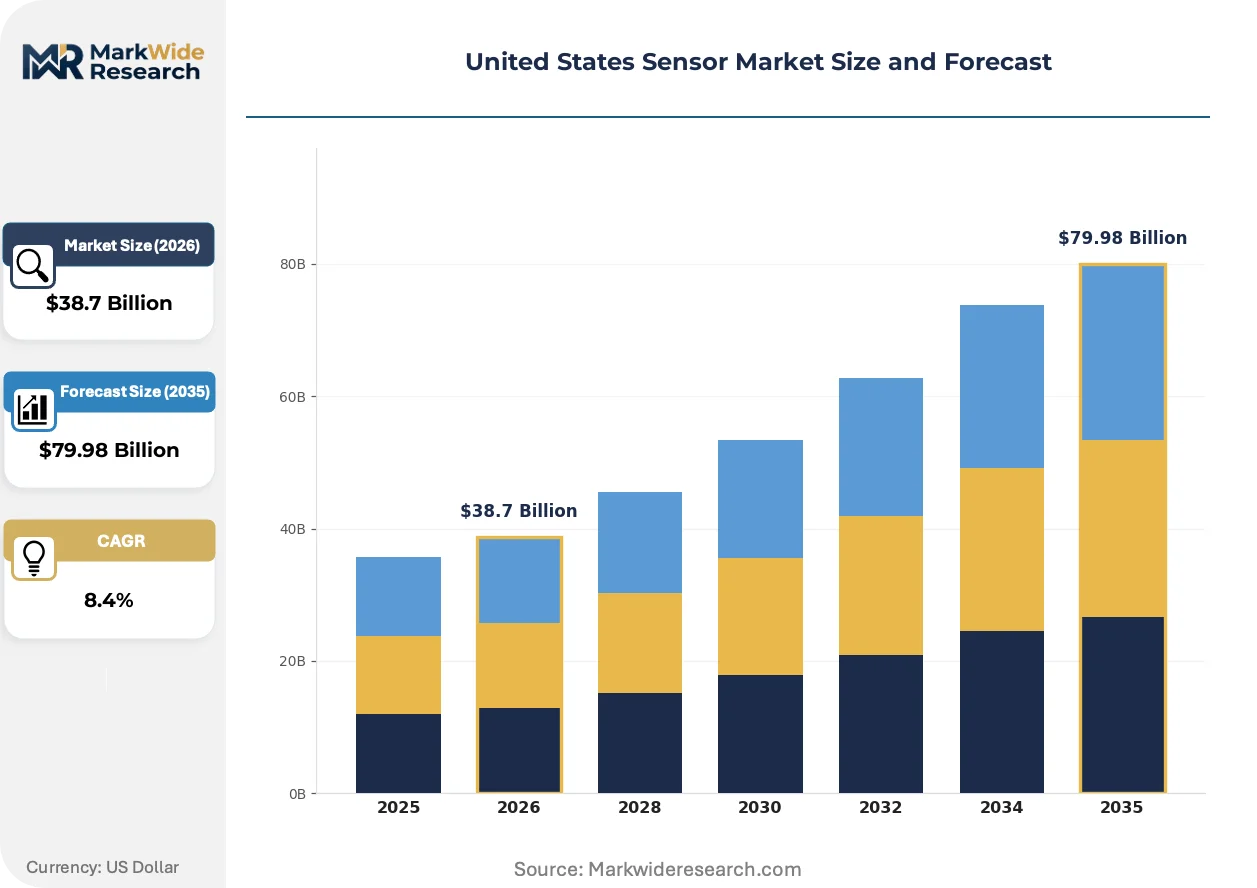
Market Dynamics
Automotive electrification programs are restructuring procurement priorities across the United States sensor market, with OEMs accelerating specifications for pressure and image sensors while CHIPS Act incentives reshape domestic fabrication capacity for MEMS and optical elements.
Growth Catalysts
- CHIPS and Science Act funding:Federal capital subsidies are conditioning market access on domestic wafer fabrication content, pressuring foreign-headquartered suppliers to qualify US-based foundry partnerships for MEMS and photonics programs.
- NHTSA automotive safety mandates:Advanced driver-assistance system requirements are expanding sensor density per vehicle platform, particularly for proximity and pressure devices in braking and collision-avoidance architectures.
- Texas manufacturing clusters:Concentrated aerospace and automotive production around Dallas-Fort Worth and Austin anchors consumption of hardened temperature and pressure sensors for industrial automation.
Market Restraints
- Photonics and MEMS talent scarcity:Engineering workforce gaps are bifurcating the market into capital-rich incumbents with captive fabrication and mid-tier players dependent on external foundries.
- EPA emissions monitoring standards:Calibration protocol complexity and product liability exposure are elevating compliance costs for environmental sensing applications in industrial settings.
- Optical sensor input concentration:Specialty wavelength-specific materials and precision optical substrates face concentrated supply from limited qualified vendors, creating vulnerability to disruption.
Strategic Opportunities
- Precision agriculture expansion:Wavelength-specific optical sensing technology captures premium positioning in crop monitoring and soil analysis applications across California's Central Valley and Midwest grain belts.
- Smart manufacturing adoption:Industrial IoT deployments are deepening sensor density per automated system, creating demand for multi-protocol temperature and displacement devices in Michigan automotive plants.
- FDA device regulation pathways:Connected healthcare diagnostics are opening revenue pools for calibrated sensor platforms certified for critical infrastructure and remote patient monitoring.
Industry Challenges
- MEMS process technology availability:BIS export control expansions on advanced semiconductor manufacturing equipment are constraining defense-adjacent sensor program qualification timelines.
- Calibration service scaling:Margin compression in mature temperature and pressure segments is forcing suppliers to build value-added packaging and certification capabilities without proportional revenue recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Sensor Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Image Sensors Technology: Analog, Digital, MEMS, Optical End User: Automotive, Consumer Electronics, Healthcare, Industrial Automation Application: Home Automation, Wearable Devices, Smart Manufacturing, Environmental Monitoring |
| Companies Covered | Texas Instruments Incorporated, TE Connectivity Ltd., Honeywell International Inc., Analog Devices Inc., Omega Engineering Inc., Rockwell Automation Inc., Infineon Technologies AG, STMicroelectronics, Emerson Electric Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Sensor Market Trends and Innovations
Silicon carbide and gallium nitride material platforms are actively reshaping temperature and power sensing architectures, while federal industrial policy accelerates domestic foundry qualification timelines.
Optical coherence tomography and structured-light 3D sensing is supplanting conventional contact-based measurement in precision manufacturing and medical imaging applications. Automotive OEMs in Michigan and California are specifying these platforms for assembly-line quality control and in-cabin occupant monitoring. The shift is compressing margins for legacy resistive and capacitive displacement sensors while opening premium positioning for wavelength-calibrated photonic devices.
FDA device regulations and NHTSA automotive safety mandates are tightening accuracy requirements and calibration protocols across healthcare and transportation end markets. Product liability exposure is elevating documentation burdens for sensor suppliers serving critical infrastructure. California and Texas medical device clusters are responding by vertically integrating testing laboratories to compress certification cycle times.
Automotive OEM procurement teams are consolidating vendor relationships and demanding multi-year sensor supply agreements with embedded calibration services. Tier-1 suppliers in Detroit and Austin are displacing spot-market component purchasing with integrated subsystem sourcing that bundles sensing, processing, and connectivity. The pattern is most visible in electric vehicle battery management systems, where pressure and temperature sensor integration determines thermal runaway detection performance.
United States Sensor Market Segmentation
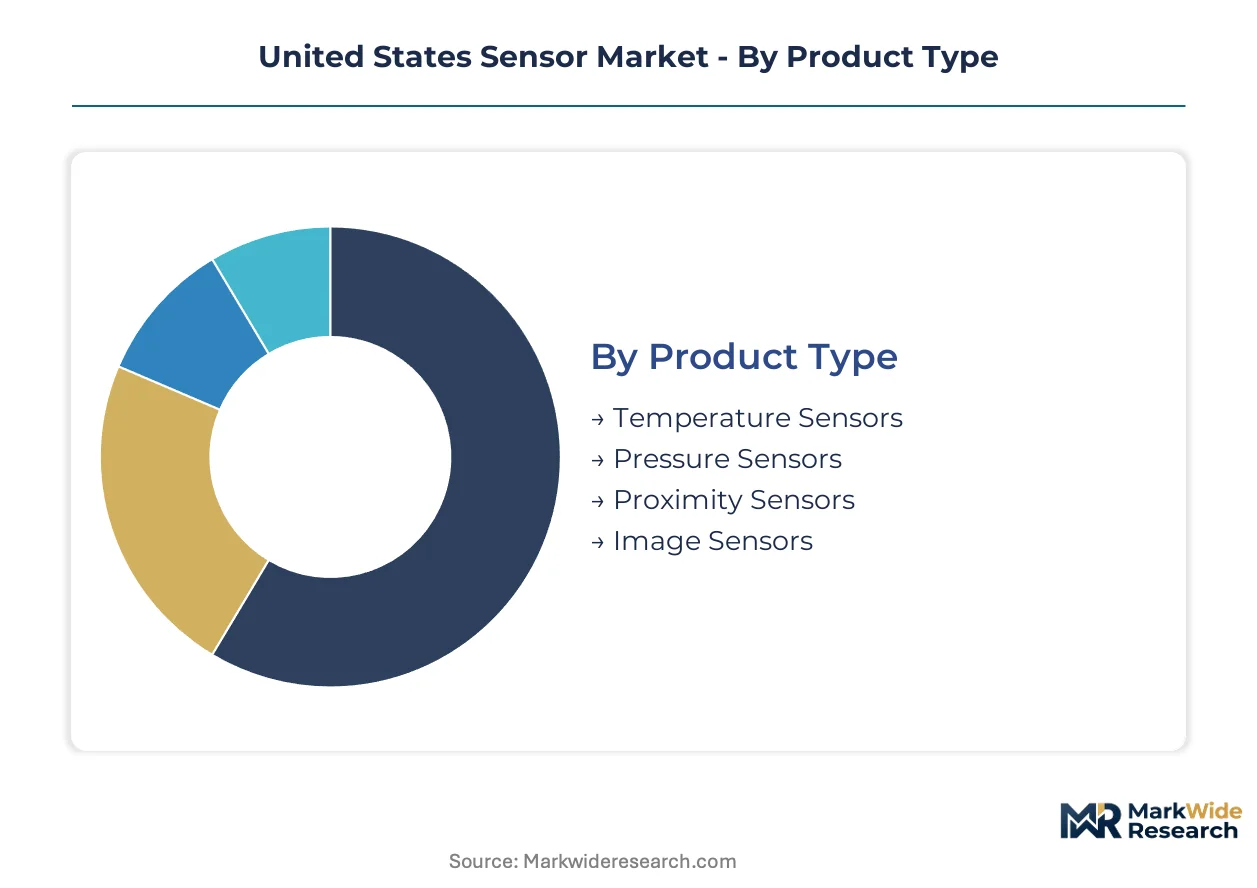
Sensor procurement patterns across the United States diverge sharply by end-use sophistication, with automotive and healthcare buyers demanding calibrated multi-sensor subsystems while industrial and consumer segments prioritize cost-optimized discrete components. Understanding these channel dynamics enables suppliers to align fabrication investments with margin profiles.
Product Type:
Temperature and pressure sensors flow through established distribution networks serving Detroit automotive clusters and Gulf Coast petrochemical corridors, while image and proximity devices route through specialized integrators supporting California ADAS development and Texas aerospace programs.
- Temperature Sensors:Thermocouple, RTD, and thermistor configurations span millivolt-to-digital output ranges with precision thresholds measured in fractions of a degree. Demand concentrates in Michigan automotive thermal management systems and Texas industrial process control, where EPA emissions monitoring standards elevate calibration documentation burdens.
- Pressure Sensors:Piezoresistive and capacitive transducers convert mechanical strain into measurable electrical signals across pascal-to-megapascal ranges. Automotive electrification programs in California and Michigan are accelerating procurement for battery thermal runaway detection and HVAC optimization.
- Proximity Sensors:Inductive and capacitive variants serve position detection in automated assembly lines. Industrial IoT deployments across Ohio and Illinois manufacturing belts are deepening sensor density per production cell.
- Image Sensors:CMOS and CCD architectures capture wavelength-specific data for machine vision and medical imaging. FDA device regulations and NHTSA automotive safety mandates are tightening accuracy requirements for California medical device and Michigan ADAS applications.
By volume, Temperature Sensors leads. By growth pace, Image Sensors is expanding most quickly.
Technology:
Cost tier differentiation separates mature analog implementations in price-sensitive industrial segments from premium digital and optical platforms commanding certification premiums in healthcare and aerospace channels.
- Analog:Voltage and current output signals dominate legacy industrial installations where retrofit economics favor compatibility over performance upgrades. Midwest manufacturing corridors retain substantial installed base.
- Digital:I2C, SPI, and CAN protocol interfaces enable direct microcontroller integration. Smart manufacturing adoption in Michigan and Texas is displacing analog architectures in new greenfield deployments.
- MEMS:Micro-electromechanical systems miniaturize mechanical sensing elements onto silicon substrates. CHIPS Act incentives are conditioning market access on domestic wafer fabrication content for defense-adjacent programs.
- Optical:Photonic transduction exploits wavelength specificity for precision measurement. Medical imaging clusters in California and Minnesota are capturing premium positioning through vertically integrated testing laboratories.
Analog retains the largest installed footprint. Optical platforms are climbing the fastest.
End User:
Customer type determines procurement modality, with automotive OEMs demanding multi-year supply agreements and healthcare buyers requiring FDA-cleared calibration chains while industrial and consumer segments tolerate spot-market purchasing.
- Automotive:OEM procurement teams are consolidating vendor relationships around integrated subsystem sourcing. Electric vehicle battery management systems in Michigan and California are specifying pressure and temperature sensor bundles with embedded thermal runaway detection.
- Consumer Electronics:High-volume, low-margin procurement favors MEMS miniaturization and multi-function integration. Wearable device manufacturers in California's Bay Area are driving proximity and image sensor consolidation into single-package solutions.
- Healthcare:Connected diagnostics and remote patient monitoring require calibrated sensor platforms certified for critical infrastructure. FDA device regulations are elevating documentation burdens for suppliers serving Minnesota and Massachusetts medical device clusters.
- Industrial Automation:Hardened sensor platforms for environmental monitoring and process control must satisfy OSHA safety mandates. Texas and Louisiana petrochemical corridors anchor consumption of explosion-proof temperature and pressure devices.
Industrial Automation holds the broadest segment footprint. Healthcare is gaining share fastest.
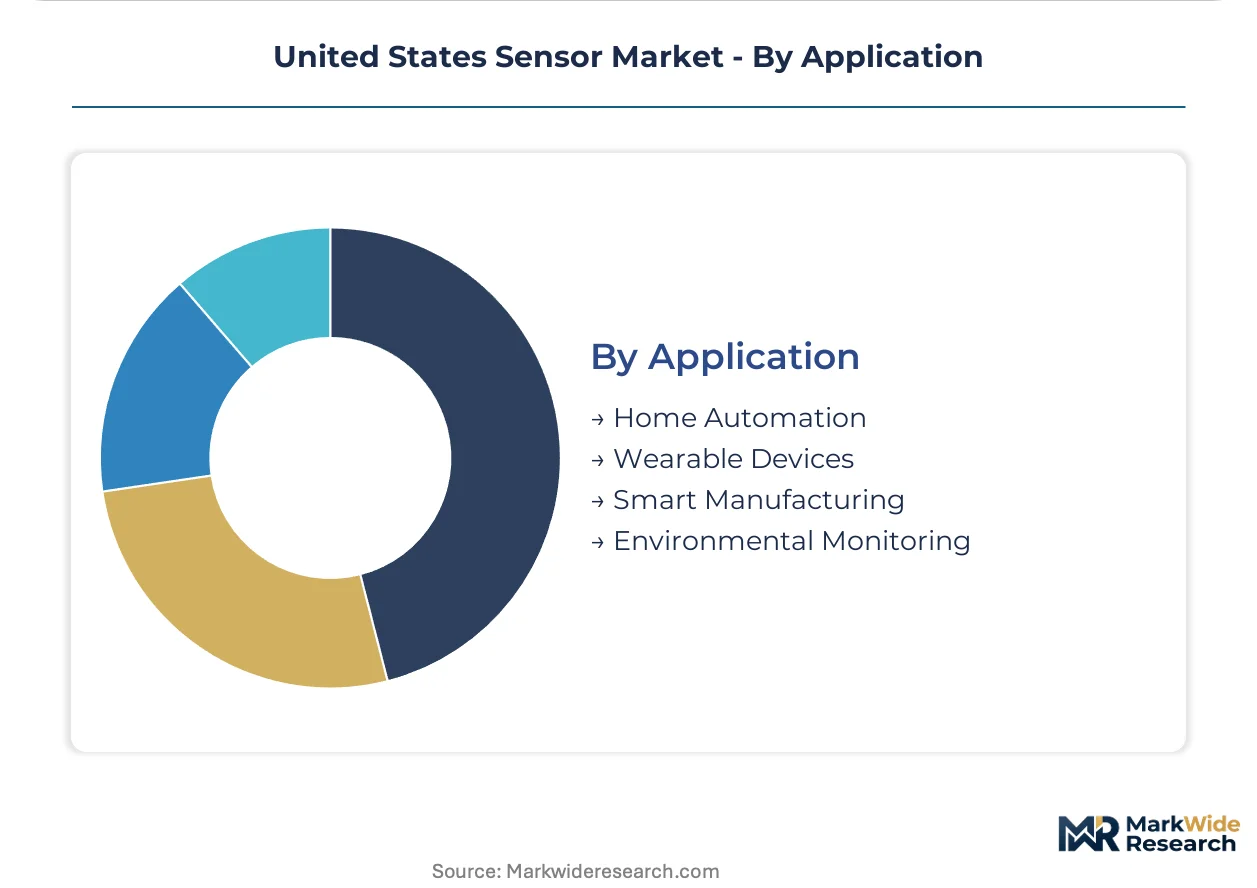
Application:
Application maturity varies from established home automation protocols to emerging environmental monitoring networks, with smart manufacturing representing the intermediate growth stage where sensor density expansion is most pronounced.
- Home Automation:Temperature, humidity, and occupancy sensors enable climate and lighting control through wireless mesh networks. Mass-market retail channels dominate distribution.
- Wearable Devices:Biometric monitoring exploits miniaturized optical and MEMS platforms for heart rate, blood oxygen, and motion tracking. California consumer electronics clusters are driving form-factor innovation.
- Smart Manufacturing:Industrial IoT deployments deepen sensor density per automated system. Michigan automotive plants are specifying multi-protocol temperature and displacement devices for predictive maintenance architectures.
- Environmental Monitoring:EPA emissions monitoring standards are elevating compliance costs for industrial sensing applications. Precision agriculture expansion across California's Central Valley and Midwest grain belts is capturing premium positioning for wavelength-specific optical technology.
Home Automation leads by unit volume. Environmental Monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA automotive safety mandates and CHIPS Act incentives anchor demand concentration across multiple US sub-regions. State-level industrial policies and cluster specialization create distinct procurement patterns for temperature, pressure, and optical sensing platforms.
California
ADAS development and medical imaging clusters drive specification intensity for image sensors and wavelength-calibrated photonic devices. FDA device regulations tighten accuracy requirements for Silicon Valley and San Diego medical device manufacturers. Precision agriculture expansion across the Central Valley captures premium positioning for optical sensing in crop monitoring applications.
Texas
Aerospace production around Dallas-Fort Worth and Austin anchors consumption of hardened temperature and pressure sensors for industrial automation. EPA emissions monitoring standards elevate calibration documentation burdens for Gulf Coast petrochemical corridors. CHIPS Act funding streams accelerate domestic foundry qualification timelines for MEMS fabrication in the state.
Michigan
Automotive electrification programs in Detroit accelerate procurement for battery thermal runaway detection and HVAC optimization systems. OSHA safety mandates govern hardened sensor deployment in manufacturing environments. Smart manufacturing adoption across automotive plants deepens sensor density per production cell for predictive maintenance architectures.
Massachusetts
Connected healthcare diagnostics and remote patient monitoring require calibrated sensor platforms certified for critical infrastructure. FDA device regulations elevate documentation burdens for suppliers serving Boston-area medical device clusters. Research institutions drive specification intensity for precision measurement in biotechnology applications.
Illinois
Industrial IoT deployments across manufacturing belts deepen sensor density per automated system. OSHA safety mandates govern explosion-proof temperature and pressure devices in process industries. Midwest grain belt precision agriculture creates secondary demand for wavelength-specific optical technology in soil analysis applications.
United States Sensor Market Competitive Landscape
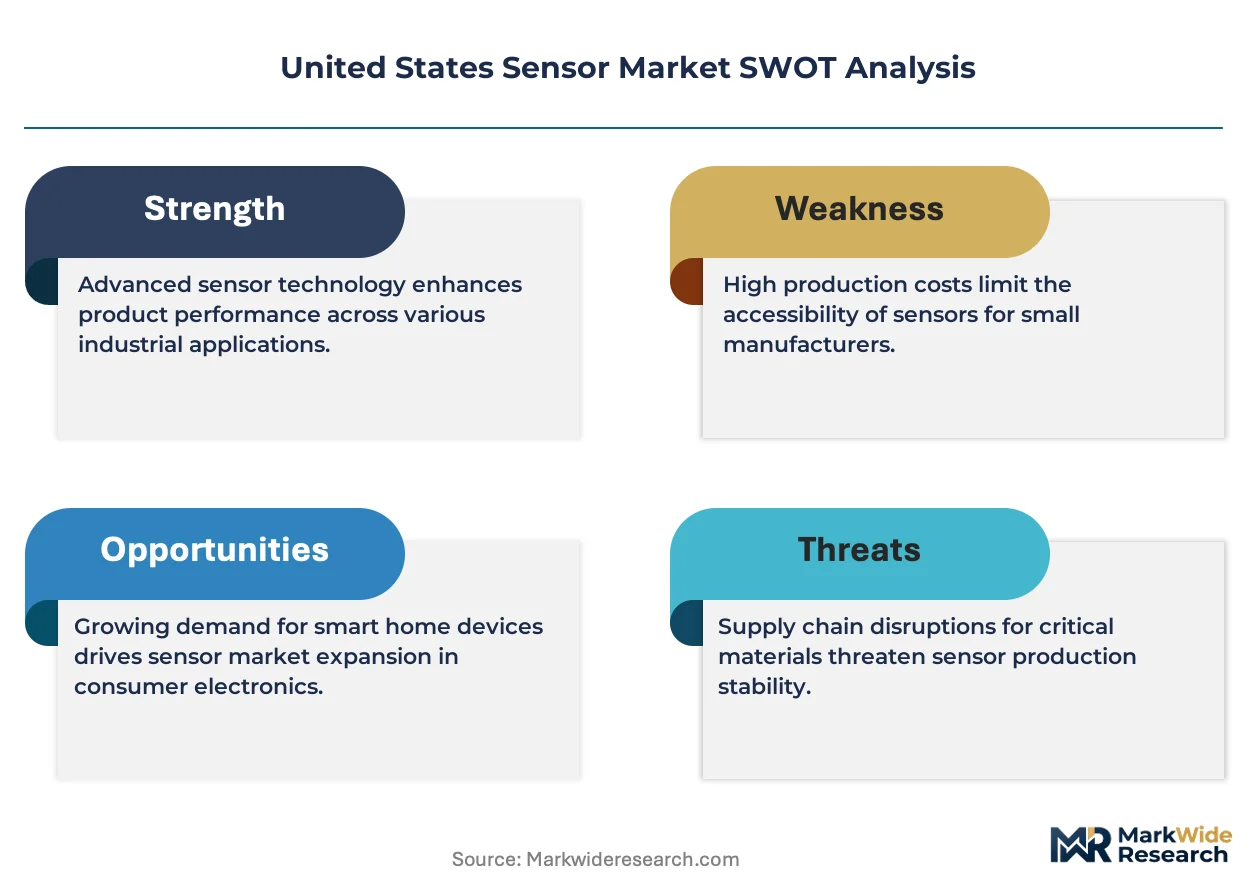
A small set of integrated leaders sits above a broader specialist tier, with capital-rich incumbents maintaining captive fabrication while mid-tier players rely on external foundries. The market structure rewards backward integration into MEMS and analog fabrication, particularly for suppliers serving automotive and aerospace channels with multi-year supply agreements. Three archetypes dominate: vertically integrated semiconductor conglomerates, specialized connectivity and automation vendors, and diversified industrial technology holding companies. Competitive moves concentrate on strategic partnerships with domestic foundries to satisfy CHIPS Act content requirements, and portfolio diversification into calibrated multi-sensor subsystems for electric vehicle battery management.
Within the integrated semiconductor tier, Texas Instruments Incorporated and Analog Devices Inc. exemplify archetypes that combine analog fabrication with MEMS process capabilities. TE Connectivity Ltd. anchors the specialized connectivity vector, representing vendors that channel pressure and proximity devices through automotive and aerospace relationships. Honeywell International Inc. occupies a diversified industrial technology position, with Emerson Electric Co. and Rockwell Automation Inc. sitting within the automation-focused specialist tier serving process industries and smart manufacturing deployments.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| TE Connectivity Ltd. |
| Honeywell International Inc. |
| Analog Devices Inc. |
| Omega Engineering Inc. |
| Rockwell Automation Inc. |
| Infineon Technologies AG |
| STMicroelectronics |
| Emerson Electric Co. |
| Others |
Pricing and Supply Chain Analysis
Multi-year supply agreements with embedded calibration services lock in both foundry access and cost visibility for automotive OEM procurement teams serving Michigan and California electric vehicle programs. CHIPS Act domestic content requirements are conditioning these contract structures on US-based wafer fabrication, reshaping how suppliers negotiate volume commitments and price escalation clauses.
Pricing Analysis
Long-term offtake contracts dominate procurement between Tier-1 suppliers and automotive OEMs, displacing spot-market purchasing for battery management system sensors. Price differentiation hinges on FDA certification tier for healthcare applications and volume scale for industrial temperature devices. Cost compression in mature analog segments is intensifying because margin pressure forces suppliers toward bundled calibration services without proportional revenue recovery. Industrial automation buyers exhibit highest price sensitivity, while aerospace and medical device procurement teams prioritize traceability documentation over unit cost.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for CMOS image sensor substrates, while US-based foundries in Texas and Arizona expand MEMS capacity under CHIPS Act incentives. Specialty optical materials and precision photonics substrates draw from concentrated qualified vendors in Germany and Japan. Single-source vulnerability for wavelength-specific substrates creates disruption exposure if export controls tighten on advanced semiconductor manufacturing equipment. Distribution runs through specialized integrators serving California ADAS development and authorized distributors for industrial process control corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM procurement consolidation around integrated subsystem sourcing has shifted bargaining power toward buyers demanding multi-sensor bundles with embedded services. Tier-1 suppliers now face margin compression unless they capture calibration and certification value-add.
For Market Incumbents: Consolidate backward integration into MEMS fabrication to satisfy CHIPS Act domestic content requirements and defend pricing power against foundry-dependent mid-tier competitors. Lock in multi-year supply agreements with Michigan and California automotive programs before qualification timelines lengthen. Prioritize certification laboratory investments to compress FDA device approval cycles for healthcare channel expansion. For New Entrants and Emerging Players: Calibration service scaling gaps in precision agriculture and environmental monitoring segments offer white-space entry points where incumbents under-invest. Target California Central Valley optical sensing applications where wavelength-specific expertise commands premium positioning. Pursue partnership-based go-to-market models with Texas-based domestic foundries to bypass capital-intensive fabrication buildout. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated sensor specialists with captive MEMS fabrication and established automotive qualification pathways. Long-term viability over the next decade rests on regulatory compliance infrastructure rather than discrete component manufacturing. Watch BIS export control expansion announcements as the critical inflection signal for defense-adjacent sensor program access.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Foundry Partnership | CHIPS Act compliance unlocks automotive OEM qualification pathways for MEMS suppliers. |
| Calibration Laboratory Buildout | FDA device regulations elevate documentation burdens that vertically integrated testing compresses. |
| Multi-Sensor Subsystem Integration | Battery thermal runaway detection bundles capture procurement consolidation in electric vehicle platforms. |
| Precision Agriculture Channel Development | Wavelength-specific optical sensing captures premium positioning in California Central Valley crop monitoring. |
| Defense Program Qualification | BIS export controls constrain MEMS process technology availability for hardened aerospace applications. |
Research Methodology
A spread of perspectives from automotive OEM procurement directors, MEMS fabrication engineers, FDA regulatory consultants, and industrial IoT deployment managers converged on the working assumptions for sensor demand trajectories. Primary fieldwork combined structured interviews with Tier-1 supplier executives and biomedical device engineers with secondary validation against SEC 10-K filings, NHTSA safety mandate documentation, and EPA emissions monitoring standards. Bottom-up unit demand modeling across temperature, pressure, and image sensor categories triangulated against top-down market size estimates from trade association data and customs import records.
Segmentation dimensions modeled include sensor product type, transduction technology, end-user industry, and application maturity across the projection horizon. CAGRs were derived from weighted average growth assumptions applied to volume and value outputs. Industry-specific forecast inputs incorporated electric vehicle battery management system sensor density specifications and precision agriculture optical sensing adoption curves from USDA grant program disclosures.
Material uncertainties — BIS export control expansion scope, CHIPS Act funding disbursement timing, and FDA device regulation pathway revisions — sit outside the modeled envelope. Forecasts reflect assumptions about domestic foundry qualification timelines and automotive electrification program acceleration. Recalibration cycles align with material shifts in federal industrial policy implementation and NHTSA safety mandate enforcement schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Laser Sensor Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Europe Air Purifier Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
Asia Pacific Industrial Sensors Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Industrial Combustion Control Components and Systems Market
Sensors and Controls
Wireless Ph Monitoring Systems Market