
 Fingerprint Module Market | 2026-2036
Fingerprint Module Market Size, Share, and Industry Trends Forecast 2026-2036
Fingerprint Module Market Intelligence
The General Data Protection Regulation (GDPR) in Europe, alongside data privacy mandates in India and Brazil, is rebalancing the cost-of-entry calculus for biometric data handlers. This regulatory pressure elevates compliance costs for new entrants. Qualcomm Technologies Inc. leverages its deep integration within the mobile chipset ecosystem to offer bundled solutions. Shenzhen Goodix Technology Co., Ltd. dominates the high-volume smartphone market through economies of scale, while Fingerprint Cards AB specializes in systems for access control.
A fingerprint module is an integrated hardware component that captures and processes a fingerprint image for biometric authentication, often at resolutions above 500 DPI. Its primary purpose is to provide secure access to devices, replacing or augmenting traditional passwords. Capacitive sensors represent the largest product type segment due to their cost-effectiveness, while ultrasonic sensors are penetrating the premium smartphone market. Although smartphones drive volume, access control systems and banking terminals offer higher-margin applications.
Frameworks like the EU's GDPR and standards from the FIDO Alliance dictate product design and data management protocols. National bodies such as the US National Institute of Standards and Technology (NIST) and the Bureau of Indian Standards (BIS) set performance criteria for modules in government applications. These rules mandate specific security and accuracy levels for market access. Vendors must navigate this complex regulatory environment while managing the technology shift to advanced under-display solutions.
Market Dynamics
The central dynamic shaping the Fingerprint Module Market is the tension between the commoditization pressure from high-volume consumer electronics and the rising cost of compliance driven by stringent data privacy regulations like the GDPR. This forces vendors to balance economies of scale against the specialized, high-margin requirements of secure applications.
Growth Catalysts
- FIDO Alliance Standards:The promotion of FIDO (Fast Identity Online) standards is creating a common framework for strong authentication, reducing interoperability friction and encouraging broader adoption of fingerprint modules across web services and enterprise applications.
- Government Digital Identity Programs:National identification projects, such as India's Aadhaar system, require the large-scale deployment of biometric hardware for enrollment and verification, creating substantial, government-backed volume demand for certified fingerprint modules.
- Automotive Integration:The automotive industry's push for vehicle personalization and enhanced security is driving the integration of fingerprint sensors for functions like driver profile loading, ignition start, and in-car payment authorization.
Market Restraints
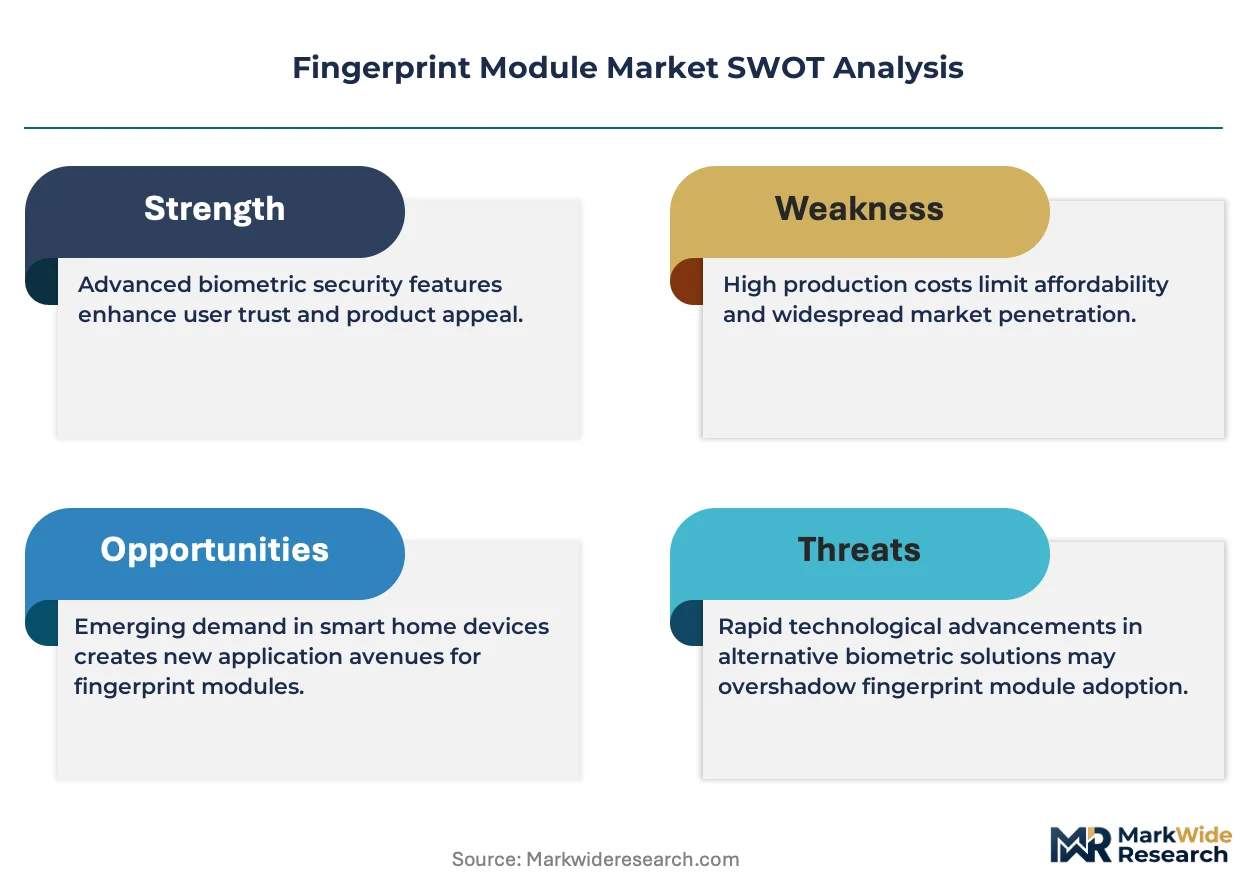
- Alternative Biometric Modalities:The rapid improvement and integration of facial recognition technology, particularly in premium smartphones and access control systems, presents a significant substitution threat to fingerprint-based authentication.
- Sensor Performance Limitations:Capacitive and optical sensors can struggle with accuracy when users have wet, dirty, or worn fingerprints, limiting their reliability in industrial, healthcare, or outdoor environments without significant software compensation.
- High R&D Investment:Developing next-generation technologies like under-display ultrasonic or optical sensors requires substantial and sustained capital investment, creating a high barrier to entry for smaller companies and concentrating innovation among a few large vendors.
Strategic Opportunities
- Biometric Payment Cards:The financial sector offers a high-margin opportunity through the development of payment cards with integrated fingerprint sensors, enhancing transaction security and aligning with the global shift towards contactless payments.
- Enterprise and IoT Security:Expanding beyond personal devices into enterprise-level access control, time and attendance systems, and securing IoT endpoints in smart buildings represents a significant avenue for growth in higher-value B2B markets.
- Healthcare Patient Identification:Integrating fingerprint modules into healthcare systems in North America and Europe can reduce medical errors by accurately identifying patients, linking them to their electronic health records, and controlling access to sensitive data.
Industry Challenges
- Regulatory Fragmentation:Vendors face the challenge of navigating a complex and divergent set of data protection laws, including Europe's GDPR and specific mandates in Brazil and India, which imposes varying requirements for data handling and consent.
- Under-Display Integration Yields:Achieving high manufacturing yields for under-display fingerprint sensors remains a technical hurdle, as integration with OLED panels is complex and can be affected by display material variations, impacting production costs.
- Intellectual Property Complexity:The market is characterized by dense patent thickets, particularly around capacitive and optical sensing technologies, leading to frequent litigation and the need for costly cross-licensing agreements among competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fingerprint Module Market |
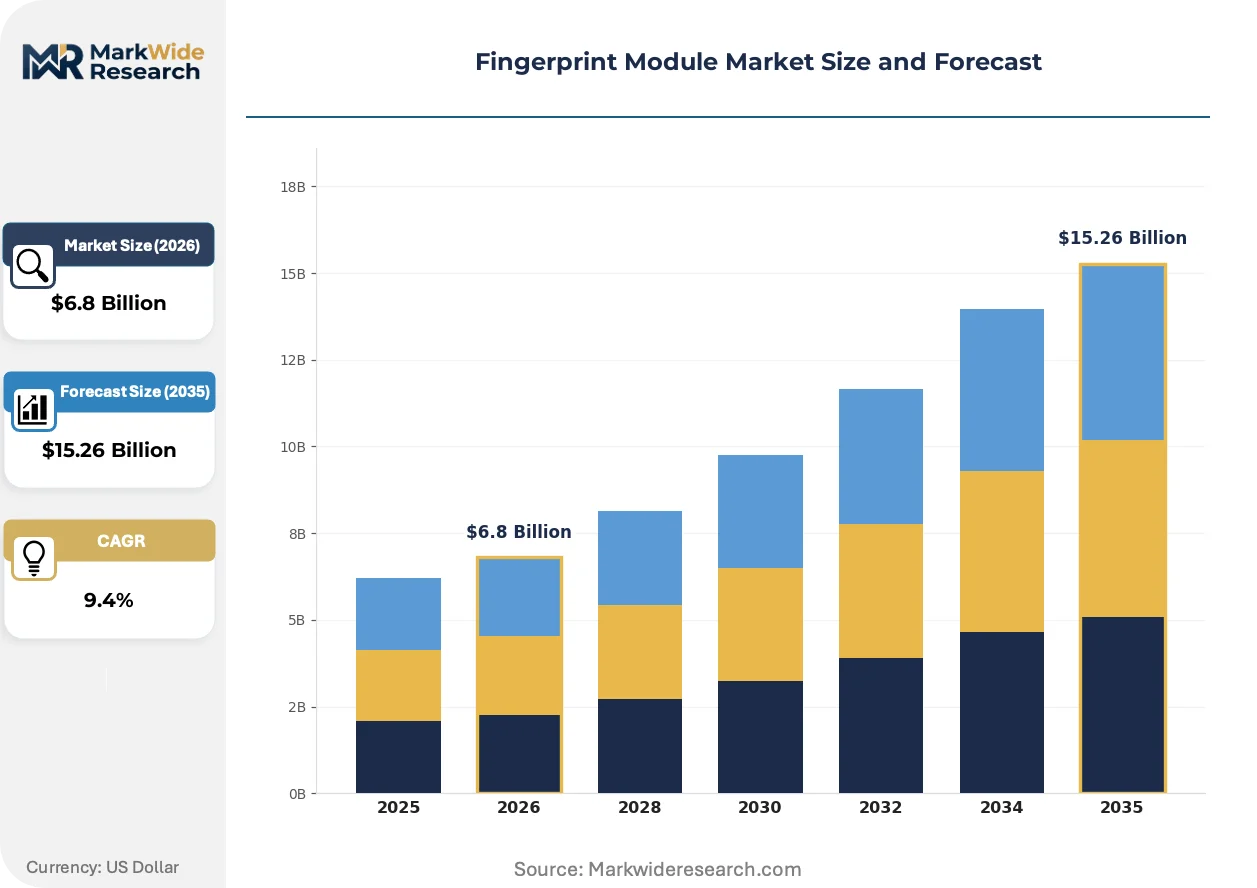
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, Capacitive, Ultrasonic, Thermal, Pressure-Based Technology: Touch, Swipe, Area, 3D Imaging, Multispectral Application: Smartphones, Laptops, Access Control Systems, Time & Attendance, Banking Terminals End User: Consumer Electronics Manufacturers, Security Firms, Enterprise Corporations, Financial Institutions, Government Agencies |
| Companies Covered | Qualcomm Technologies Inc., Egis Technology Inc., Synaptics Incorporated, IDEX Biometrics ASA, Suprema Inc., Shenzhen Goodix Technology Co., Ltd., HID Global Corporation, SecuGen Corporation, Fingerprint Cards AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fingerprint Module Market Strategic Shifts & Innovations
The market's evolution is defined by the drive toward seamless integration and enhanced functionality. Fingerprint modules are transitioning from standalone components to invisible, multifunctional sensors embedded within other materials, primarily driven by the design demands of the consumer electronics industry.
Ultrasonic sensing is a key technological advance that uses sound waves to capture a detailed, three-dimensional image of a fingerprint's ridges and valleys. This technology is being rapidly adopted by manufacturers of premium smartphones due to its enhanced security and ability to function through glass or metal. Ultrasonic technology is expanding into automotive and secure access applications, challenging the cost-performance leadership of traditional capacitive sensors.
Regulations like the EU's forthcoming AI Act are poised to classify biometric identification systems based on risk level, directly influencing product development. This legislation will likely mandate rigorous testing, transparency in operation, and data governance protocols for high-risk applications. Module manufacturers supplying government, law enforcement, and critical infrastructure sectors will face the most significant impact, needing to re-engineer products for compliance.
A notable behavioral shift is occurring in enterprise procurement, with a move away from one-time hardware purchases toward subscription-based Biometrics-as-a-Service (BaaS) models. This trend disrupts traditional hardware sales channels by bundling sensor deployment with ongoing identity management and cloud-based software updates. The shift is most visible in the corporate security and financial services verticals in North America and Europe, where buyers prefer predictable operating expenses.
Fingerprint Module Market Segmentation
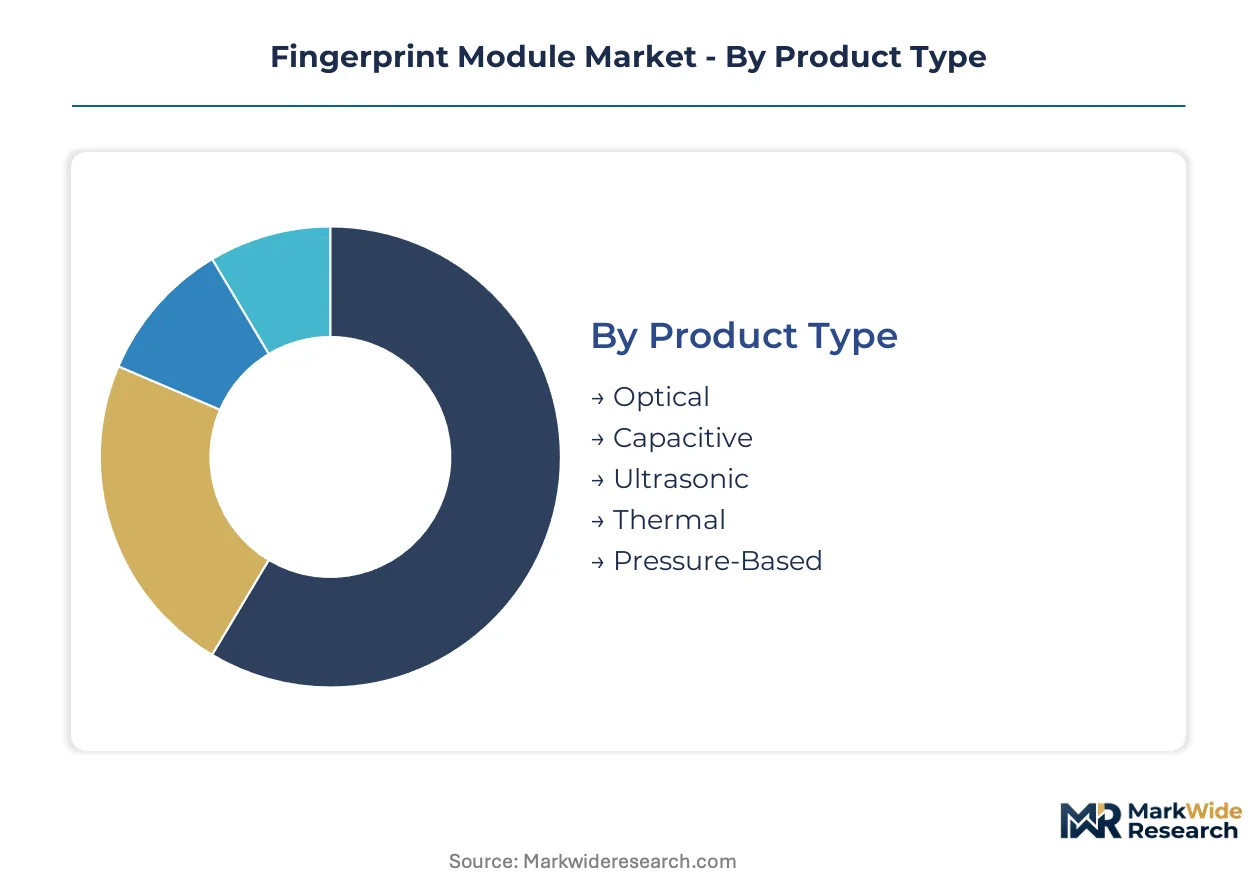
The Fingerprint Module Market segments by product type, technology, application, and end user, reflecting diverse operational requirements and commercial priorities. Understanding these distinctions helps vendors align product development with specific demand patterns and regulatory landscapes across various industries.
Product Type:
Product type segmentation reveals the tension between cost-effective volume solutions and premium offerings with enhanced performance. Capacitive sensors dominate the mass market, while ultrasonic technology gains traction in high-end applications.
- Capacitive:These sensors detect fingerprint ridge patterns by measuring electrical capacitance variations, offering a cost-effective solution for high-volume consumer electronics. Demand concentrates in smartphone manufacturing hubs like China, driven by their widespread integration into mid-range devices.
- Ultrasonic:Utilizing sound waves to create detailed 3D maps of fingerprints, ultrasonic sensors provide superior security and can operate through various materials like glass. This technology penetrates the premium smartphone market in regions like North America, valued for its enhanced accuracy and durability.
- Optical:Optical sensors use light to capture a 2D image of the fingerprint, commonly found in access control systems and older smartphone models.
- Thermal:Thermal sensors detect temperature differences between ridges and valleys, making them effective for detecting live fingers and resisting spoofing attempts.
- Pressure-Based:These sensors measure the pressure applied by a finger to create an image, suitable for specific industrial or ruggedized applications.
Today's leader: Capacitive. Tomorrow's challenger: Ultrasonic.
Technology:
Technological differentiation drives adoption across diverse use cases, from basic access to advanced identity verification. Area sensors provide convenience for consumer devices, while 3D imaging enhances security for critical infrastructure.
- Area:Area sensors capture the entire fingerprint in a single touch, offering quick and convenient authentication widely adopted in modern smartphones. This technology is prevalent in consumer devices across Europe and Asia, where user experience is paramount.
- 3D Imaging:These advanced technologies create a volumetric representation of the fingerprint, significantly improving security against spoofing and enabling more robust authentication. Demand for 3D imaging expands into government and financial applications in the US, requiring high assurance levels.
- Touch:Touch-based technology requires a user to place their finger on a sensor for image capture, a standard method for many devices.
- Swipe:Swipe sensors require the user to drag their finger across a narrow strip, often used in space-constrained devices like older laptops or peripherals.
- Multispectral:Multispectral imaging captures both surface and subsurface fingerprint data, enhancing performance in challenging conditions such as wet or dirty fingers.
Innovation in 3D Imaging drives market expansion, while Multispectral secures niche applications.
Application:
Application segments highlight where fingerprint modules provide value, ranging from consumer convenience to high-security enterprise solutions. Smartphones represent the largest volume, while access control systems offer higher margin opportunities.
- Smartphones:Fingerprint modules provide quick and secure user authentication for unlocking devices, authorizing payments, and accessing applications on mobile phones. The sheer volume of smartphone production, particularly in Asian manufacturing hubs, makes this segment a primary market driver.
- Access Control Systems:These systems integrate fingerprint modules for secure entry to buildings, restricted areas, and data centers, enhancing physical and logical security. Enterprise corporations in North America and Europe increasingly deploy these systems for employee authentication and compliance.
- Laptops:Integrated fingerprint sensors offer biometric login and data protection for personal computers, streamlining user access.
- Time & Attendance:Fingerprint modules accurately record employee work hours, preventing "buddy punching" and improving workforce management efficiency in industrial settings.
- Banking Terminals:Fingerprint authentication secures transactions and identifies users at ATMs and point-of-sale systems, reducing fraud in financial services.
The largest volume originates from Smartphones, with Access Control Systems offering significant revenue opportunities.
End User:
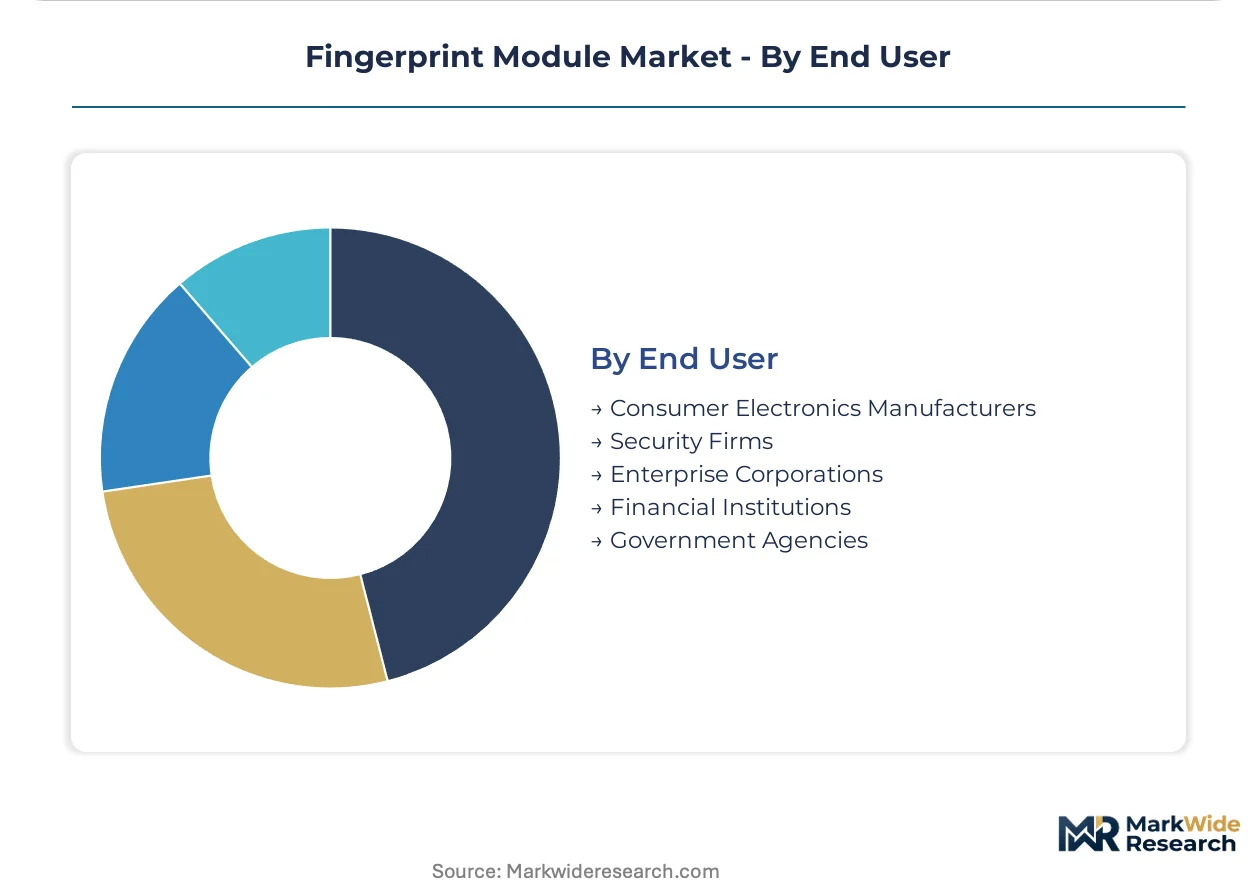
End-user segmentation reveals distinct purchasing behaviors and regulatory influences shaping product design. Consumer electronics manufacturers prioritize cost and integration, while government agencies demand stringent security and compliance.
- Consumer Electronics Manufacturers:These companies integrate fingerprint modules into mass-market devices like smartphones, tablets, and wearables, driven by consumer demand for convenience and security features. Design priorities include cost-effectiveness, compact size, and seamless integration with device aesthetics.
- Government Agencies:Government bodies utilize fingerprint modules for national digital identity programs, law enforcement, and secure access to classified information. Compliance with national standards like those from the US National Institute of Standards and Technology (NIST) is a critical requirement.
- Security Firms:Security firms deploy fingerprint modules in their integrated security solutions for physical access control, surveillance, and identity management.
- Enterprise Corporations:Businesses use fingerprint modules for employee authentication, secure access to corporate networks, and time and attendance tracking within their operations.
- Financial Institutions:Banks and payment providers integrate fingerprint modules into payment cards, ATMs, and online banking platforms to enhance transaction security and user verification.
Demand from Consumer Electronics Manufacturers shapes the market's cost structure, as Government Agencies emphasize security protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fingerprint module industry initially scaled through early integration into consumer electronics, particularly smartphones. Manufacturing hubs like China became central to high-volume production, serving the global electronics supply chain. This foundation established the market's global footprint.
China
Demand for fingerprint modules in China centers on its vast smartphone manufacturing base and domestic consumer market. The government's GB standards influence product design for local applications. Shenzhen's electronics ecosystem drives innovation and mass production of capacitive sensors.
United States
Premium smartphone integration and enterprise security solutions drive demand for advanced fingerprint modules in the United States. NIST guidelines set performance criteria for government and critical infrastructure applications. Silicon Valley and other tech hubs foster research into under-display ultrasonic technology.
Germany
European access control systems and automotive integration create significant demand for fingerprint modules in Germany. The EU's GDPR mandates stringent data privacy protocols for biometric data handling. Munich and Stuttgart serve as centers for automotive and industrial automation, driving specialized sensor development.
India
National digital identity programs, like Aadhaar, generate substantial demand for certified fingerprint modules across India. The Bureau of Indian Standards (BIS) sets specific performance criteria for government applications. Bangalore's tech sector and other urban centers are expanding biometric integration for banking terminals.
South Korea
Advanced consumer electronics and smart device innovation propel demand for cutting-edge fingerprint modules in South Korea. The country's data protection laws influence biometric security features in locally produced devices. Seoul's technology firms lead in developing ultrasonic and under-display sensor solutions.
Fingerprint Module Market Key Industry Players
The competitive structure tilts toward a tiered landscape, with large semiconductor firms alongside specialized biometric technology providers. The market features highly consolidated segments, particularly for high-volume consumer electronics components. Strategic archetypes include integrated chipset providers, dedicated sensor manufacturers, and niche solution developers for secure applications. Companies frequently engage in strategic partnerships and technology licensing to expand market reach and accelerate innovation.
Within the integrated chipset provider archetype, Qualcomm Technologies Inc. leverages its ecosystem presence to offer bundled solutions. Shenzhen Goodix Technology Co., Ltd. exemplifies the scale-driven sensor manufacturer, dominating the high-volume smartphone market through cost-effectiveness. Fingerprint Cards AB, a Sweden-based AB, occupies a position as a specialized provider for access control and higher-margin applications. These players anchor different segments of the fingerprint module value chain, reflecting diverse market strategies from mass-market penetration to secure niche applications.
| Leading Market Players |
|---|
| Qualcomm Technologies Inc. |
| Egis Technology Inc. |
| Synaptics Incorporated |
| IDEX Biometrics ASA |
| Suprema Inc. |
| Shenzhen Goodix Technology Co., Ltd. |
| HID Global Corporation |
| SecuGen Corporation |
| Fingerprint Cards AB |
| Others |
Cost & Logistics Intelligence
The EU's forthcoming AI Act directly influences product development and qualified supply for high-risk fingerprint modules. This legislation mandates rigorous testing and data governance protocols, thereby affecting premium-tier pricing for compliant solutions.
Pricing Analysis
Per-unit transactional pricing dominates the fingerprint module market, particularly in high-volume consumer electronics. Pricing stratifies across premium, standard, and economy tiers, driven by sensor technology like ultrasonic versus capacitive, and certification levels such as NIST compliance. Cost compression in the mass-market segment stems from intense competition among consumer electronics manufacturers. Government agencies and financial institutions exhibit lower price sensitivity, prioritizing security and accuracy over cost.
Supply Chain Analysis
Direct-to-OEM channels facilitate high-volume sales to consumer electronics manufacturers, while specialized distributors serve niche markets. Geographic supply concentrates heavily in China, supporting its vast smartphone production, with advanced R&D hubs in the United States and South Korea. The supply chain relies on semiconductor components and specialized materials for ultrasonic sensors. Intellectual property complexity, characterized by dense patent thickets, presents a significant structural risk across the value chain.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fingerprint module market offers geographic arbitrage opportunities, leveraging lower manufacturing costs in Asian hubs against stringent data privacy regulations in Europe. This differential influences production location and market access strategies.
For Market Incumbents:Cement market leadership by deepening integration within mobile chipset ecosystems, leveraging established OEM relationships against facial recognition substitution. Invest aggressively in next-generation under-display ultrasonic technology to counter performance limitations of older sensors. Secure FIDO Alliance certifications to reinforce interoperability and maintain a competitive edge in enterprise applications. This approach defends against new entrants focused on niche segments.
For New Entrants and Emerging Players:Enter via high-margin applications like biometric payment cards within the financial services sector in Europe, where transaction security is paramount. Target healthcare patient identification systems in North America, addressing critical needs for medical error reduction. Focus on a Biometrics-as-a-Service (BaaS) model to bundle hardware with ongoing identity management, appealing to enterprise procurement shifts. This strategy avoids direct competition in commoditized smartphone segments.
For Investors and Strategic Acquirers:Roll-up economics work for specialized biometric technology providers because regulatory fragmentation creates distinct market demands. Seek acquisition targets with strong intellectual property in secure access control or biometric payment card solutions. The long-term viability favors entities capable of navigating complex compliance landscapes. Monitor the accelerating adoption rates of Biometrics-as-a-Service models as a key inflection indicator for scalable growth opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Under-display ultrasonic sensor | Captures premium smartphone market share for advanced consumer electronics manufacturers. |
| Strategic Partnership: FIDO Alliance integration | Improves interoperability and broadens adoption across web services for enterprise corporations. |
| Acquisition of Specialist Firm: Access control system provider | Expands into higher-margin B2B markets for integrated security firms. |
| Geographic Expansion: India's Aadhaar program | Taps into large-scale government-backed volume demand for national digital identity programs. |
| Green Certification Program: EU AI Act compliance | Ensures market access and premium pricing for high-risk government applications in Europe. |
Research Approach
Bottom-up smartphone end-use modeling reconciled against top-down sensor component supply-side tracking forms the analytical core of this study. Primary interviews with mobile chipset executives, security solution architects, and government procurement officers informed market dynamics. Secondary validation drew from SEC filings, FIDO Alliance reports, NIST and BIS standards, and global electronics trade statistics. This approach ensured comprehensive data triangulation.
Historical trendline analysis established foundational growth patterns across the analysis window. The analytical framework modeled product type, technology, application, end user, and regional regulatory compliance dimensions. Compound annual growth rates derived from historical performance and projected adoption rates. Key forecast inputs included global smartphone shipment forecasts and national digital identity program budgets.
Inputs from public company reports and industry consortiums were available through the study window; gaps in proprietary OEM production data introduce uncertainty bands. Forecasts reflect assumptions regarding technological adoption and regulatory stability. The pace of alternative biometric modality adoption and evolving regulatory interpretations present key risk factors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Piece-Level Inventory Tracking and Vision Systems Market
Sensors and Controls
RET Controller Market
Sensors and Controls
Air Pressure Sensor Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Magnetic Proximity Sensor Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Italy Digital Thermometer Market