
 Actigraphy Sensors Market | 2026-2036
Actigraphy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Actigraphy Sensors Market Analytics
Research institutions are rotating toward cloud-based actigraphy platforms as healthcare providers tighten capital budgets for bedside monitoring hardware. ActiGraph LLC dominates institutional procurement with validated devices that meet pharmaceutical trial protocols. Garmin Ltd competes in the fitness enthusiast channel with GPS-integrated wearables that extend activity tracking beyond sleep metrics. SOMNOmedics GmbH specializes in European sleep clinic installations, leveraging CE-marked bed sensor systems that anchor its regional presence.
Actigraphy sensors measure limb movement through accelerometer-based transducers, typically sampling tri-axial motion at 30-100 Hz to distinguish wake periods from sleep epochs via algorithmic scoring. These devices serve sleep medicine, psychiatry, and sports science by quantifying circadian rest-activity patterns outside laboratory polysomnography settings. Wrist wearables occupy the largest volume tier as consumer familiarity with bracelet form factors drives clinical acceptance, while machine learning integration represents the fastest-expanding technology layer as vendors deploy adaptive sleep staging algorithms that reduce manual scoring labor. Mobile app connectivity sits at the margin intersection where subscription revenue pools form around longitudinal data analytics.
FDA 510(k) clearance requirements and EU MDR Class IIa designation pressure manufacturers to generate clinical validation data before commercializing health-claim wearables. Japan's PMDA enforces similar substantiation for sleep disorder diagnostic aids, creating a convergent compliance burden across the three largest revenue territories. Stakeholders must monitor how FDA's evolving software-as-medical-device guidance applies to cloud-based actigraphy analytics that auto-update algorithms post-market.
Market Dynamics
Machine learning sleep staging is compressing manual scoring labor across pharmaceutical trials, while FDA software-as-medical-device guidance tightens compliance for cloud-based analytics platforms that auto-update algorithms post-market.
Growth Catalysts
- Decentralized Clinical Trial Mandates:Pharmaceutical sponsors are embedding wrist-worn actigraphy into remote patient monitoring protocols, eliminating site visits for circadian rhythm endpoints.
- EU MDR Class IIa Designation:European conformity requirements for sleep disorder diagnostic aids are elevating validation standards that favor institutional-grade devices over consumer trackers.
- Cloud Platform Migration:Research institutions are rotating capital expenditure away from bedside hardware toward subscription-based actigraphy analytics with longitudinal data warehousing.
Market Restraints
- Accelerometer Component Concentration:MEMS sensor supply chains cluster in East Asian foundries, exposing manufacturers to single-source fragility for tri-axial motion transducers.
- Polysomnography Substitution Ceiling:Gold-standard laboratory sleep studies retain diagnostic authority for complex apnea cases, capping actigraphy penetration in severe sleep disorder protocols.
- FDA 510(k) Validation Burden:Pre-market clinical evidence requirements for health-claim wearables extend development timelines and inflate regulatory compliance costs for algorithm-based devices.
Strategic Opportunities
- Psychiatry CNS Drug Development:Mood disorder and schizophrenia trials are adopting actigraphy for objective rest-activity biomarkers, expanding addressable trial volume beyond sleep medicine.
- Japan PMDA Sleep Diagnostic Pathway:Japanese reimbursement expansion for home-based sleep testing creates regulatory tailwind for CE-marked devices seeking Asian market entry.
- GPS-Integrated Wearable Convergence:Activity tracking fusion with location-based circadian rhythm analysis opens sports science applications for jet lag and athletic performance optimization.
Industry Challenges
- Algorithm Scoring Standardization:Absence of universal sleep-wake epoch classification protocols forces vendors to maintain multiple validation datasets for regional regulatory submissions.
- Legacy Polysomnography Integration:Hospital sleep centers require bidirectional data interoperability with existing EMR and PSG systems, complicating cloud-native actigraphy platform deployment.
- Biostatistician Talent Scarcity:Adaptive sleep staging model development demands specialized expertise in time-series signal processing and regulatory biostatistics that outpaces academic pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Actigraphy Sensors Market |
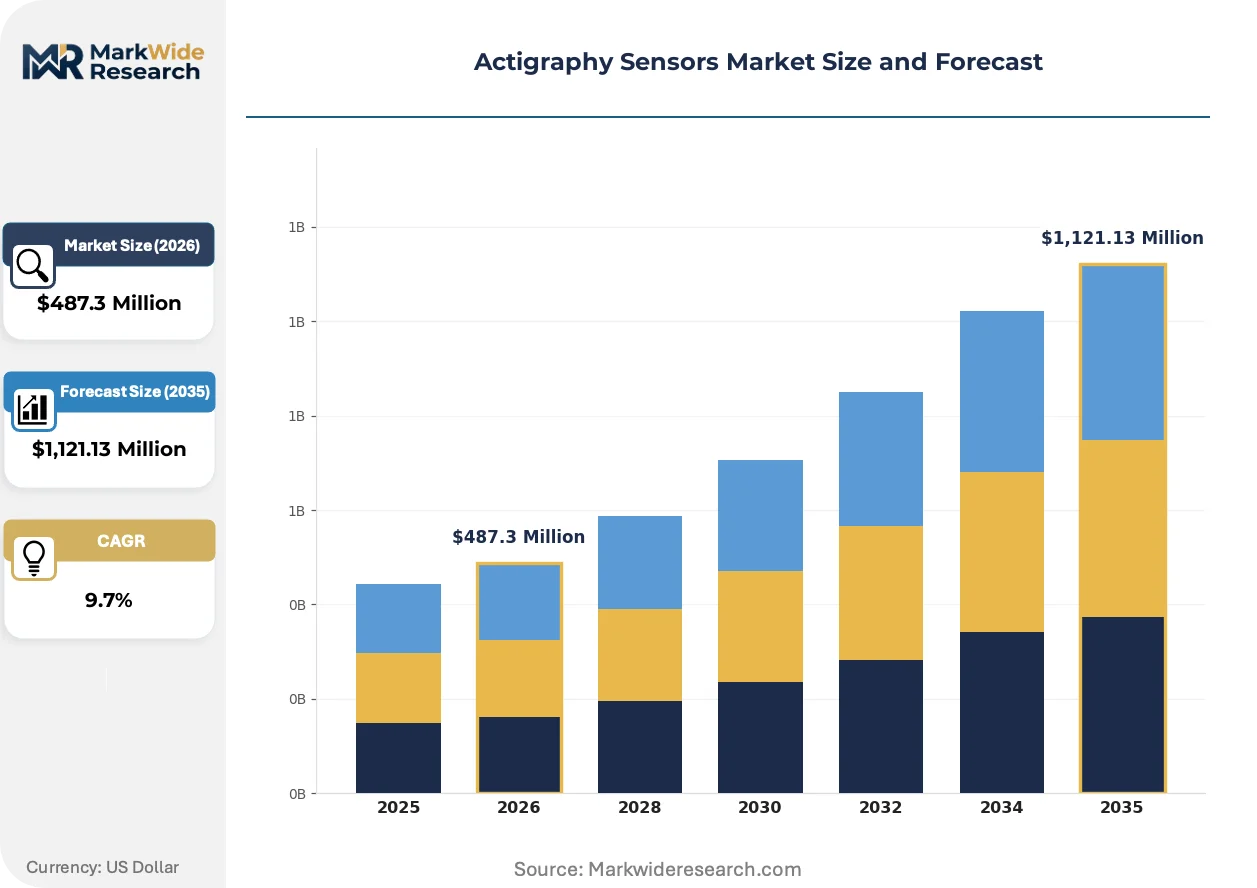
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,121.13 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wrist Wearables, Bed Sensors, Mobile Devices, Wearable Clips End User: Healthcare Providers, Research Institutions, Fitness Enthusiasts, Clinical Trials Technology: Bluetooth, Cloud-Based, Machine Learning, Mobile App Integration Application: Sleep Monitoring, Activity Tracking, Health Assessments, Behavioral Research |
| Companies Covered | ActiGraph LLC, Fitbit LLC, Garmin Ltd, Koninklijke Philips N.V., ResMed Inc., Natus Medical Inc., SOMNOmedics GmbH, Activinsights Ltd, Compumedics Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Actigraphy Sensors Market Evolving Landscape
Adaptive algorithm architectures are redistributing competitive advantage from hardware fidelity toward predictive analytics accuracy, compressing the value capture window for device-centric business models.
Photoplethysmography fusion with accelerometer cores is supplanting pure motion-based sleep detection in next-generation wearables. Sleep clinic procurement committees in Germany and Japan are prioritizing multi-modal sensors for cardiovascular comorbidity screening. This convergence is collapsing the historical separation between consumer fitness bands and clinical-grade actigraphy systems.
EU AI Act risk classification for health-related algorithmic decision support is mandating conformity assessments for cloud-based sleep staging models. Device manufacturers serving European sleep centers must now document training data provenance and performance drift monitoring protocols. CE-marked systems with pre-validated algorithm documentation are capturing expanded share of institutional procurement tenders.
Subscription revenue models are displacing perpetual license sales for actigraphy data platforms. Research sponsors in the United States are negotiating per-patient-per-month analytics fees rather than capital purchases of bedside hardware. This shift concentrates vendor cash flow predictability while transferring hardware refresh risk to equipment lessors serving academic medical centers.
Actigraphy Sensors Market Segmentation
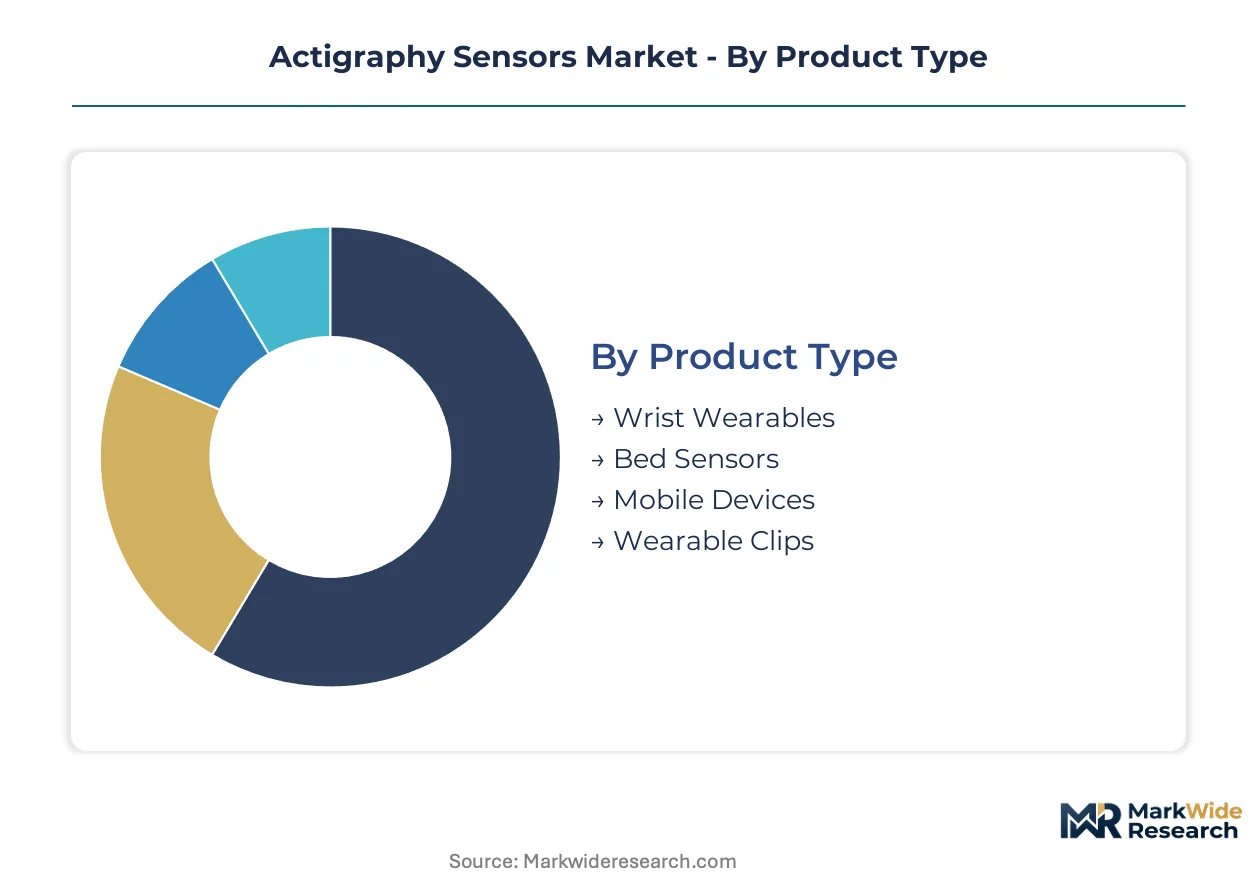
Actigraphy sensor procurement diverges sharply across use cases, with FDA 510(k) clearance requirements separating clinical-grade devices from consumer wellness trackers. Each segment category carries distinct regulatory burdens, reimbursement pathways, and algorithm validation standards that reshape vendor positioning.
Product Type:
FDA Class II and EU MDR Class IIa designations create tiered compliance thresholds that stratify manufacturing investments and channel access across wearable form factors.
- Wrist Wearables:Tri-axial accelerometer cores sampling at 30-100 Hz dominate pharmaceutical trial protocols and home sleep testing programs. United States reimbursement expansion for remote patient monitoring drives institutional procurement of bracelet-format devices with validated sleep-wake algorithms.
- Bed Sensors:Non-contact piezoelectric or pressure-sensitive mats capture movement without patient adherence constraints. German sleep clinics favor CE-marked systems for cardiovascular comorbidity screening where wrist-worn compliance fails.
- Mobile Devices:Smartphones with embedded accelerometers serve behavioral research and consumer wellness applications lacking diagnostic claims. Regulatory pathways remain lighter where no sleep disorder classification is asserted.
- Wearable Clips:Alternative attachment points on clothing or bedding address populations with wrist-worn intolerance, including pediatric and dermatological cases. Volume concentrates in academic research grants requiring flexible deployment.
Established volume favors wrist wearables; emerging adoption favors bed sensors.
End User:
Customer procurement authority ranges from hospital capital committees to individual subscription purchases, fragmenting pricing power and contract structures.
- Healthcare Providers:Sleep medicine clinics and psychiatry departments purchase validated devices through group purchasing organizations. Japan's PMDA reimbursement expansion for home-based testing accelerates institutional procurement cycles.
- Research Institutions:Academic medical centers and pharmaceutical sponsors drive demand for raw data export capabilities and longitudinal analytics platforms. Cloud-based subscription models are displacing perpetual hardware licenses in this segment.
- Fitness Enthusiasts:Consumer-directed purchases prioritize GPS integration and multi-sport tracking over sleep staging accuracy. This segment tolerates algorithm opacity that clinical users reject.
- Clinical Trials:Contract research organizations mandate devices meeting International Council for Harmonisation GCP standards with audit trails for regulatory submission. Decentralized trial mandates are expanding wrist-worn deployment for circadian rhythm endpoints.
Procurement concentration sits with research institutions; fastest expansion occurs in clinical trials.
Technology:
Connectivity and analytics architectures determine regulatory classification under FDA software-as-medical-device guidance and EU AI Act risk tiers.
- Bluetooth:Short-range wireless transmission enables real-time data offload to paired smartphones or bedside hubs. Low-energy protocols extend battery life for multi-day monitoring required in pharmaceutical studies.
- Cloud-Based:Centralized data warehousing with algorithm auto-update capabilities triggers heightened conformity assessments in Europe. Training data provenance documentation now gates CE-marked system tenders.
- Machine Learning:Adaptive sleep staging models reduce manual scoring labor but demand specialized biostatistician talent for validation. EU AI Act health-related decision support classifications mandate performance drift monitoring protocols.
- Mobile App Integration:Patient-facing interfaces capture subjective sleep diaries and drive subscription revenue pools. Consumer familiarity with smartphone ecosystems accelerates clinical acceptance of bracelet form factors.
Legacy dominance belongs to Bluetooth; steepest expansion trajectory marks machine learning.
Application:
Use case specificity determines whether devices require diagnostic-grade validation or wellness-tier regulatory lightness.
- Sleep Monitoring:Circadian rest-activity pattern quantification outside polysomnography laboratories represents the core clinical value proposition. FDA 510(k) clearance requirements intensify for devices asserting sleep disorder diagnostic claims.
- Activity Tracking:GPS-integrated wearables extend utility into sports science applications including jet lag optimization and athletic performance. Consumer-grade specifications suffice where no medical endpoint is measured.
- Health Assessments:Photoplethysmography fusion with accelerometer cores enables cardiovascular comorbidity screening in German and Japanese sleep clinics. Multi-modal sensors collapse historical separations between fitness bands and clinical systems.
- Behavioral Research:Psychiatry CNS drug development adopts actigraphy for objective rest-activity biomarkers in mood disorder and schizophrenia trials. Academic grants favor flexible data export formats over polished patient interfaces.
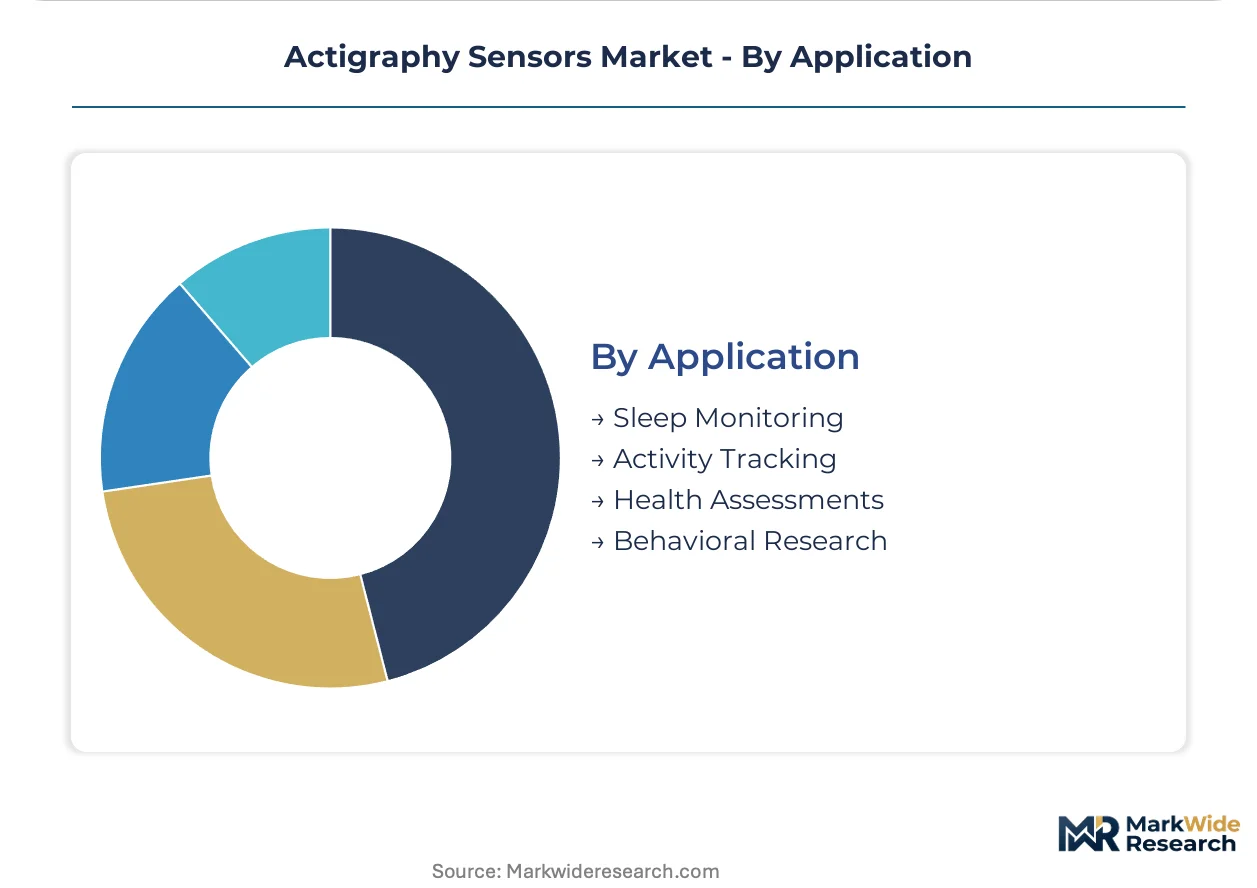
Clinical authority concentrates in sleep monitoring; behavioral research shows fastest volume gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-to-Washington corridor anchors United States demand through its concentration of academic medical centers running pharmaceutical trials with wrist-worn monitoring protocols.
United States
FDA 510(k) clearance pathways for sleep disorder diagnostic devices drive institutional procurement of validated wrist wearables. The Medicare remote patient monitoring reimbursement expansion accelerates hospital adoption of cloud-based actigraphy analytics. Research Triangle Park in North Carolina hosts contract research organizations embedding actigraphy into decentralized clinical trial designs.
Germany
EU MDR Class IIa designation for sleep diagnostic aids elevates validation requirements that favor CE-marked bed sensor systems. The country's statutory health insurance system reimburses home-based sleep testing through integrated care contracts. Munich and Berlin sleep medicine clusters prioritize multi-modal sensors combining accelerometry with cardiovascular screening.
Japan
PMDA enforcement of clinical substantiation requirements for sleep disorder diagnostic aids creates compliance convergence with FDA and EU standards. METI funding for digital health innovation accelerates hospital procurement of algorithm-validated devices. Osaka-Kobe medical device manufacturing corridor supplies components for Asian market entry by European actigraphy vendors.
United Kingdom
NHS England's Long Term Plan prioritizes remote monitoring for chronic conditions including circadian rhythm disorders in psychiatric populations. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR standards for CE-marked device recognition. Cambridge and Oxford academic medical centers lead European adoption of machine learning sleep staging for CNS drug development trials.
Australia
TGA conformity assessment pathways for software-as-medical-device classification pressure cloud-based actigraphy platforms to document algorithm training data provenance. National Health and Medical Research Council grants fund longitudinal sleep studies using consumer-grade wearables in remote Indigenous health programs. Melbourne biomedical research precinct exports validation datasets to Asian regulators seeking clinical evidence packages.
Actigraphy Sensors Market Competitive Landscape
Listed leaders compete with private specialists across regulatory validation capabilities, creating tiered procurement access where FDA-cleared devices command hospital premium pricing while consumer wellness trackers occupy retail channels. The vendor base concentrates around three strategic archetypes: institutional-grade device manufacturers with pharmaceutical trial certifications, fitness-integrated wearable producers leveraging GPS convergence, and regional sleep clinic specialists with CE-marked bed sensor installations. Capacity expansion in cloud analytics platforms and strategic partnerships between hardware manufacturers and contract research organizations dominate competitive maneuvering.
Within the institutional validation tier, ActiGraph LLC and SOMNOmedics GmbH exemplify divergent regional positioning—ActiGraph anchoring United States pharmaceutical trial procurement through GCP-compliant wrist wearables, SOMNOmedics occupying German sleep clinic installations with CE-marked bed sensor systems. Garmin Ltd represents the fitness-convergence archetype, its GPS-integrated wearables extending activity tracking applications beyond sleep medicine into sports science and jet lag optimization protocols.
| Leading Market Players |
|---|
| ActiGraph LLC |
| Fitbit LLC |
| Garmin Ltd |
| Koninklijke Philips N.V. |
| ResMed Inc. |
| Natus Medical Inc. |
| SOMNOmedics GmbH |
| Activinsights Ltd |
| Compumedics Ltd |
| Others |
Value Network & Pricing Analysis
MEMS foundry scale economies in Taiwan and South Korea anchor component cost floors for tri-axial accelerometer cores, concentrating pricing power among sensor vendors with captive wafer supply while forcing smaller manufacturers toward fabless models with compressed margins. This capacity concentration elevates price floors for FDA-validated wrist wearables while subscription SaaS models in cloud analytics redistribute margin capture toward software layers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical trial-grade devices with GCP compliance documentation from clinical sleep clinic systems and consumer wellness trackers. FDA 510(k) certification tier and raw data export capability drive the steepest price differentiation between institutional and retail channels. Pricing pressure stems from cloud platform subscription displacement of perpetual hardware licenses, compressing upfront capital recovery. Research institutions demonstrate lowest price sensitivity due to grant-funded procurement, while fitness enthusiasts tolerate algorithm opacity in exchange for GPS convergence at economy price points.
Supply Chain Analysis
Strait of Malacca transit vulnerability exposes East Asian MEMS foundry output to logistics disruption, with tri-axial accelerometer wafer fabrication concentrating in Taiwan, South Korea, and Japan. Raw material dependencies span silicon wafers, piezoelectric ceramics for bed sensors, and lithium-polymer cells for extended monitoring protocols. Single-source vulnerability for 30-100 Hz sampling rate transducers forces manufacturers toward dual-qualified foundry strategies. Distribution runs through pharmaceutical contract research organization procurement channels for trial-grade devices, while sleep clinic installations favor regional medical device distributors with CE-marking documentation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The actigraphy sensors market exhibits cyclical recovery characteristics as pharmaceutical trial volumes rebound from pandemic-era site visit restrictions, with decentralized protocol mandates creating durable demand expansion for remote patient monitoring endpoints.
For Market Incumbents: Consolidate algorithm validation datasets across FDA, EU MDR, and Japan PMDA submission requirements to defend against emerging cloud-native competitors with auto-update capabilities. Secure backward integration into MEMS accelerometer supply through foundry partnerships or captive capacity in Taiwan, insulating margin pressure from single-source wafer fragility. Prioritize CE-marked bed sensor line extensions for German cardiovascular comorbidity screening protocols where wrist-worn compliance fails. For New Entrants and Emerging Players: FDA 510(k) predicate device pathways for sleep-wake scoring algorithms offer the fastest certification fast-track for cloud-based analytics platforms seeking institutional procurement access. Target psychiatry CNS drug development trials for rest-activity biomarker adoption, where objective circadian endpoints remain underpenetrated by established sleep medicine vendors. Deploy per-patient-per-month subscription pricing to bypass hospital capital budget constraints and capture research sponsor operating expenditure flows. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated device manufacturers with pharmaceutical trial certifications and cloud platform subscription revenue visibility. Long-term viability hinges on adaptive sleep staging model accuracy rather than hardware fidelity, compressing the value capture window for pure-play sensor producers. Watch FDA software-as-medical-device guidance evolution as the inflection signal for cloud-native algorithm platforms displacing bedside hardware incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Class IIa designation gates institutional procurement tenders for sleep diagnostic aids. |
| Hospital System Partnership | GPO contracts with academic medical centers secure pharmaceutical trial device volumes. |
| Software Companion Development | Cloud analytics platforms with auto-update algorithms trigger SaaS revenue displacement of hardware sales. |
| Reimbursement Strategy | Medicare remote patient monitoring coding expansion accelerates hospital cloud platform adoption. |
| FDA Submission | 510(k) clearance for sleep disorder diagnostic claims commands premium pricing in clinical channels. |
Research Methodology
Cross-validation between primary interviews with sleep medicine clinicians, pharmaceutical trial operations managers, biomedical engineers, and GPO contracts managers anchors the qualitative findings, with secondary validation drawing from FDA 510(k) filings, EU MDR technical documentation, ClinicalTrials.gov protocol registries, and hospital procurement database extracts. Bottom-up demand modeling from device shipment records triangulates against top-down pharmaceutical trial expenditure estimates.
Sensitivity analysis across algorithm validation tier, wearable form factor adoption curves, and regional reimbursement expansion scenarios informs the projection framework. Segmentation dimensions span product type, end user procurement authority, connectivity architecture, and application specificity with diagnostic-grade versus wellness-tier regulatory classification. CAGRs derive from fitted growth curves against historical pharmaceutical trial volume patterns and cloud platform subscription displacement rates.
The analysis sits within stated boundaries; outcomes outside sustained decentralized trial mandates, stable MEMS foundry capacity utilization, and convergent FDA-EU-Japan regulatory alignment would require recalibration. Forecasts reflect documented assumptions regarding reimbursement expansion velocity and algorithm performance drift monitoring protocol adoption. Practitioners should keep alternative scenarios live as pharmaceutical sponsor procurement preferences and cloud platform conformity assessment requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Collision Sensors Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
US Temperature Sensors Market
Sensors and Controls
Global Smart Biosensors Market
Sensors and Controls
Ceramic Transducers Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
3D Sensors Market