
 Spain Digital Thermometer Market | 2026-2036
Spain Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Digital Thermometer Market Insights
Shortages of biomedical equipment technicians is redrawing how manufacturers staff service networks across Spain. Omron Corporation leverages its established distribution partnerships to sustain shelf presence in major pharmacy chains. Microlife Corporation specializes in infrared and ear-type formats that anchor its position in home care segments.
Digital thermometers are electronic temperature measurement devices that use thermistors, infrared sensors, or thermocouples to quantify body or surface heat, typically displaying readings within seconds on LCD or LED interfaces with precision to one decimal degree Celsius. Their primary commercial purpose spans clinical diagnosis, home health monitoring, and workplace health screening where speed and hygiene matter. Infrared and forehead-type units now lead hospital procurement due to non-contact hygiene protocols, while Bluetooth-enabled smart thermometers represent the fastest-growing technology segment as remote patient monitoring expands. Oral and ear formats retain dominant share in home care and pediatric settings where cost sensitivity shapes purchasing decisions.
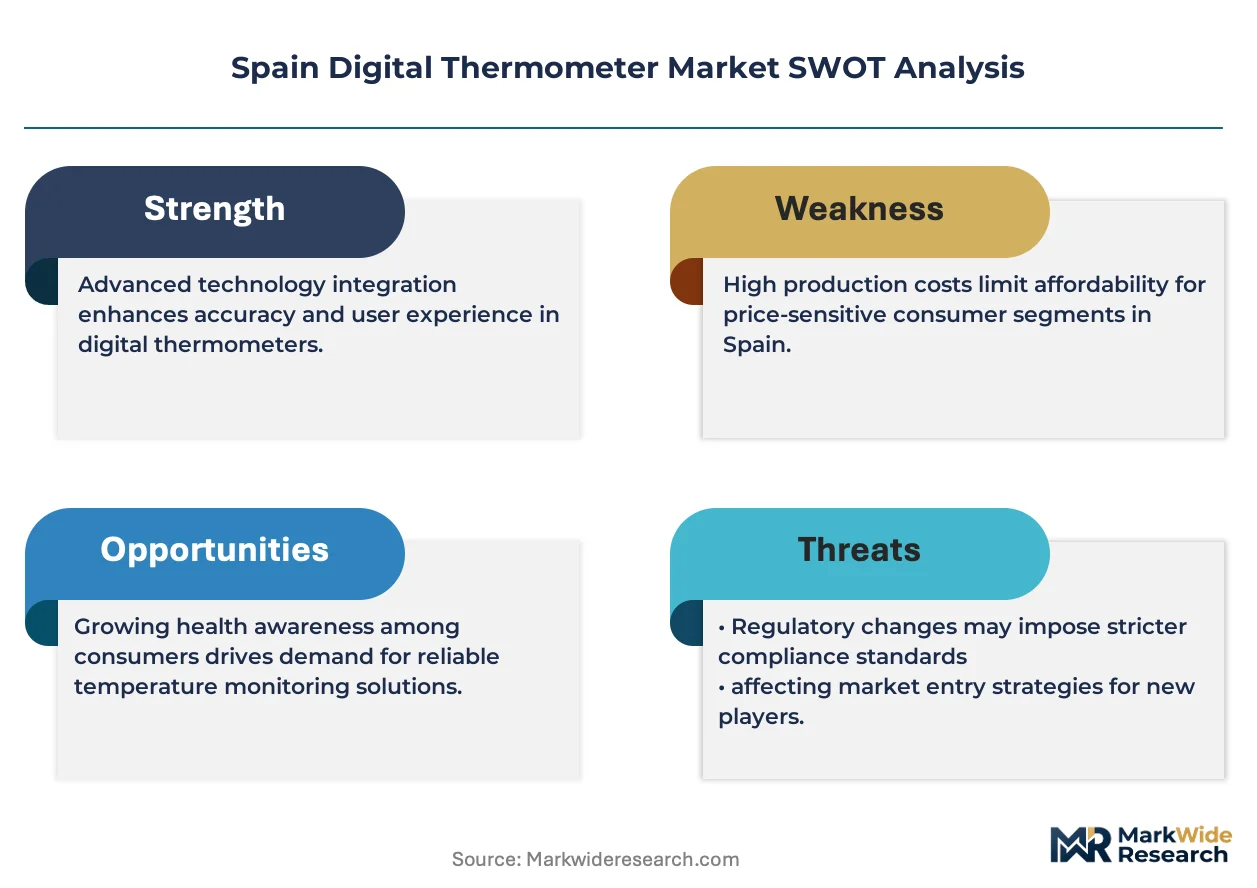
Spain's national pharmaceutical regulator, operating under EU MDR frameworks, mandates clinical performance documentation and post-market surveillance for all diagnostic thermometers sold to healthcare providers. BIS-equivalent metrology standards enforced through Spain's national accreditation body require periodic calibration traceability for devices used in clinical settings. Stakeholders must monitor how upcoming EU AI Act classifications affect smart thermometers with algorithmic fever detection before committing R&D budgets to connected-device platforms.
Market Dynamics
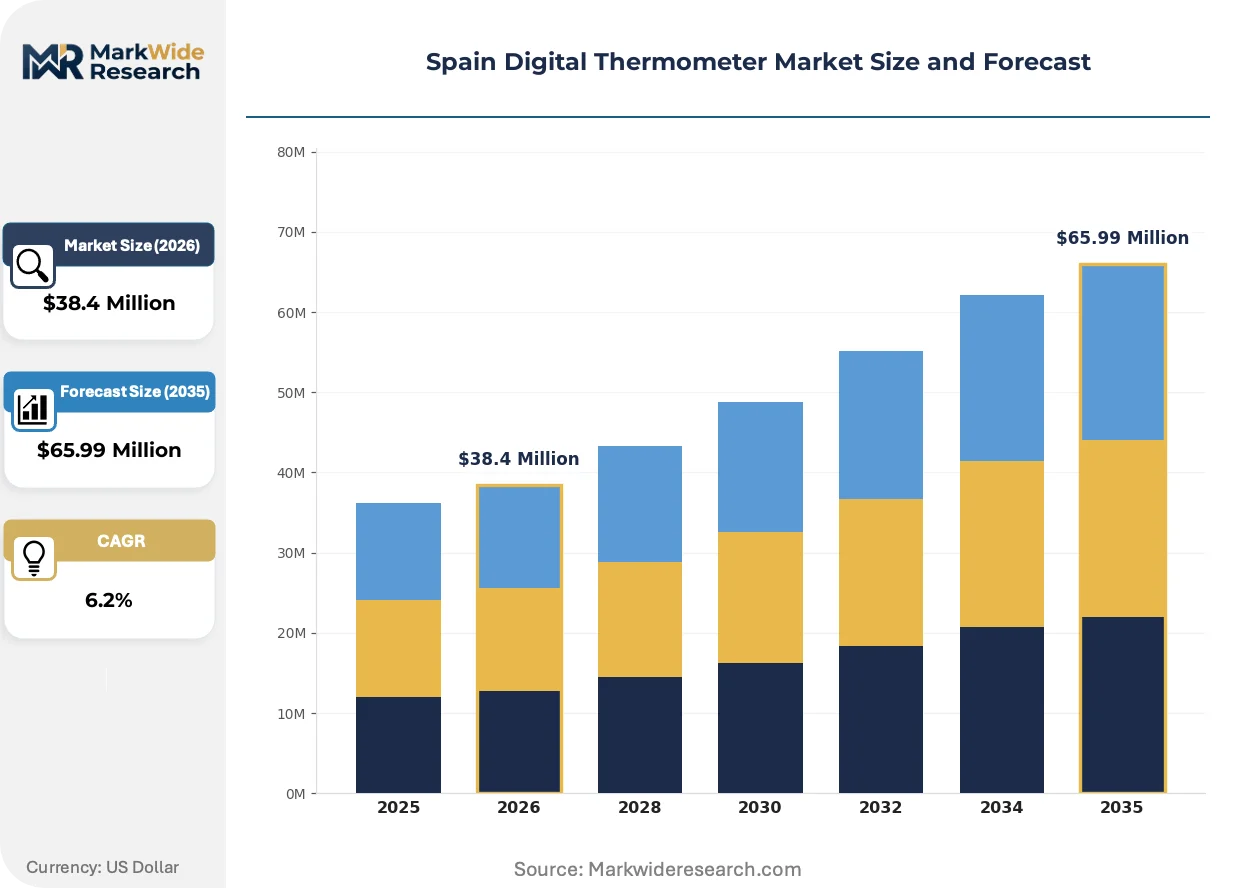
EU MDR compliance timelines are compressing certification cycles for clinical-grade thermometer manufacturers serving Spanish healthcare networks. This regulatory pressure is restructuring how suppliers allocate R&D resources and validate product performance before market entry.
Growth Catalysts
- Contactless Screening Mandates:Spanish hospital networks in Madrid and Barcelona are institutionalizing non-contact temperature protocols in emergency departments and outpatient clinics, expanding procurement volumes for infrared forehead units.
- EU MDR Accuracy Standards:Tightened metrology requirements for clinical-grade devices are elevating barriers to entry, protecting incumbent suppliers with established calibration traceability systems.
- Bluetooth Connectivity:Remote patient monitoring platforms in home care segments are integrating smart thermometer data streams, creating pull-through demand for connected-device formats.
Market Restraints
- Semiconductor Component Volatility:Infrared sensor and microcontroller supply remains concentrated among Asian foundries, exposing Spanish manufacturers to input cost fluctuations and extended lead times.
- Substitution by Thermal Imaging:Multi-person screening systems using thermal camera arrays are displacing individual forehead thermometers in high-throughput settings like airports and stadiums.
- Calibration Infrastructure Gaps:Spain's accredited metrology laboratories face capacity constraints for periodic recertification of clinical devices, creating compliance bottlenecks for healthcare providers.
Strategic Opportunities
- Andalusian Pharmacy Network Expansion:Regional pharmacy cooperatives in southern Spain remain underpenetrated by premium digital thermometer brands, offering whitespace for distribution partnerships.
- EU AI Act Algorithmic Classification:Fever-detection algorithms in smart thermometers may qualify as low-risk AI systems, creating regulatory tailwinds for connected-device platforms with embedded decision-support features.
- Pediatric Home Care Integration:Ear-type thermometers with parental mobile app connectivity represent an emerging application segment where purchasing decisions prioritize ease-of-use over unit cost.
Industry Challenges
- Biomedical Technician Scarcity:Field service networks for calibration and repair face recruitment constraints across Spanish provinces, forcing manufacturers to centralize technical support functions.
- MDR Technical Documentation Burden:Clinical performance studies and post-market surveillance requirements demand specialized regulatory affairs capacity that smaller suppliers struggle to maintain.
- Legacy Health IT Integration:Hospital procurement teams report friction connecting Bluetooth-enabled devices to existing electronic health record architectures, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Digital Thermometer Market |
| Market Size in 2026 | $38.4 Million |
| Market Size in 2035 | $65.99 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Infrared, Ear, Oral, Forehead End User: Hospitals, Clinics, Home Care, Pharmacies Technology: Bluetooth, Non-Contact, Smart, Digital Distribution Channel: Online, Retail Stores, Direct Sales, Distributors |
| Companies Covered | Omron Corporation, Terumo Corporation, Microlife Corporation, Philips Healthcare, Siemens Healthineers, Medtronic plc, Roche Diagnostics, Ametek, Inc., PCE Holding GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Digital Thermometer Market Trends and Innovations
Digital thermometer technology is bifurcating between premium connected formats and cost-optimized clinical workhorses. This divergence is reshaping how manufacturers segment their product portfolios and target distinct buyer constituencies across Spanish healthcare and consumer markets.
Infrared sensing technology is fragmenting thermometer architectures into specialized variants optimized for specific use environments. Forehead-type units with adjustable emissivity settings now dominate hospital triage areas where rapid sequential screening matters. Pediatric clinics are adopting ear canal designs with pre-warmed tips to improve measurement stability. This specialization is fragmenting the market into application-specific niches rather than general-purpose devices, compressing margins on undifferentiated units while enabling premium pricing for purpose-built formats.
Spain's national pharmaceutical regulator, operating under EU MDR frameworks, is enforcing clinical performance documentation requirements that extend beyond basic accuracy claims. Post-market surveillance obligations now mandate adverse event reporting for diagnostic thermometers used in clinical settings. Healthcare procurement teams in Catalonia and Madrid are responding by demanding extended calibration certificates and traceability documentation before contract award, shifting supplier evaluation criteria toward compliance depth rather than unit cost alone.
Spanish pharmacy chains are consolidating thermometer purchasing through centralized procurement functions that bypass traditional distributor relationships. Regional cooperative buying groups in Galicia and the Basque Country now negotiate directly with manufacturers for private-label and exclusive-brand arrangements. This channel consolidation is most visible in metropolitan Madrid, where three pharmacy banners control shelf placement decisions for home-care temperature monitoring devices, compressing available slots for secondary brands and elevating slotting fee requirements.
Spain Digital Thermometer Market Segmentation
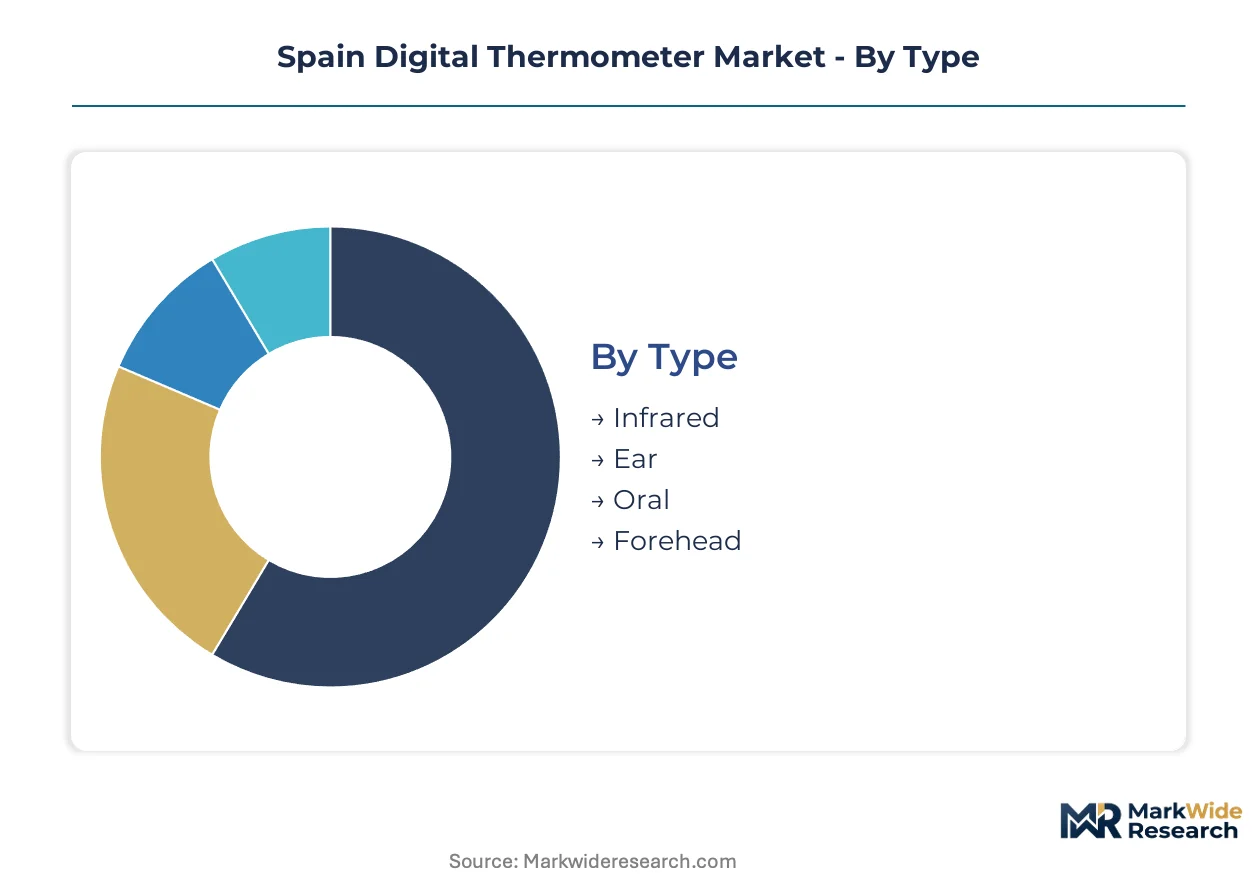
Digital thermometer segmentation in Spain reflects divergent hygiene protocols, connectivity demands, and procurement channels reshaping how manufacturers allocate R&D and distribution resources. Each dimension carries distinct margin profiles and regulatory burdens that determine competitive positioning.
Type:
Infrared formats face the strongest displacement threat from thermal imaging arrays in high-throughput settings, while ear and oral segments defend entrenched positions in cost-sensitive home care.
- Infrared:Non-contact sensors using thermopile arrays measure surface temperature through emitted thermal radiation. Hospital networks in Madrid and Barcelona are expanding procurement of forehead-type units for emergency department triage, though thermal camera substitution looms in airport and stadium deployments.
- Ear:Tympanic designs with pre-warmed probe tips measure core body temperature via infrared detection in the ear canal. Pediatric clinics across Catalonia favor this format for measurement stability in infant care, where parental trust outweighs unit cost sensitivity.
- Oral:Thermistor-based sublingual devices remain the lowest-cost clinical option. Home care segments in Andalusia and Galicia drive volume through pharmacy chain promotions.
- Forehead:Temporal artery scanners using sweep-motion infrared detection. Outpatient clinics prioritize this format for speed in sequential patient screening.
Oral thermometers anchor the volume base while infrared units gain share at the steepest rate.
End User:
Cost tier stratification separates premium clinical procurement from mass-market consumer purchasing, with distinct compliance thresholds governing each segment.
- Hospitals:Large networks in Madrid and Barcelona demand EU MDR-certified devices with calibration traceability and post-market surveillance documentation. Procurement teams prioritize infrared forehead units for infection control protocols.
- Home Care:Individual consumers and family caregivers purchase through pharmacy chains and online channels. Bluetooth-enabled smart thermometers with parental mobile apps are climbing the fastest in this segment.
- Clinics:Outpatient and specialty practices require mid-tier accuracy with portable form factors. Ear-type units dominate pediatric and ENT specialist settings.
- Pharmacies:Retail dispensaries function as both sales channel and end-user through private-label arrangements. Centralized buying groups in the Basque Country and Galicia negotiate direct manufacturer contracts.
Hospital procurement commands premium pricing while home care delivers the volume foundation.
Technology:
Application maturity varies sharply, with legacy digital formats defending installed base against connected-device platforms requiring health IT integration.
- Digital:Standard LCD-display thermistors without connectivity features. This mature technology retains dominant share in budget-conscious clinical and home settings across Spanish provinces.
- Bluetooth:Wireless data transmission to smartphones and remote monitoring platforms. Remote patient monitoring providers are pulling this technology into chronic care management programs.
- Non-Contact:Infrared sensing without physical patient contact. EU MDR accuracy requirements are elevating barriers for new entrants in this hospital-focused category.
- Smart:Algorithmic fever detection with embedded decision-support features. The EU AI Act may classify these as low-risk AI systems, creating regulatory clarity for R&D investment.
Digital thermometers defend the installed base while Bluetooth formats expand most quickly through home care integration.
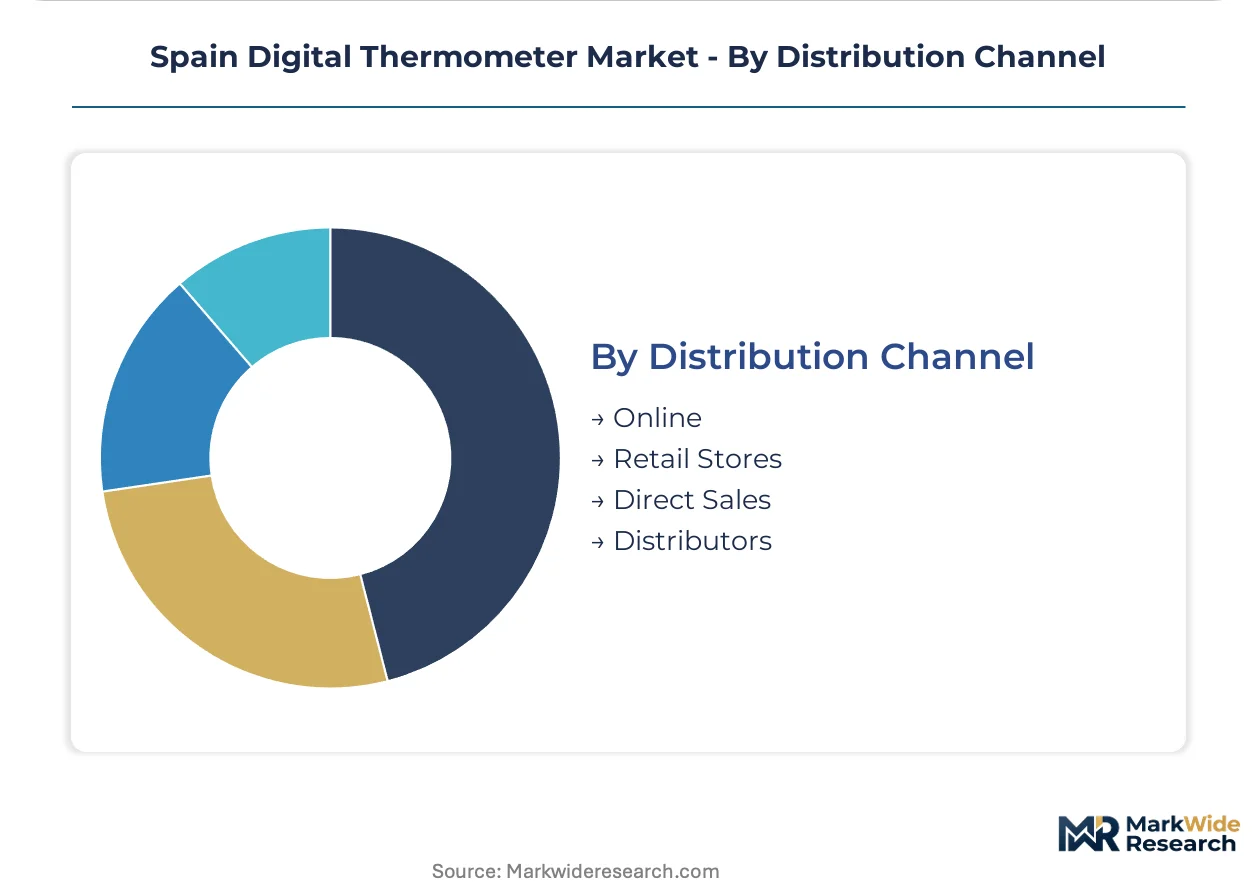
Distribution Channel:
Channel concentration in metropolitan Madrid and Barcelona is compressing available shelf space and elevating slotting fees for secondary brands.
- Retail Stores:Pharmacy chains and medical supply outlets with physical presence. Three major banners in Madrid control home-care thermometer placement decisions.
- Online:E-commerce platforms and direct-to-consumer sales. This channel is expanding fastest as remote patient monitoring platforms integrate smart thermometer purchases into subscription models.
- Distributors:Traditional medical device wholesalers serving regional healthcare providers. Biomedical technician scarcity is forcing manufacturers to centralize technical support functions previously handled through distributor networks.
- Direct Sales:Manufacturer-led contracting with hospital networks and pharmacy cooperatives. Regional buying groups in Galicia and the Basque Country increasingly bypass distributor relationships.
Retail stores maintain volume leadership while online channels capture the steepest growth trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU MDR anchors regulatory harmonization across Spanish healthcare procurement, with regional pharmacy cooperatives and hospital networks driving distinct demand patterns across autonomous communities.
Madrid
Hospital networks in the capital region dominate clinical-grade thermometer procurement, with large public health systems mandating infrared forehead units for emergency department triage. The EU MDR compliance timelines compress certification cycles for suppliers seeking contract awards. Three major pharmacy banners control shelf placement decisions for home-care devices, elevating slotting fees for secondary brands.
Catalonia
Barcelona anchors pediatric and specialty clinic demand, with ear-type thermometers preferred for measurement stability in infant care settings. The regional health service enforces calibration traceability requirements that exceed baseline EU standards. Biomedical technician scarcity forces manufacturers to centralize technical support functions previously handled through local distributor networks.
Basque Country
Pharmacy cooperative buying groups in this northern region negotiate direct manufacturer contracts, bypassing traditional wholesale relationships. The EU MDR post-market surveillance obligations reshape how suppliers structure regional service commitments. San Sebastián and Bilbao host concentrated procurement decision-making for private-label thermometer arrangements.
Andalusia
Southern pharmacy networks remain underpenetrated by premium digital thermometer brands, offering whitespace for distribution partnerships. The national pharmaceutical regulator's enforcement of clinical performance documentation extends to regional hospital procurement. Seville and Málaga drive volume demand through cost-sensitive home care segments.
Galicia
Regional cooperative buying groups consolidate purchasing power for pharmacy chains across this northwestern autonomous community. EU MDR accuracy standards elevate barriers for new entrants seeking shelf placement in retail channels. Santiago de Compostela anchors procurement coordination for mid-tier clinical devices serving outpatient clinics.
Spain Digital Thermometer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Spain's thermometer market. Hospital procurement teams in Madrid and Barcelona prioritize suppliers with established EU MDR certification and calibration traceability systems. Three archetypes dominate: multinational health technology conglomerates with full diagnostic portfolios, specialized temperature measurement manufacturers with focused product lines, and regional distributors evolving into private-label brand operators. Competitive moves concentrate on securing direct pharmacy cooperative contracts and centralizing technical service networks to offset biomedical technician scarcity.
Within the multinational tier, Omron Corporation and Terumo Corporation exemplify integrated health technology positioning. Philips Healthcare and Siemens Healthineers occupy positions bridging diagnostic imaging with point-of-care measurement devices. Among specialized temperature measurement players, Microlife Corporation represents focused expertise in infrared and ear-type formats. Roche Diagnostics and Medtronic plc anchor positions where diagnostic platforms integrate with connected-device ecosystems. PCE Holding GmbH and Ametek, Inc. sit within the precision instrumentation archetype serving industrial and clinical metrology overlap segments.
| Leading Market Players |
|---|
| Omron Corporation |
| Terumo Corporation |
| Microlife Corporation |
| Philips Healthcare |
| Siemens Healthineers |
| Medtronic plc |
| Roche Diagnostics |
| Ametek, Inc. |
| PCE Holding GmbH |
| Others |
Pricing and Supply Chain Analysis
Asian foundry scale economies in infrared sensor production concentrate cost advantages among established manufacturers, compressing price floors for Spanish entrants while elevating procurement leverage for Madrid hospital networks demanding EU MDR-certified devices. This concentration cascades through distribution tiers, with pharmacy cooperatives in the Basque Country and Galicia extracting volume discounts that secondary brands cannot match.
Pricing Analysis
Madrid hospital procurement commands 15-25% premiums over Andalusian pharmacy retail for identical infrared forehead units, reflecting divergent compliance documentation requirements. Pricing stratifies across EU MDR-certified clinical tiers, standard home-care formats, and unconnected economy segments, with calibration traceability driving the wedge between premium and standard tiers. Cost compression in oral thermometers intensifies as Galician cooperative buying groups consolidate volume, while Bluetooth-enabled smart formats defend margins through app ecosystem stickiness. Home care consumers in southern provinces exhibit highest price sensitivity, whereas Catalonia pediatric clinics prioritize measurement stability over unit cost.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes extend component lead times for infrared thermopile arrays sourced from Chinese and Taiwanese foundries. Manufacturing concentration in China, Malaysia, and Vietnam for microcontrollers and LCD displays creates single-source vulnerability when geopolitical disruptions reroute maritime freight. Spain's thermometer assembly draws from German precision optics for lens components and Dutch semiconductor packaging for sensor modules, exposing margins to euro-denominated input volatility. Distribution runs through centralized pharmacy cooperative warehouses in Madrid and Barcelona before last-mile deployment to regional clinics, with biomedical technician scarcity forcing manufacturers to bypass traditional wholesaler technical support roles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance fragmentation creates defendable niches for specialists with calibration infrastructure, as hospital procurement teams abandon undifferentiated suppliers lacking post-market surveillance documentation.
For Market Incumbents: Shield market position by deepening calibration traceability investments that smaller competitors cannot replicate under compressed EU MDR certification timelines. Consolidate technical service networks into Madrid and Barcelona hubs to offset biomedical technician scarcity across Spanish provinces. Omron Corporation's distribution partnerships demonstrate how channel control defends shelf presence against private-label encroachment from pharmacy cooperatives. For New Entrants and Emerging Players: Anchor in Andalusian pharmacy networks where premium brand penetration remains sparse and cooperative buying groups have not yet consolidated procurement decisions. Target pediatric home care integration with ear-type formats featuring parental mobile app connectivity, bypassing saturated hospital procurement channels where EU MDR barriers protect incumbents. Direct manufacturer contracts with regional Basque Country cooperatives offer faster traction than Madrid's slotting-fee-dominated retail environment. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors connected-device platforms with algorithmic fever detection capabilities that may qualify as low-risk AI systems under pending EU AI Act classifications. Acquisition candidates should demonstrate existing calibration infrastructure and established EU MDR technical documentation rather than pure hardware volume scale. Watch EU AI Act implementation timelines as the inflection signal determining whether smart thermometer R&D investments convert to reimbursable remote patient monitoring endpoints.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Acceleration | Compressed timelines favor incumbents with existing clinical performance documentation and post-market surveillance systems. |
| Bluetooth Platform Integration | Remote patient monitoring providers in home care segments pull connected-device data streams into chronic care management workflows. |
| Andalusian Distribution Partnership | Underpenetrated southern pharmacy cooperatives offer whitespace for brands bypassing Madrid's consolidated retail banners. |
| Calibration Infrastructure Centralization | Biomedical technician scarcity forces technical service consolidation into Madrid and Barcelona hubs serving national accounts. |
| Pediatric App Ecosystem Development | Parental mobile connectivity in ear-type formats commands premium pricing over cost-optimized home care alternatives. |
Research Methodology
Cross-validation between hospital procurement database analysis and regulatory filing review anchors the qualitative findings on EU MDR compliance timelines. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and pharmacy cooperative procurement directors combined with secondary validation against Spanish national accreditation body metrology standards, EU MDR technical documentation requirements, hospital procurement contract awards, and customs import records. Bottom-up volume estimates from pharmacy chain SKU data triangulate against top-down market sizing derived from healthcare expenditure flows.
Sensitivity analysis across pricing tier elasticity and regulatory compliance cost scenarios informs the projection framework over the analysis window. Segmentation dimensions modeled include thermometer type, end-user category, connectivity technology, and distribution channel, with regional adoption patterns capturing autonomous community procurement concentration. CAGRs derive from installed base replacement cycles, remote patient monitoring platform integration rates, and EU MDR transition timelines for clinical-grade device recertification. Forecast inputs incorporate infrared sensor foundry capacity utilization and pharmacy cooperative consolidation trajectories.
Underlying assumptions cover EU MDR enforcement continuity, Asia-Europe maritime route stability, and remote patient monitoring reimbursement framework development, with deviation risk concentrated in semiconductor supply disruptions and EU AI Act algorithmic classification timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Inertial Sensors Market
Sensors and Controls
Window Sensors Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Submarine Sensor Market
Sensors and Controls
Advanced Carbon Dioxide (CO2) Sensors Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Digital Sensor Sleeves Market
Sensors and Controls
Exhaust Sensors Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Humidity Sensor Market
Sensors and Controls
Asia-Pacific Industrial Control System Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
North America Proximity Sensor Market