
 Wireless IoT Sensors Market | 2026-2036
Wireless IoT Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless IoT Sensors Market Outlook
South Korea is narrowing its focus on MEMS foundry capacity for ultra-low-power sensor modules. Bosch leverages captive semiconductor fabrication to control die yields for environmental sensing nodes. STMicroelectronics sustains R&D intensity across multi-protocol radio cores that unify LoRaWAN and BLE stacks. NXP competes through automotive-grade qualification programs that extend its industrial sensor portfolio into fleet telematics.
Wireless IoT sensors are transducer-equipped devices that convert physical phenomena into digital signals and transmit them via unlicensed or licensed radio spectrum, typically operating below one milliwatt in sleep mode to achieve decade-long battery life. Their primary purpose is to feed real-time telemetry into cloud analytics platforms without wired infrastructure. LoRaWAN dominates wide-area utility deployments where kilometre-range links justify gateway infrastructure, while BLE anchors proximity-dense settings such as healthcare asset tracking and smart building occupancy systems. Edge computing deployments are capturing margin pools as enterprises process sensor streams locally to reduce backhaul costs and latency.
FCC Part 15 rules govern unlicensed transmission bands in the United States, compelling manufacturers to certify spurious emissions and coexistence behaviour before market entry. The EU Radio Equipment Directive mandates interoperability testing and cybersecurity baselines for sensors sold across member states. ISO/IEC 27001-aligned supply chain audits are becoming de facto requirements for healthcare and critical infrastructure procurement. Stakeholders must weigh protocol fragmentation against vertical-specific certification costs when selecting radio architectures for new product lines.
Market Dynamics
ITU-standardized low-power wide-area network certification is compressing hardware validation cycles from eighteen months to under six months, forcing incumbent radio suppliers to retool firmware architectures or cede socket share to modular chipset vendors.
Growth Catalysts
- EU Radio Equipment Directive:Mandatory interoperability testing and cybersecurity baselines create procurement gatekeeping that favors certified vendors in cross-border industrial automation tenders.
- Predictive maintenance workflows:Automotive and machinery OEMs in Germany's industrial corridor are digitizing factory floors with dense sensor meshes for vibration and thermal monitoring.
- MEMS foundry capacity expansion:South Korea's narrowing focus on ultra-low-power module fabrication is shortening lead times for environmental sensing nodes.
Market Restraints
- Protocol fragmentation:Enterprise buyers face redundant certification costs when LoRaWAN, BLE, and proprietary mesh stacks coexist in single-site deployments.
- Spurious emissions compliance:FCC Part 15 rules in the United States impose pre-market testing burdens that extend time-to-revenue for unlicensed spectrum hardware.
- Gateway infrastructure economics:Kilometre-range LoRaWAN links require capital-intensive gateway placement that limits rural and developing-market penetration.
Strategic Opportunities
- Edge computing integration:Local processing of sensor streams is capturing margin pools as enterprises reduce backhaul costs and latency in bandwidth-constrained environments.
- Healthcare asset tracking:BLE proximity-dense deployments in hospital systems remain underpenetrated relative to industrial applications.
- ISO/IEC 27001-aligned audits:Supply chain security certification is becoming a de facto procurement requirement for critical infrastructure buyers.
Industry Challenges
- Multi-protocol firmware engineering:Unifying LoRaWAN and BLE stacks demands scarce radio-frequency and embedded systems talent.
- Automotive-grade qualification timelines:Fleet telematics certification programs extend eighteen to thirty-six months, compressing product refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless IoT Sensors Market |
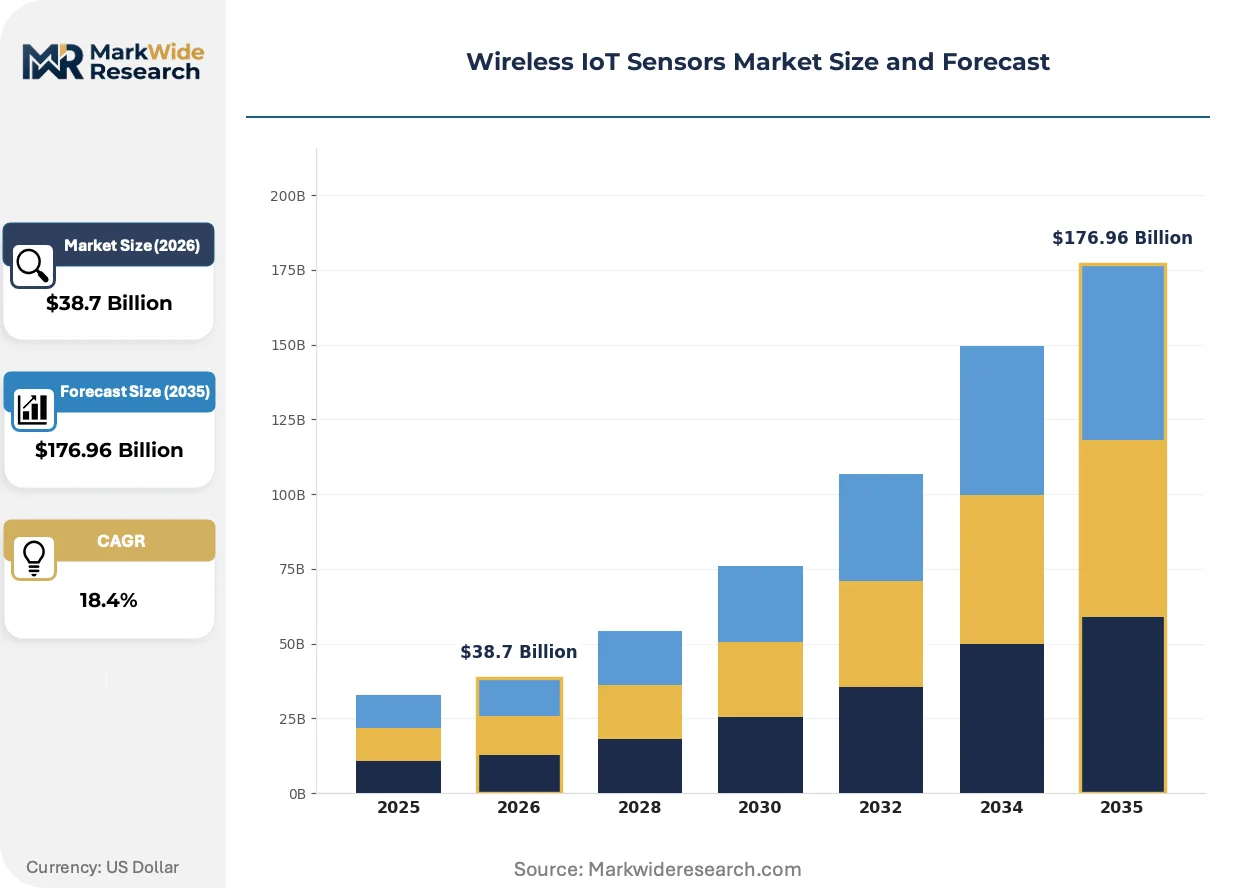
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $176.96 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LoRaWAN, Zigbee, BLE, NB-IoT End User: Agriculture, Healthcare, Smart Cities, Industrial Automation Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Application: Environmental Monitoring, Asset Tracking, Smart Metering, Home Automation |
| Companies Covered | Analog Devices, onsemi, Bosch, Disruptive Technologies, Polysense Technologies, NXP, STMicroelectronics, Sensative, Infineon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless IoT Sensors Market Strategic Shifts
Radio architecture decisions are migrating from hardware-centric discrete designs toward software-defined transceivers, altering how sensor vendors compete on time-to-market and protocol agility.
Energy harvesting is migrating from experimental pilots toward production-grade vibration and photovoltaic modules. Industrial predictive maintenance buyers in German automotive plants are deploying self-powered vibration sensors at scale. This shift is migrating from battery-dependent maintenance schedules toward zero-touch decade-long deployments.
REACH substance restrictions are tightening material constraints on sensor housings and solder alloys. Manufacturers must reformulate potting compounds and antenna substrates to maintain CE marking eligibility. German machinery OEMs are accelerating supplier audits to preempt compliance gaps in their sensor supply chains.
Buyers are consolidating vendor relationships around full-stack telemetry providers rather than discrete hardware suppliers. System integrators in the United States are bundling sensor procurement with cloud analytics contracts. This pattern is most visible in smart building deployments where facilities managers prefer single-accountability service agreements over component sourcing.
Wireless IoT Sensors Market Segmentation
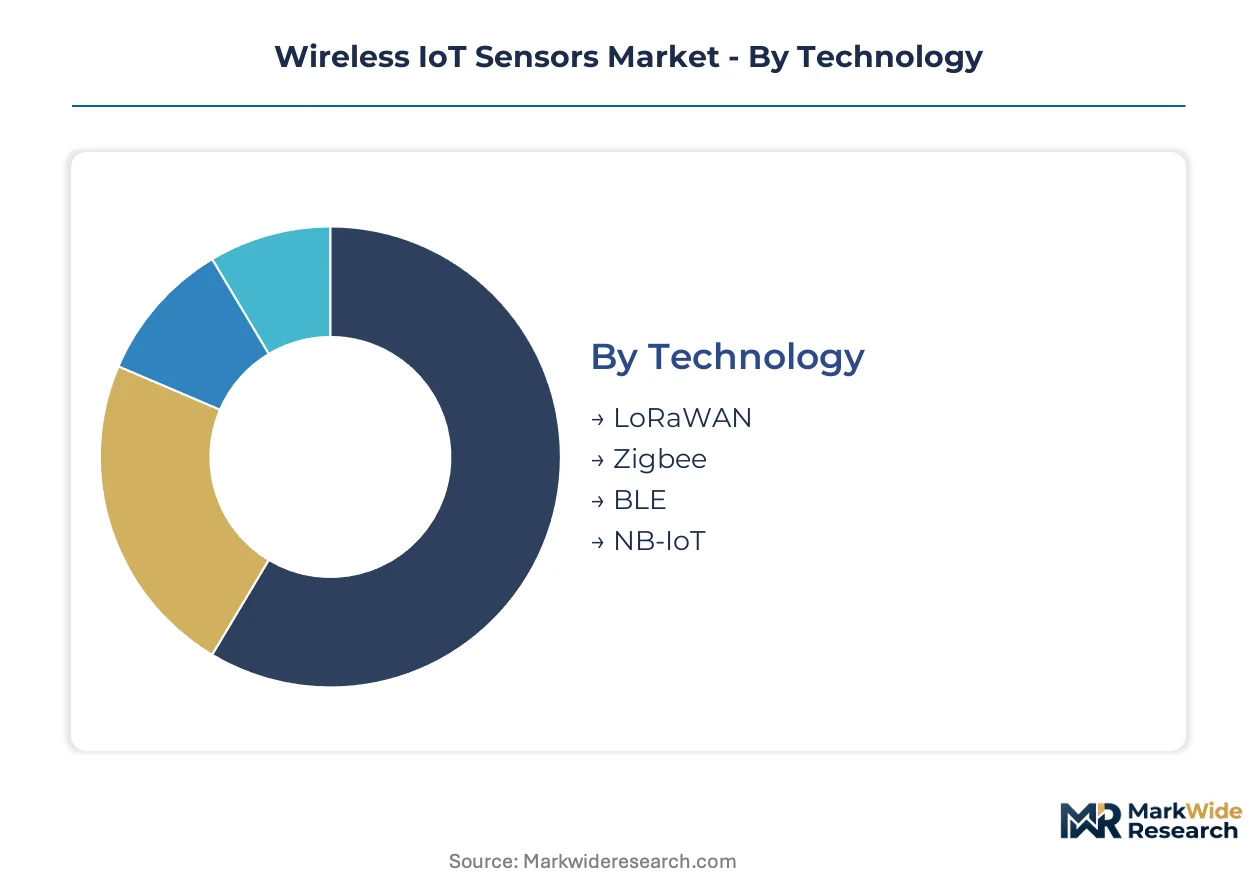
Technology choices in wireless IoT sensors lock in decade-long battery life profiles and determine gateway infrastructure economics. End-use verticals impose divergent certification timelines and cybersecurity baselines that reshape vendor selection criteria.
Technology:
LoRaWAN modules turn over slowest due to multi-year utility deployment cycles, while BLE refreshes fastest as proximity applications demand annual feature upgrades.
- LoRaWAN:Chirp spread spectrum modulation enables 15-kilometre rural links at sub-gigahertz frequencies with 10-year battery endurance. German water utilities concentrate demand for smart metering networks where kilometre-range coverage justifies capital-intensive gateway infrastructure.
- BLE:2.4 GHz frequency-hopping delivers sub-10-meter precision for proximity-dense hospital asset tracking and occupancy sensing. Healthcare systems in the United States drive fastest refresh cycles as security patches and location accuracy improvements release annually.
- Zigbee:Mesh networking protocol stacks self-heal across 65,000-node industrial floors. Smart building integrators favor Zigbee for lighting control where node density exceeds LoRaWAN gateway economics.
- NB-IoT:Licensed spectrum operation through cellular infrastructure eliminates private gateway deployment. European smart city pilots leverage NB-IoT where municipal IT departments prefer carrier-managed connectivity over unlicensed radio operations.
LoRaWAN dominates installed base in utility-scale telemetry. BLE is where expansion concentrates in healthcare and commercial real estate.
End User:
Cost tier separation is starkest here, with industrial automation commanding premium pricing and agriculture operating at economy margins.
- Industrial Automation:Vibration and thermal sensors feed predictive maintenance algorithms with millisecond-latency requirements. German automotive OEMs digitize factory floors with dense sensor meshes that demand automotive-grade qualification timelines.
- Smart Cities:Streetlight controllers, waste bin fill-level monitors, and parking occupancy sensors share municipal procurement frameworks. South Korean metropolitan governments bundle NB-IoT connectivity with cloud analytics contracts to reduce vendor fragmentation.
- Healthcare:BLE-enabled asset tags and environmental monitors track equipment location and cold-chain integrity. ISO/IEC 27001-aligned supply chain audits are becoming de facto requirements for hospital procurement departments.
- Agriculture:Soil moisture and microclimate sensors operate at lowest price points with solar-harvesting power architectures. Brazilian soybean operations deploy LoRaWAN soil probes where cellular coverage gaps persist across vast farmland holdings.
Industrial Automation captures the steepest expansion trajectory as predictive maintenance workflows scale. Agriculture remains price-constrained despite rising precision farming interest.
Deployment:
Volume concentration favors cloud-based architectures, though edge computing is climbing fastest as backhaul costs pressure enterprise budgets.
- Cloud-Based:Sensor streams route through public internet to centralized analytics platforms. United States smart building operators prefer cloud deployment for multi-site portfolio visibility without on-premise IT overhead.
- Edge Computing:Local gateways process telemetry before selective cloud synchronization. German machinery OEMs deploy edge nodes to reduce latency for vibration anomaly detection on safety-critical production lines.
- Hybrid:Time-sensitive processing executes locally while long-term analytics migrate to cloud. Healthcare systems balance real-time alerting with population-level trend analysis across this architecture.
- On-Premise:Fully air-gapped sensor networks satisfy critical infrastructure cybersecurity mandates. Nuclear and defense facilities in France mandate on-premise deployment under national security regulations.
Cloud-Based dominates current procurement volume. Edge Computing is where margin expansion concentrates as enterprises seek latency reduction.
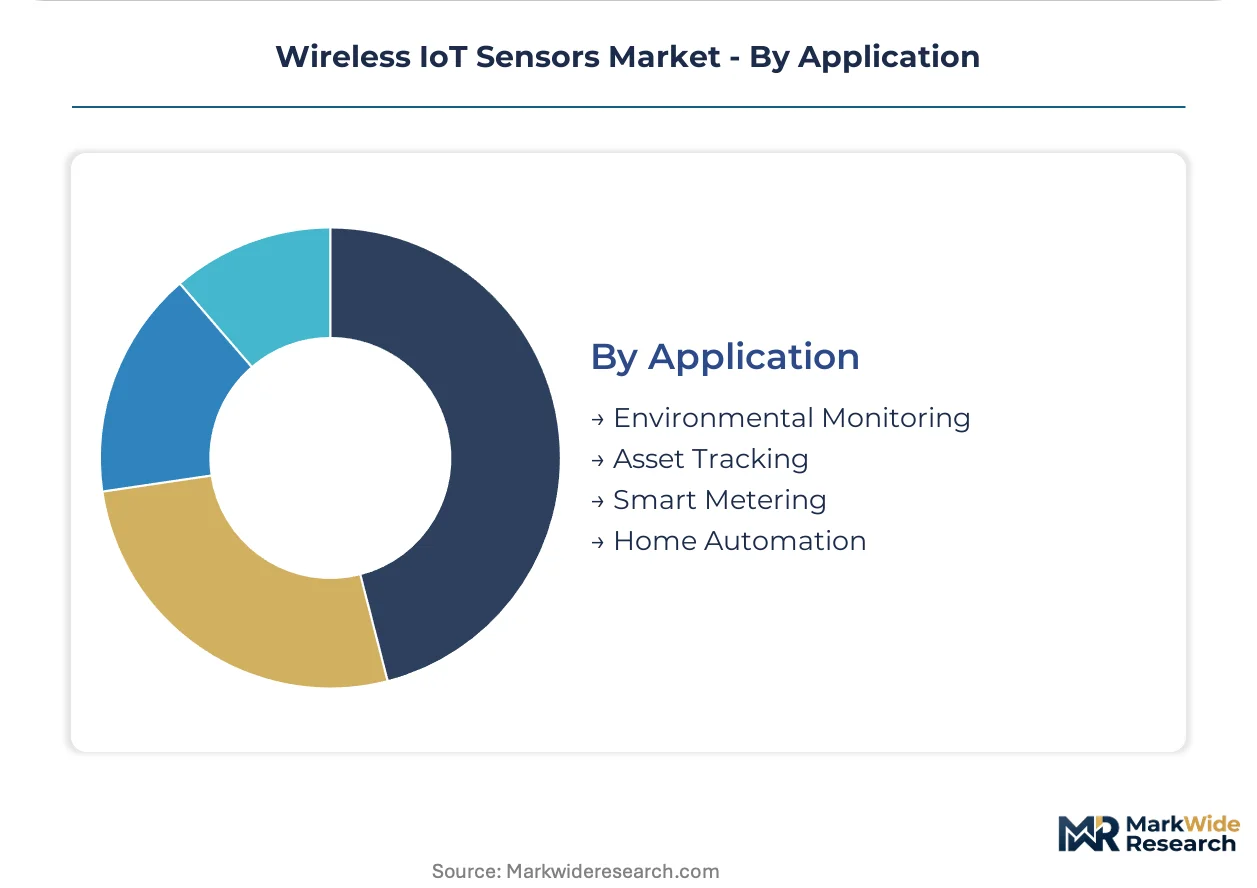
Application:
Maturity varies widely, with smart metering representing the most standardized procurement and home automation the most fragmented.
- Smart Metering:Utility-grade metrology combines with wireless modules for automated billing and demand-response programs. European electricity distributors standardize on LoRaWAN under EU Radio Equipment Directive interoperability mandates.
- Asset Tracking:BLE and UWB tags locate mobile equipment across manufacturing floors and hospital campuses. United States health systems concentrate demand for FDA-aligned device location services.
- Environmental Monitoring:Air quality, noise, and radiation sensors feed municipal compliance dashboards. Chinese environmental bureaus deploy dense urban sensor grids under dual carbon goals monitoring requirements.
- Home Automation:Consumer-facing thermostats, security sensors, and lighting controllers compete on retail price and ecosystem lock-in. Zigbee and Thread protocols fragment this segment across competing smart home platforms.
Smart Metering dominates utility procurement pipelines. Asset Tracking is where healthcare and logistics buyers are expanding fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FCC Part 15 certification requirements anchor the United States as the regulatory benchmark for unlicensed spectrum hardware, while Germany's EU Radio Equipment Directive implementation shapes procurement standards across European industrial automation. South Korea's MEMS foundry investments and China's dual carbon monitoring mandates complete the geographic concentration matrix.
United States
Healthcare asset tracking systems drive BLE module procurement across hospital networks seeking FDA-aligned device location services. FCC Part 15 spurious emissions testing extends hardware validation timelines before market entry. Facilities managers in the Boston and New York metro corridors consolidate vendor relationships around full-stack telemetry providers bundling sensor procurement with cloud analytics contracts.
Germany
Automotive and machinery OEMs digitize factory floors with dense vibration and thermal sensor meshes for predictive maintenance workflows. The EU Radio Equipment Directive mandates interoperability testing and cybersecurity baselines that favor certified vendors in cross-border tenders. Industrial clusters in Bavaria and Baden-Württemberg deploy edge computing nodes to reduce latency for safety-critical production line monitoring.
South Korea
Metropolitan governments bundle NB-IoT connectivity with cloud analytics contracts to reduce vendor fragmentation in smart city deployments. MFDS-aligned supply chain audits are becoming de facto requirements for healthcare and critical infrastructure procurement. Seoul Capital Area foundries concentrate MEMS capacity expansion for ultra-low-power environmental sensing modules.
China
Environmental bureaus deploy dense urban sensor grids under dual carbon goals monitoring requirements for air quality and radiation compliance dashboards. MIIT standardization efforts accelerate hardware certification cycles for unlicensed spectrum devices. Yangtze River Delta manufacturing bases supply LoRaWAN soil probes to Brazilian soybean operations where cellular coverage gaps persist.
Japan
Industrial automation buyers source multi-protocol radio cores unifying LoRaWAN and BLE stacks for smart building lighting control systems. METI efficiency standards push manufacturers toward energy-harvesting vibration and photovoltaic modules. Kanto region electronics fabricators supply Zigbee mesh networking components for 65,000-node industrial floor deployments.
Wireless IoT Sensors Market Competitive Environment
Vertically integrated semiconductor conglomerates and modular chipset specialists split the market along protocol agility versus captive fabrication lines. Consolidation pressure concentrates around radio architecture decisions migrating from discrete hardware toward software-defined transceivers. Three archetypes dominate: captive foundry operators controlling die yields, multi-protocol firmware houses, and edge computing integrators capturing telemetry margin pools. Competitive moves center on MEMS foundry capacity expansion and strategic partnerships bundling hardware procurement with cloud analytics contracts.
Within the captive fabrication tier, Bosch exemplifies vertical control over environmental sensing node production through in-house semiconductor operations. STMicroelectronics occupies a position representing multi-protocol radio core development across unified LoRaWAN and BLE stack architectures. NXP sits within the automotive-grade qualification specialist archetype, extending industrial sensor portfolios into fleet telematics certification programs. These three anchors illustrate how geographic regulatory alignment and manufacturing control determine competitive positioning.
| Leading Market Players |
|---|
| Analog Devices |
| onsemi |
| Bosch |
| Disruptive Technologies |
| Polysense Technologies |
| NXP |
| STMicroelectronics |
| Sensative |
| Infineon |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port congestion feeds directly into module cost spreads between German automotive OEMs and Brazilian agricultural buyers, compressing margins for LoRaWAN gateway suppliers while amplifying price premiums for ISO/IEC 27001-certified healthcare telemetry providers.
Pricing Analysis
German industrial corridors command 40-60% premiums over Brazilian agricultural deployments for identical LoRaWAN vibration sensors. Three-tier pricing structure across automotive-grade qualification, standard industrial certification, and economy agriculture tiers separates buyers by cybersecurity audit requirements and gateway bundling intensity. Cost compression in the agriculture tier intensifies as solar-harvesting modules commoditize, while healthcare systems show lowest price sensitivity due to cold-chain liability exposure.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for radio module vendors. MEMS fabrication concentrates in South Korea, Taiwan, and China's Yangtze River Delta, drawing from specialty silicon wafers, sub-gigahertz RF front-ends, and REACH-compliant potting compounds. Single-source vulnerability in BLE protocol stack licensing forces contingency planning. Distribution runs through authorized component distributors to system integrators bundling cloud analytics contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as the primary defensive moat, where EU Radio Equipment Directive certification timelines and automotive-grade qualification programs lock out unqualified competitors for eighteen to thirty-six month windows.
For Market Incumbents: Pre-empt modular chipset vendors by accelerating MEMS foundry capacity expansion in Seoul Capital Area corridors and capturing ISO/IEC 27001-aligned audit pipelines before healthcare procurement departments finalize vendor shortlists. Threat substitution from software-defined transceivers demands firmware architecture retooling. Certification investment remains the priority lever for cross-border industrial automation tenders. For New Entrants and Emerging Players: Rural agricultural telemetry in Brazil's Mato Grosso soybean belt offers the most penetrable white-space, where cellular coverage gaps persist and solar-harvesting LoRaWAN probes face minimal incumbent saturation. Target hospital asset tracking systems in secondary United States metro corridors where BLE refresh cycles run annual and security patch urgency creates vendor switching opportunities. Go-to-market through regional system integrators bundling cloud analytics contracts reduces direct certification burden. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-protocol firmware houses with unified LoRaWAN and BLE stack capabilities over discrete hardware specialists. Long-term viability across the projection horizon hinges on edge computing integration depth and cloud analytics contract attach rates. Acquisition target archetype: modular chipset vendors with ITU-standardized certification pipelines. The inflection signal to watch is ITU compression of hardware validation cycles below six months accelerating socket share migration.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Seoul Capital Area investments shorten lead times for ultra-low-power environmental sensing nodes serving German automotive OEMs. |
| Multi-Protocol Firmware Unification | Unified LoRaWAN and BLE stacks capture procurement preference from smart building integrators facing protocol fragmentation costs. |
| Edge Computing Node Deployment | Local telemetry processing captures margin pools as German machinery OEMs reduce backhaul costs for vibration anomaly detection. |
| ISO/IEC 27001 Supply Chain Certification | Healthcare procurement departments mandate aligned audits for cold-chain integrity sensors in United States hospital networks. |
| Software-Defined Transceiver Migration | Radio architecture shift from discrete hardware accelerates time-to-market for ITU-standardized certification cycles under six months. |
Study Parameters
Initial hypotheses were tested against primary input from IoT platform engineering directors, industrial automation procurement leads, MEMS foundry operations managers, and healthcare biomedical engineering heads, then refined against secondary validation from FCC Part 15 certification databases, EU Radio Equipment Directive harmonized standards filings, ITU low-power wide-area network technical specifications, and hyperscaler IoT connectivity revenue disclosures. Bottom-up sensor shipment modeling triangulated with top-down enterprise IoT spending estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, modeling volume and value through technology protocol, end-use vertical, deployment architecture, and regional regulatory cluster dimensions. CAGRs derived from segment-level growth trajectory synthesis rather than single-point extrapolation. Forecast inputs included ITU certification cycle compression timelines and REACH substance restriction phase-in schedules affecting sensor housing materials.
Practitioners should monitor ITU standardization velocity, MEMS foundry utilization rates, and EU cybersecurity baseline enforcement stringency for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Spain Digital Thermometer Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
Inductive Encoder Market
Sensors and Controls
Capacitive Pressure Sensor Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Latin America Wireless Sensors Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Global Hazardous Location Thermostats Market
Sensors and Controls
Global Light Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
APAC Chemical Sensors Market