
 Variable Reluctance Sensor Market | 2026-2036
Variable Reluctance Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Variable Reluctance Sensor Market Intelligence
The end-use mix for variable reluctance sensors is shifting towards industrial automation and robotics from its traditional automotive base. This transition creates distinct competitive arenas. Infineon Technologies specializes in integrated sensor solutions for automotive OEMs, particularly for powertrain applications. Honeywell International, Inc. leverages its broad industrial portfolio, while Allegro MicroSystems competes with a focus on magnetic sensor ICs for speed and position sensing.
A variable reluctance sensor is an electromechanical device that measures changes in magnetic reluctance. It operates by detecting the proximity of a ferrous target, generating a voltage output proportional to the change in magnetic flux without requiring external power. Speed sensors constitute the largest segment by sensor type, driven by their extensive use in automotive systems. The transition from analog to digital technology is a key dynamic, enabling more precise signal processing and integration.
Automotive safety mandates, such as those governed by the NHTSA in the United States, necessitate reliable speed and position sensors. Concurrently, CE marking requirements in Europe and China’s GB standards for industrial equipment dictate sensor performance and electromagnetic compatibility. Sensor manufacturers must therefore navigate divergent regional standards while managing the cost pressures inherent in high-volume applications.
Market Dynamics
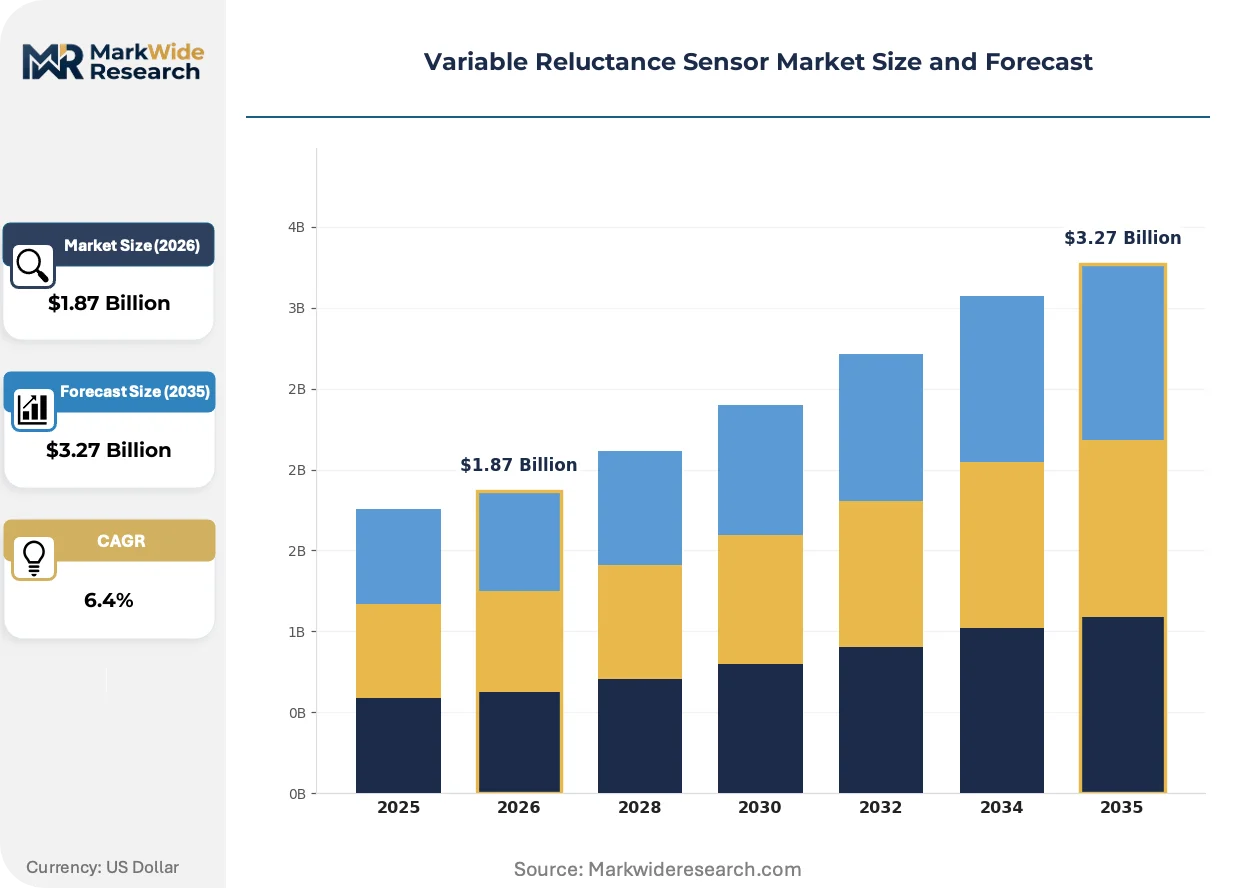
The market's central dynamic is the transition from analog components to intelligent, digital-native sensors. This shift is driven by demand from industrial automation and electric vehicle systems for higher-precision data, self-diagnostics, and seamless integration into digital control networks.
Growth Catalysts
- EU Green Deal Framework:New industrial motor efficiency standards under this framework require more precise speed and position monitoring, directly stimulating demand for high-resolution variable reluctance sensors in factory automation and HVAC systems across Europe.
- Automotive Electrification:The expansion of electric vehicle powertrains creates substantial demand for sensors in traction motor speed control, transmission systems, and anti-lock braking systems, with safety mandates from regulators like the NHTSA reinforcing adoption.
- Advanced Manufacturing Hubs:Production concentration in Chinese manufacturing centers like the Yangtze River Delta fuels requirements for robust sensors in robotics, CNC machinery, and automated assembly lines, where operational uptime is critical.
Market Restraints
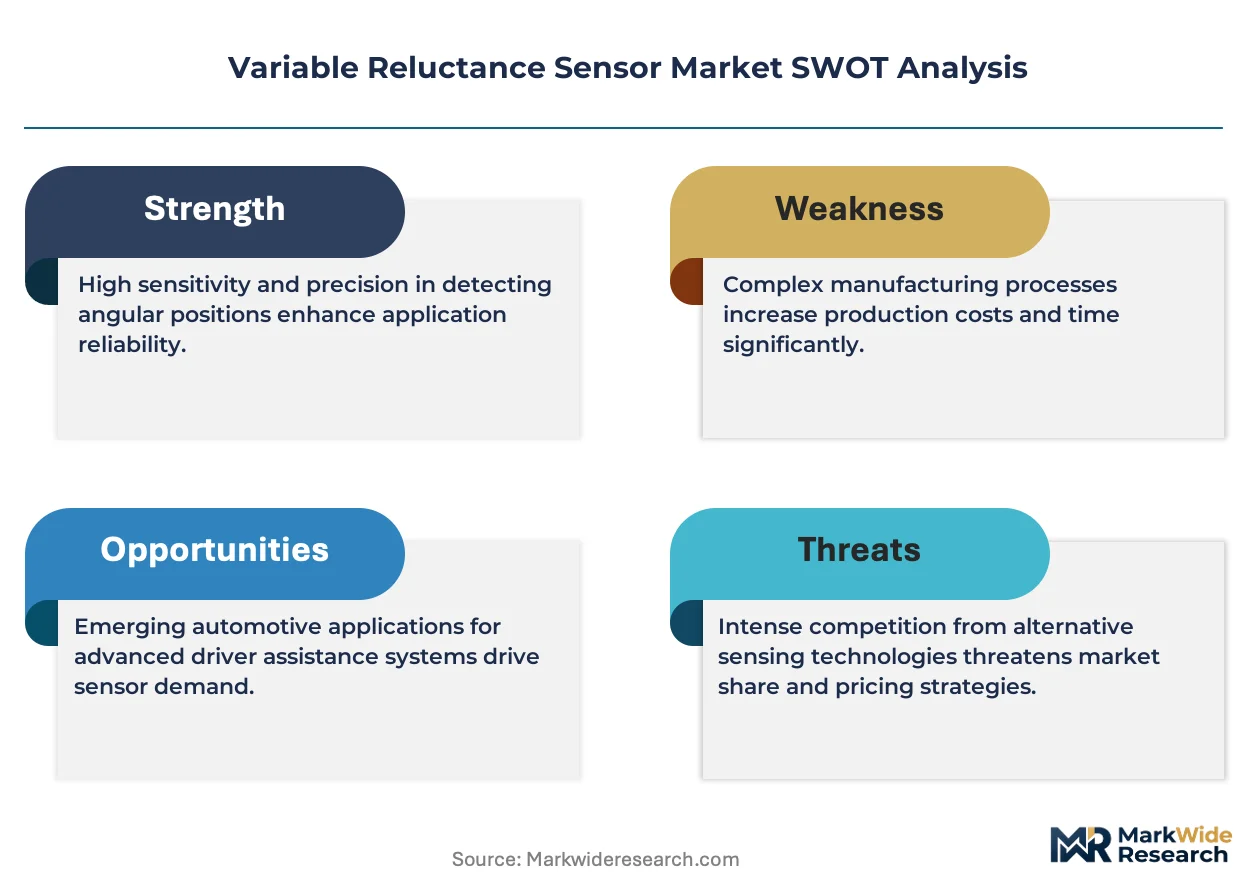
- Substitution from Hall-Effect Sensors:In certain cost-sensitive or low-speed applications, Hall-effect sensors present a viable alternative, challenging the market position of variable reluctance sensors, particularly where simpler digital output is sufficient.
- Inherent Performance Limitations:Variable reluctance sensors generate a weak signal at very low speeds, often requiring complex signal conditioning circuitry, which can be a technical barrier in applications like machine tool positioning or slow-moving conveyors.
- Divergent Regional Standards:Manufacturers face increased design and compliance costs navigating conflicting requirements, such as Europe's CE marking for electromagnetic compatibility and China's separate GB standards for industrial equipment.
Strategic Opportunities
- Predictive Maintenance in IIoT:Integrating sensors into Industrial IoT platforms enables predictive maintenance by monitoring equipment speed and vibration, creating an opportunity in sectors like energy, mining, and heavy manufacturing to reduce downtime.
- Sensor Technology Convergence:The fusion of variable reluctance sensing elements with on-chip digital signal processing (DSP) and wireless connectivity protocols opens new applications in smart infrastructure and remote asset monitoring where cabling is impractical.
- Domestic Manufacturing Incentives:Policies like the US Inflation Reduction Act (IRA) encourage domestic production of electric vehicles and their components, creating a significant opportunity for sensor suppliers to establish or expand manufacturing within North America.
Industry Challenges
- Legacy System Integration:A significant installed base of industrial machinery relies on analog control systems, presenting a challenge for manufacturers to ensure backward compatibility or to convince end-users to undertake costly system-wide digital upgrades.
- Complex Certification Pathways:Achieving compliance with multiple international and regional standards, including automotive safety integrity levels (ASIL) and industrial functional safety (SIL), involves lengthy and expensive testing and documentation processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Variable Reluctance Sensor Market |
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.27 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Angular Position Sensors, Linear Position Sensors, Speed Sensors, Proximity Sensors Application: Automotive Systems, Industrial Automation, Robotics, Consumer Electronics End User: Manufacturers, Research Institutions, Automotive OEMs, Electronics Developers Technology: Analog Technology, Digital Technology, Wireless Technology, Integrated Sensors |
| Companies Covered | Sensoronix, ACDelco, Honeywell International, Inc., ON Semiconductor, HarcoSemco, Allegro MicroSystems, Delphi, Infineon Technologies, Texas Instruments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Variable Reluctance Sensor Market Strategic Shifts & Innovations
The fundamental push for higher data fidelity and system intelligence is transforming variable reluctance sensors from simple electromechanical components into critical nodes in digital ecosystems. This evolution is driven by specific advancements in semiconductor integration, regulatory pressures, and shifting procurement models.
Integrated sensor ICs, which combine a sensing element, signal conditioning, and processing logic on a single silicon die, are a key product evolution. The automotive and industrial automation sectors are rapidly adopting these devices for their improved noise immunity and reliability. This high level of integration is rewriting the sensor's value proposition from a passive component to a smart subsystem, compressing the bill of materials for OEMs.
China's GB standards for industrial equipment and vehicles mandate stringent electromagnetic compatibility (EMC) and performance levels. This regulatory pressure forces sensor manufacturers to develop and validate products specifically for the Chinese market, impacting design cycles and testing protocols. The industrial motor and EV powertrain segments are most affected, requiring localized engineering to secure market access and ensure compliance.
Industrial OEMs are increasingly moving toward sourcing pre-validated sensor subsystems rather than purchasing discrete components. This shift disrupts the business model of traditional component distributors, favoring suppliers that offer application-specific engineering support and integrated solutions. This trend is highly visible in the robotics and automated guided vehicle (AGV) sectors, where rapid system development is a key competitive advantage.
Variable Reluctance Sensor Market Segmentation
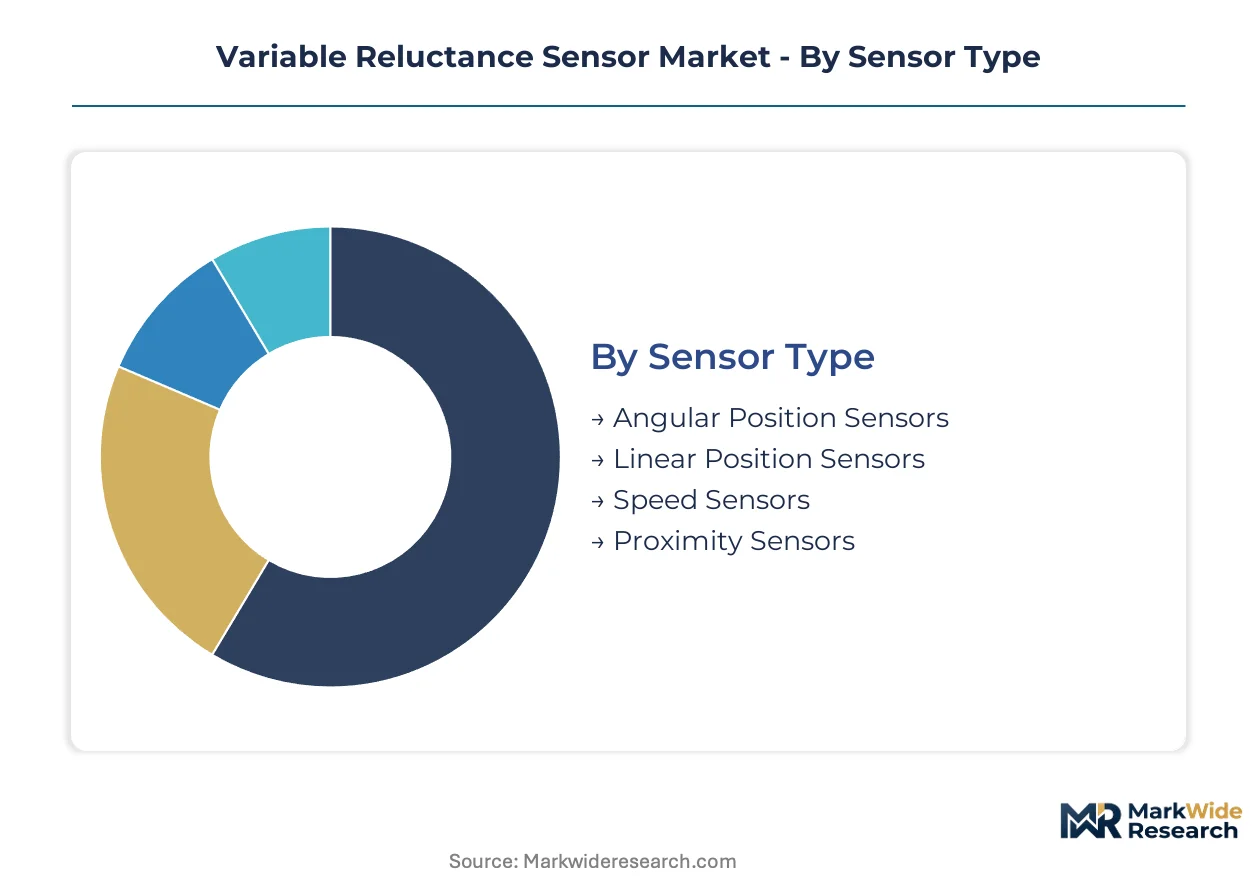
The Variable Reluctance Sensor market is analyzed across several dimensions, reflecting the diverse technical requirements and application landscapes. Understanding these segmentation nuances is crucial for identifying pockets of demand and tailoring product development. This detailed breakdown highlights specific growth vectors within the broader market.
Sensor Type:
The functional specification of variable reluctance sensors defines their primary application in motion control and position feedback systems.
- Speed Sensors:These devices detect rotational or linear speed by measuring the frequency of changes in magnetic flux from a ferrous target. Demand for speed sensors in automotive systems is accelerating, particularly for traction motor control in electric vehicle powertrains.
- Angular Position Sensors:These sensors precisely determine the rotational angle of a shaft or component within industrial automation machinery. New industrial motor efficiency standards under the EU Green Deal require more precise angular position monitoring.
- Linear Position Sensors:These sensors measure linear displacement, crucial for hydraulic cylinder control and automated manufacturing processes.
- Proximity Sensors:These devices detect the presence or absence of objects, commonly used in factory automation for material handling and safety.
Mature deployment sits with Speed Sensors. Newer deployment is concentrated in Angular Position Sensors.
Application:
The end-use environment for variable reluctance sensors dictates specific performance and reliability standards.
- Automotive Systems:This segment includes applications in anti-lock braking systems, transmission speed sensing, and camshaft/crankshaft position monitoring. Automotive electrification creates substantial demand for these sensors in new EV powertrain architectures.
- Industrial Automation:Sensors in this sector enable precise control of robotics, CNC machinery, and automated assembly lines. Production concentration in Chinese manufacturing hubs fuels requirements for robust sensors in these critical industrial applications.
- Robotics:Variable reluctance sensors provide essential speed and position feedback for robotic arms and mobile platforms in manufacturing.
- Consumer Electronics:This segment includes limited use in specific consumer devices requiring robust, non-contact speed or position detection.
Demand in Automotive Systems represents the fastest-growing trajectory.
End User:
The procurement patterns of various end-user types influence sensor design and distribution channels.
- Automotive OEMs:These companies integrate variable reluctance sensors directly into vehicle components and systems, often requiring custom designs and rigorous validation. Safety mandates from regulators like the NHTSA reinforce sensor adoption in new vehicle platforms.
- Manufacturers:This broad category includes industrial equipment producers, aerospace firms, and heavy machinery makers, sourcing sensors for integration into their final products. Cost pressures inherent in high-volume applications drive procurement decisions for these manufacturers.
- Research Institutions:These entities utilize variable reluctance sensors for experimental setups, prototyping, and fundamental studies in material science or mechanical engineering.
- Electronics Developers:This group designs and builds electronic control units and embedded systems, incorporating sensors for specific functional requirements.
Volume procurement largely originates from Manufacturers.
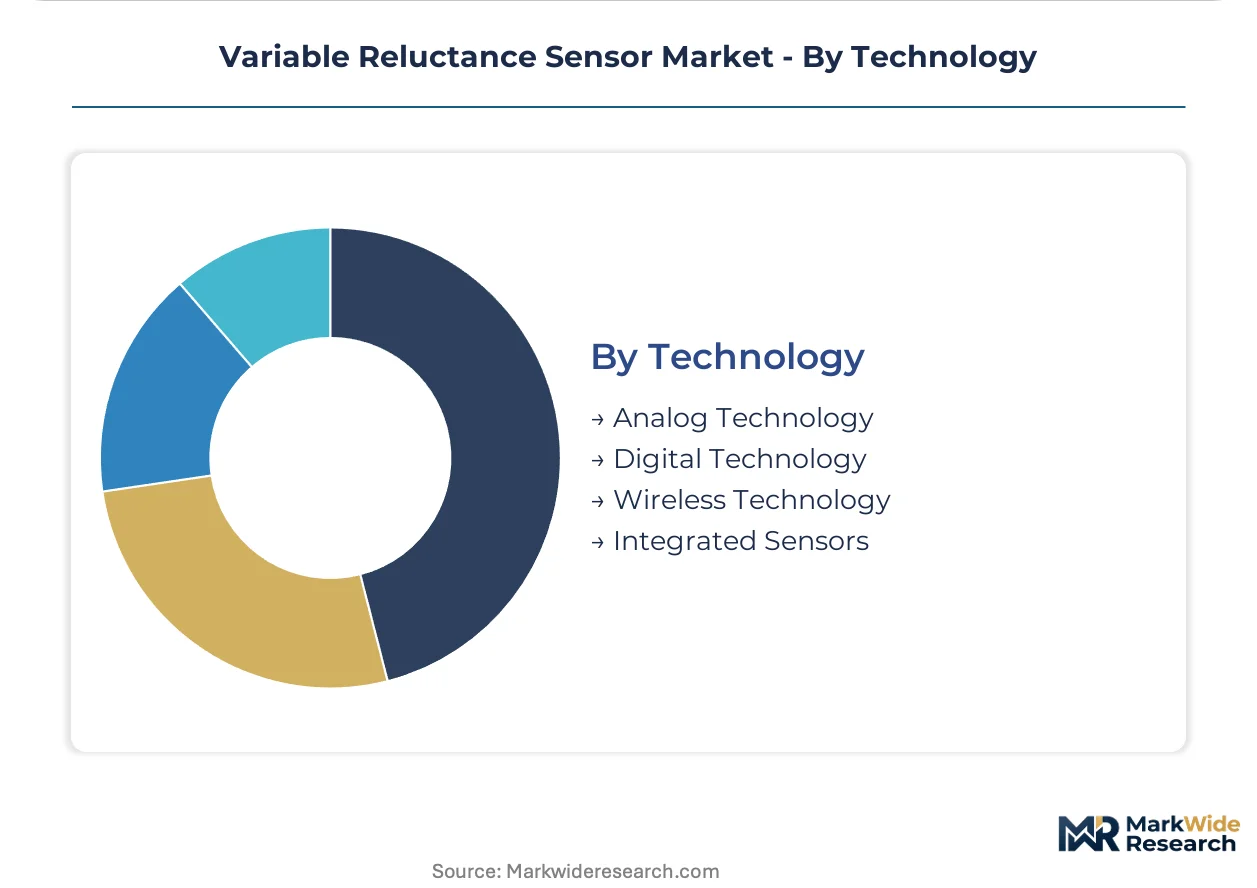
Technology:
The level of technological integration defines sensor capabilities and signal processing sophistication.
- Digital Technology:These sensors output a digital signal, enabling more precise signal processing and seamless integration into digital control networks. The market's central dynamic is the transition towards intelligent, digital-native sensors for higher-precision data.
- Integrated Sensors:These solutions combine sensing elements with on-chip signal conditioning and processing logic on a single die. This high level of integration improves noise immunity and reliability, compressing the bill of materials for OEMs.
- Analog Technology:Traditional analog sensors generate a voltage output proportional to flux change, often requiring external signal conditioning circuitry.
- Wireless Technology:These sensors incorporate wireless communication protocols, allowing remote asset monitoring where physical cabling is impractical or costly.
Advancements in Integrated Sensors are displacing traditional Analog Technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region drives significant sensor demand, acting as a global manufacturing hub. This concentration influences regional market dynamics for variable reluctance sensors. Demand for these sensors is accelerating in key industrial and automotive sectors.
China
Demand for robust sensors in China stems from extensive robotics and CNC machinery applications. China’s GB standards for industrial equipment dictate stringent performance and electromagnetic compatibility requirements. The Yangtze River Delta region, a major manufacturing hub, sees high sensor integration into automated assembly lines.
United States
Automotive electrification and safety mandates from the NHTSA create substantial demand for variable reluctance sensors in the United States. The US Inflation Reduction Act encourages domestic production of EV components, stimulating local sensor manufacturing. Michigan’s automotive corridor integrates these sensors into new vehicle platforms and industrial machinery.
Germany
Industrial motor efficiency standards under the EU Green Deal significantly boost demand for high-resolution variable reluctance sensors in Germany. CE marking requirements ensure sensor performance and electromagnetic compatibility for European markets. Bavaria and Baden-Württemberg, centers for advanced manufacturing, integrate these sensors into factory automation and automotive systems.
Japan
Precision machinery and industrial robotics drive demand for advanced variable reluctance sensors across Japan. METI industrial policies promote high-efficiency manufacturing, requiring sophisticated speed and position feedback. The Kanto region, including Tokyo, and the Chubu region, home to major automotive manufacturers, heavily utilize these sensors.
India
The expanding automotive manufacturing sector and new industrial equipment drive sensor demand in India. The PLI scheme for automotive components encourages local production and technological integration. Maharashtra and Tamil Nadu, key industrial states, integrate variable reluctance sensors into vehicle systems and automated production lines.
Variable Reluctance Sensor Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the variable reluctance sensor market. The competitive landscape features both large diversified electronics firms and specialized sensor manufacturers. Strategic archetypes include integrated solution providers focusing on full system integration, component manufacturers offering discrete sensing elements, and application-specific developers targeting niche industrial uses. Companies pursue portfolio diversification and strategic partnerships to expand their market reach and leverage new technological advancements.
Providers of integrated sensor solutions, such as Infineon Technologies, exemplify the trend towards combining sensing elements with processing logic on a single die for automotive OEMs. These firms offer advanced solutions that improve noise immunity and reliability in critical powertrain applications. Honeywell International, Inc. occupies a position among diversified industrial conglomerates, leveraging its broad portfolio to integrate variable reluctance sensors into various industrial automation applications. Allegro MicroSystems, Inc. sits within the specialized magnetic sensor IC segment, anchoring solutions for speed and position sensing in high-volume applications across diverse end-use sectors.
| Leading Market Players |
|---|
| Sensoronix |
| ACDelco |
| Honeywell International, Inc. |
| ON Semiconductor |
| HarcoSemco |
| Allegro MicroSystems |
| Delphi |
| Infineon Technologies |
| Texas Instruments |
Cost & Logistics Intelligence
Vertical integration into component manufacturing anchors both the supply position and the pricing power for leading variable reluctance sensor firms. This strategic choice allows companies to control critical aspects of production, influencing cost structures and market competitiveness.
Pricing Analysis
Premium pricing for short lead times and specialized configurations drives revenue, while discounts apply to high-volume, standard inventory. Per-unit transactional pricing dominates this market, reflecting the component nature of variable reluctance sensors. Price differentiation stems from quality grade, such as ASIL certification for automotive applications, and the overall volume scale of procurement. Pricing pressure stems from the inherent cost sensitivity of high-volume applications, particularly within the automotive systems segment. Manufacturers, especially Automotive OEMs, exhibit the highest price sensitivity, contrasting with Research Institutions that prioritize technical specifications over cost.
Supply Chain Analysis
Rigorous certification and qualification gating define the entry barriers and structure the variable reluctance sensor supply chain. Geographic supply concentration centers in China, particularly the Yangtze River Delta, alongside advanced manufacturing hubs in Germany and the United States. The supply chain draws from critical magnetic materials like neodymium and iron, alongside specialized semiconductor wafers. Single-source vulnerability for highly integrated sensor ICs represents a key supply chain risk. Distribution runs through direct sales channels to large Automotive OEMs and specialized electronics distributors serving smaller industrial manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is in a technology-transition phase, with integrated sensor ICs rapidly displacing traditional analog variable reluctance sensors. This evolution demands strategic adjustments across the value chain.
For Market Incumbents: Hedge against the threat of substitution from Hall-effect sensors by accelerating investment in digital signal processing capabilities for integrated sensor ICs. Secure long-term supply agreements for critical magnetic materials to mitigate commodity price volatility. Invest in achieving global compliance certifications, such as CE marking and China’s GB standards, to maintain market access and differentiation in core automotive and industrial segments.
For New Entrants and Emerging Players: Underserved smaller manufacturers in niche industrial automation applications present a viable entry point. Target smart infrastructure projects requiring wireless connectivity and robust environmental resilience. Offer pre-validated sensor subsystems with application-specific engineering support, particularly for emerging markets like India's expanding industrial base. Focus on rapid prototyping and flexible manufacturing to cater to specialized, lower-volume demands.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized sensor technology firms with strong intellectual property in digital signal processing and advanced integration. The market demonstrates long-term viability for the next 5-10 years, driven by electric vehicle powertrains and industrial automation. Acquisition targets should include companies possessing unique compliance expertise for divergent regional standards, such as those in Europe or China. A key signal to watch is the increasing adoption rates of integrated sensor ICs within new vehicle platforms and advanced robotics systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Integrated Sensor ICs | This enhances sensor reliability and noise immunity for critical automotive powertrain applications. |
| Secure Long-Term Material Contracts | Such agreements stabilize input costs for magnetic materials and reduce supply chain risk for manufacturers. |
| Expand Regional Certification Expertise | Achieving compliance with diverse standards like CE marking and GB standards ensures market access in key geographies. |
| Develop Application-Specific Subsystems | This strategy caters to industrial OEMs seeking pre-validated solutions for robotics and automated guided vehicles. |
| Target Wireless Sensor Integration | This opens new opportunities in remote asset monitoring and smart infrastructure where cabling is impractical. |
Research Approach
Independent corroboration across primary interviews, secondary data sources, and internal quantitative models underwrites the qualitative findings within this analysis. The research involved discussions with Automotive OEM engineers, industrial automation procurement leads, sensor R&D directors, and regulatory compliance specialists. Secondary validation drew from NHTSA safety reports, EU Green Deal policy documents, China’s GB standards, and company financial filings, triangulating bottom-up and top-down market estimates.
Comparable historical periods anchored the forecast window, establishing a baseline for future projections across the analysis window. The analytical framework integrated detailed segmentation dimensions, including sensor type, application, end-user, technology, and regional production clusters. Compound annual growth rates were derived from statistical analysis of historical trends and projected market dynamics, incorporating industry-specific forecast inputs such as global electric vehicle production forecasts and industrial automation investment patterns.
Revisions become necessary when unforeseen technological disruptions or major shifts in global trade policies materialize. Forecasts reflect assumptions regarding market growth drivers and competitive dynamics. A model refresh is warranted upon material change in automotive electrification rates or industrial efficiency mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Asia-Pacific MEMS and Sensors Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
US Wireless Sensors Market
Sensors and Controls
Fiber Bragg Grating Sensor Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Electrochemical Sensor Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Pressure Sensor Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Europe Optical Sensors Market
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Air Quality Monitoring System Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Industrial Wireless Sensor Market