
 Thermoformed Skin Packaging Market | 2026-2036
Thermoformed Skin Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoformed Skin Packaging Market Analytics
Polyethylene terephthalate (PET) is repositioning polyvinyl chloride (PVC) across fresh protein and medical device applications, driven by recyclability mandates and optical clarity requirements. Sealed Air leverages its global film extrusion network to sustain premium positioning in healthcare barrier films. Berry Global Group anchors North American supply through captive resin compounding and thermoforming asset density. Klöckner Pentaplast competes on pharmaceutical-grade calendering expertise and cleanroom-certified rollstock production.
Thermoformed skin packaging denotes a vacuum-sealing process where a heated plastic film drapes over a product and substrate card, creating a transparent, tamper-evident enclosure with typical film gauges of 75–250 microns and seal strengths exceeding 3 N/15mm for medical applications. The primary purpose centers on product visibility, contamination resistance, and extended shelf stability for retail and institutional distribution. Blister packs dominate pharmaceutical compliance dosing, while trays capture the fastest expansion in automated retail meat case stocking. PET rollstock commands margin concentration due to rPET integration complexity and EFSA food-contact certification burdens.
FDA 21 CFR Part 177 governs indirect food additive thresholds for olefin and polyester films, while EPA guidelines on fluorinated greenhouse gases constrain high-barrier multilayer constructions. REACH and the EU Green Deal mandate recyclability disclosures and recycled content minimums, redirecting capital toward mono-material lines and chemical recycling partnerships. Stakeholders must monitor evolving extended producer responsibility schemes and decide between retrofitting existing thermoformers for thinner-gauge operation or investing in all-electric reheat stretch machines.
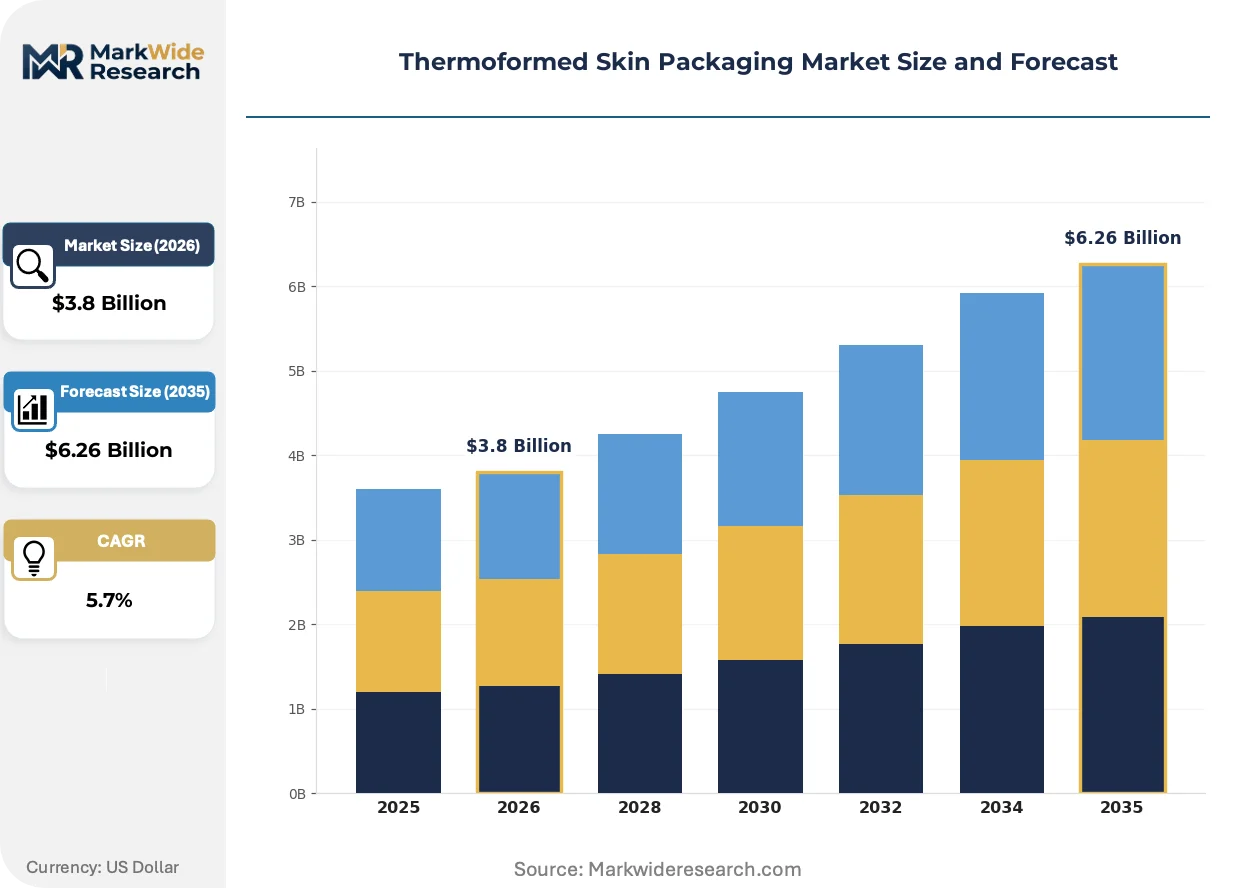
Market Dynamics
Mono-material PET structures are compressing multilayer film architectures as Europe's F-Gas Regulation and REACH compliance force recyclability redesigns across protein retail and medical device packaging. Machinery integration with thermoforming lines in Germany's industrial corridor is creating cluster advantages that reshape competitive positioning.
Growth Catalysts
- Vacuum-sealed tray adoption:Food processors are expanding thermoformed skin formats for protein retail display, driven by automated meat case stocking requirements and extended shelf stability demands.
- REACH and EU Green Deal mandates:Recyclability disclosures and recycled content minimums redirect capital toward mono-material lines and chemical recycling partnerships.
- Healthcare barrier film specifications:Medical device manufacturers require seal strengths exceeding 3 N/15mm and cleanroom-certified rollstock, creating premium positioning for compliant suppliers.
Market Restraints
- rPET integration complexity:EFSA food-contact certification burdens and optical clarity requirements constrain margin concentration for recycled content rollstock.
- Fluorinated greenhouse gas constraints:EPA guidelines limit high-barrier multilayer constructions, forcing redesign of legacy barrier film portfolios.
- Film gauge standardization:Typical 75–250 micron specifications create technical limitations for ultra-thin gauge applications in pharmaceutical compliance dosing.
Strategic Opportunities
- Chemical recycling partnerships:Mono-material PET investments align with extended producer responsibility schemes emerging across EU member states.
- All-electric reheat stretch machinery:Equipment suppliers can wedge into retrofit decisions as processors choose between thinner-gauge operation and full line replacement.
- Pharmaceutical-grade calendering:Cleanroom-certified production capabilities remain scarce, creating white space for specialized rollstock manufacturers.
Industry Challenges
- Retrofit versus greenfield capex decisions:Existing thermoformer fleets require significant capital for mono-material compatibility, straining mid-tier processor balance sheets.
- Cross-regulatory compliance timelines:Simultaneous FDA 21 CFR Part 177, REACH, and F-Gas alignment creates certification bottlenecks for multinational film suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoformed Skin Packaging Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Clamshell Packs, Trays, Folded Skin Packs Material: Polypropylene, PVC, PET, Polystyrene Industry Vertical: Food & Beverage, Healthcare, Consumer Goods, Electronics Form: Sheet, Rollstock, Custom Die-Cut, Pre-formed |
| Companies Covered | G. Modini, ULMA Group, DRADER Manufacturing Industries Ltd., SouthPack, Sealed Air, DMD 2000 Ltd., Vinpac Innovations, Berry Global Group, Klöckner Pentaplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoformed Skin Packaging Market Evolving Landscape
Active materials substitution and regulatory redesign are compressing legacy film architectures while reshaping equipment procurement patterns across protein processing and healthcare packaging.
PET rollstock is overtaking PVC across fresh protein and medical device applications due to superior optical clarity and mandated recyclability. Food processors and healthcare manufacturers are accelerating adoption as EFSA certification pathways mature. This material transition is compressing incumbent multilayer suppliers unable to achieve mono-material compliance.
Europe's F-Gas Regulation is forcing abandonment of fluorinated barrier layers in high-performance films. Industrial consequence includes accelerated development of ceramic and silicon oxide barrier coatings. Germany's protein packaging corridor is most affected, with processors redesigning thermoforming lines for non-fluorinated sealant compatibility.
Automated retail meat case stocking is reshaping procurement specifications for tray format standardization. Protein processors are consolidating supplier relationships around integrated film-tray-equipment providers capable of line-speed optimization. This concentration pattern is most visible in Germany's industrial packaging corridor and extending into adjacent Benelux processing clusters.
Thermoformed Skin Packaging Market Segmentation
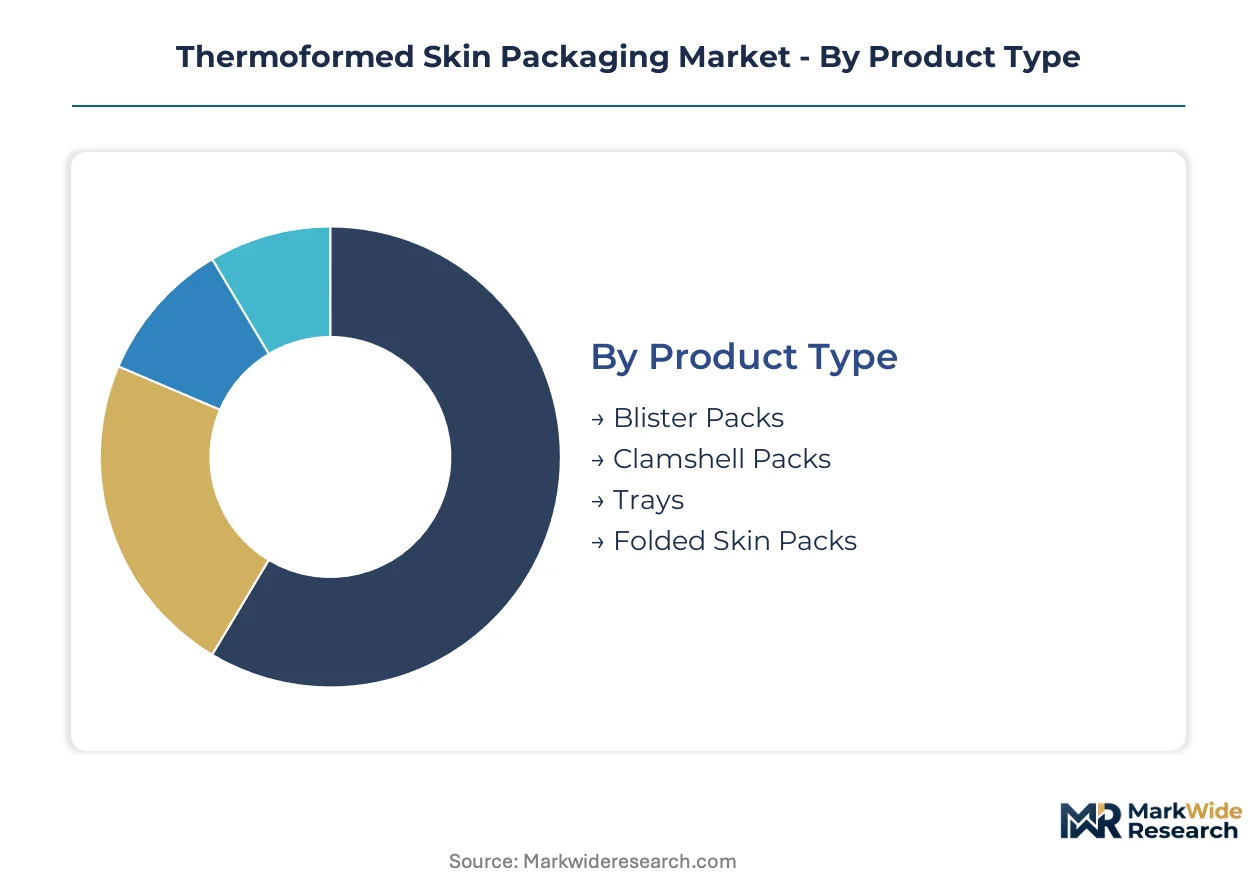
Thermoformed skin packaging segmentation reveals divergent capital requirements across product geometries and material specifications. Equipment selection, tooling complexity, and regulatory compliance burdens vary dramatically by segment, reshaping supplier economics and processor procurement priorities.
Product Type:
Capital intensity peaks with tray formats requiring precision thermoforming lines and integrated vacuum-sealing stations, while blister packs demand pharmaceutical-grade cleanroom infrastructure.
- Trays:Vacuum-sealed tray formats for protein retail display require automated meat case stocking compatibility and extended shelf stability engineering. Protein processors in Germany's industrial corridor are consolidating supplier relationships around integrated film-tray-equipment providers.
- Blister Packs:Pharmaceutical compliance dosing applications mandate seal strengths exceeding 3 N/15mm and cleanroom-certified rollstock production. Medical device manufacturers prioritize tamper-evident enclosures with optical clarity for institutional distribution.
- Clamshell Packs:Hinged designs suit consumer goods visibility requirements with lower tooling investment than sealed formats.
- Folded Skin Packs:Card-backed configurations reduce material gauge for lightweight electronics and hardware applications.
Trays absorb the bulk of installed capacity; blister packs are expanding most quickly.
Material:
Raw material selection drives margin concentration through rPET integration complexity and EFSA food-contact certification burdens, with mono-material compliance redirecting capital flows.
- PET:Polyethylene terephthalate rollstock commands premium positioning due to recyclability mandates and optical clarity requirements. EFSA certification pathways and rPET sourcing complexity constrain mid-tier suppliers.
- Polypropylene:Olefin-based films governed by FDA 21 CFR Part 177 indirect food additive thresholds offer lower barrier performance but simplified regulatory pathways for protein retail applications.
- PVC:Polyvinyl chloride faces displacement across fresh protein and medical device applications as REACH and EU Green Deal mandates accelerate material transitions.
- Polystyrene:Styrene-based structures retain cost advantages in consumer goods clamshells with limited recyclability compliance exposure.
PET captures the steepest expansion trajectory; polypropylene retains the broadest installed base.
Industry Vertical:
End-use concentration determines equipment specification intensity, with healthcare barrier films requiring the most stringent cleanroom and certification infrastructure.
- Healthcare:Medical device packaging demands pharmaceutical-grade calendering expertise and cleanroom-certified rollstock production with barrier film specifications exceeding standard food applications.
- Food & Beverage:Protein retail display drives vacuum-sealed tray adoption with automated meat case stocking requirements reshaping procurement specifications.
- Consumer Goods:Visibility-driven clamshell and blister formats prioritize optical clarity over barrier performance for retail shelf presence.
- Electronics:Static-dissipative formulations and custom die-cut precision suit component protection with lower regulatory compliance burdens.
Food & Beverage dominates volume throughput; Healthcare generates the highest margin concentration.
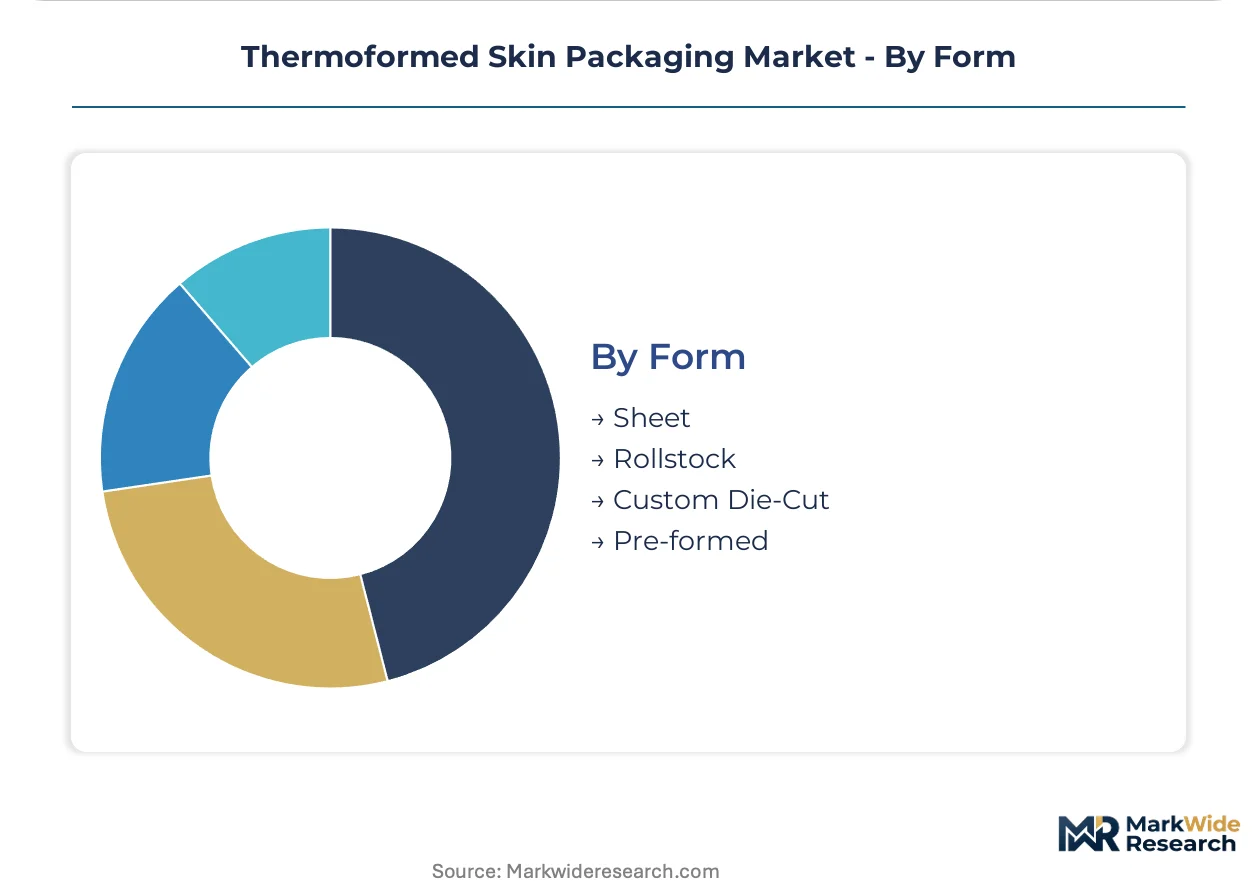
Form:
Upstream integration depth varies by format, with rollstock production requiring captive resin compounding and sheet extrusion assets that strain mid-tier processor balance sheets.
- Rollstock:Continuous film production demands thermoforming line integration and gauge standardization across 75–250 micron specifications for high-speed automated operations.
- Sheet:Flat extruded structures serve custom thermoforming applications with flexible tooling adaptation for shorter production runs.
- Pre-formed:Ready-to-seal containers reduce downstream processor capital requirements but constrain line-speed optimization potential.
- Custom Die-Cut:Precision-cut formats for electronics and medical devices require tight tolerance tooling with higher per-unit conversion costs.
Rollstock anchors supplier revenue; custom die-cut formats are gaining share fastest in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's industrial packaging corridor functions as Europe's primary concentration zone, where machinery integration with thermoforming lines generates cluster efficiencies that attract capital from adjacent Benelux processing centers.
Germany
Protein processors dominate vacuum-sealed tray procurement for automated retail meat case stocking. REACH and the EU Green Deal mandate recyclability disclosures that redirect capital toward mono-material PET lines. The Rhineland industrial corridor hosts integrated film-tray-equipment providers optimizing line-speed performance.
United States
Healthcare barrier film specifications drive cleanroom-certified rollstock demand from medical device manufacturers. FDA 21 CFR Part 177 governs indirect food additive thresholds for polyester films used in protein retail applications. The Midwest packaging belt concentrates thermoforming asset density around captive resin compounding operations.
China
Domestic protein processors expand thermoformed skin formats for fresh meat retail display. SAMR food-contact material standards and dual carbon goals accelerate shifts toward rPET integration in packaging films. The Yangtze River Delta hosts machinery suppliers integrating vacuum-sealing stations with thermoforming lines.
France
Pharmaceutical compliance dosing applications sustain demand for blister packs with seal strengths exceeding medical thresholds. ANSM medical device regulations and EMA quality standards constrain supplier qualification to cleanroom-certified manufacturers. The Île-de-France region anchors pharmaceutical-grade calendering expertise for barrier film production.
India
Food processors adopt vacuum-sealed tray formats for organized retail meat distribution. FSSAI food safety standards and BIS packaging material certifications create compliance pathways for PET rollstock suppliers. Maharashtra's industrial corridor attracts thermoforming equipment investments serving domestic protein processing expansion.
Thermoformed Skin Packaging Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated film-tray-equipment providers commanding premium positioning in protein retail while pharmaceutical-grade specialists capture margin concentration in healthcare barrier films. The vendor base organizes into three strategic archetypes: global film extrusion networks with captive resin operations, regional machinery-integrated system providers, and niche cleanroom-certified rollstock specialists. Capacity expansion and portfolio diversification toward mono-material PET structures represent the dominant competitive moves as regulatory deadlines compress redesign timelines.
Among North American material suppliers, Berry Global Group exemplifies the integrated film extrusion archetype through captive resin compounding density. Sealed Air occupies a position within the healthcare barrier film tier, leveraging global rollstock production networks. Klöckner Pentaplast represents the pharmaceutical-grade specialization vector, with calendering expertise anchoring cleanroom-certified supply positioning. European machinery-integrated providers including ULMA Group and G. Modini sit within the regional system solution tier, bundling thermoforming equipment with film supply relationships. Contract manufacturers such as SouthPack and Vinpac Innovations occupy the service-based fabrication segment, converting rollstock to finished packs without upstream material production.
| Leading Market Players |
|---|
| G. Modini |
| ULMA Group |
| DRADER Manufacturing Industries Ltd. |
| SouthPack |
| Sealed Air |
| DMD 2000 Ltd. |
| Vinpac Innovations |
| Berry Global Group |
| Klöckner Pentaplast |
| Others |
Value Network & Pricing Analysis
Protein processors in Germany's industrial corridor concentrate procurement volumes around integrated film-tray-equipment providers, anchoring a contract-based long-term offtake model that rewards line-speed optimization and penalizes spot-market sourcing.
Pricing Analysis
Short lead-time premiums command significant price elevation as protein processors facing automated meat case stocking deadlines pay premium rates for EFSA-certified PET rollstock delivered within compressed windows. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-grade certification levels separates healthcare barrier film suppliers from commodity converters. Pricing pressure stems from rPET integration complexity constraining mid-tier suppliers unable to achieve optical clarity specifications. Healthcare manufacturers exhibit the least price sensitivity due to cleanroom certification requirements, while consumer goods clamshell buyers drive aggressive cost compression.
Supply Chain Analysis
Post-consumer PET collection and chemical recycling flows are emerging as critical reverse-logistics infrastructure supporting mono-material compliance mandates across European protein packaging. Raw material sourcing draws from Germany, Belgium, and the Netherlands for virgin PET resin, with rPET feedstock increasingly tethered to domestic collection systems. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade calendering expertise concentrated among limited cleanroom-certified manufacturers. Distribution runs through integrated film-tray-equipment providers in Germany's Rhineland corridor serving automated retail meat case stocking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory deadlines compressing redesign timelines for F-Gas and REACH compliance are forcing mid-tier processors toward exit or acquisition, consolidating market share among integrated suppliers with captive resin and thermoforming assets.
For Market Incumbents: Deploy pharmaceutical-grade calendering certification as a defensive moat against commodity PET converters encroaching on healthcare barrier film margins. Incumbents should accelerate mono-material PET line investments ahead of EU Green Deal recycled content minimums while acquiring distressed mid-tier processors unable to fund thermoformer retrofits. The threat of emerging Asian machinery suppliers bundling low-cost equipment with film supply relationships demands preemptive channel control through exclusive line-speed optimization partnerships. For New Entrants and Emerging Players: The gap between premium healthcare barrier films and economy-grade consumer goods clamshells offers entry space for specialized rPET converters achieving EFSA certification without legacy multilayer equipment burdens. New entrants should target India's Maharashtra industrial corridor where FSSAI compliance pathways remain less saturated than European markets. A contract manufacturing model converting imported rollstock to finished vacuum-sealed trays for domestic protein processors minimizes upstream capital requirements while building customer relationships. For Investors and Strategic Acquirers: The window for entry favors cleanroom-certified rollstock specialists with pharmaceutical-grade production capabilities as healthcare packaging generates sustained margin concentration. Acquisition targets should demonstrate established EFSA or FDA 21 CFR Part 177 certification pathways and thermoforming line integration relationships with protein processors. Investors should monitor chemical recycling partnership announcements as inflection indicators for rPET supply security and mono-material compliance positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material PET Line Conversion | REACH and F-Gas compliance deadlines force abandonment of fluorinated multilayer architectures by protein processors. |
| Chemical Recycling Partnership | Extended producer responsibility schemes in EU member states create rPET supply security for EFSA-certified rollstock. |
| Cleanroom Certification Investment | ANSM and EMA quality standards constrain pharmaceutical barrier film supply to qualified manufacturers. |
| All-electric Reheat Stretch Machinery Deployment | Equipment suppliers capture retrofit decisions as processors choose between thinner-gauge operation and full replacement. |
| Integrated Film-tray-equipment Bundling | Germany's industrial corridor rewards suppliers optimizing vacuum-sealing station line-speed performance for automated retail stocking. |
Research Methodology
Multi-period observation of thermoforming line installation rates, rPET integration announcements, and EFSA certification grants anchored the trend analysis, supplemented by interviews with film extrusion plant managers, protein processor procurement leads, pharmaceutical packaging engineers, and thermoforming equipment specialists. Secondary validation drew from FDA 21 CFR Part 177 filings, ECHA REACH registration databases, EU F-Gas Regulation implementation reports, and SEC disclosures from listed packaging material suppliers. Bottom-up capacity estimates triangulated against top-down protein retail display volume projections.
Input-output matrices modeled PET rollstock demand against thermoformed tray production capacity across the analysis window, with segmentation by product type, material specification, industry vertical, and geographic production cluster. CAGRs derived from regression analysis of historical machinery shipment data correlated with protein processing capital expenditure cycles. Forecast inputs included EFSA food-contact certification timeline projections and SAMR standards evolution for Chinese rPET integration.
Inputs from ECHA registration databases and FDA master file submissions were available through the study window; gaps in real-time chemical recycling partnership disclosure introduce uncertainty bands around rPET supply elasticity assumptions. Forecasts reflect documented assumptions regarding regulatory deadline adherence and machinery delivery lead times. Practitioners should monitor EU member state extended producer responsibility scheme implementation schedules and FDA guidance updates on recycled content thresholds for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Sterilization Roll Market
Packaging Materials
Latin America Single-Use Packaging Market
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
Aerosol Packaging Market
Packaging Materials
Bottle Sealing Wax Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Strapping Materials Market
Packaging Materials
Non-Plastic Punnets Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Reel in Box Market
Packaging Materials
Foam Trays Market
Packaging Materials
3D Printed Packaging Market
Packaging Materials
Cork Packaging Market