
 Foam Trays Market | 2026-2036
Foam Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Foam Trays Market Intelligence
The substitution of traditional expanded polystyrene with biodegradable foam alternatives is repositioning product economics for food processors. Huhtamaki Oyj champions this shift with its portfolio of sustainable packaging solutions. In contrast, Dart Container Corporation leverages its extensive manufacturing scale in conventional foam products. Sealed Air Corporation differentiates through high-performance materials for specialized applications like electronics packaging.
Foam trays are lightweight cellular plastic containers manufactured primarily through an extrusion and thermoforming process. Their structure provides essential cushioning, thermal insulation, and a barrier against moisture for perishable goods. While expanded polystyrene continues to lead the product type segment due to its low cost, meat packaging represents the largest application by volume. The demand for biodegradable foam trays shows the highest growth potential among material types.
Regulatory frameworks such as the EU's Single-Use Plastics Directive and FDA food-contact material standards directly influence material selection. In parallel, China's MEE policies on plastic waste reduction accelerate the adoption of recyclable and compostable options. Future market leadership will depend on developing cost-effective, compliant materials that align with regional circular economy goals.
Market Dynamics
The foam trays market is defined by a structural tension between the cost-efficiency of incumbent expanded polystyrene (EPS) and intense regulatory pressure to adopt biodegradable or recyclable alternatives. This dynamic forces producers to balance manufacturing scale against material innovation to meet divergent market demands.
Growth Catalysts
- Regulatory Mandates:The EU's Single-Use Plastics Directive is compelling food service operators and retailers to source compliant alternatives to traditional foam, directly stimulating demand for trays made from biodegradable polymers or recycled content.
- Food Safety in Meat Packaging:Sustained demand from the meat and poultry processing industry for absorbent and insulating trays supports market volume. These trays are essential for maintaining product freshness, minimizing microbial growth, and enhancing retail presentation.
- Cold Chain Expansion in Asia:The rapid development of cold chain logistics and formal grocery retail in countries like China and Vietnam is increasing the consumption of packaged perishable goods, creating a large-scale need for protective foam trays.
Market Restraints
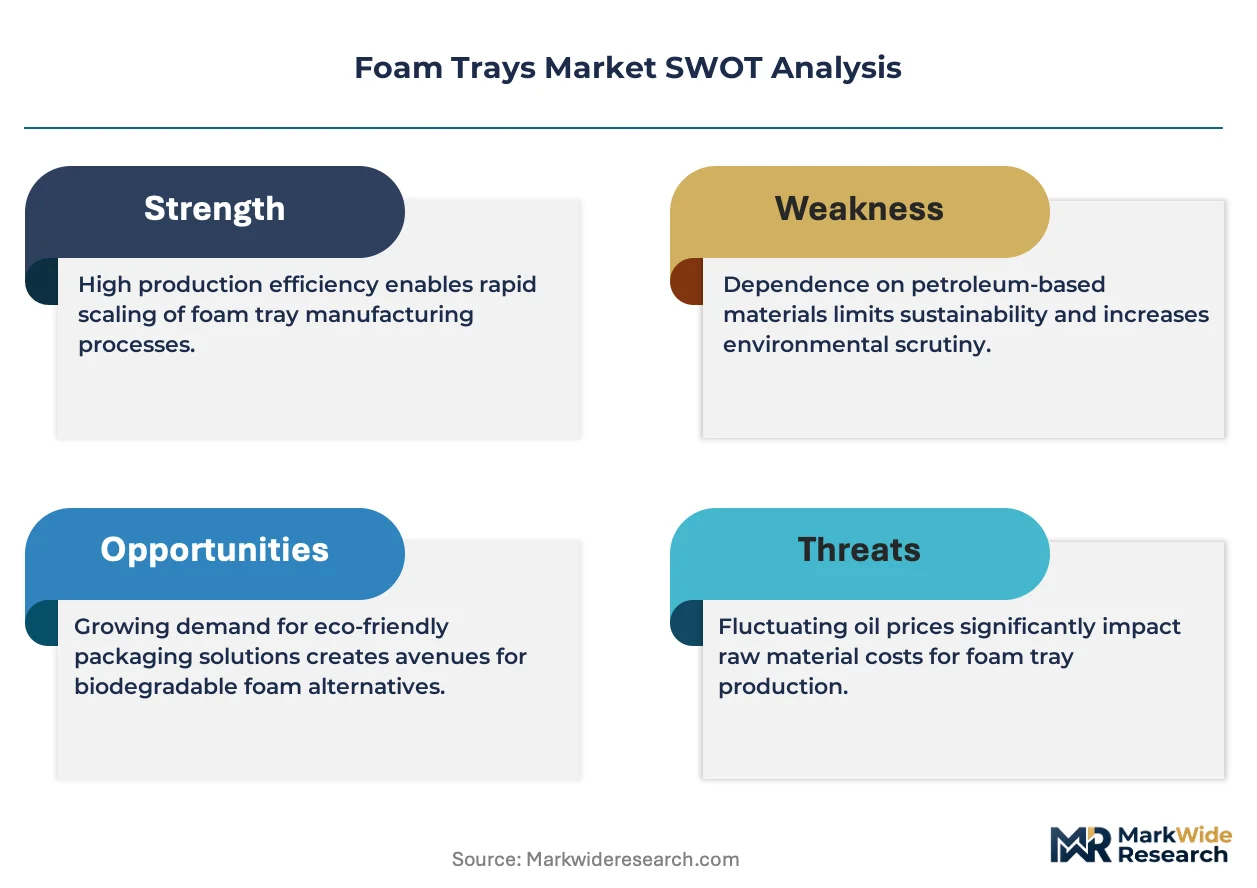
- Petrochemical Price Volatility:The production cost of expanded polystyrene is directly tied to fluctuating prices of styrene monomer, a crude oil derivative. This volatility creates margin uncertainty for manufacturers of conventional foam trays.
- Substitution from Molded Fiber:Molded pulp and fiber-based trays present a significant substitution threat, particularly in fresh produce and food service applications where consumers perceive them as a more environmentally friendly option.
- Fragmented Food-Contact Standards:Navigating disparate food-contact safety regulations, such as those from the FDA in the United States and the EFSA in Europe, adds complexity and cost to material qualification and product development.
Strategic Opportunities
- High-Performance Electronics Packaging:A clear opportunity exists in designing specialized anti-static and shock-absorbent foam trays for the packaging and transport of sensitive semiconductor components, circuit boards, and other electronics.
- Home-Compostable Biopolymers:Developing cost-effective, high-performance bioplastics like advanced PLA or PHA blends that are certified for home composting would meet stringent circular economy goals and unlock a premium market segment.
- Market Entry in Southeast Asia:Underpenetrated markets in Indonesia and the Philippines, characterized by a growing middle class and expanding supermarket infrastructure, offer significant greenfield opportunities for both conventional and sustainable foam tray products.
Industry Challenges
- Recycling Infrastructure Gaps:The lack of segregated collection streams and processing facilities capable of handling post-consumer biodegradable or compostable foam trays hinders the development of a true circular economy for these materials.
- Capital-Intensive Re-tooling:Transitioning manufacturing lines from EPS to newer bioplastics requires significant capital investment in new extrusion and thermoforming equipment calibrated for different material processing parameters.
- Standardization of Eco-Labels:A lack of universally recognized standards and labels for biodegradability and compostability creates confusion for consumers and complicates marketing efforts for manufacturers of sustainable trays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Foam Trays Market |
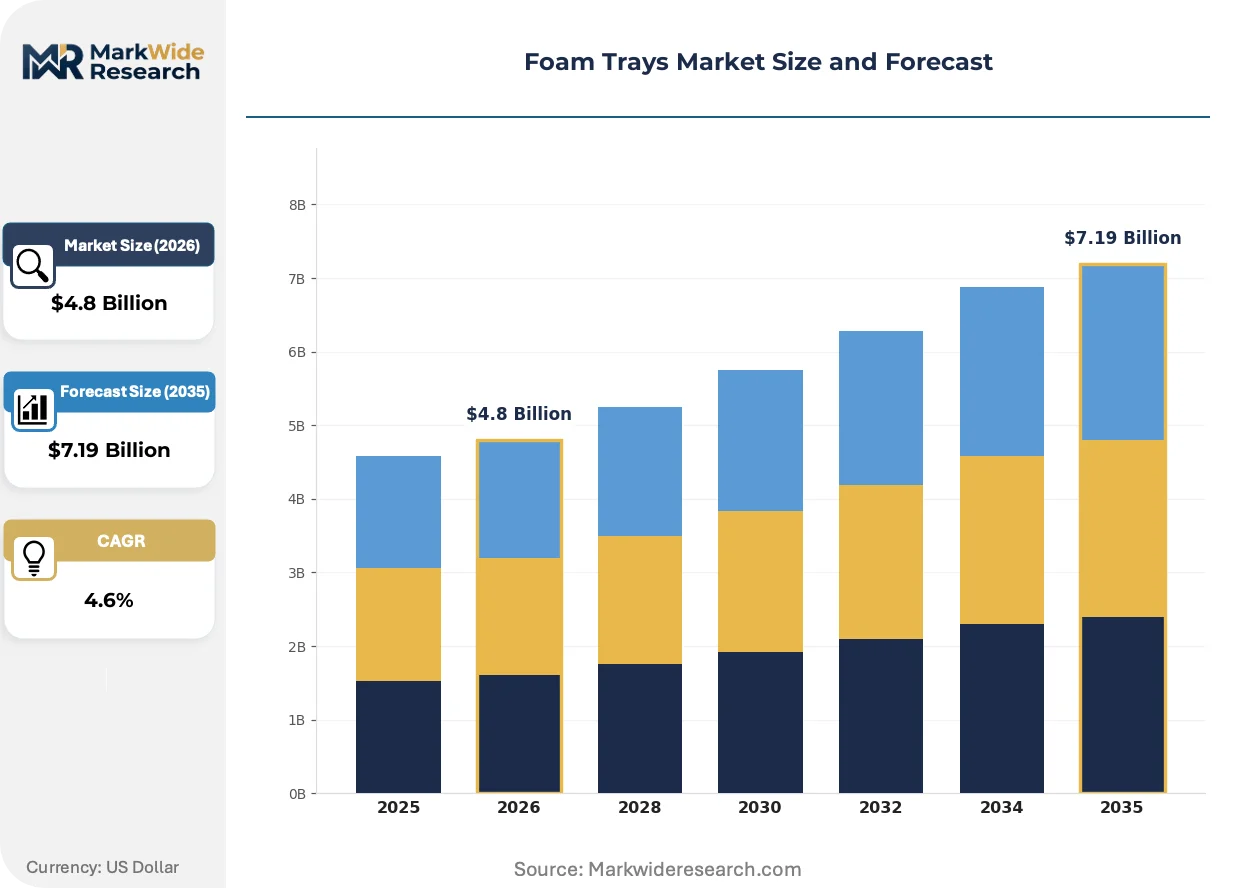
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Polystyrene, Polyethylene, Polypropylene, Biodegradable Foam, Polyurethane Application: Bakery Packaging, Meat Packaging, Fresh Produce Packaging, Electronic Component Packaging, Pharmaceutical Packaging End User: Food Processing Companies, Electronics Manufacturers, Pharmaceutical Producers, Agricultural Exporters, Cosmetic Brands Distribution Channel: Direct Sales, E-Commerce, Wholesale Distributors, Retail Stores, Packaging Suppliers |
| Companies Covered | Dart Container Corporation, Genpak LLC, Huhtamaki Oyj, Pactiv Evergreen Inc., Sealed Air Corporation, Placon Corporation, Anchor Packaging Inc., Berry Global Inc., Novipax LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Foam Trays Market Strategic Shifts & Innovations
Material science innovation is the central theme, driven by a dual mandate to reduce environmental impact while maintaining the performance and cost-effectiveness required by the food packaging industry. This is leading to a portfolio approach where different materials are targeted at specific applications and regulatory environments.
Active packaging technology integrates functional agents directly into the foam tray material. The food and beverage industry, particularly premium meat and seafood processors, is adopting these trays to inhibit spoilage and extend product shelf life. This innovation is modularizing the tray itself, converting it from a passive container into a functional element of the food preservation system.
Policies from China's Ministry of Ecology and Environment (MEE) are accelerating the phase-out of certain single-use plastics. This regulatory action creates a direct commercial consequence, forcing a rapid shift away from disposable EPS foam in the domestic market. The food service and e-commerce delivery sectors are most affected, spurring investment in recyclable polypropylene foam and compostable tray options.
A distinct behavioral shift is evident in how large-scale food processors and retailers select packaging. Buyer decisions are increasingly influenced by on-pack sustainability claims and the verified recyclability or compostability of materials. This disrupts procurement models based purely on unit cost, forcing suppliers to provide clear end-of-life solutions. This trend is highly visible in European grocery retail, where EPR schemes hold producers financially responsible for packaging waste.
Foam Trays Market Segmentation
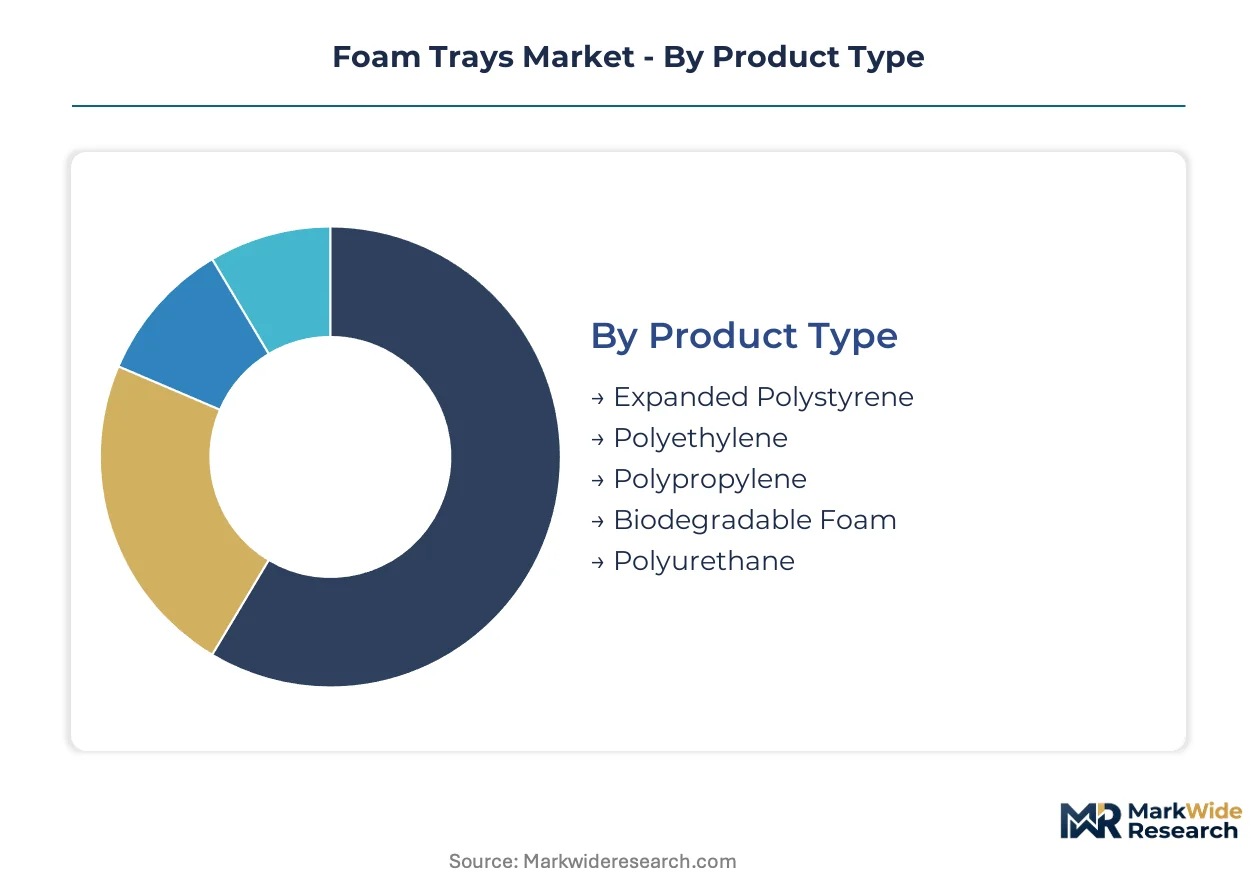
The foam trays market structure reflects a complex interplay of material science, application-specific demands, and evolving regulatory landscapes. Strategic segmentation reveals the underlying drivers of consumption and highlights areas of innovation and competitive differentiation for manufacturers.
Product Type:
Material selection for foam trays is primarily driven by performance requirements, cost constraints, and increasingly, environmental compliance. Each material offers a distinct balance of properties for various packaging needs.
- Expanded Polystyrene:This lightweight cellular plastic offers excellent thermal insulation and cushioning properties at a low cost, making it a prevalent choice for general-purpose food packaging, particularly in meat and produce applications. However, its non-biodegradable nature faces significant regulatory scrutiny in regions like the European Union.
- Biodegradable Foam:Composed of bioplastics or plant-based materials, this segment addresses environmental concerns by offering compostable or naturally degradable alternatives to traditional plastics. Demand for these materials is accelerating due to policies such as China's MEE plastic waste reduction targets and consumer preference for sustainable options.
- Polyethylene:Known for its flexibility, moisture barrier properties, and chemical resistance, polyethylene foam trays find use in specialized packaging where product integrity and protection are paramount.
- Polypropylene:Offering good heat resistance and recyclability, polypropylene foam trays are increasingly adopted in food service and microwaveable applications, providing a more durable alternative to EPS.
- Polyurethane:This material provides superior cushioning and insulation, making it suitable for high-performance applications where impact protection and thermal stability are critical.
Volume sits with Expanded Polystyrene; growth tilts toward Biodegradable Foam.
Application:
The functional requirements of the packaged product dictate specific foam tray designs and material properties across diverse end-uses.
- Meat Packaging:As the largest application segment, meat packaging requires foam trays with excellent absorbency, thermal insulation, and structural integrity to maintain product freshness and prevent microbial growth. These trays are crucial for safe transport and retail presentation in cold chain logistics.
- Electronic Component Packaging:This specialized application demands anti-static, shock-absorbent, and often custom-molded foam trays to protect sensitive components like semiconductors and circuit boards during transit. High-performance materials are essential to prevent physical damage and electrostatic discharge.
- Bakery Packaging:Foam trays in bakery applications prioritize product presentation, gentle cushioning for delicate items, and a barrier against moisture loss to preserve freshness.
- Fresh Produce Packaging:These trays provide cushioning, promote air circulation, and manage moisture to extend the shelf life of fruits and vegetables during storage and transport.
- Pharmaceutical Packaging:Foam trays ensure the sterile and protected transport of medical devices and pharmaceutical products, requiring materials that meet stringent regulatory standards for cleanliness and integrity.
Demand concentration is highest in meat packaging, with specialized applications like electronics presenting significant value opportunities.
End User:
Different end-user industries require foam trays tailored to their specific operational scales, regulatory environments, and supply chain logistics.
- Food Processing Companies:These entities represent high-volume buyers, driven by cost-efficiency, food safety regulations from bodies like the FDA and EFSA, and the need for reliable cold chain packaging solutions for perishable goods. Their procurement decisions increasingly incorporate sustainability metrics.
- Electronics Manufacturers:Requiring precision-engineered, anti-static, and shock-absorbent foam trays, these manufacturers prioritize material performance and global distribution capabilities to protect high-value, sensitive components. Compliance with international shipping standards is critical.
- Pharmaceutical Producers:Strict regulatory adherence, product integrity, and sterility are paramount for pharmaceutical producers utilizing foam trays for sensitive medical products and devices.
- Agricultural Exporters:Foam trays for agricultural exporters must withstand long-distance transit, provide temperature control, and protect perishable goods from bruising and spoilage.
- Cosmetic Brands:Focusing on product presentation and protection for delicate items, cosmetic brands use foam trays to enhance brand image and ensure product integrity during shipping and retail display.
Food processing companies represent a mature and substantial market segment, while electronics manufacturers drive demand for advanced material solutions.
Distribution Channel:
The foam tray supply chain leverages multiple distribution channels to reach a diverse customer base, from large industrial buyers to individual retailers.
- Wholesale Distributors:These channels serve as intermediaries, managing bulk purchasing and logistics for a wide array of smaller businesses, including independent retailers and food service operators, ensuring broad market access. They offer efficiency in reaching fragmented customer bases.
- Direct Sales:Manufacturers engage in direct sales for large-volume contracts with major food processors, electronics firms, and pharmaceutical companies, often providing custom solutions and fostering strong, long-term client relationships. This channel allows for direct control over product delivery and service.
- E-Commerce:The e-commerce channel is expanding for foam trays, catering to smaller orders, specialized packaging needs, and a growing base of online businesses requiring convenient access to packaging supplies.
- Retail Stores:Retail stores offer foam trays for general consumer use or small-scale business needs, providing immediate availability for various packaging purposes.
- Packaging Suppliers:These suppliers integrate foam trays into broader packaging solutions, offering value-added services and comprehensive packaging systems to their clients across multiple industries.
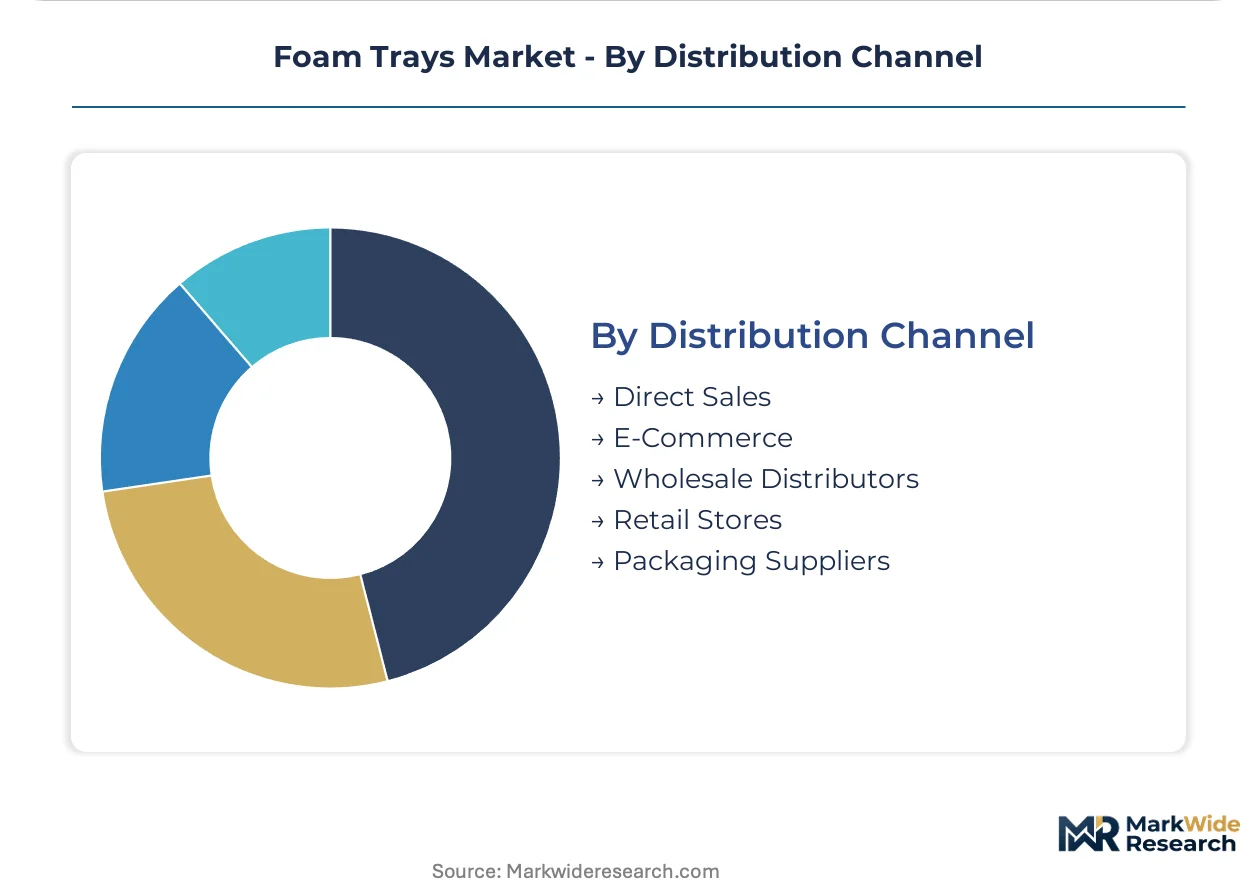
Wholesale distributors and direct sales channels manage the majority of foam tray volume, with e-commerce expanding most quickly for niche requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for foam trays concentrates significantly within food processing industries across key global markets. This consumption is driven by the necessity for protective packaging, particularly for perishable goods. Expanding cold chain logistics further supports market volume in these regions.
China
Demand for foam trays in China accelerates due to expanding food processing and e-commerce delivery sectors. China's MEE policies on plastic waste reduction directly influence material selection toward recyclable polypropylene foam and compostable options. Investment in sustainable packaging solutions concentrates in major manufacturing hubs like the Yangtze River Delta.
United States
Meat packaging and fresh produce applications drive substantial foam tray consumption across the United States. FDA food-contact material standards mandate stringent safety and integrity requirements for all packaging materials. Large-scale food processors in agricultural states like California and Texas require high-volume, cost-effective tray solutions.
Germany
European grocery retail and food service operators in Germany require compliant foam tray alternatives to traditional plastics. The EU's Single-Use Plastics Directive compels a shift towards biodegradable polymers or recycled content. Packaging manufacturers in industrial regions like North Rhine-Westphalia are retooling for bioplastics production.
India
Expanding supermarket infrastructure and a growing middle class fuel foam tray demand in India's food packaging sector. The Bureau of Indian Standards (BIS) establishes quality and safety benchmarks for food contact materials. Urban centers such as Maharashtra and Karnataka see increasing consumption of packaged perishable goods.
Indonesia
Underpenetrated markets in Indonesia present significant opportunities for both conventional and sustainable foam tray products. Local environmental regulations are beginning to encourage the adoption of more eco-friendly packaging solutions. The expanding food and beverage industry in Jakarta and Surabaya drives localized demand for protective trays.
Foam Trays Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments of the foam trays market. The industry exhibits a tiered structure, with large-scale producers of conventional materials coexisting with innovators in biodegradable solutions. Strategic archetypes include high-volume commodity providers, sustainability-driven innovators, and specialized high-performance material developers. These players often pursue material science innovation and geographic expansion as dominant competitive moves to secure market position.
On the scale-driven end of the market, Dart Container Corporation, a US-based entity, exemplifies a focus on conventional foam products and extensive manufacturing capacity. This company leverages its established infrastructure to serve broad market needs. Huhtamaki Oyj, a Finnish-based company, occupies a distinct position by championing a portfolio of sustainable packaging solutions, aligning with evolving regulatory demands. Meanwhile, Sealed Air Corporation, another US-based firm, represents a segment focused on high-performance materials for specialized applications such as electronics packaging, emphasizing advanced material properties. These entities collectively anchor the industry's diverse competitive landscape.
| Leading Market Players |
|---|
| Dart Container Corporation |
| Genpak LLC |
| Huhtamaki Oyj |
| Pactiv Evergreen Inc. |
| Sealed Air Corporation |
| Placon Corporation |
| Anchor Packaging Inc. |
| Berry Global Inc. |
| Novipax LLC |
| Others |
Cost & Logistics Intelligence
Family-owned mid-caps and private-equity-backed specialists shape foam tray supply behavior, influencing pricing discipline across conventional and sustainable segments. This ownership structure often balances cost-efficiency with material innovation demands.
Pricing Analysis
The foam trays market exhibits a volume-driven pricing structure for conventional products and a margin-focused approach for advanced materials. Per-unit transactional pricing dominates for expanded polystyrene, while contract-based long-term agreements secure specialized biopolymer supply. Price differentiation stems from material type, such as biodegradable bioplastics, and the volume scale of procurement. Pricing softness stems from petrochemical price volatility impacting expanded polystyrene costs. Food processing companies are highly price-sensitive, while electronics manufacturers prioritize performance over unit cost.
Supply Chain Analysis
Styrene monomer supply for expanded polystyrene production largely rests on major petrochemical hubs in China and the United States. Biopolymer feedstocks for biodegradable foam trays draw from a more diversified global base, including European producers. A structural risk involves the capital-intensive re-tooling required for bioplastic manufacturing. Distribution runs through a dual channel of wholesale distributors for broad market access and direct sales for large-volume industrial clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foam trays market is a cost-of-compliance story, with the EU's Single-Use Plastics Directive creating a significant barrier-to-entry moat for producers of compliant biodegradable alternatives. This regulation mandates a shift away from traditional plastics, favoring sustainable material innovation.
For Market Incumbents:Acquire bioplastic compounding expertise through targeted M&A to counter substitution from molded fiber alternatives. Expand manufacturing capacity for recyclable polypropylene foam in key growth regions like China, addressing regulatory shifts from the MEE. Invest in R&D for home-compostable biopolymers to meet evolving consumer demands and regulatory pressures in Europe.
For New Entrants and Emerging Players:Advanced active packaging technology for perishable goods provides a technology-first wedge into premium meat and seafood segments. Target underpenetrated markets in Southeast Asia, specifically Indonesia, with cost-effective, sustainable foam tray solutions. A go-to-market angle involves partnering with rapidly expanding cold chain logistics providers to offer integrated packaging solutions.
For Investors and Strategic Acquirers:Distressed-cycle entries favor vertically integrated bioplastic converters in Europe, particularly Germany, as regulatory pressures intensify for traditional expanded polystyrene producers. Long-term viability (5-10 year window) centers on firms with certified compostable material portfolios and established supply agreements. A signal to watch is the widespread adoption of standardized eco-labels, indicating market readiness for premium sustainable offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increase production of biopolymer foam trays in China to meet MEE regulations. |
| Material Science R&D | Develop advanced PLA/PHA blends for home-compostable applications. |
| Strategic Partnership | Collaborate with cold chain logistics firms for integrated packaging solutions in Asia. |
| Certification Investment | Secure FDA and EFSA food-contact certifications for new sustainable materials. |
| Geographic Market Entry | Establish manufacturing or distribution hubs in Indonesia for regional expansion. |
Research Approach
Customs data, industry association reports, and company annual filings formed the secondary backbone for this analysis, providing foundational market sizing. Primary interviews with food processing executives, packaging procurement managers, material science R&D directors, and wholesale distributors validated these findings. A blend of bottom-up and top-down triangulation ensured data accuracy and comprehensive market coverage.
Historical trendline analysis, coupled with a forward-looking assessment of technological advancements, defined the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and regional regulatory impact. Compound annual growth rates were derived from a multi-variant regression model incorporating raw material price fluctuations and new biopolymer capacities.
Several conditions sit outside the modeled scope, including unforeseen geopolitical events and rapid, disruptive material science breakthroughs beyond current R&D pipelines. Forecasts reflect assumptions regarding regulatory enforcement and sustained investment in recycling infrastructure. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Reel in Box Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Europe Paint Packaging Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
Packaging Lacquering Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Cutting Tool Packaging Market
Packaging Materials
Desiccant Market
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Polystyrene Packaging Market
Packaging Materials
Collagen Sausage Casings Market
Packaging Materials
Africa Packaging Market