
 PCR Thermoforms Market | 2026-2036
PCR Thermoforms Market Size, Share, and Industry Trends Forecast 2026-2036
PCR Thermoforms Market Insights
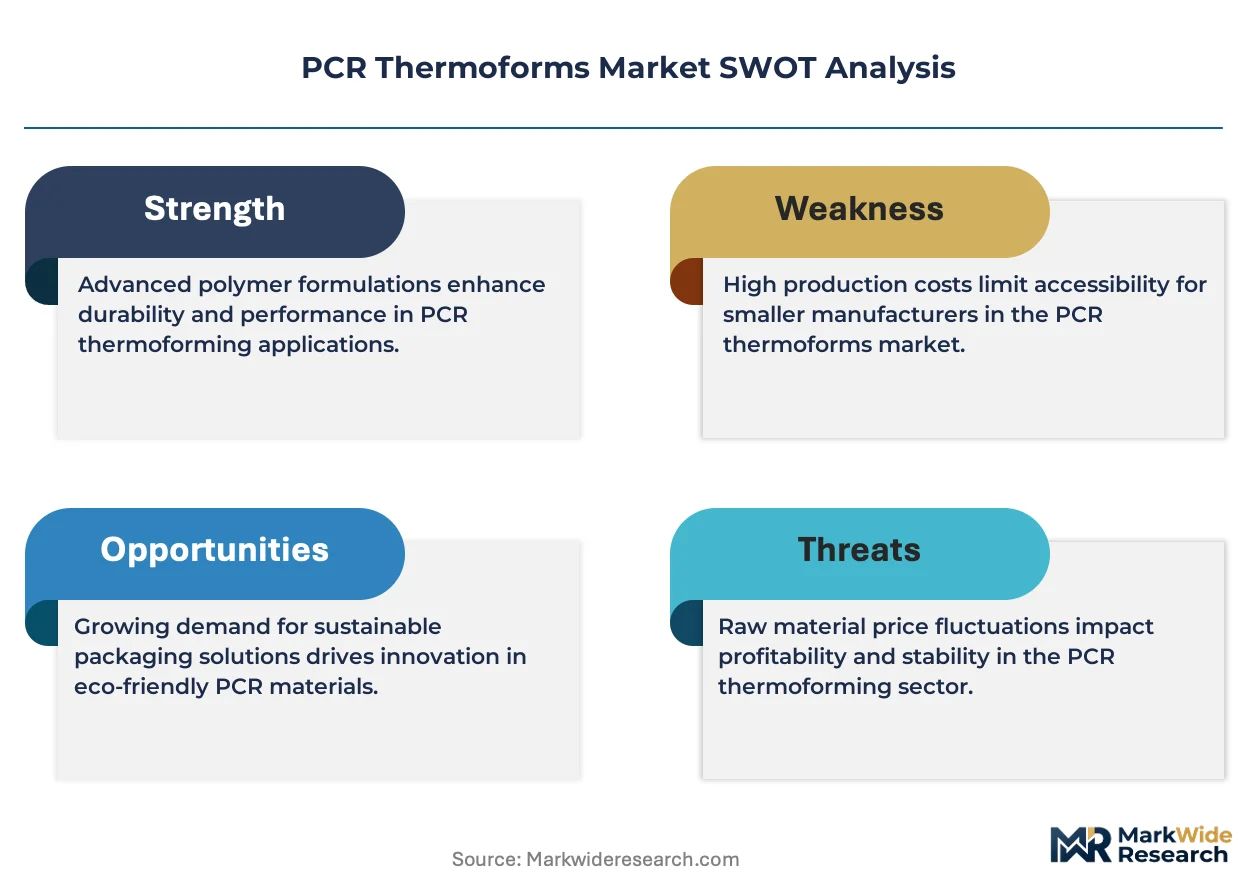
The capital-intensity divergence between integrated sheet extruders and standalone thermoformers is unwinding competitive stability in PCR thermoforms. Faerch leverages captive recycling and extrusion assets across Northern Europe to control resin quality and cost. Amcor sustains global scale advantages through pre-existing polymer recovery partnerships that feed multiple packaging divisions. Placon anchors its position in North American retail packaging through specialized rPET flake washing and extrusion lines dedicated to food-contact applications.
PCR thermoforms denote rigid packaging structures vacuum-formed or pressure-formed from post-consumer recycled polymers, typically rPET or rPP, with sheet calipers ranging from 0.010 to 0.080 inches and processing temperatures between 250°F and 400°F depending on resin grade and forming depth. These structures serve primarily to contain, protect, and display consumer products while closing material loops in circular packaging systems. Food-grade rPET trays lead volume due to established collection and decontamination infrastructure, though pharmaceutical blister packs command premium positioning through medical-grade certification barriers. Clamshells compete aggressively on price in electronics protection and consumer goods, while cups and lids face margin compression from lightweighting trends and alternative fiber competition.
The EPA guides post-consumer recycled content standards in U.S. food-contact applications, while the EU Green Deal and REACH constrain additive chemistries and mandate recycled content minimums across member states. EFSA and FDA both enforce decontamination performance thresholds that determine which PCR streams qualify for direct food contact, effectively filtering processor capabilities and market access. Stakeholders must monitor evolving state-level extended producer responsibility implementations and batch-level mass balance verification requirements that will reshape qualification costs and supplier eligibility.
Market Dynamics
Extended producer responsibility laws in California and Germany now mandate recycled content thresholds that thermoformers must meet to retain shelf placement with major retail chains. This regulatory compression forces processors to secure qualified PCR resin streams ahead of contract renewals.
Growth Catalysts
- EU Green Deal recycled content mandates:The framework establishes binding minimums for post-consumer material in packaging, compelling food processors to specify PCR thermoforms in procurement tenders across member states.
- rPET decontamination infrastructure maturation:Advanced super-cleaning technologies now achieve FDA and EFSA food-contact thresholds, unlocking dairy and ready-meal applications previously restricted to virgin polymers.
- Retailer sustainability scorecards:Walmart and Carrefour now penalize suppliers lacking verified recycled content, redirecting volume toward certified PCR thermoform converters.
Market Restraints
- PCR resin supply concentration:Quality-assured rPET flake production clusters in Germany and the United States, exposing thermoformers elsewhere to feedstock disruption and freight cost volatility.
- Food-contact certification bottlenecks:EFSA and FDA batch-level verification requirements extend qualification timelines to 18-24 months, freezing out smaller processors lacking dedicated regulatory staff.
- Fiber-based packaging substitution:Molded pulp and paperboard alternatives capture premium produce and electronics segments where moisture resistance is less critical.
Strategic Opportunities
- Pharmaceutical blister pack certification:Medical-grade rPET thermoforms command 40-60% price premiums over food-grade equivalents, with only three processors currently holding EMA-equivalent cleanroom qualifications.
- California SB 54 implementation:The state's extended producer responsibility law creates guaranteed offtake volumes for PCR thermoforms through 2032, with penalties funding collection infrastructure expansion.
- Digital mass balance verification:Blockchain-tracked resin provenance systems enable premium pricing for batch-certified circular content, differentiating suppliers in RFP evaluations.
Industry Challenges
- Food-contact toxicologist scarcity:EFSA and FDA submission preparation requires specialized expertise concentrated among fewer than 50 consultants globally, extending time-to-market for new PCR sources.
- Multi-site extrusion line synchronization:Thermoformers integrating acquired sheet extrusion assets face yield inconsistency when calibrating rPET formulations across legacy equipment from different OEMs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PCR Thermoforms Market |
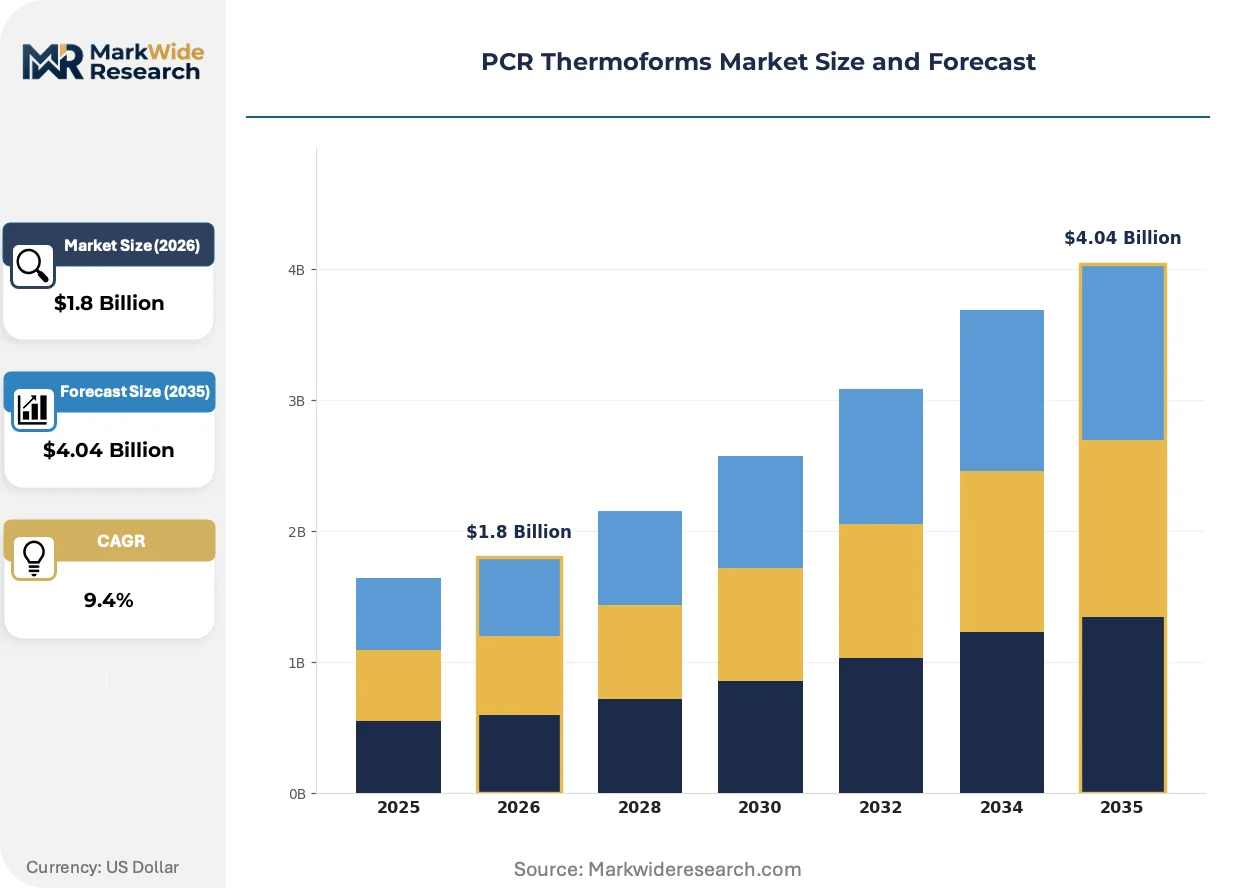
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clamshells, Blister Packs, Trays, Cups, Lids, Bladders Material Grade: Food Grade, Medical Grade, Industrial Grade, Cosmetic Grade, Electronic Grade End Use Application: Food Packaging, Pharmaceutical Packaging, Cosmetic Containers, Electronics Protection, Consumer Goods Packaging Distribution Channel: Direct Sales, Distributors, E-commerce, Retail Chains, Institutional Buyers |
| Companies Covered | Faerch, Amcor, Placon, Pactiv Evergreen, Genpak, TOPPAN Packaging, Sabert, Berry Global, Sonoco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PCR Thermoforms Market Trends and Innovations
Active developments across material science, regulatory enforcement, and buyer behavior are compressing the competitive window for PCR thermoform qualification. Processors must now synchronize technical upgrades with procurement cycle timing.
Chemical recycling of contaminated PET waste streams is decomposing the traditional mechanical recycling bottleneck that restricted food-grade rPET supply. Nestlé and Unilever packaging procurement teams now specify chemically recycled content in 2024-2026 tender documents. This technology is decomposing the virgin resin price floor that previously capped PCR thermoform margins.
REACH additive restrictions and EU Green Deal implementation timelines are tightening allowable substance lists for PCR thermoforms entering European food packaging. The industrial consequence is forced reformulation of legacy rPET streams containing legacy flame retardants or colorants. Dairy and meat tray segments in France and the Netherlands are responding fastest, with processors accelerating EFSA renewal submissions ahead of 2025 enforcement windows.
Retailer sustainability audits now dominate supplier selection criteria previously weighted on unit cost alone. Walmart's packaging scorecard and Carrefour's Act for Food program evaluate PCR content percentage, batch traceability, and carbon footprint in composite scoring. This behavioral shift is most visible in North American private-label fresh produce, where three suppliers have lost shelf placement despite 15% price advantages due to mass balance documentation gaps.
PCR Thermoforms Market Segmentation
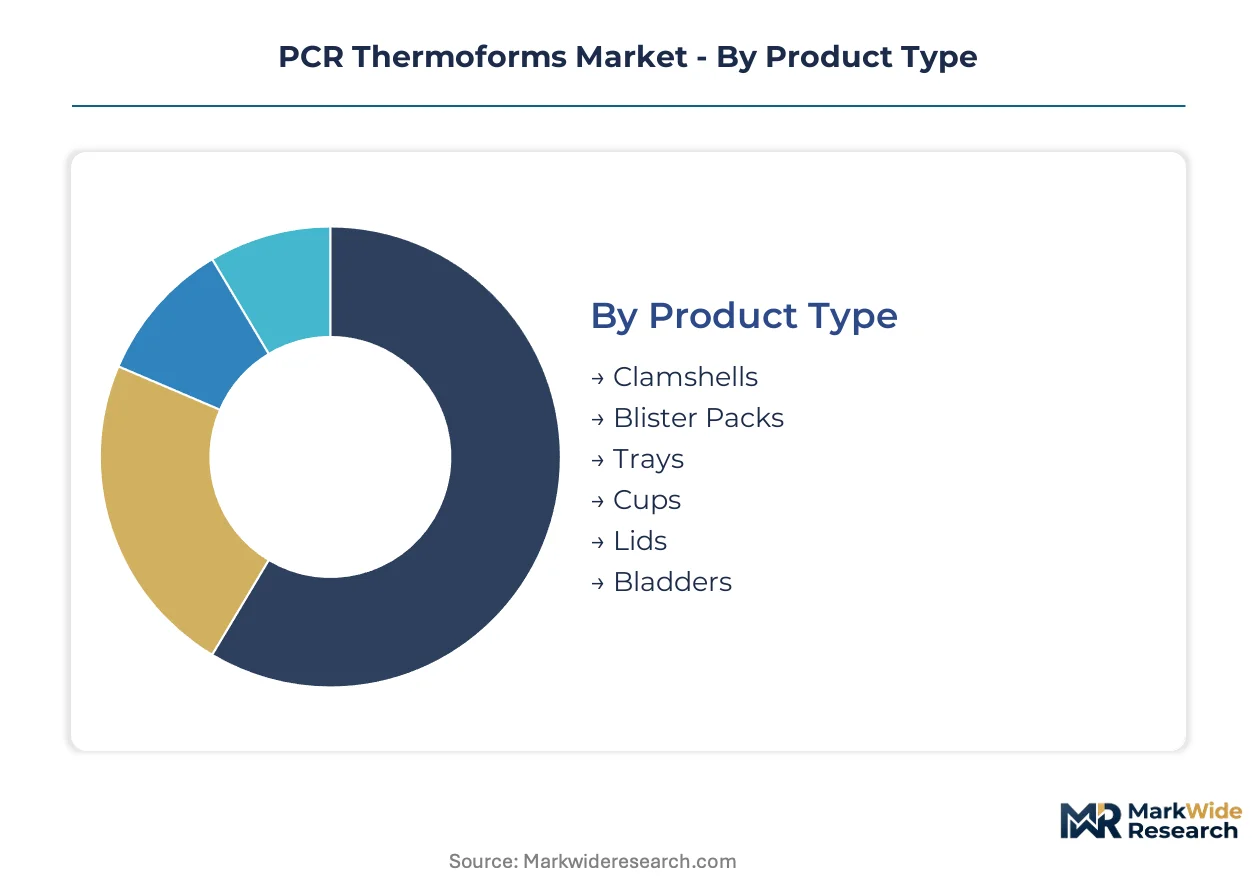
PCR thermoform segmentation reveals distinct supply chain configurations where food-contact certification barriers create tiered market access. Material grade distinctions and end-use application requirements determine which processors capture premium pricing versus commodity volume.
Product Type:
Domestic consumption patterns in Germany, the United States, and France absorb most tray and clamshell output, while blister packs and specialized bladders serve export pharmaceutical markets from certified cleanroom facilities.
- Trays:Vacuum-formed rPET structures with 0.015-0.040 inch calipers dominate dairy, meat, and ready-meal containment. French and Dutch supermarket chains now mandate 30% minimum recycled content in fresh produce trays, locking in qualified suppliers through multi-year procurement agreements.
- Clamshells:Hinged protective structures formed from rPET or rPP serve electronics and consumer goods display. Margin pressure intensifies as Walmart and Amazon specifications tighten around batch-level mass balance documentation, disqualifying smaller thermoformers lacking blockchain-tracked resin systems.
- Blister Packs:Medical-grade rPET thermoforms with EMA-equivalent cleanroom certification command substantial premiums in pharmaceutical primary packaging.
- Cups:Lightweight rPET vessels face displacement from fiber-based alternatives in cold beverage applications.
- Lids:Secondary sealing components experience commoditization as sheet extruders integrate downstream forming capacity.
- Bladders:Flexible containment structures for liquid and semi-solid products remain specialized, with demand concentrated in industrial chemical handling.
Trays command the established base. The steepest expansion runs through blister packs.
Material Grade:
Cost stratification separates food-contact certified streams from industrial applications, with medical grade representing a distinct premium tier accessible to only three processors globally.
- Food Grade:rPET and rPP resins meeting FDA and EFSA decontamination thresholds for direct food contact. Super-cleaning technology maturation in Germany and the United States has expanded qualified supply, though EFSA batch verification timelines still stretch 18-24 months for new entrants.
- Medical Grade:rPET thermoforms produced under ISO 15378 pharmaceutical packaging standards with dedicated cleanroom extrusion and forming. Nestlé and Unilever procurement teams now specify this grade for high-visibility sustainability commitments, compressing availability for traditional pharmaceutical clients.
- Industrial Grade:Non-food-contact rPP and rPS structures for manufacturing component trays and dunnage.
- Cosmetic Grade:rPET with enhanced clarity and color consistency requirements for premium personal care presentation.
- Electronic Grade:Static-dissipative formulations protecting sensitive semiconductor components during transport.
Food grade absorbs the volume base. Medical grade delivers the margin expansion.
End Use Application:
Customer procurement patterns bifurcate between retail-driven sustainability mandates and industrial specifications prioritizing unit cost over circular content verification.
- Food Packaging:The dominant application consuming rPET trays, clamshells, and cups. EU Green Deal recycled content minimums and California SB 54 implementation create guaranteed offtake volumes through 2032, with penalties funding collection infrastructure that feeds qualified resin streams.
- Pharmaceutical Packaging:Blister packs and unit-dose containers requiring EMA-equivalent certification. Only three processors currently hold the toxicologist-reviewed submissions necessary for this segment, creating supply scarcity that supports 40-60% price premiums over food-grade equivalents.
- Electronics Protection:Anti-static clamshells and trays for component shipping. REACH additive restrictions are forcing reformulation of legacy rPET streams containing flame retardants, with compliance costs squeezing smaller thermoformers.
- Cosmetic Containers:Premium rPET jars and lids where brand sustainability storytelling justifies material cost premiums.
- Consumer Goods Packaging:General merchandise containment facing aggressive substitution from molded pulp in non-moisture-critical applications.
Food packaging anchors volume. Pharmaceutical applications scale the value curve.
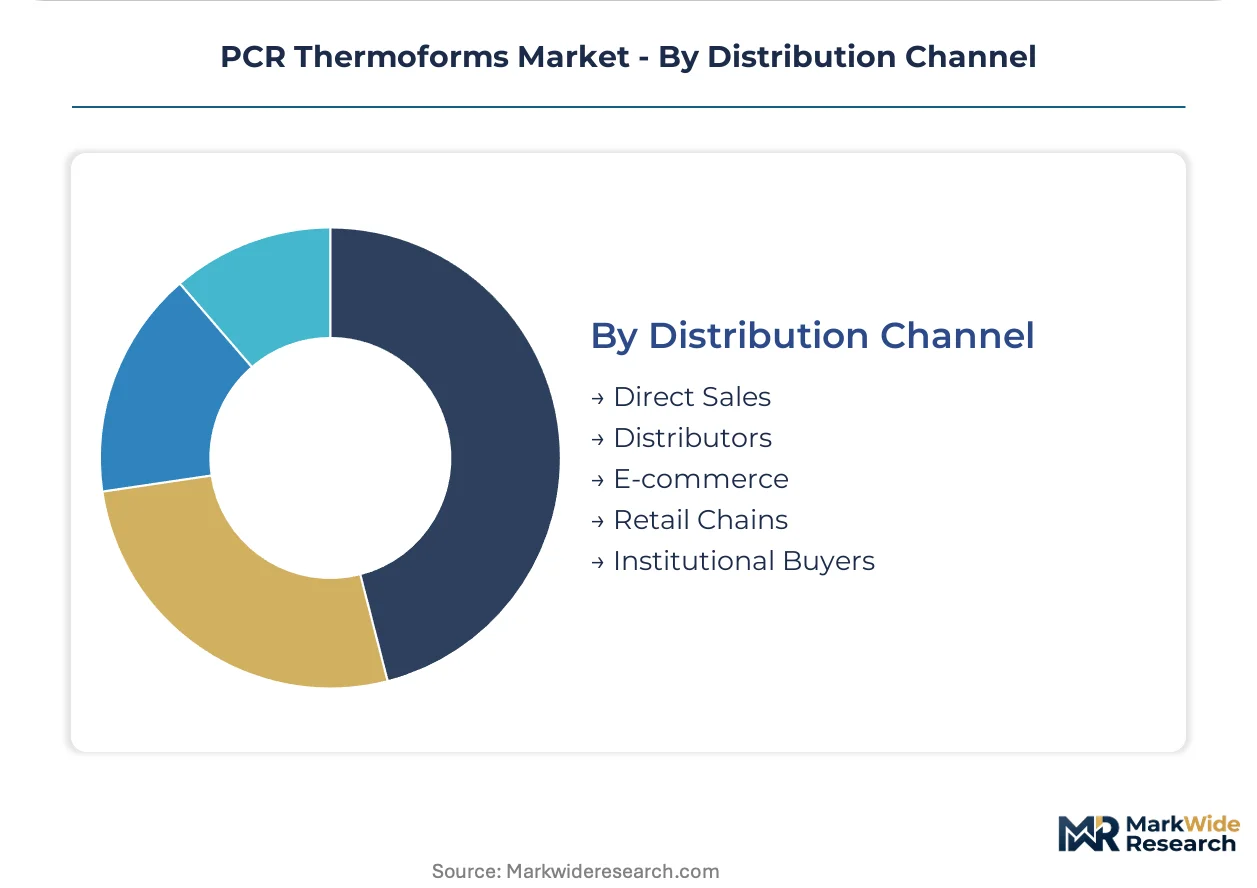
Distribution Channel:
Channel selection reflects customer scale and certification complexity, with direct relationships dominating food and pharmaceutical procurement while distributors serve fragmented industrial demand.
- Direct Sales:Long-term supply agreements between thermoformers and multinational food processors or pharmaceutical manufacturers. Carrefour's Act for Food program and Walmart's packaging scorecard now embed recycled content percentage and carbon footprint into composite supplier evaluations, making direct technical collaboration essential.
- Distributors:Regional inventory holders serving mid-sized food processors and industrial customers lacking dedicated packaging procurement staff.
- Retail Chains:Private-label packaging specifications set by supermarket sustainability mandates, increasingly requiring mass balance documentation as a condition of shelf placement.
- E-commerce:Digital platforms connecting small-batch buyers with certified converters, growing fastest for cosmetic and specialty food applications.
- Institutional Buyers:Healthcare systems and government procurement entities with standardized sustainability requirements.
Direct sales secure the strategic accounts. E-commerce channels gain share fastest among emerging brands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and the United States where qualified rPET flake production clusters around established decontamination infrastructure, while thermoformers elsewhere absorb freight cost volatility and feedstock disruption risk.
United States
California SB 54 mandates recycled content thresholds that thermoformers must meet to retain shelf placement with Walmart and Amazon. The EPA guides post-consumer standards for food-contact applications. Sheet extrusion and forming operations cluster in the Midwest and Southeast, where processors integrate acquired assets to synchronize rPET formulations across legacy equipment.
Germany
Centralized recycling infrastructure and retailer sustainability mandates converge to anchor European demand. The EU Green Deal and REACH constrain additive chemistries while mandating recycled content minimums. Northern industrial corridors host Faerch's captive recycling and extrusion assets, controlling resin quality and cost through backward integration.
France
Supermarket chains now mandate minimum recycled content in fresh produce trays, locking in qualified suppliers through multi-year procurement agreements. EFSA enforces decontamination performance thresholds that filter processor capabilities. Dairy and meat tray segments in the Netherlands and northern France accelerate EFSA renewal submissions ahead of enforcement windows.
United Kingdom
Post-Brexit regulatory divergence creates parallel compliance tracks for thermoformers serving EU and UK markets simultaneously. The country's national environmental regulator maintains food-contact standards aligned with EFSA thresholds. Packaging converters in the Midlands and southeast England face extended qualification timelines as batch-level verification requirements reshape supplier eligibility.
Japan
METI circular economy initiatives drive specification of PCR content in retail packaging procurement. The national pharmaceutical regulator maintains standards for medical-grade applications that command substantial premiums. Industrial clusters around Osaka and Nagoya host thermoformers specializing in electronics protection and cosmetic containers where brand sustainability storytelling justifies material cost premiums.
PCR Thermoforms Market Competitive Landscape
Concentration sits with integrated sheet extruders who control captive recycling assets and command resin quality premiums unavailable to standalone thermoformers. Three strategic archetypes define competitive positioning: Northern European specialists with backward integration into flake washing and extrusion, global packaging conglomerates leveraging pre-existing polymer recovery partnerships, and North American regional players with dedicated food-contact certification infrastructure. Dominant competitive moves include acquisition of sheet extrusion capacity to secure feedstock control and formation of blockchain-tracked resin provenance systems to enable premium pricing in RFP evaluations.
Among the integrated specialists, Faerch anchors the Northern European tier through captive recycling and extrusion assets across Denmark and neighboring markets. Amcor occupies a position among global packaging conglomerates sustaining scale advantages through polymer recovery partnerships feeding multiple divisions. Placon exemplifies the North American regional specialist archetype, with specialized rPET flake washing and extrusion lines dedicated to food-contact applications in retail packaging.
| Leading Market Players |
|---|
| Faerch |
| Amcor |
| Placon |
| Pactiv Evergreen |
| Genpak |
| TOPPAN Packaging |
| Sabert |
| Berry Global |
| Sonoco Products |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month EFSA batch verification timelines concentrate pricing power among German and United States processors with established toxicologist relationships, while thermoformers elsewhere absorb freight premiums and feedstock disruption risk. This lead-time asymmetry separates qualified resin streams from commodity spot markets.
Pricing Analysis
The customization-premium spread between medical-grade blister packs and standard food-contact trays runs 40-60% based on EMA-equivalent cleanroom certification scarcity. Three-tier pricing structure across medical, food, and industrial grades anchors on FDA and EFSA decontamination thresholds, with pharmaceutical procurement teams now specifying medical-grade for sustainability commitments. Cost compression in clamshells intensifies as Walmart and Amazon tighten mass balance documentation requirements. Industrial buyers exhibit highest price sensitivity, while pharmaceutical clients absorb premiums for batch-certified provenance.
Supply Chain Analysis
Inventory buffers stretch across 18-24 month qualification windows as thermoformers stockpile rPET flake ahead of contract renewals. Quality-assured feedstock production clusters in Germany and the United States, drawing from post-consumer bottle collection infrastructure and super-cleaning decontamination lines. The supply chain rests on virgin PET pricing floors, chemical recycling maturation, and fiber-based substitution threats. Single-source vulnerability concentrates in EFSA-toxicologist-reviewed submission preparation, with fewer than 50 qualified consultants globally. Distribution runs through direct long-term agreements with multinational food processors and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges from divergent state-level extended producer responsibility implementations, creating regional qualification niches where specialized processors capture mandated offtake volumes ahead of national consolidation.
For Market Incumbents: Secure captive recycling assets and extrusion capacity in California and Germany ahead of SB 54 and EU Green Deal enforcement windows. Invest in blockchain-tracked resin provenance systems to defend margin position against smaller thermoformers lacking mass balance documentation infrastructure. Prioritize EFSA toxicologist relationships to accelerate batch verification timelines. For New Entrants and Emerging Players: Anchor in pharmaceutical blister pack certification, where only three processors currently hold EMA-equivalent cleanroom qualifications and 40-60% price premiums persist. Target California SB 54 implementation geographies with modular rPET flake washing and extrusion lines sized for regional food processor contracts. Lead with digital mass balance verification as a differentiated RFP response. For Investors and Strategic Acquirers: Carve-out targets emerge from global packaging conglomerates spinning non-core thermoforming divisions lacking backward integration into resin recovery. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than unit cost position. Watch EFSA and FDA batch-level verification requirement expansions as signals for qualified processor scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Flake Washing | Captive resin quality control secures FDA and EFSA food-contact thresholds ahead of contract renewals. |
| Blockchain-Tracked Resin Provenance System | Batch-certified circular content enables premium positioning in Walmart and Carrefour sustainability scorecards. |
| EMA-Equivalent Cleanroom Certification | Medical-grade pharmaceutical packaging qualification unlocks 40-60% price premiums over food-grade equivalents. |
| Chemical Recycling Partnership | Nestlé and Unilever procurement specifications for chemically recycled content decompose virgin resin price floors. |
| California SB 54 Compliance Infrastructure | Guaranteed offtake volumes through 2032 with penalty-funded collection infrastructure expansion. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with thermoforming plant managers, polymer procurement leads at multinational food processors, regulatory affairs directors, and retail packaging sustainability officers; and secondary validation through EFSA guidance documents, FDA food-contact notifications, EPA post-consumer recycled content standards, EU Green Deal implementation texts, and California SB 54 regulatory filings. Bottom-up volume modeling across product type, material grade, and end-use application triangulated against top-down macroeconomic drivers.
Across the analysis window, forecasts reflect segment-level CAGRs derived from regulatory mandate timelines, retailer sustainability scorecard adoption curves, and rPET decontamination infrastructure buildout rates. Segmentation dimensions modeled include product type, material certification tier, end-use application, and distribution channel structure. Industry-specific inputs incorporated EFSA batch verification timeline distributions, chemical recycling capacity announcements, and extended producer responsibility law implementation schedules.
Material uncertainties — regulatory enforcement intensity, chemical recycling cost curves, and fiber-based packaging substitution rates — sit outside the modeled envelope. Forecasts reflect assumptions about sustained retailer sustainability mandate momentum and stable virgin-to-recycled resin price relationships. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Hot-Melt Based Packaging Market
Packaging Materials
France Packaging Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Cardboard Trays Market
Packaging Materials
Global Anti-Static Films Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Metallized Rollstock Film Market
Packaging Materials
Paint Packaging Market
Packaging Materials
Vacuum Packaging Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Desiccant Market
Packaging Materials
Primary Packaging Market
Packaging Materials
Direct Thermal Printing Films Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Printable Self-Adhesive Vinyl Films Market
Packaging Materials
PET Packaging Market