
 Latin America Single-Use Packaging Market | 2026-2036
Latin America Single-Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Single-Use Packaging Market Insights
Market Context
The capital-intensity divergence between integrated multinationals and regional converters is unwinding competitive stability across Latin America. Amcor Group GmbH leverages its blown-film extrusion network to supply pan-regional beverage accounts from Brazilian and Mexican plants. Huhtamaki Oyj sustains leadership in molded fiber through its dedicated food-service manufacturing in the region. Berry Global Inc anchors its position via rigid container capacity serving healthcare and personal care multinationals operating in Mexico and Colombia.
Technical Definition and Structural Segments
Single-use packaging denotes containers, wraps, bags, and trays designed for one-time product protection, distribution, and consumption before disposal, typically manufactured through thermoforming, injection molding, extrusion blow molding, or flat-die extrusion with gauge tolerances ranging from 0.5 to 3.0 mils for flexible films. These materials serve primarily to extend shelf stability, enable portion control, and reduce contamination risk across food, medical, and consumer supply chains. Plastic material categories still dominate volume shipments, though biodegradable alternatives are capturing margin pools as quick-service chains adopt certified compostable food containers under emerging procurement mandates. Food packaging applications absorb the largest share of regional converter output, while medical packaging commands premium pricing through sterilization-grade barrier specifications that few Latin American suppliers currently meet.
Regulatory Frame and Outlook
ANVISA governs food-contact material safety approvals in Brazil, while Mexico's COFEPRIS maintains parallel sanitary registration requirements that constrain import flexibility for non-compliant suppliers. Argentina's INTI standards and Chile's extended producer responsibility legislation are adding compliance layers that favor converters with in-house testing laboratories. Stakeholders must monitor how Colombia's advancing single-use plastic restrictions reshape demand trajectories for conventional polyethylene formats versus paper and aluminum substitutes.
Market Dynamics
Quick-service restaurant chains penetrating Brazil's secondary cities are compressing procurement cycles and forcing converters to localize flexible film production within São Paulo state's industrial corridor.
Growth Catalysts
- ANVISA Compliance Mandates:Brazil's sanitary regulations for food-contact materials are disqualifying non-certified imports, redirecting procurement toward domestic converters with in-house testing laboratories.
- Quick-Service Expansion:Chains operating across Mexico and Argentina require standardized packaging formats that scale across franchise networks, consolidating supplier relationships.
- Biodegradable Certification:Certified compostable food containers are capturing procurement mandates as chains face pressure from the EU Green Deal's indirect influence on Latin American export packaging standards.
Market Restraints
- Resin Price Volatility:Polyethylene and polypropylene input costs fluctuate with global petrochemical pricing, squeezing converter margins on fixed-price annual contracts.
- Converting Capacity Concentration:Blown-film extrusion capacity clusters disproportionately in São Paulo state, creating geographic supply risk for buyers in northern Brazil and Andean markets.
- Sterilization-Grade Barrier Scarcity:Medical packaging specifications requiring ethylene oxide compatibility and microbial barrier testing exceed capabilities of most regional converters.
Strategic Opportunities
- Colombian Regulatory Tailwind:Advancing single-use plastic restrictions in Colombia are accelerating demand rotation toward paper and aluminum substitutes ahead of regional peers.
- Chile EPR Legislation:Extended producer responsibility frameworks create first-mover advantage for converters offering take-back programs and recyclable mono-material structures.
- Digital Print Convergence:Combination of narrow-web flexography and variable-data printing enables short-run customization for regional craft food brands.
Industry Challenges
- Barrier Polymer Formulation Expertise:Converter engineering teams lack depth in multilayer coextrusion design for oxygen and moisture-sensitive food applications.
- COFEPRIS Registration Timelines:Mexico's sanitary registration requirements impose 12-18 month approval windows that delay product launches for new market entrants.
Report Scope
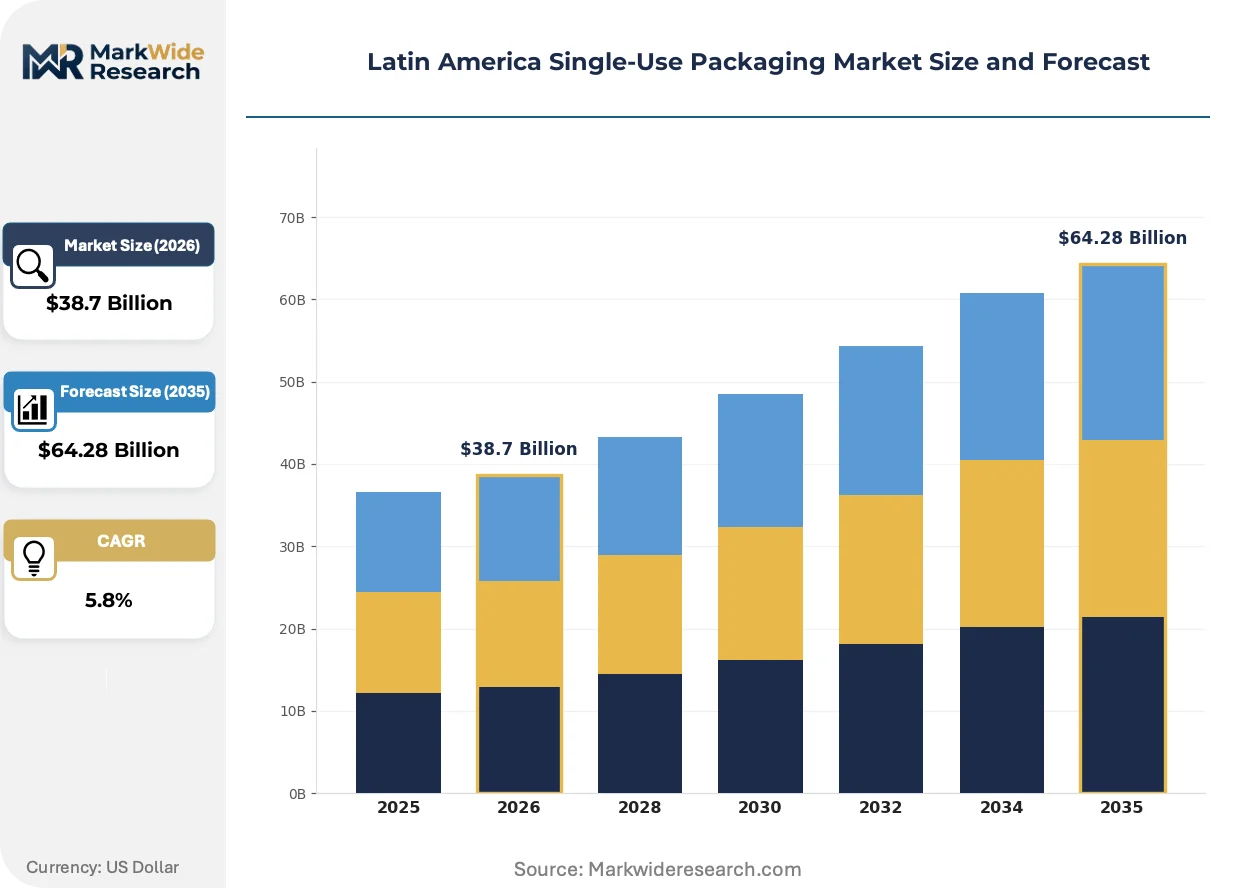
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Single-Use Packaging Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $64.28 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bags, Containers, Wraps, Trays Material: Plastic, Paper, Biodegradable, Aluminum End User: Food Service, Retail, Healthcare, Consumer Goods Application: Food Packaging, Beverage Packaging, Medical Packaging, Personal Care |
| Companies Covered | Amcor Group GmbH, Graphic Packaging International LLC, Dart Container Corporation, Transcontinental Inc, Pactiv Evergreen Inc, Winpak Ltd, Huhtamaki Oyj, Sonoco Products Company, Berry Global Inc, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Single-Use Packaging Market Trends and Innovations
Material substitution and regulatory compression are rewiring competitive advantage across Latin American converting, with sustainability certifications becoming non-negotiable in buyer qualification.
Polylactic acid and polyhydroxyalkanoate formulations are supplanting conventional polyethylene in quick-service food containers. Chains operating across Brazil and Mexico are mandating certified compostable alternatives in procurement specifications. This material transition is compressing margins for converters lacking backward integration into biopolymer resin supply.
ANVISA's updated food-contact additive positive lists are tightening migration limits for plasticizers and slip agents. Brazilian converters must reformulate masterbatch recipes and resubmit compliance documentation. Medical and infant food packaging segments face the steepest requalification burdens.
Chain procurement departments are consolidating supplier panels and demanding pan-regional consistency in specifications and pricing. Quick-service operators in Argentina and Chile are shifting from fragmented local sourcing toward master service agreements with converters operating multiple Latin American plants. Brazil's São Paulo corridor remains the primary beneficiary of this concentration.
Latin America Single-Use Packaging Market Segmentation
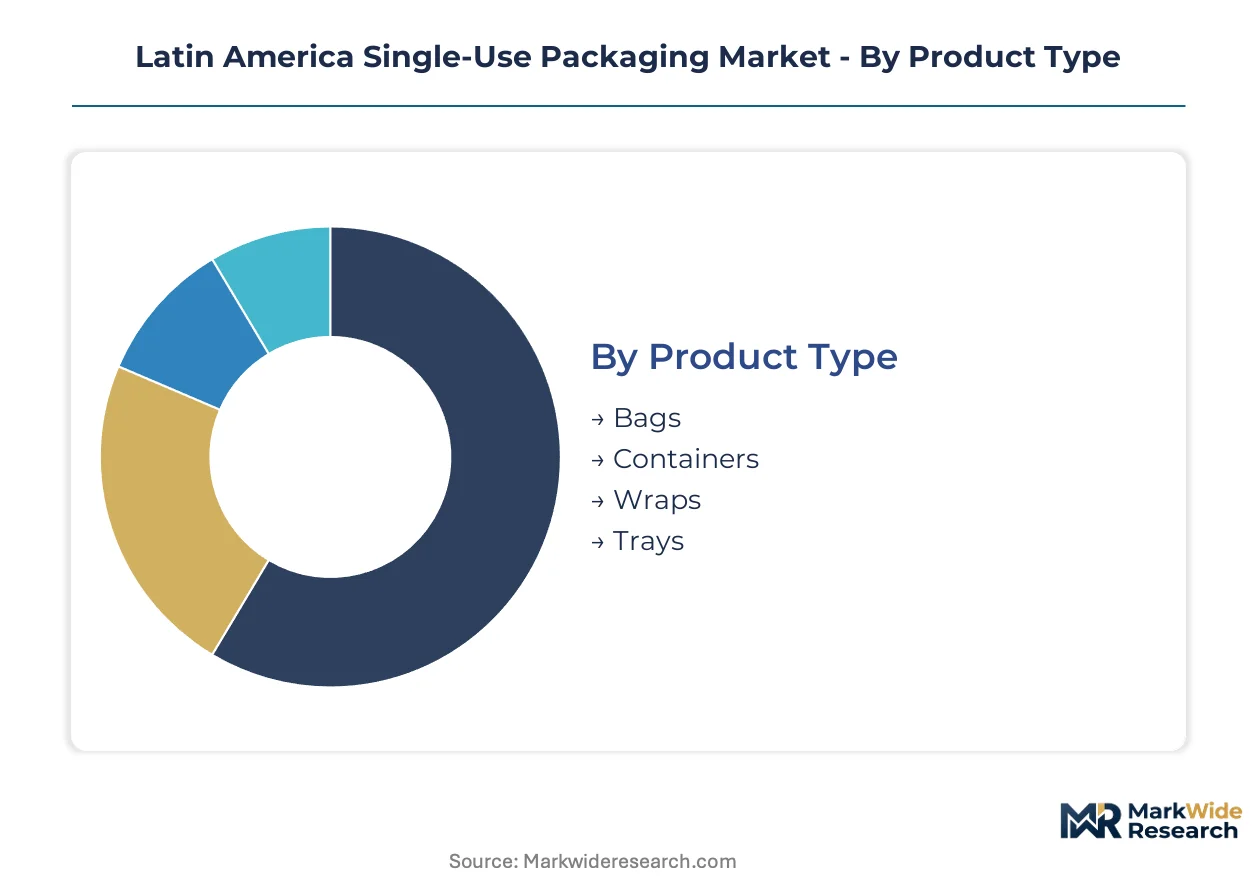
Single-use packaging procurement in Latin America fragments across four structural dimensions, each shaping how converters configure capacity and which regulatory frameworks govern compliance. Understanding these segment boundaries clarifies why São Paulo's industrial corridor attracts disproportionate investment and where material substitution pressures concentrate.
Product Type:
Quick-service chains and retail distributors route distinct product formats through separate channel infrastructures, with food service operators consolidating procurement around standardized formats that scale across franchise networks.
- Bags:Flexible polyethylene and polypropylene structures dominate grocery retail and food service carry-out applications. São Paulo's blown-film extrusion corridor supplies Brazil's supermarket chains, though resin price volatility compresses margins on fixed-price annual contracts.
- Containers:Rigid injection-molded and thermoformed structures serve portion-controlled ready-meal applications. Quick-service chains penetrating Mexico's secondary cities are mandating certified compostable alternatives, displacing conventional polypropylene in procurement specifications.
- Wraps:Cling films and stretch films protect perishables through distribution. Brazil's ANVISA migration limits for plasticizers are forcing masterbatch reformulation across converter laboratories.
- Trays:Thermoformed PET and polystyrene structures absorb meat and produce merchandising demand. Argentina's INTI standards add compliance layers that favor converters with in-house testing capabilities.
Containers dominate installed base. Bags are where expansion concentrates.
Material:
Cost tier stratification separates commodity resin applications from certified sustainable alternatives that command procurement premiums.
- Plastic:Polyethylene and polypropylene still absorb the largest share of regional converter output. São Paulo's extrusion capacity clusters serve pan-regional beverage accounts, though geographic concentration creates supply risk for northern Brazil buyers.
- Biodegradable:Polylactic acid and polyhydroxyalkanoate formulations are capturing procurement mandates as chains face EU Green Deal influence on export packaging standards. Converters lacking backward integration into biopolymer resin supply face margin compression.
- Paper:Molded fiber and coated paperboard serve quick-service food containers and retail carry-out. Colombia's advancing single-use plastic restrictions are accelerating demand rotation ahead of regional peers.
- Aluminum:Foil laminates and rigid containers protect oxygen-sensitive pharmaceuticals and premium food segments. Medical packaging specifications requiring sterilization-grade barrier properties exceed capabilities of most regional converters.
Plastic dominates installed base. Biodegradable alternatives are gaining share fastest.
End User:
Customer type determines specification stringency, with healthcare and food service imposing divergent compliance burdens on supplier qualification.
- Food Service:Quick-service chains require standardized formats across franchise networks. Chains operating across Brazil, Mexico, and Argentina are consolidating supplier panels and demanding pan-regional consistency.
- Healthcare:Sterilization-grade barrier specifications command premium pricing. Ethylene oxide compatibility and microbial barrier testing requirements exceed capabilities of most Latin American suppliers.
- Retail:Supermarket private-label programs drive volume procurement of flexible films and rigid containers. São Paulo converters supply Brazil's largest grocery chains through dedicated production lines.
- Consumer Goods:Personal care and household product multinationals operating in Mexico and Colombia specify rigid container formats. Berry Global anchors position through dedicated healthcare and personal care capacity.
Food service dominates installed base. Healthcare is where margin expansion concentrates.
Application:
Volume-maturity divergence separates established food packaging formats from medical applications where technical barriers limit supplier participation.
- Food Packaging:Flexible films, trays, and containers extend shelf stability across meat, dairy, and produce supply chains. ANVISA's updated additive positive lists are tightening migration limits and forcing requalification burdens.
- Medical Packaging:Sterilization pouches, blister packs, and barrier films protect pharmaceutical and surgical instruments. Few regional converters meet ethylene oxide compatibility and microbial barrier testing specifications.
- Beverage Packaging:Bottles, caps, and flexible pouches serve carbonated and still drinks. Amcor's blown-film extrusion network supplies pan-regional accounts from Brazilian and Mexican plants.
- Personal Care:Rigid containers and flexible tubes package cosmetics and hygiene products. Mexico's COFEPRIS sanitary registration requirements impose approval windows that delay product launches.
Food packaging dominates installed base. Medical packaging is where premium pricing concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented packaging converters across Latin America face divergent regulatory headwinds as EU Green Deal standards reshape import requirements while domestic sanitary frameworks tighten compliance burdens. Import substitution pressures favor local production over foreign supply, concentrating investment in industrial corridors with established converting infrastructure.
Brazil
Quick-service restaurant chains expanding into secondary cities drive flexible film demand through São Paulo state's industrial corridor. ANVISA's updated food-contact additive positive lists force masterbatch reformulation across converter laboratories. Blown-film extrusion capacity clusters disproportionately in Greater São Paulo, creating supply risk for northern Brazil buyers.
Mexico
Pan-regional beverage accounts source standardized packaging formats from dedicated production lines serving franchise networks. COFEPRIS sanitary registration requirements impose 12-18 month approval windows that delay product launches for new market entrants. Mexico City Metro and Nuevo León host the densest converting infrastructure for healthcare and personal care multinationals.
Argentina
Supermarket private-label programs consolidate procurement around converters with in-house testing capabilities. INTI standards add compliance layers that disqualify non-certified imports, redirecting demand toward domestic suppliers. Buenos Aires province anchors molded fiber and thermoformed capacity serving Mercosur distribution networks.
Chile
Extended producer responsibility legislation creates first-mover advantage for converters offering take-back programs and recyclable mono-material structures. Santiago's industrial belt attracts investment in certified compostable alternatives as chains face procurement mandates. Valparaíso region converters supply export-oriented food producers with barrier specifications.
Colombia
Advancing single-use plastic restrictions accelerate demand rotation toward paper and aluminum substitutes ahead of regional peers. Bogotá-based converters expand molded fiber capacity to capture quick-service procurement shifting from conventional polyethylene. Antioquia department hosts emerging flexible packaging clusters serving Andean distribution networks.
Latin America Single-Use Packaging Market Competitive Landscape
Concentration sits with integrated multinationals operating pan-regional networks from Brazilian and Mexican plants, while regional converters defend position through specialized sanitary compliance capabilities. The vendor base fragments across three strategic tiers: global packaging conglomerates with dedicated Latin American manufacturing, mid-cap national converters with ANVISA-certified laboratories, and local specialists in biodegradable formulations. Dominant competitive moves include capacity expansion in São Paulo's extrusion corridor and strategic partnerships between resin suppliers and converters seeking backward integration into biopolymer supply.
Among European-originated packaging conglomerates, Amcor Group GmbH and Huhtamaki Oyj occupy positions exemplifying scale-driven and sustainability-focused archetypes respectively. Berry Global Inc represents the North American-anchored tier serving healthcare and personal care segments. These three entities anchor the competitive structure, with regional converters clustering around compliance specialization and geographic proximity to São Paulo's industrial corridor.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Graphic Packaging International LLC |
| Dart Container Corporation |
| Transcontinental Inc |
| Pactiv Evergreen Inc |
| Winpak Ltd |
| Huhtamaki Oyj |
| Sonoco Products Company |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day resin inventory cycles across São Paulo converters compress pricing power when polyethylene spot markets spike, binding supply-chain concentration in Brazil's industrial corridor directly to margin volatility for regional buyers.
Pricing Analysis
Customization-premium spreads separate configured-to-order flexible film contracts from standard polyethylene rollstock, with three-tier pricing structure across premium, standard, and economy levels anchored by ANVISA certification grade and volume scale. Price differentiation hinges on sterilization-grade barrier specifications and biopolymer content ratios, with certified compostable containers commanding procurement premiums. Cost compression in standard polyethylene tiers is intensifying because resin price volatility squeezes converter margins on fixed-price annual contracts. Quick-service chains operating across franchise networks demonstrate lowest price sensitivity, while independent retail distributors in northern Brazil exhibit highest elasticity.
Supply Chain Analysis
Inbound logistics costs from Asian resin suppliers through Santos port congestion create geographic arbitrage disadvantages for converters lacking coastal warehousing, with container availability fluctuations on Asia-Latin America trade lanes disrupting just-in-time production schedules. Supply concentrates in Brazil, Mexico, and Argentina, with blown-film extrusion capacity clustering disproportionately in São Paulo state. Raw material dependencies center on polyethylene and polypropylene resin imports, polylactic acid biopolymer feedstocks, and masterbatch additive formulations. Single-source vulnerability sits with petrochemical resin supply tethered to global pricing cycles. Distribution runs through dedicated production lines serving pan-regional beverage accounts and supermarket private-label programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable certification mandates are accelerating material substitution faster than converter engineering capacity can adapt, creating a high-growth disruption window for stakeholders with backward integration into biopolymer resin supply.
For Market Incumbents: Fortify market position through captive supply of polylactic acid and polyhydroxyalkanoate formulations before resin price volatility erodes fixed-contract profitability. Expand blown-film extrusion capacity in São Paulo's industrial corridor to capture quick-service procurement consolidation. ANVISA compliance mandates threaten non-certified imports, making in-house testing laboratory investment the priority defensive lever. For New Entrants and Emerging Players: Medical packaging sterilization-grade barrier scarcity offers white-space entry where ethylene oxide compatibility specifications exceed capabilities of most regional converters. Target Colombian quick-service chains facing advancing single-use plastic restrictions with paper and aluminum substitute portfolios. Pursue digital print convergence partnerships with regional craft food brands requiring short-run customization. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-transition play because EU Green Deal influence on Latin American export packaging standards is rewiring procurement qualification criteria. Acquisition focus should center on mid-cap converters with ANVISA-certified laboratories and biopolymer formulation expertise. Monitor Colombia's regulatory implementation velocity as inflection indicator for regional demand rotation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biopolymer Supply | Captive PLA and PHA resin production insulates margins from petrochemical price cycles. |
| ANVISA Certification Laboratory Investment | In-house migration testing accelerates food-contact material approvals versus 12-18 month external timelines. |
| Colombia Market Entry | First-mover positioning captures demand rotation ahead of regional single-use plastic restrictions. |
| Digital Print Capability Expansion | Narrow-web flexography with variable-data printing enables craft brand short-run customization. |
| Pan-Regional Master Service Agreements | Consolidated supplier panels with quick-service chains lock in volume across Brazil, Mexico, Argentina networks. |
Research Methodology
A standing panel of converter plant managers, quick-service chain procurement directors, resin supplier technical sales leads, and ANVISA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from COFEPRIS registration databases, Brazilian customs polyethylene import records, SEC 10-K filings of listed packaging conglomerates, and EU Green Deal implementation tracking. Bottom-up capacity assessments across São Paulo's extrusion corridor were triangulated with top-down demand modeling from food service expansion patterns.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with modeled segmentation spanning product type, material category, end-user vertical, and application format. CAGRs were derived from regression analysis of historical procurement data and projected quick-service restaurant penetration into secondary cities. Forecast inputs incorporated ANVISA regulatory timeline assumptions and biopolymer capacity buildout trajectories.
Material uncertainties — resin price volatility spikes, COFEPRIS registration delays, Colombian restriction implementation timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory compliance burden trajectories and substitution elasticity coefficients. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Tube and Stick Packaging Market
Packaging Materials
Packaging Supplies Market
Packaging Materials
Disposable Icepacks Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Sanitizer Packaging Market
Packaging Materials
Microwave Packaging Market
Packaging Materials
Tamper Evident Shrink Bands Market
Packaging Materials
Packaging Primers Market
Packaging Materials
Insulated Thermal Box Liners Market
Packaging Materials
Packaging Materials Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Protein Packaging Market
Packaging Materials
Global Adherence Packaging Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Tube Packaging Market