
 Carded Packaging Market | 2026-2036
Carded Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Carded Packaging Market Outlook
The gap between premium display-grade carded packaging and commodity protective formats is shifting as brand owners split procurement budgets between shelf-impact investments and cost-down programs. WestRock Company leverages its North American paperboard mill network to control substrate supply for folding carton carded lines. Amcor plc anchors its position through pre-formed blister film capacity integrated with pharmaceutical serialization compliance. Sonoco Products Company competes in durable carded segments with engineered paperboard-composite structures for power tool retail packs.
Carded packaging denotes a family of retail-ready formats where a product mounts to a stiff backing substrate, typically paperboard or thermoformed plastic, with sealing achieved through heat, adhesive, or mechanical retention; blister packs employ PVC or PET lidding sealed to foil or paperboard backing to provide tamper evidence and product visibility for high-velocity retail environments. Folding cartons dominate volume in consumer goods applications where graphic surface area and structural rigidity drive brand communication at point of sale. Blister packs capture the fastest expansion in pharmaceutical and electronics end uses where unit-dose compliance and theft resistance justify higher per-unit format costs.
The EPA regulates paperboard mill effluent under Cluster Rules that elevate recycled content mandates for domestic carded packaging substrates, while the EU Green Deal and REACH constrain PVC migration thresholds in food-contact blister applications. FDA enforcement of pharmaceutical packaging integrity standards under 21 CFR Part 211 shapes qualification timelines for new carded drug delivery formats. Stakeholders must monitor how diverging state-level extended producer responsibility laws in California, Maine, and Oregon reshape post-consumer collection economics for multi-material carded structures.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is compressing format choices as brand owners face mandatory recycled content floors and extended producer responsibility fees that alter total cost of ownership calculations across blister and folding carton lines.
Growth Catalysts
- Pharmaceutical serialization mandates:The FDA's 21 CFR Part 211 enforcement drives unit-dose blister adoption for track-and-trace compliance in North American drug distribution.
- Germany:Pharmaceutical contract packaging clusters around Frankfurt and Munich anchor Central European distribution networks for carded dose formats.
- PET thermoforming advances:Post-consumer recycled PET film qualifies for food-contact blister applications under evolving EFSA guidance, expanding material pool availability.
Market Restraints
- Resin cost volatility:PVC and PET feedstock prices swing with crude oil indices, compressing margin stability for high-volume blister converters.
- Mill concentration:North American paperboard substrate supply concentrates among integrated producers, limiting negotiating leverage for independent folding carton specialists.
- Multi-layer recycling incompatibility:Adhesive-bonded paperboard-plastic carded structures face technical barriers in mechanical separation streams, raising disposal cost exposure under state extended producer responsibility laws.
Strategic Opportunities
- India:CDSCO's tightening pharmaceutical packaging standards create compliance-driven upgrade cycles for domestic blister line capacity.
- Rechargeable electronics retail:Theft-deterrent blister formats penetrate power tool and personal electronics segments where open-stock loss rates exceed category averages.
- EU Green Deal:The bloc's packaging waste reduction targets position fiber-based alternatives for share gain against plastic-heavy formats in non-barrier applications.
Industry Challenges
- Serialization integration:Pharmaceutical packagers face compressed qualification timelines when retrofitting blister lines with aggregation and verification hardware.
- Cross-state compliance:Diverging extended producer responsibility frameworks across California, Maine, and Oregon force multi-SKU packaging strategies that fragment production economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carded Packaging Market |
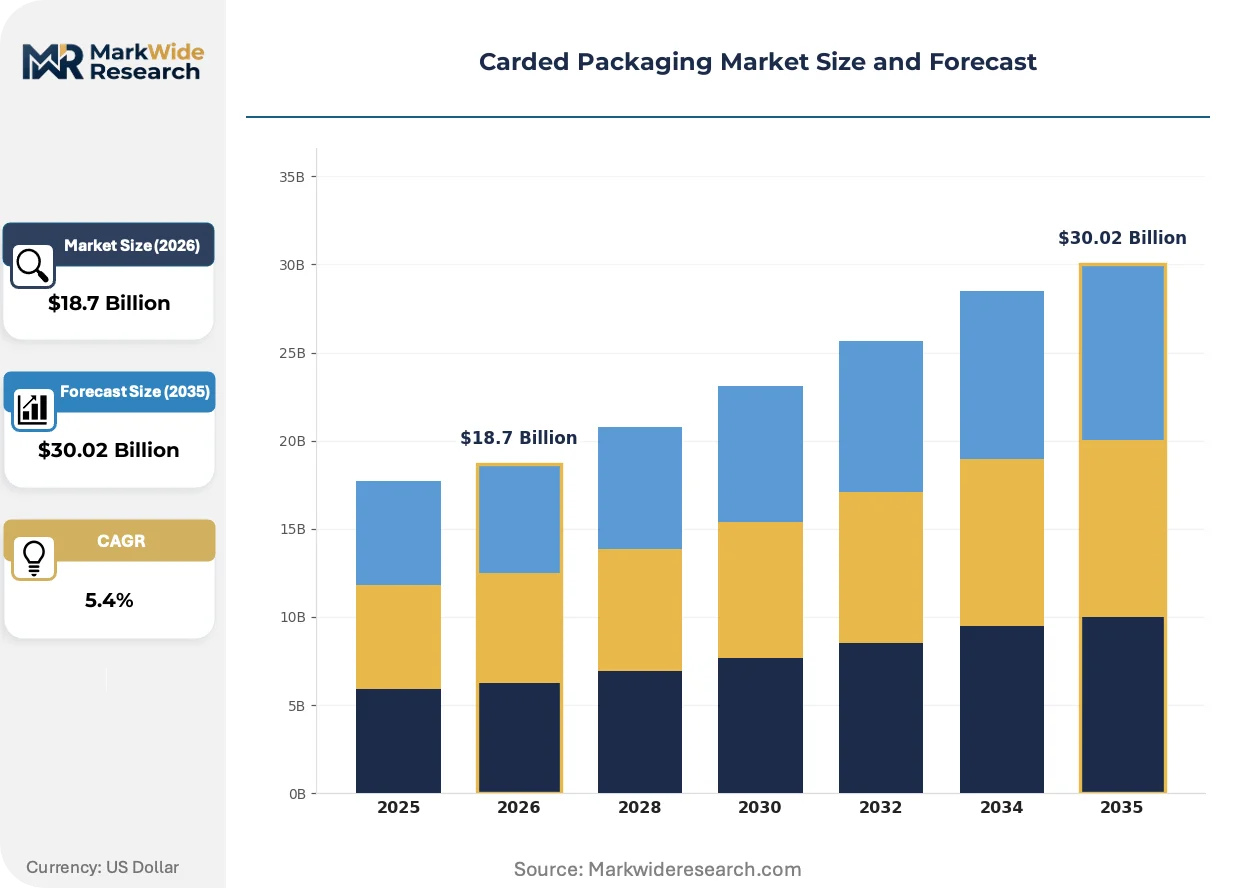
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blister Packs, Folding Cartons, Sleeves, Clamshells Material: Paperboard, Plastic, PVC, PET End User: Consumer Goods, Electronics, Pharmaceuticals, Food & Beverages Packaging Type: Retail Packaging, Durable Packaging, Display Packaging, Eco-Friendly Packaging |
| Companies Covered | WestRock Company, Amcor plc, Sonoco Products Company, International Paper Company, Berry Global Inc., Mondi Group, Graphic Packaging International, Constantia Flexibles, Smurfit Kappa Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carded Packaging Market Strategic Shifts
Active and intelligent packaging functions are migrating from premium pharmaceutical applications into mid-market consumer goods as unit cost curves flatten and brand owners seek differentiation at point of sale.
RFID-enabled blister packs is converging with pharmaceutical cold chain monitoring to create tamper-evident formats that log temperature excursions during distribution. Specialty drug manufacturers in the US and EU are piloting these formats for high-value biologics where stability documentation supports reimbursement claims. The technology is converging with existing serialization infrastructure to compress total authentication system costs.
REACH amendments tightening PVC migration thresholds for food-contact applications are forcing reformulation investments across European blister converters. The regulation's industrial consequence is accelerated PET and PP substitution in dairy and confectionery carded formats. German packaging developers are responding with co-extruded barrier films that match PVC's thermoforming latitude while meeting EFSA compliance windows.
Retailers are consolidating carded packaging specifications across private-label portfolios to reduce supplier management overhead and unlock volume pricing. This specification consolidation disrupts fragmented regional converter relationships in favor of national contract packaging networks. The shift is most visible in US mass-market electronics accessories where Walmart and Target have reduced approved blister suppliers by half since 2022.
Carded Packaging Market Segmentation
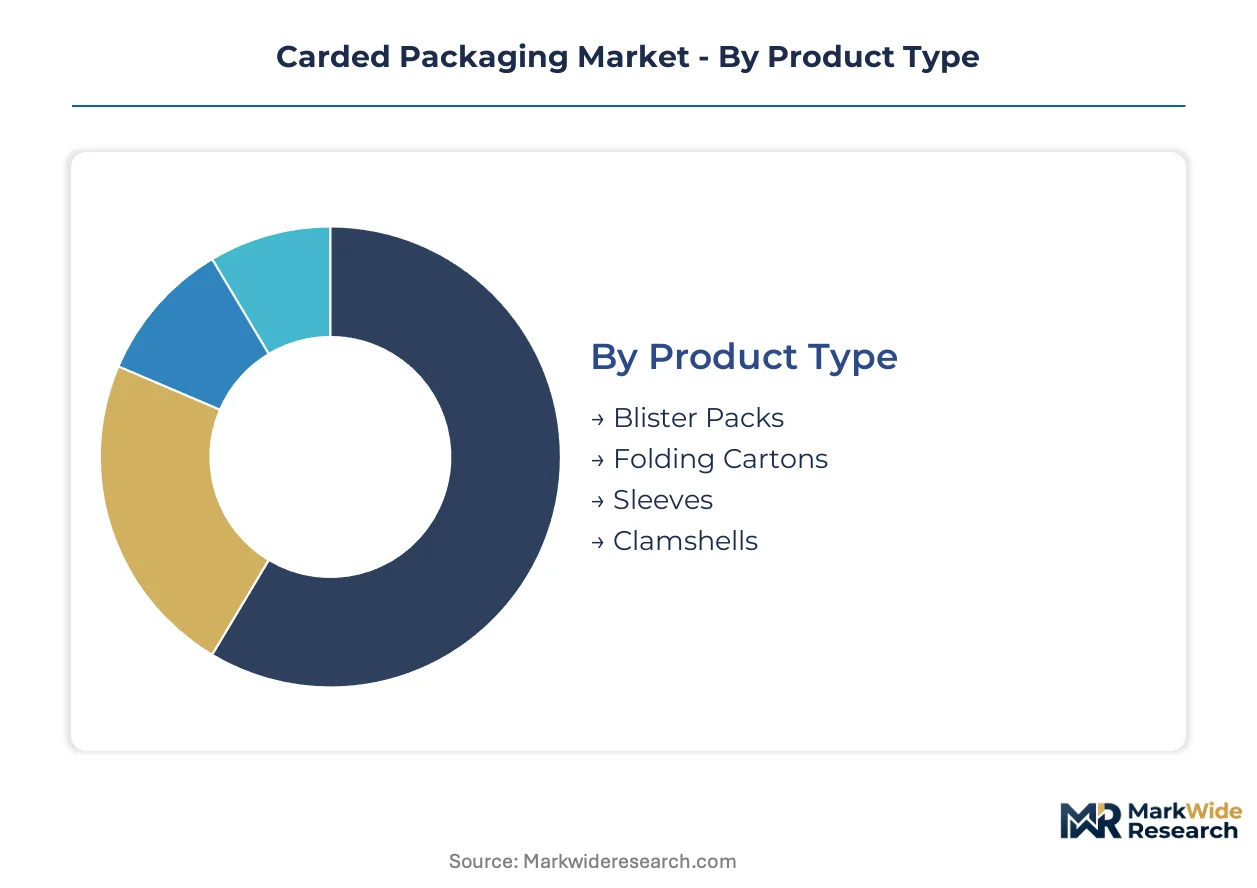
Carded packaging procurement splits between format-driven specifications and substrate-driven compliance requirements. Pharmaceutical serialization mandates and EU recycled content floors create divergent qualification burdens across product categories.
Product Type:
FDA 21 CFR Part 211 compliance separates pharmaceutical-grade formats from consumer goods specifications, with serialization-readiness determining supplier eligibility.
- Blister Packs:Thermoformed plastic cavities sealed to foil or paperboard backing provide tamper evidence and unit-dose compliance. Demand concentrates in pharmaceutical serialization applications and electronics theft-deterrence programs across Germany and the United States.
- Folding Cartons:Paperboard substrates with structural rigidity maximize graphic surface area for brand communication at point of sale. Volume concentrates in consumer goods applications where shelf impact justifies premium substrate costs over corrugated alternatives.
- Sleeves:Wrap-around paperboard or film formats secure multi-unit retail configurations.
- Clamshells:Hinged thermoformed containers enclose products in theft-resistant transparent shells.
Leading the category by volume: Folding Cartons. Expanding most quickly: Blister Packs.
Material:
REACH PVC migration thresholds and EPA Cluster Rules elevate recycled content mandates, forcing substrate substitutions in food-contact and domestic packaging lines.
- Paperboard:Virgin and recycled fiber grades serve folding carton and backing applications. EPA mill effluent regulations compress supply availability for independent converters lacking integrated pulp access.
- Plastic:Polypropylene and polystyrene films provide thermoforming latitude for non-barrier blister applications.
- PVC:Legacy blister film faces EFSA compliance pressure as REACH amendments tighten migration limits for food-contact uses.
- PET:Post-consumer recycled grades qualify under evolving EFSA guidance for food-contact thermoforming, expanding material pool availability for European converters.
Dominant by tonnage: Paperboard. Steepest compliance-driven shift: PET substitution for PVC.
End User:
Serialization mandates and theft-loss rates create divergent format specifications across customer verticals.
- Consumer Goods:Folding cartons and display-grade carded formats prioritize shelf visibility and graphic reproduction quality.
- Electronics:Theft-deterrent blister and clamshell formats penetrate power tool and personal electronics retail where open-stock loss rates exceed category averages.
- Pharmaceuticals:Unit-dose blister packs anchor track-and-trace compliance under FDA and EMA serialization frameworks.
- Food & Beverages:Barrier-coated paperboard and co-extruded films replace PVC in dairy and confectionery carded applications.
Highest format premium: Pharmaceuticals. Fastest adoption of theft-resistant formats: Electronics.
Packaging Type:
Retailer specification consolidation favors national contract packaging networks over fragmented regional converters.
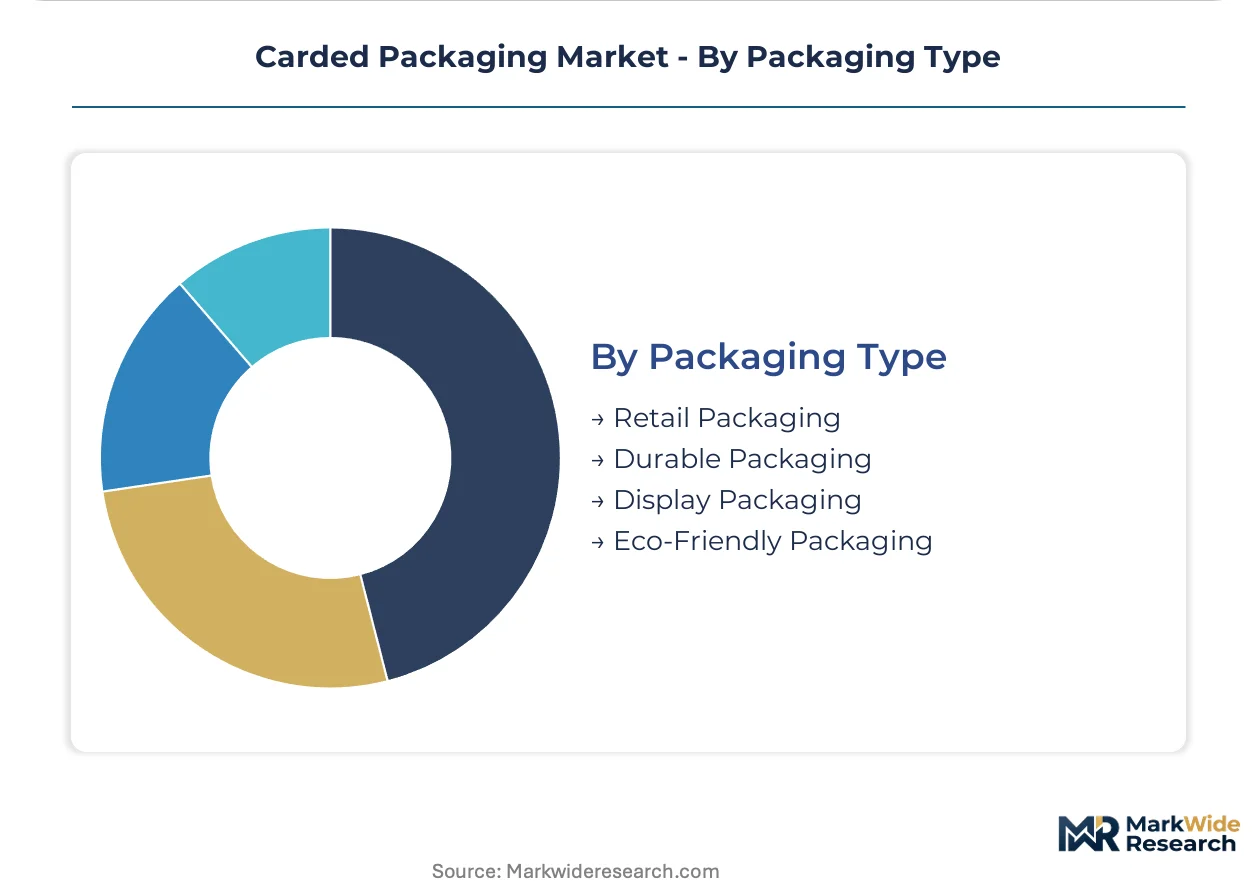
- Retail Packaging:Standard carded formats for high-velocity shelf placement balance unit cost against graphic impact.
- Durable Packaging:Engineered paperboard-composite structures protect power tools and industrial equipment through distribution handling.
- Display Packaging:Pallet-ready and shelf-ready configurations reduce retail labor costs for mass-market electronics accessories.
- Eco-Friendly Packaging:Fiber-based and recyclable mono-material structures gain share under EU Green Deal waste reduction targets.
Widest specification consolidation: Retail Packaging. Fastest regulatory tailwind: Eco-Friendly Packaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main corridor anchors European pharmaceutical contract packaging capacity, with clusters around Offenbach and Darmstadt feeding Central European distribution networks for unit-dose blister formats.
United States
Pharmaceutical serialization mandates under FDA 21 CFR Part 211 drive blister pack qualification timelines for North American drug distribution. EPA Cluster Rules elevate recycled content floors for domestic paperboard substrates, compressing supply availability for independent converters. The Southeast paperboard mill corridor spanning Georgia and Alabama concentrates integrated substrate production for folding carton lines.
Germany
Contract packaging clusters around Munich and Frankfurt anchor Central European pharmaceutical distribution for carded dose formats. REACH amendments tighten PVC migration thresholds, forcing PET substitution in food-contact blister applications. The Baden-Württemberg region hosts co-extruded barrier film development targeting EFSA compliance windows.
China
Dual carbon goals and GB standards accelerate fiber-based packaging substitution in consumer goods applications. NMPA tightening of pharmaceutical packaging integrity standards shapes qualification timelines for domestic blister line upgrades. The Yangtze River Delta concentrates thermoforming capacity serving electronics theft-deterrent programs for export markets.
India
CDSCO's tightening pharmaceutical packaging standards create compliance-driven upgrade cycles for domestic blister line capacity. FSSAI regulations on food-contact materials constrain substrate choices in dairy and confectionery carded applications. Gujarat's pharmaceutical packaging corridor near Ahmedabad concentrates contract manufacturing for export-oriented dose formats.
Japan
PMDA enforcement of pharmaceutical packaging integrity standards shapes serialization infrastructure investments for unit-dose formats. METI circular economy targets elevate recycled content mandates for retail-ready carded structures. The Kansai region around Osaka hosts specialty film development for high-barrier pharmaceutical applications.
Carded Packaging Market Competitive Environment
Capital-heavy integrated producers compete with asset-light specialty converters across substrate supply and format conversion stages. The market structure concentrates around paperboard mill networks and pre-formed blister film capacity, with tiered competition separating multinational substrate controllers from regional format specialists. Three archetypes dominate: integrated paperboard-backing suppliers, pre-formed film and lidding specialists, and engineered composite structure fabricators. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure serialization-ready qualification status.
Among North American integrated producers, WestRock Company and International Paper Company occupy positions anchored by captive paperboard mill networks. Amcor plc exemplifies the pre-formed film specialist archetype with pharmaceutical serialization compliance infrastructure. Sonoco Products Company represents the engineered composite segment with durable carded structures for industrial retail applications.
| Leading Market Players |
|---|
| WestRock Company |
| Amcor plc |
| Sonoco Products Company |
| International Paper Company |
| Berry Global Inc. |
| Mondi Group |
| Graphic Packaging International |
| Constantia Flexibles |
| Smurfit Kappa Group |
| Others |
Value Chain & Pricing Dynamics
PET thermoforming qualification for food-contact blister applications is compressing cost differentials between virgin and recycled substrate grades while concentrating film supply among converters with EFSA-compliant extrusion lines. This technical transition simultaneously elevates qualification barriers for independent converters and shifts pricing power toward integrated producers with captive resin compounding.
Pricing Analysis
Serialization-readiness pricing anchors pharmaceutical blister contracts, with FDA 21 CFR Part 211 compliance tiers separating premium qualified suppliers from commodity converters. Three-tier pricing structure across serialization-ready, standard thermoformed, and economy-grade paperboard backing reflects certification investment recovery. Cost compression in economy folding cartons is intensifying because EPA Cluster Rules elevate recycled fiber premiums. Retailer private-label buyers exhibit highest price sensitivity; pharmaceutical contract packers show lowest due to compliance switching costs.
Supply Chain Analysis
Paperboard substrate supply rests on integrated North American mill networks spanning Georgia and Alabama, with German and Chinese converters dependent on regional pulp access. Virgin fiber grades, post-consumer recycled content, and barrier-coated films constitute the critical input trinity. Single-source vulnerability concentrates in pharmaceutical-grade lidding foil supply from European specialty metal rollers. Distribution runs through national contract packaging networks consolidating regional converter relationships under retailer specification harmonization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carded packaging sector is becoming a vertical-integration race as players pursue captive control over pharmaceutical serialization qualification infrastructure to lock in multi-year contract packaging agreements.
For Market Incumbents: To counter retailer specification consolidation threatening regional converter margins, secure backward integration into post-consumer recycled PET film extrusion and expand serialization-ready capacity in the Frankfurt-Rhine-Main corridor. Certification investment in EFSA-compliant barrier coatings represents the critical defensive lever against PET substitution acceleration. For New Entrants and Emerging Players: Begin with India's CDSCO-driven pharmaceutical packaging upgrade cycle, where domestic blister line modernization outpaces qualified local converter capacity. Theft-deterrent electronics formats for power tool retail present the most penetrable white-space segment. A go-to-market angle anchored by rapid FDA 21 CFR Part 211 qualification timelines distinguishes entrants against incumbent legacy infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated paperboard producers seeking pharmaceutical serialization capabilities. Five-to-ten year viability favors converters with dual competence in fiber-based and thermoformed formats capable of navigating EU Green Deal material substitution. The signal to watch is EFSA guidance evolution on post-consumer recycled PET food-contact approval velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled PET Extrusion | Captive resin supply secures EFSA compliance windows against virgin price volatility. |
| Pharmaceutical Serialization Infrastructure Deployment | FDA 21 CFR Part 211 qualification anchors multi-year contract packaging relationships. |
| Co-Extruded Barrier Film Development | German R&D clusters target PVC displacement in dairy and confectionery applications. |
| National Contract Packaging Network Expansion | Retailer specification consolidation favors scale players with geographic coverage density. |
| Fiber-Based Format Portfolio Diversification | EU Green Deal waste reduction targets position paperboard alternatives for share gain. |
Study Parameters
Independent corroboration across primary interviews with pharmaceutical packaging engineers, retail category buyers, and thermoforming plant managers, supplemented by secondary validation through FDA 510(k) filings, EPA effluent compliance records, and EFSA scientific opinions, underwrites the qualitative findings. Bottom-up demand modeling triangulates against top-down substrate consumption estimates from integrated paperboard mill disclosures and regional trade flow analysis.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, material substrate, end-use vertical, and geographic regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating pharmaceutical serialization mandate phase-ins, EU recycled content floor escalations, and electronics theft-deterrent format penetration curves. Blister line capacity utilization rates and folding carton substrate yield trends inform industry-specific forecast inputs.
Resin cost volatility, regulatory guidance delays, and retailer specification consolidation pace are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions on compliance timeline adherence and substitution elasticity parameters. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Reel in Box Market
Packaging Materials
Nonwoven Packaging Market
Packaging Materials
Global Strapping Market
Packaging Materials
Wrapping Tissues Market
Packaging Materials
PCR Packaging Market
Packaging Materials
Brazil Packaging Market
Packaging Materials
Cold Seal Films Market
Packaging Materials
Cold Form Foil Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
Cohesive Packaging Market
Packaging Materials
Finish Foils Market
Packaging Materials
Plastic Strapping Materials Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
United Arab Emirates (UAE) Disposables (Single-Use) Packaging Market
Packaging Materials
Anti-Static Liners Market
Packaging Materials
Wooden and Plywood Packaging Market