
 Tube and Stick Packaging Market | 2026-2036
Tube and Stick Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Tube and Stick Packaging Market Analytics
The EU Green Deal is realigning material specifications across European personal care supply chains, forcing converters to certify recyclability streams. Sonoco leverages its North American paperboard tube infrastructure to capture brand sustainability mandates. Amcor competes through laminated barrier expertise in pharmaceutical stick packs. Hoffmann Neopac specializes in small-diameter aluminum tubes for premium cosmetic applications.
Tube and stick packaging encompasses cylindrical and elongated primary containers, typically extruded from polyethylene, polypropylene, or aluminum substrates with internal lacquer barriers, designed for measured dispensing of viscous, semi-solid, or powder formulations. These formats serve industries requiring precise unit dosing, portability, and shelf differentiation. Squeeze tubes dominate cosmetic and oral care applications where consumer ergonomics and brand billboard surface area command premium placement. Stick packs represent the fastest-growing configuration in single-serve food and pharmaceutical segments, driven by on-the-go consumption patterns and dose-accuracy requirements. Laminates capture expanding share as brands pursue barrier performance without aluminum content, though plastic retains cost advantage in high-volume household product lines.
FDA food-contact substance notifications and EPA resin identification requirements shape material approval timelines and recycling infrastructure access in the United States. ECHA REACH restrictions on certain phthalate plasticizers and the EU Packaging and Packaging Waste Regulation are accelerating substitution toward bio-based and mono-material structures across European manufacturing. China's GB standards for food packaging safety and India's BIS certification for pharmaceutical primary materials add compliance layers for exporters. Stakeholders must monitor evolving extended producer responsibility frameworks and material recovery facility sorting capabilities to align portfolio investments with technically achievable circularity claims.
Market Dynamics
Extended producer responsibility frameworks are forcing converters to redesign tube structures for mechanical recyclability, collapsing legacy multi-layer laminates into mono-material alternatives that satisfy sorting infrastructure limitations.
Growth Catalysts
- EPR Mandates:France and Germany enforce strict recyclability certification for cosmetic packaging, compelling brands to source mono-material polyethylene tubes compatible with existing European collection streams.
- Pharmaceutical Corridor Expansion:Domestic formulation output around Hyderabad and Mumbai drives stick pack demand for unit-dose medications targeting rural distribution networks.
- Barrier Laminate Advances:High-performance polymer coextrusions now replicate aluminum's oxygen protection without metal content, unlocking food-contact applications previously reserved for composite structures.
Market Restraints
- Aluminum Price Volatility:Raw material swings squeeze margin structures for premium cosmetic tube producers dependent on slug-drawn aluminum substrates.
- Mechanical Recycling Limitations:Current material recovery facilities cannot sort small-format stick packs from mixed waste streams, capping circularity claims regardless of mono-material design.
- Phthalate Substitution Costs:ECHA REACH restrictions on legacy plasticizers force reformulation of flexible tube shoulders and caps, adding compliance expenditure without performance guarantees.
Strategic Opportunities
- India's Generic Pharmaceutical Export Growth:Contract manufacturers serving regulated markets require child-resistant stick packs with tamper-evident features, a capability gap local converters can fill.
- China's SAMR Food-Contact Rules:Tighter safety documentation creates first-mover advantage for laminated barrier suppliers with established GB standard compliance and migration testing protocols.
- Digital Printing Convergence:Direct-to-tube inkjet systems enable run-length flexibility and personalization for cosmetic brands pursuing limited-edition strategies without plate costs.
Industry Challenges
- Mono-Material Engineering Expertise:Shortage of polymer scientists capable of matching multi-layer barrier performance with single-substrate structures delays product qualification timelines.
- Retrofitting Extrusion Lines:Converting legacy equipment for thinner-gauge high-barrier films demands capital outlay that mid-scale converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tube and Stick Packaging Market |
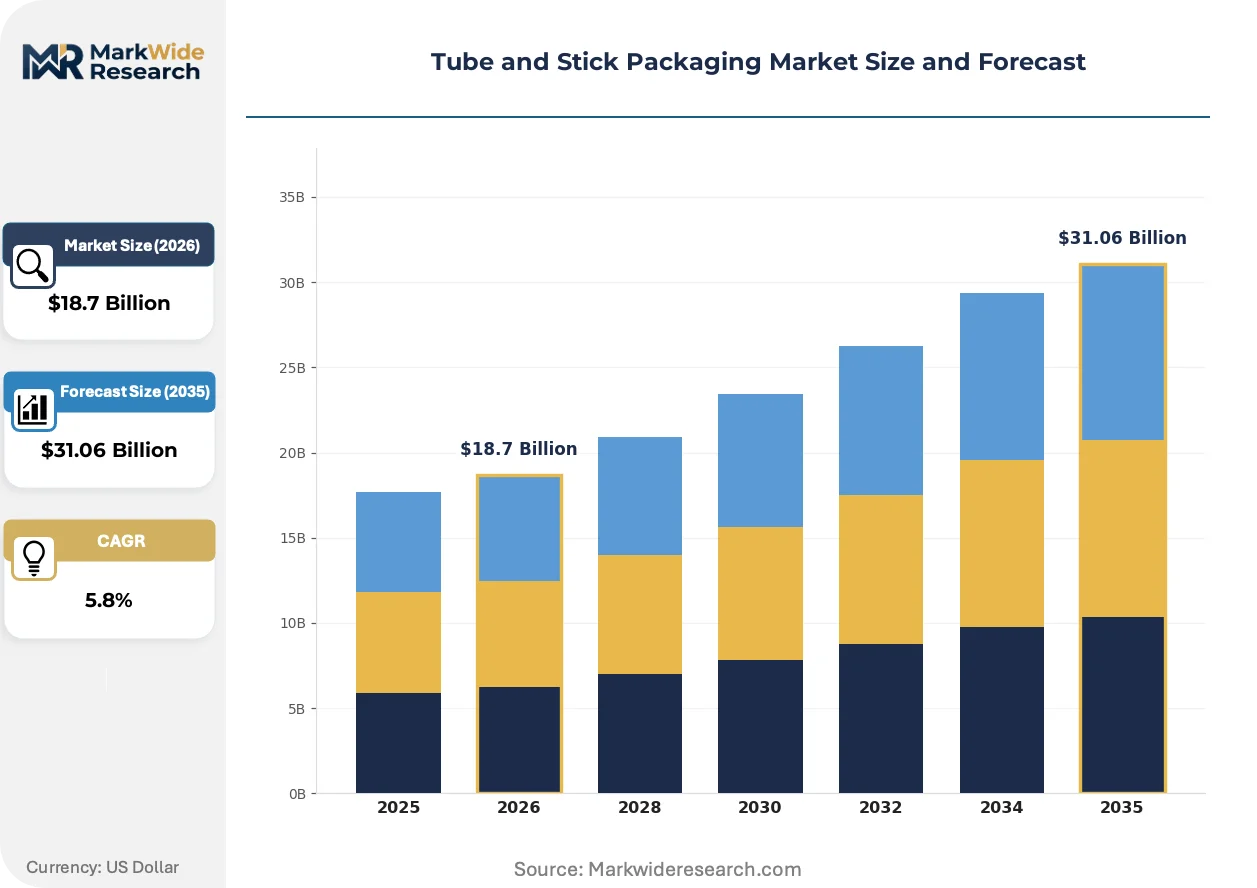
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubes, Stand-Up Pouches, Squeeze Tubes, Stick Packs Material: Plastic, Aluminum, Laminates, Paper End User: Cosmetics, Food & Beverage, Pharmaceuticals, Household Products Packaging Type: Child-Resistant Packaging, Eco-Friendly Packaging, Resealable Packaging, Bulk Packaging |
| Companies Covered | Sonoco, Constantia Flexibles, Amcor, Montebello Packaging, Berry Global, Albea, Hoffmann Neopac, CTL Packaging, Essel Propack, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tube and Stick Packaging Market Evolving Landscape
Material science breakthroughs and regulatory compression are collapsing traditional packaging hierarchies, with functionality migrating from substrate complexity to surface engineering and structural design.
Mono-material polyethylene laminates are consolidating barrier performance into single-substrate tubes through advanced coextrusion and surface coating technologies. Cosmetic brands in France and Germany are adopting these structures at accelerated pace to satisfy EPR documentation requirements. This consolidation is compressing demand for aluminum-plastic composites and forcing converters to retire legacy lamination assets.
REACH restrictions on phthalate plasticizers and the EU Packaging and Packaging Waste Regulation are eliminating flexible additives from tube shoulder and cap formulations. Industrial consequence includes accelerated substitution toward bio-based plasticizers and polyolefin elastomers with comparable flexural properties. Pharmaceutical and personal care segments most affected are responding with multi-year material qualification programs to secure supply chain continuity.
Single-serve consumption patterns are fragmenting bulk packaging demand into stick pack formats across food supplements and over-the-counter medications. E-commerce direct-to-consumer channels are displacing traditional retail stocking units, compressing minimum order quantities and accelerating format change cycles. This shift is most visible in China's tier-one cities and India's metropolitan pharmaceutical distribution networks.
Tube and Stick Packaging Market Segmentation
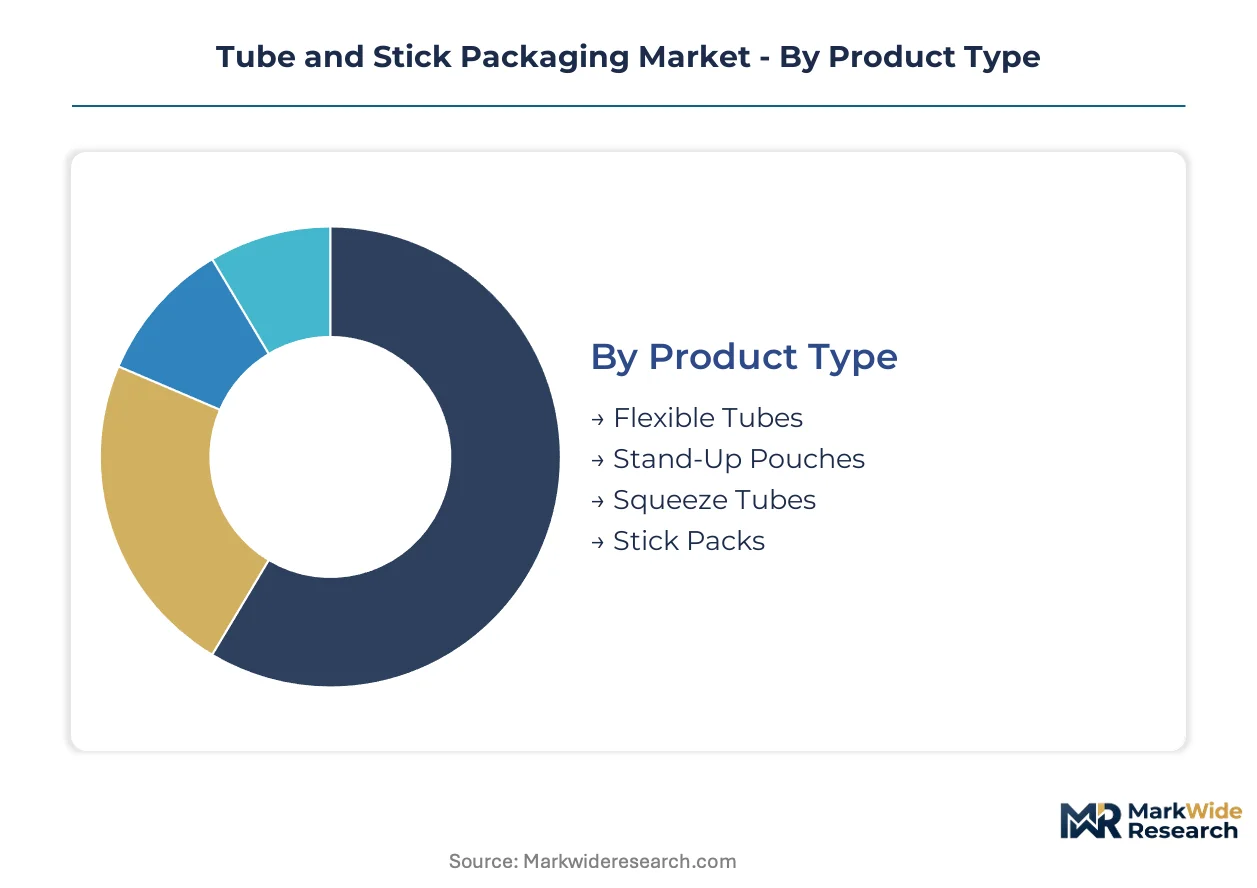
Tube and stick packaging serves heterogeneous demand profiles across personal care, pharmaceutical, and food sectors. Material selection and format geometry determine regulatory compliance pathways and recyclability credentials. Segmentation reveals where capital deployment concentrates and which technology platforms command premium positioning.
Product Type:
Capital intensity varies sharply across extrusion and forming technologies, with barrier coextrusion lines demanding the highest upfront investment per installed meter of capacity.
- Squeeze Tubes:Multi-layer polyethylene or polypropylene structures with internal lacquer barriers dominate oral care and cosmetic applications. EPR mandates in France and Germany are accelerating conversion to mono-material alternatives compatible with existing European collection infrastructure.
- Stick Packs:Elongated single-serve formats serve pharmaceutical unit-dose requirements and on-the-go food supplement consumption. Demand concentrates around India's pharmaceutical corridor near Hyderabad and Mumbai as domestic formulation output expands.
- Flexible Tubes:Collapsible aluminum or laminate structures for viscous product dispensing. Pharmaceutical and industrial adhesive segments maintain steady demand despite aluminum price volatility.
- Stand-Up Pouches:Gusseted formats with spout or cap closure systems. Food and beverage applications in China's tier-one cities drive format experimentation for convenience positioning.
Squeeze tubes absorb the bulk of installed capacity; stick packs are expanding most quickly.
Material:
Raw material selection determines barrier performance, recyclability certification, and exposure to commodity price cycles.
- Plastic:Polyethylene and polypropylene substrates dominate high-volume household and personal care lines. ECHA REACH restrictions on phthalate plasticizers are forcing reformulation of flexible tube shoulders and caps.
- Laminates:Multi-layer polymer coextrusions now replicate aluminum oxygen protection without metal content. Cosmetic brands in France and Germany are adopting these structures to satisfy EPR documentation requirements.
- Aluminum:Slug-drawn substrates with internal lacquer barriers for premium cosmetic and pharmaceutical applications. Raw material price swings squeeze margin structures for converters dependent on metal content.
- Paper:Fiber-based tubes with barrier coatings for dry powder and select food applications. Sonoco's North American paperboard infrastructure captures brand sustainability mandates.
Plastic substrates command the largest production footprint; laminates are climbing the fastest as brands pursue aluminum-free barrier performance.
End User:
Customer sophistication and regulatory burden vary dramatically across application segments, shaping converter qualification timelines and margin structures.
- Pharmaceuticals:Child-resistant and tamper-evident stick packs serve unit-dose medications for rural distribution networks. India's generic pharmaceutical export growth creates demand for contract manufacturers serving regulated markets.
- Cosmetics:Premium tube formats with billboard surface area for brand differentiation. Amcor competes through laminated barrier expertise while Hoffmann Neopac specializes in small-diameter aluminum tubes.
- Food & Beverage:Single-serve stick packs for supplements and on-the-go consumption. China's SAMR tightening of food-contact packaging rules creates first-mover advantage for compliant suppliers.
- Household Products:High-volume polyethylene tubes for viscous cleaners and adhesives. Cost-sensitive positioning favors plastic substrates over laminate alternatives.
Cosmetics and pharmaceuticals together absorb the majority of converter technical resources; pharmaceutical stick packs are gaining share fastest.
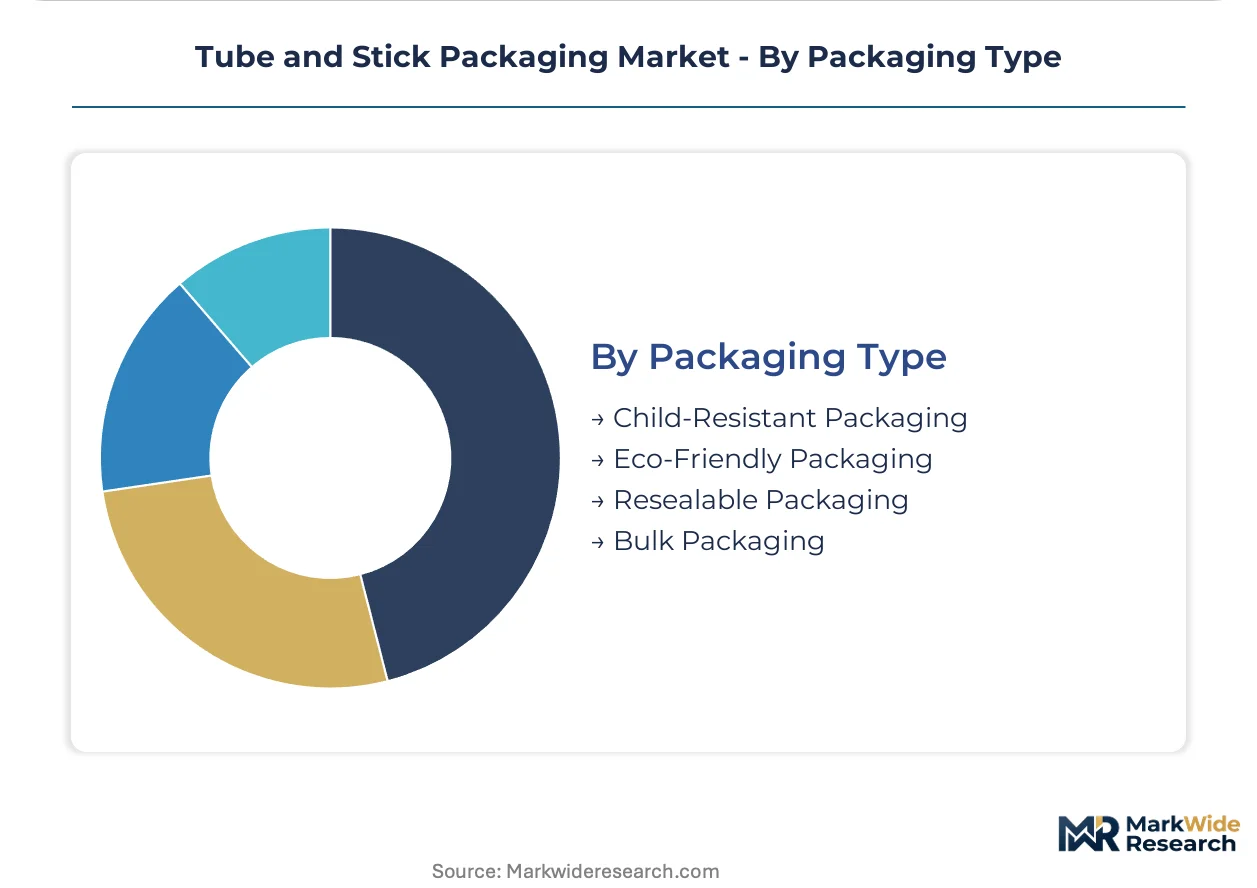
Packaging Type:
Functional requirements and sustainability positioning drive format selection, with regulatory compliance costs varying by certification tier.
- Eco-Friendly Packaging:Mono-material polyethylene structures and paper-based alternatives designed for mechanical recyclability. EU Packaging and Packaging Waste Regulation accelerates substitution toward technically achievable circularity claims.
- Child-Resistant Packaging:Push-and-turn caps and blister formats for pharmaceutical safety compliance. India's generic export growth demands capabilities local converters are racing to build.
- Resealable Packaging:Zipper closures and screw caps for multi-use convenience. Food and personal care segments balance functionality against material complexity penalties in recycling streams.
- Bulk Packaging:Large-format tubes and multi-unit stick pack bundles for institutional and e-commerce channels. Direct-to-consumer displacement of traditional retail compresses minimum order quantities.
Eco-friendly formats capture the largest share of new product development investment; child-resistant capabilities are expanding most quickly in emerging pharmaceutical manufacturing regions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Asia-Pacific extrusion hubs while consumption tilts toward European sustainability mandates and North American pharmaceutical demand. This geographic split shapes converter investment priorities and regulatory compliance pathways.
United States
FDA food-contact substance notifications and EPA resin identification requirements govern material approval timelines for domestic tube manufacturers. Pharmaceutical stick pack demand accelerates around Boston and Research Triangle Park as contract formulation services expand. Converters serving these clusters prioritize child-resistant certification and tamper-evident features.
Germany
EPR mandates under the EU Packaging and Packaging Waste Regulation compel cosmetic brands to source mono-material polyethylene tubes compatible with existing collection infrastructure. ECHA REACH restrictions on phthalate plasticizers force reformulation of flexible tube components. Industrial conversion activity concentrates in North Rhine-Westphalia's packaging corridor.
China
SAMR tightening of food-contact packaging rules creates compliance barriers for imported barrier laminates. Domestic demand for single-serve stick packs surges in Shanghai and Shenzhen tier-one cities as e-commerce direct-to-consumer channels displace traditional retail. Local converters with established GB standard compliance capture first-mover positioning.
India
Domestic pharmaceutical formulation output around Hyderabad and Mumbai drives stick pack demand for unit-dose medications targeting rural distribution networks. BIS certification requirements for pharmaceutical primary materials add qualification layers for exporters. Contract manufacturers serving regulated markets seek child-resistant capabilities local converters are racing to build.
France
ANSM and environmental agency oversight enforces strict recyclability certification for cosmetic packaging under national EPR frameworks. Premium cosmetic brands in the Île-de-France region accelerate conversion to mono-material laminate tubes. This regulatory compression is collapsing demand for legacy aluminum-plastic composite structures.
Tube and Stick Packaging Market Competitive Landscape
The competitive structure tilts toward diversified packaging conglomerates with laminated barrier expertise. Tiered specialization separates premium cosmetic tube specialists from high-volume household product suppliers. Strategic archetypes include sustainability-focused material innovators, pharmaceutical compliance specialists, and integrated paperboard converters. Dominant competitive moves encompass portfolio diversification into mono-material structures and geographic expansion into India's pharmaceutical manufacturing corridor.
Among North American integrated converters, Sonoco anchors the paperboard tube segment with sustainability-focused infrastructure. European specialists exemplify laminated barrier leadership, with Amcor occupying a position in high-performance pharmaceutical applications and Hoffmann Neopac representing the premium cosmetic aluminum tube tier. These three entities capture distinct positioning vectors without direct overlap in core capabilities.
| Leading Market Players |
|---|
| Sonoco |
| Constantia Flexibles |
| Amcor |
| Montebello Packaging |
| Berry Global |
| Albea |
| Hoffmann Neopac |
| CTL Packaging |
| Essel Propack |
| Others |
Value Network & Pricing Analysis
Mono-material polyethylene coextrusion technology is collapsing legacy multi-layer lamination economics while concentrating supply among converters with qualified barrier coating capabilities. This production-method transition simultaneously elevates capital requirements for new entrants and compresses margins for aluminum-dependent premium tube producers facing slug-drawn substrate volatility.
Pricing Analysis
Margin tightening in premium cosmetic tubes reflects aluminum price volatility and EPR-driven substitution toward polymer alternatives. Three-tier pricing structure across premium, standard, and economy levels separates certified mono-material laminates from legacy composites and commodity polyethylene. Price differentiation hinges on barrier performance certification and volume scale. Cost-down pressure on standard-tier converters accelerates because mid-scale extruders struggle to finance high-barrier film line retrofits. Household product buyers exhibit highest price sensitivity; pharmaceutical and premium cosmetic segments absorb certification premiums.
Supply Chain Analysis
Direct-to-brand channels handle sustainability-mandated cosmetic tube demand while distributor networks serve price-sensitive household segments. Raw material supply concentrates in Germany, China, and India, with polymer resin production anchored in North Rhine-Westphalia and Guangdong chemical corridors. Converter operations draw from polyethylene pellets, aluminum slugs, and barrier coating chemistries. Single-source vulnerability in high-performance coextrusion equipment creates qualification bottlenecks. Distribution runs through regional packaging distributors with EPR documentation capabilities for EU-bound shipments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converters are racing to secure backward integration into barrier coating chemistries and polymer compounding to defend margin structures against raw material volatility and qualification delays.
For Market Incumbents: Hedge aluminum exposure through laminate portfolio expansion while accelerating mono-material qualification timelines. Invest in North American and European extrusion capacity to capture EPR-mandated cosmetic brand conversions. Defend against Asian converter encroachment by embedding recycling documentation services into customer contracts. For New Entrants and Emerging Players: E-commerce direct-to-consumer channels offer the most penetrable route for digital-native cosmetic brands seeking short-run personalization capabilities. Target India's pharmaceutical corridor with child-resistant stick pack qualifications. Pursue white-label manufacturing partnerships with sustainability-positioned personal care startups. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified packaging conglomerates seeking barrier coating expertise and EPR-compliant geographic footprints. Long-term viability favors converters with integrated polymer science capabilities spanning formulation through finished tube production. Watch for inflection in mechanical recycling infrastructure investment announcements as circularity claim validation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Lamination Line Investment | Captures EPR-mandated cosmetic brand conversions in France and Germany. |
| Backward Integration into Barrier Coatings | Reduces dependency on single-source specialty chemical suppliers. |
| Child-Resistant Certification Program | Unlocks contract manufacturing opportunities in India's pharmaceutical export corridor. |
| Digital Printing Platform Deployment | Enables short-run personalization for limited-edition cosmetic brand strategies. |
| EPR Documentation Service Launch | Differentiates converter offerings for EU-bound cosmetic and personal care shipments. |
Research Methodology
Multi-period observation of regulatory filing patterns, capacity expansion announcements, and certification timelines anchored the trend analysis, supplemented by interviews with extrusion line operators, cosmetic brand packaging directors, pharmaceutical contract manufacturers, and polymer compounding specialists. Secondary validation drew from ECHA REACH restriction updates, EU Packaging and Packaging Waste Regulation implementation guidance, FDA food-contact substance notifications, and customs trade data for polyethylene and aluminum substrate flows. Bottom-up segment sizing triangulated against top-down macro demand indicators.
Input-output matrices modeled capacity utilization, raw material cost pass-through elasticity, and substitution dynamics across the projection horizon. Segmentation dimensions included product type, material substrate, end-use application, and geographic regulatory cluster. CAGRs derived from trend extrapolation of historical conversion activity and scenario-weighted regulatory implementation timelines. Industry-specific forecast inputs incorporated EPR mandate phase-in schedules and pharmaceutical formulation output projections.
The model holds under stable regulatory implementation schedules and mechanical recycling infrastructure investment continuity; deviation in polymer science talent availability or aluminum price volatility spikes would shift converter margin and qualification timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Insulated Box Liner Market
Packaging Materials
Card Films Market
Packaging Materials
Strip Pack Market
Packaging Materials
Non-Breathable Films Market
Packaging Materials
Window Packaging Market
Packaging Materials
Gift Wrapping Product Market
Packaging Materials
Middle East and Africa Single-Use Packaging Market
Packaging Materials
Mailer Packaging Market
Packaging Materials
Foam Trays Market
Packaging Materials
Cushion Case Liner Market
Packaging Materials
Cork Packaging Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Thermal Lamination Films Market
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Stick Packaging Market