
 Global Thermoelectric Modules Market | 2026-2036
Global Thermoelectric Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Global Thermoelectric Modules Market Outlook
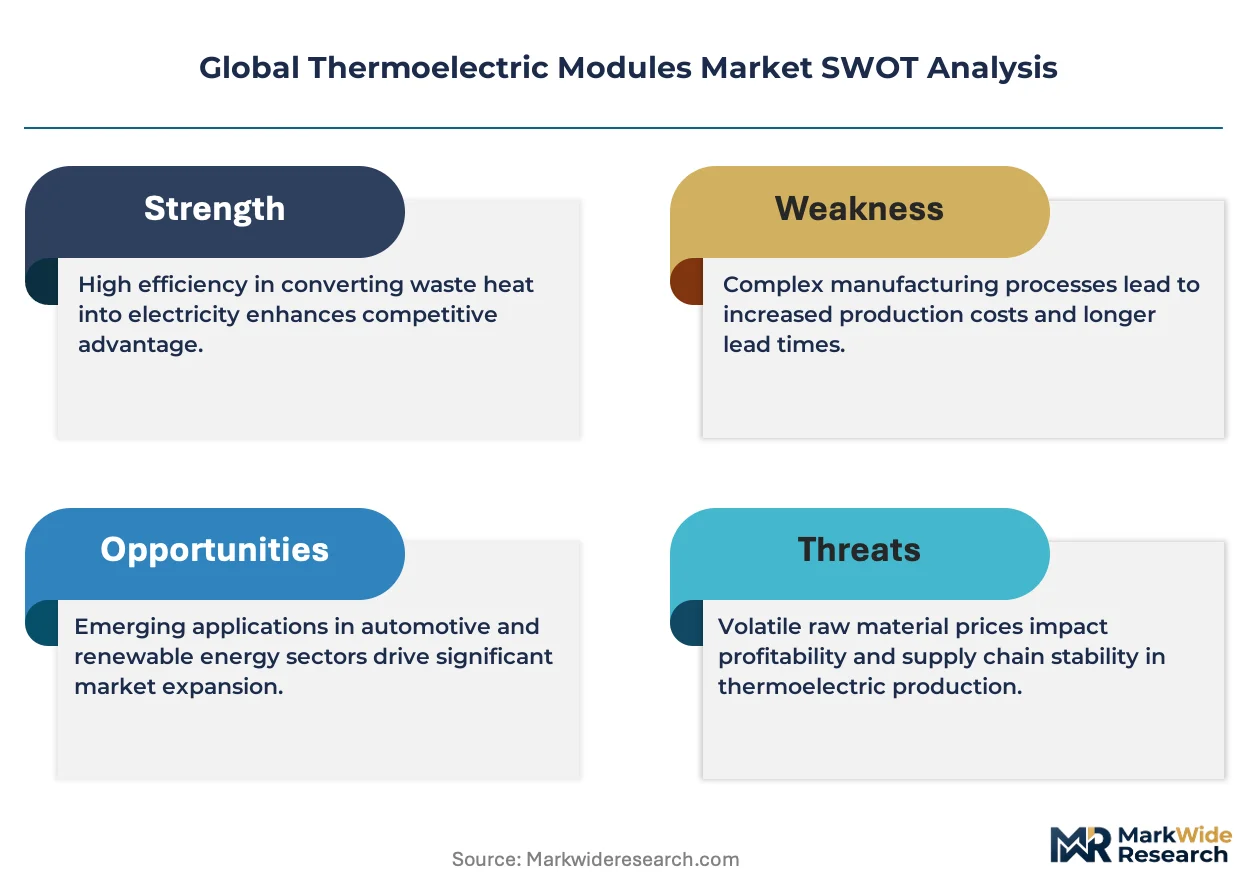
REACH is restructuring material sourcing protocols for thermoelectric module producers across European supply chains. Ferrotec Holdings Corporation leverages vertical integration in ceramic-metal bonding to sustain cost advantages in high-reliability segments. Kyocera Corporation anchors its position through proprietary thick-film metallization processes that dominate telecommunications cooling applications. Coherent Corp competes in precision laser thermal management, where module stability requirements exceed standard commercial specifications.
Thermoelectric modules are solid-state devices composed of semiconductor junctions—typically bismuth telluride alloys—that convert electrical energy into temperature differentials or harvest waste heat into electricity, operating without refrigerants or moving parts across temperature ranges from minus forty to plus two hundred degrees Celsius. Their primary industrial purpose centers on precise thermal stabilization in environments where mechanical compression cooling fails due to size, vibration, or environmental constraints. Bulk modules occupy the mature volume tier in industrial process control, while thin film variants capture expanding margin pools in consumer electronics miniaturization. Micromodule architectures are accelerating fastest in aerospace sensor conditioning, where gram-level mass budgets override unit cost considerations.
FDA device-clearance pathways shape thermal management requirements for portable medical equipment, while EPA refrigerant-phaseout timelines compress the competitive window for solid-state alternatives in North American commercial cooling. China's MEE enforces dual carbon compliance thresholds that elevate thermoelectric waste-heat recovery in steel and cement operations. Japan's METI funds next-generation Seebeck-material research through national laboratory partnerships. Stakeholders must weigh ceramic substrate supply security against thin-film deposition capacity expansion when committing capital across the technology portfolio.
Market Dynamics
The EU F-Gas Regulation is compressing conventional compressor markets and elevating thermoelectric alternatives as the dominant structural force reshaping procurement patterns across precision cooling applications.
Growth Catalysts
- Dual carbon compliance:China's MEE enforces waste-heat recovery mandates in steel and cement operations, accelerating module deployment for industrial energy harvesting.
- Medical device thermal stabilization:FDA clearance pathways for portable diagnostic equipment specify solid-state cooling to eliminate refrigerant leakage risks in point-of-care settings.
- Thick-film metallization advances:Proprietary ceramic-metal bonding processes from East Asian suppliers are reducing junction resistance in high-density telecommunications modules.
Market Restraints
- Bismuth telluride supply concentration:Refined tellurium sourcing clusters in Chinese smelter operations, exposing module fabricators to concentrate availability volatility.
- Coefficient of performance ceiling:Bulk thermoelectric junctions achieve maximum efficiency below vapor-compression alternatives, limiting addressable cooling load ranges.
- REACH material substitution timelines:ECHA restricted substance reviews are forcing reformulation of solder alloys and ceramic dopants before qualification cycles complete.
Strategic Opportunities
- Aerospace sensor conditioning:Gram-level mass budgets in satellite thermal management are overriding unit cost considerations for micromodule architectures.
- Semiconductor fabrication cluster expansion:East Asian precision electronics manufacturing is concentrating demand for sub-ambient wafer chuck cooling in Taiwan, South Korea, and Japan.
- IRA clean energy manufacturing credits:US domestic content bonuses for advanced energy components are incentivizing localized module assembly for waste-heat recovery systems.
Industry Challenges
- Seebeck material synthesis expertise:PhD-level electrochemists capable of controlled zone refining for bismuth telluride alloys command premium compensation in Japanese and German research institutes.
- Multi-physics simulation capability:Coupled thermal-electric-mechanical modeling for custom module design requires software licenses and trained engineers that mid-tier fabricators struggle to retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Thermoelectric Modules Market |
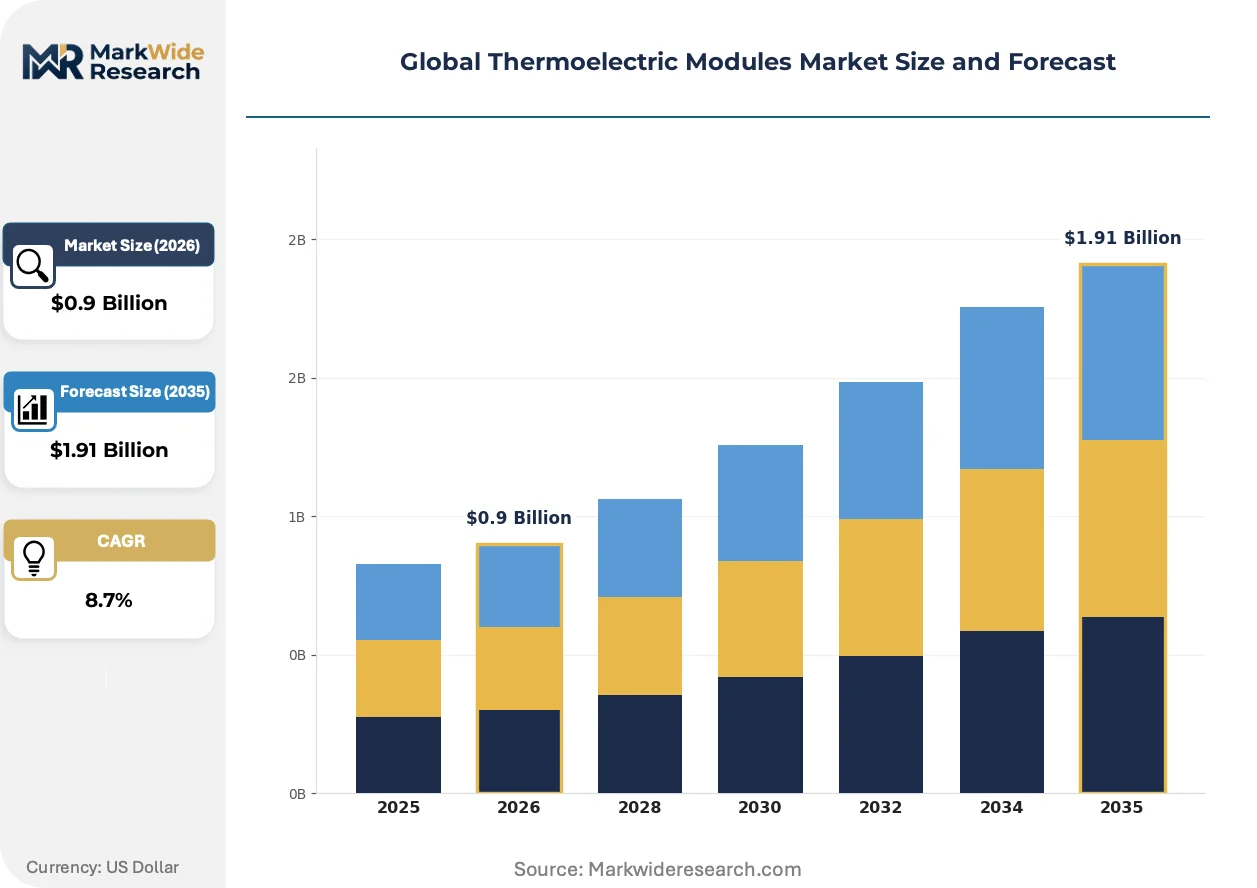
| Market Size in 2026 | $0.9 Billion |
| Market Size in 2035 | $1.91 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk, Thin Film, Micromodule, Custom Designed End User: Consumer Electronics, Automotive, Industrial, Aerospace Application: Cooling Systems, Power Generation, Waste Heat Recovery, Temperature Control Technology: PELTIER Effect, Seebeck Effect, Module Design, Hybrid Systems |
| Companies Covered | Ferrotec Holdings Corporation, Kyocera Corporation, Coherent Corp, Laird Thermal Systems, Crystal Ltd., Komatsu Ltd., Hi-Z Technology Inc., KELK Ltd., TEC Microsystems GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Thermoelectric Modules Market Strategic Shifts
Material scientists and process engineers are converging on architectures that sacrifice raw efficiency for deployability, reshaping how thermal management solutions penetrate cost-sensitive verticals.
Thin-film thermoelectric deposition on flexible polymer substrates is modularizing wearable and conformal electronics cooling. Medical patch manufacturers and flexible display fabricators are adopting these architectures faster than projected, compressing the timeline for rigid ceramic-based solutions in sub-watt applications. The technology is modularizing supply chains around roll-to-roll processing equipment rather than batch ceramic sintering.
REACH substance restrictions are forcing systematic replacement of lead-bearing solders and certain ceramic dopants in European-sourced modules. Industrial consequence includes extended qualification cycles for redesigned junction assemblies as fabricators validate alternative metallization schemes. Telecommunications cooling applications face the steepest compliance burden given their reliance on historical high-reliability material sets.
Buyer consolidation among precision electronics OEMs is compressing vendor qualification cycles and demanding module-level thermal performance guarantees rather than discrete component sales. Direct procurement relationships with East Asian semiconductor fabrication facilities are displacing traditional distributor channels for high-volume applications. Taiwan and South Korea display the most pronounced concentration of this purchasing pattern shift.
Global Thermoelectric Modules Market Segmentation
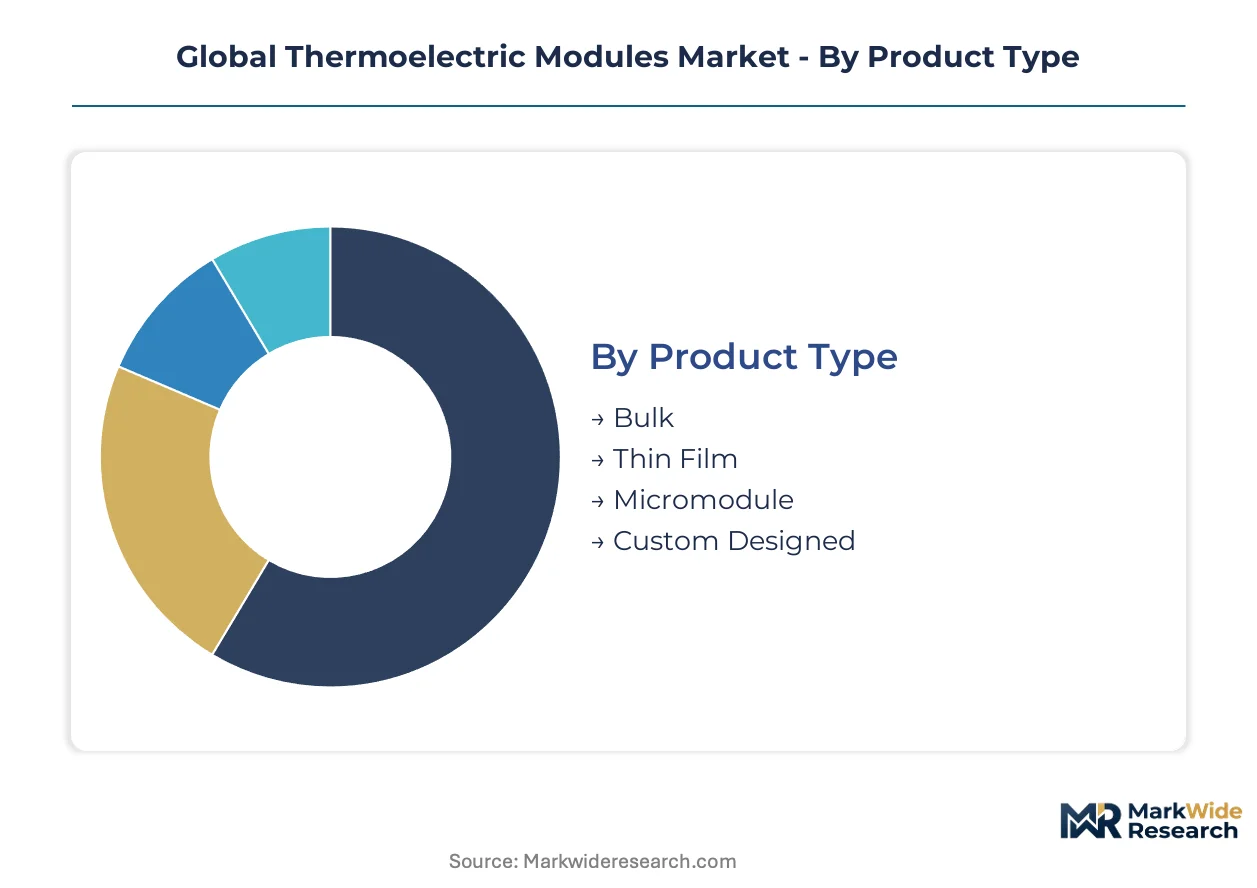
Thermoelectric module procurement splits across four critical dimensions. Product architecture determines manufacturing scale and margin structure. End-use concentration shapes regional demand clusters and regulatory exposure.
Product Type:
Supply concentration in East Asian ceramic sintering operations favors bulk module fabricators with captive substrate capacity.
- Bulk:Standardized bismuth telluride junctions bonded to alumina ceramic substrates dominate industrial process control and telecommunications cooling. Demand concentrates in Chinese precision electronics manufacturing clusters serving semiconductor fabrication equipment.
- Thin Film:Sputtered or electrodeposited semiconductor layers on flexible polymer substrates enable conformal cooling for wearable medical patches and curved display assemblies. Japanese roll-to-roll processing equipment suppliers are capturing expanding margin pools as medical device OEMs accelerate qualification timelines.
- Micromodule:Sub-gram architectures prioritize mass minimization over unit cost in satellite thermal management.
- Custom Designed:Application-specific junction geometries and metallization schemes address unique thermal-electric-mechanical constraints.
Today's leader: Bulk. Tomorrow's challenger: Thin Film.
End User:
Cost tier differentiation separates high-reliability aerospace specifications from consumer electronics price sensitivity.
- Consumer Electronics:Miniaturized cooling for smartphones, AR headsets, and gaming peripherals drives thin-film adoption. South Korean display manufacturers are integrating sub-watt modules directly into flexible OLED assemblies.
- Automotive:Cabin comfort systems and battery thermal management in electric vehicles favor bulk modules with automotive-grade qualification. German OEMs are specifying solid-state alternatives under EU F-Gas Regulation compliance timelines.
- Industrial:Process control instrumentation and laser thermal stabilization specify high-reliability bulk architectures with extended operational lifespans.
- Aerospace:Satellite sensor conditioning and avionics cooling demand micromodule architectures where gram-level mass budgets override procurement cost considerations.
Industrial volume anchors current revenue. Automotive applications are climbing the fastest as electrification accelerates.
Application:
Volume concentration in cooling systems reflects the technology's historical deployment pattern, while emerging applications reshape competitive positioning.
- Cooling Systems:Solid-state refrigeration for medical devices, telecommunications equipment, and precision electronics represents the mature volume tier. FDA device-clearance pathways for portable diagnostic equipment are compressing refrigerant-based alternatives in point-of-care settings.
- Waste Heat Recovery:Industrial energy harvesting from steel and cement operations is gaining share fastest under China's MEE dual carbon enforcement. Module stability across wide temperature differentiates qualified suppliers.
- Power Generation:Remote sensor networks and IoT edge devices leverage thermoelectric harvesting to eliminate battery replacement cycles.
- Temperature Control:Precision thermal stabilization for semiconductor wafer chucks and laser cavities demands sub-degree accuracy.
Cooling systems dominate present procurement. Waste heat recovery shows steepest expansion trajectory.
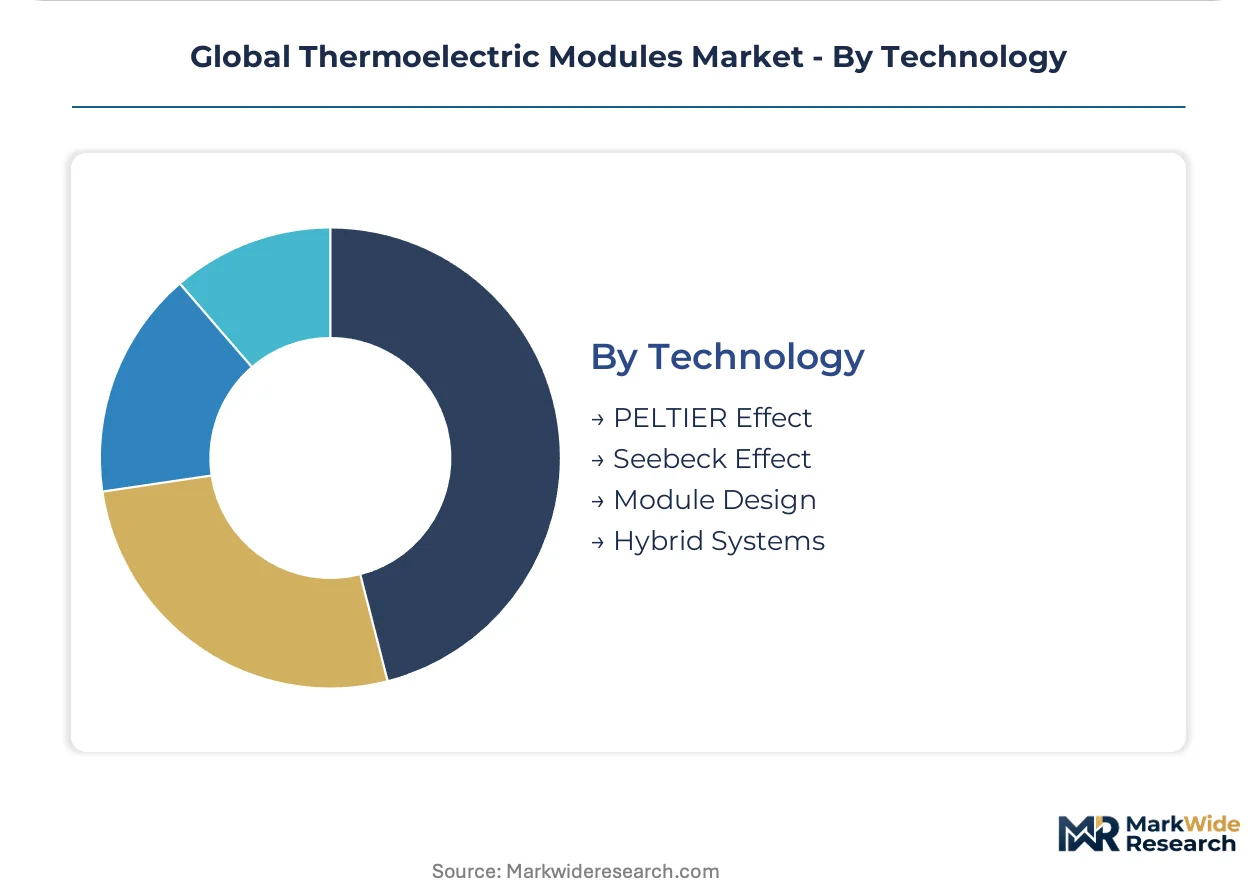
Technology:
Margin structure varies sharply between established Peltier cooling architectures and emerging hybrid system designs.
- PELTIER Effect:Reversible thermal-electric conversion for active cooling and heating applications. Medical device manufacturers specify Peltier-based modules to eliminate refrigerant leakage risks in portable equipment.
- Seebeck Effect:Unidirectional heat-to-electricity conversion for energy harvesting. Japan's METI funds next-generation Seebeck-material research through national laboratory partnerships targeting higher conversion efficiencies.
- Module Design:Junction geometry optimization and ceramic-metal bonding process development differentiate supplier capabilities.
- Hybrid Systems:Integrated thermoelectric-vapor compression architectures address cooling loads beyond solid-state efficiency ceilings.
PELTIER architectures anchor commercial deployment. Hybrid systems are emerging as the challenger for high-capacity applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
PhD-level electrochemists specializing in bismuth telluride zone refining concentrate in Japanese national laboratories and German research institutes. These talent clusters anchor regional innovation capacity. Foundry engineers with ceramic-metal bonding expertise cluster in East Asian manufacturing hubs.
China
Steel and cement operations deploy waste-heat recovery modules under MEE dual carbon enforcement timelines. The country's dual carbon goals compress conventional compressor markets in industrial cooling. Manufacturing clusters around Shenzhen and Shanghai concentrate precision electronics module procurement for semiconductor fabrication equipment.
Japan
Telecommunications equipment manufacturers specify thick-film metallization modules for base station thermal management. METI funds next-generation Seebeck-material research through national laboratory partnerships targeting higher conversion efficiencies. Nagoya-area ceramic fabricators supply high-reliability substrates for aerospace micromodule architectures.
Germany
Automotive OEMs specify solid-state cooling alternatives under EU F-Gas Regulation compliance timelines for electric vehicle battery thermal management. ECHA REACH reviews force reformulation of solder alloys in European-sourced modules. Bavarian precision engineering clusters integrate thermoelectric temperature control into laser manufacturing equipment.
United States
Portable medical device manufacturers pursue FDA clearance pathways specifying solid-state cooling to eliminate refrigerant leakage risks. IRA clean energy manufacturing credits incentivize localized module assembly for waste-heat recovery systems. Greater Boston and Pacific Northwest research corridors concentrate advanced material synthesis expertise.
South Korea
Display manufacturers integrate sub-watt thin-film modules directly into flexible OLED assemblies for consumer electronics. MFDS medical device regulations parallel FDA thermal stability requirements for diagnostic equipment. Seoul-area semiconductor fabrication facilities concentrate demand for sub-ambient wafer chuck cooling modules.
Global Thermoelectric Modules Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers. The vendor base organizes around three strategic archetypes: integrated ceramic-metal bonding specialists, precision thermal management solution providers, and application-specific custom module fabricators. Dominant competitive moves include backward integration into ceramic substrate production and strategic partnerships with East Asian semiconductor fabrication facilities.
Among Japan-based conglomerates, Ferrotec Holdings Corporation and Kyocera Corporation exemplify integrated ceramic-metal bonding capabilities. TEC Microsystems GmbH represents European precision engineering specialization in compact module architectures. These three anchors occupy positions across the premium reliability tier, with Ferrotec and Kyocera leveraging captive substrate capacity and TEC Microsystems emphasizing custom junction geometries for telecommunications and medical applications.
| Leading Market Players |
|---|
| Ferrotec Holdings Corporation |
| Kyocera Corporation |
| Coherent Corp |
| Laird Thermal Systems |
| Crystal Ltd. |
| Komatsu Ltd. |
| Hi-Z Technology Inc. |
| KELK Ltd. |
| TEC Microsystems GmbH |
| Others |
Value Chain & Pricing Dynamics
EU F-Gas Regulation compliance timelines gate access to premium-tier automotive and medical module contracts, compressing qualified supplier pools while elevating pricing power for REACH-certified fabricators with captive ceramic substrate capacity.
Pricing Analysis
Module-level thermal performance guarantees versus discrete component sales define the bundled-unbundled split. Three-tier pricing structure across aerospace-qualified, industrial-grade, and consumer-economy tiers differentiates on certification level and after-sales service intensity. Cost compression in consumer electronics thin-film segments is intensifying because South Korean display manufacturers are integrating sub-watt modules directly into flexible OLED assemblies. Automotive OEMs under EU F-Gas Regulation timelines show least price sensitivity; consumer electronics OEMs concentrate procurement volume and exert maximum downward pressure.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale semiconductor fabrication facility demand in Taiwan and South Korea, displacing traditional distributor relationships for high-volume wafer chuck cooling applications. Bismuth telluride refining clusters in China, ceramic substrate sintering operations in Japan, and precision metallization foundries in Germany anchor upstream supply. Tellurium concentrate availability, alumina ceramic dopant formulations, and thick-film bonding equipment constitute critical input dependencies. Single-source vulnerability in Chinese tellurium smelter operations exposes module fabricators to concentrate availability volatility. Distribution runs through qualified supplier programs for medical device OEMs and direct procurement desks at East Asian precision electronics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film deposition cost curves are steepening margin expansion for early movers, as medical patch manufacturers and flexible display fabricators accelerate qualification timelines faster than projected.
For Market Incumbents: Acquire ceramic-metal bonding expertise in Nagoya-area substrate fabricators to defend against thin-film modularization threats. Lock in long-term tellurium concentrate offtake agreements before Chinese smelter capacity rationalizes. Extend qualification cycle advantages by investing in REACH-compliant solder alloy reformulation ahead of ECHA substance review deadlines. For New Entrants and Emerging Players: Enter via micromodule architectures for satellite thermal management, where gram-level mass budgets override incumbent cost advantages and procurement runs through non-traditional aerospace channels. Target South Korean semiconductor fabrication equipment suppliers seeking localized sub-ambient wafer chuck cooling alternatives. Pursue direct technical partnerships with METI-funded national laboratory researchers for Seebeck material synthesis credibility. For Investors and Strategic Acquirers: Roll-up economics work for precision thermal management specialists because buyer consolidation among telecommunications OEMs is compressing vendor counts and concentrating procurement with qualified module-level guarantee providers. Five-to-ten year viability hinges on thin-film deposition equipment access and ceramic substrate supply security. Watch for inflection when East Asian semiconductor fabrication facility expansion accelerates sub-ambient cooling module procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Substrate Backward Integration | Captive alumina supply insulates Ferrotec and Kyocera from Chinese smelter volatility. |
| Thin-Film Roll-to-Roll Processing Scale-Up | Japanese equipment suppliers capture expanding margin pools in medical patch cooling. |
| REACH-Compliant Solder Alloy Reformulation | ECHA reviews force qualification cycle investments before European medical contracts renew. |
| Direct Semiconductor Fab Procurement Relationships | Taiwan and South Korean fabs displace distributor channels for high-volume wafer chuck modules. |
| METI-Funded Seebeck Material Research Partnership | Japanese national laboratory alliances anchor next-generation energy harvesting efficiency gains. |
Study Parameters
Bottom-up medical device and semiconductor fabrication equipment modeling reconciled against top-down bismuth telluride concentrate and ceramic substrate production tracking forms the analytical core of this study. Primary interviews with biomedical engineers at portable diagnostic OEMs, procurement leads at East Asian precision electronics clusters, plant managers at Chinese steel and cement operations deploying waste-heat recovery, and thermal management specialists at telecommunications equipment manufacturers combined with secondary validation from EPA refrigerant-phaseout timelines, FDA device-clearance pathway databases, ECHA REACH substance restriction registers, and METI research funding disclosures. Top-down trade data and bottom-up installation tracking triangulate to module-level unit estimates.
Input-output matrices map bismuth telluride alloy consumption through ceramic substrate bonding operations to end-use application demand across cooling systems, waste heat recovery, and power generation segments over the projection horizon. Product architecture splits across bulk, thin-film, micromodule, and custom-designed tiers; end-use concentration spans consumer electronics, automotive, industrial, and aerospace; application segmentation covers cooling, waste heat recovery, power generation, and temperature control; technology differentiation tracks Peltier, Seebeck, and hybrid system architectures. CAGRs derive from segment-level volume trajectories stress-tested against regulatory enforcement timelines and OEM procurement pattern shifts. Forecast inputs incorporate MEE dual carbon compliance thresholds, EU F-Gas Regulation phaseout schedules, and IRA clean energy manufacturing credit utilization rates.
Inputs from EPA, ECHA, METI, and MEE regulatory filings were available through the study window; gaps in real-time East Asian semiconductor fabrication facility capex disclosure introduce uncertainty bands around precision electronics demand projections. Forecasts reflect assumptions regarding REACH substance substitution timelines, tellurium concentrate supply continuity, and thin-film deposition equipment delivery schedules. Periodic stress-testing of base assumptions against regulatory enforcement acceleration or ceramic substrate supply disruptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Photosensitive Semiconductor Device Market
Semiconductor Devices
Epi Wafer Market
Semiconductor Devices
N-Topcon Solar Cells Market
Semiconductor Devices
VCSEL Market
Semiconductor Devices
India MLCC Market
Semiconductor Devices
Japan Semiconductor Device Market
Semiconductor Devices
Global 8 - Bit Microcontroller Market
Semiconductor Devices
Semiconductor Device in Aerospace and Defense Industry Market
Semiconductor Devices
Americas Semiconductor Diode Market
Semiconductor Devices
Global Gan on Diamond Semiconductor Substrates Market
Semiconductor Devices
Japan International CEP Market
Semiconductor Devices
Japan Semiconductor Device in Consumer Industry Market
Semiconductor Devices
Global Silicon Carbide Wafers Market
Semiconductor Devices
Voltage Controlled Oscillators Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Hybrid Microcircuits Market