
 Zinc Oxide Market | 2026-2036
Zinc Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Zinc Oxide Market Intelligence
Direct synthesis and vapor phase transport methods is narrowing the purity gap between commodity and specialty zinc oxide grades. Hindustan Zinc leverages captive zinc metal supply to anchor cost positions across Asian markets. EverZinc competes through R&D intensity in nanoparticle formulations for cosmetic and pharmaceutical applications. American Chemet Corporation sustains geographic dominance in North American rubber compounding channels through long-standing distributor relationships.
Zinc oxide is an inorganic compound with the formula ZnO, typically produced as a white powder with particle sizes ranging from nanoscale to several microns depending on the manufacturing route; it functions primarily as an activator, UV absorber, or pigment across industrial formulations. The French Process and American Process remain the dominant manufacturing routes for bulk applications, though the wet chemical process is gaining traction where sub-micron particle distribution is specified. Nanoparticle grades command premium positioning in cosmetics and pharmaceuticals due to transparency and enhanced reactivity, while uncoated bulk material serves as the volume foundation in rubber manufacturing where cost efficiency governs procurement.
REACH registration requirements in Europe and FDA oversight of pharmaceutical-grade zinc oxide in the United States shape product certification pathways and limit market access for non-compliant suppliers. China's GB standards and SAMR oversight establish parallel compliance thresholds for domestic consumption and export-oriented production. Stakeholders must monitor evolving particulate toxicity classifications under ECHA review and corresponding formulation substitution patterns in personal care applications.
Market Dynamics
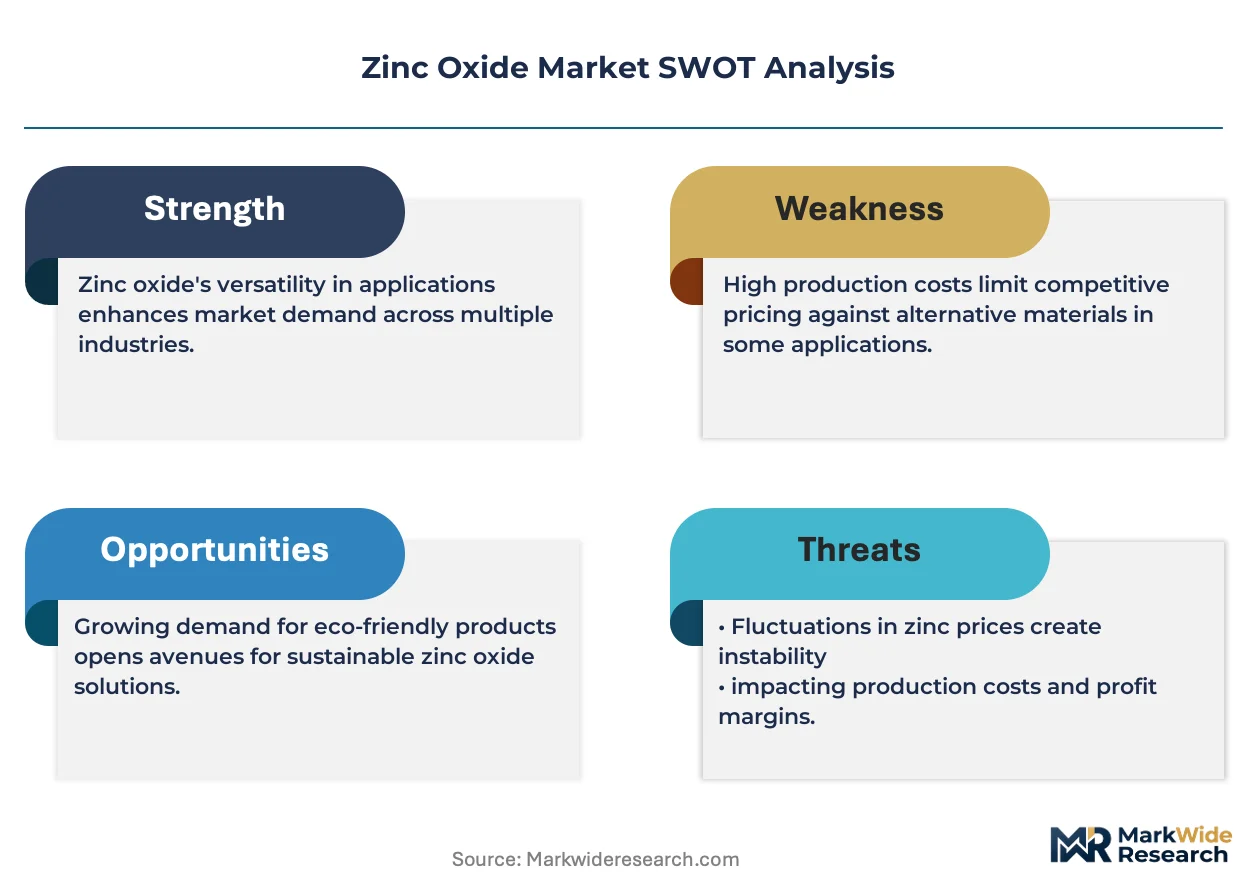
Rubber tire manufacturers are expanding zinc oxide consumption for vulcanization acceleration, while REACH and RoHS compliance in Europe is redirecting formulation choices toward coated and nanoparticle grades. This dual pressure from volume demand and regulatory stringency is compressing margins for commodity producers while rewarding specialized grades.
Growth Catalysts
- Vulcanization Acceleration Demand:Rubber tire manufacturers are expanding zinc oxide consumption as automotive production scales in China and Southeast Asia. The compound functions as an essential activator in sulfur-based cross-linking systems.
- REACH Registration Thresholds:European chemical compliance requirements are redirecting procurement toward coated and nanoparticle grades that meet particulate toxicity standards. This is elevating technical specifications across personal care and pharmaceutical applications.
- Photocatalytic Functionality:Advanced ceramics and coatings applications are leveraging zinc oxide's UV absorption and photocatalytic properties for antimicrobial surfaces and self-cleaning materials.
Market Restraints
- Zinc Metal Price Volatility:Feedstock costs for the French Process and American Process fluctuate with London Metal Exchange pricing, compressing margins for non-integrated producers without captive smelter access.
- Supply Concentration in China:Domestic zinc processing capacity expansion has concentrated global production in Shandong and Hunan provinces, creating geographic risk for buyers seeking supply diversification.
- Titanium Dioxide Substitution:Certain pigment applications face displacement from TiO2 in paint formulations where opacity requirements permit reformulation at competitive cost structures.
Strategic Opportunities
- Pharmaceutical-Grade Certification:FDA oversight of pharmaceutical-grade zinc oxide in the United States creates premium positioning for producers achieving USP monograph compliance, opening margins above commodity tiers.
- Cosmetic Transparency Requirements:Nanoparticle grades command premium positioning in sun care and color cosmetics due to transparency and enhanced reactivity, with South Korean and Japanese beauty markets driving specification intensity.
- Green Chemistry Incentives:The EU Green Deal and associated sustainable chemistry frameworks are favoring wet chemical process routes with lower energy intensity versus traditional thermal methods.
Industry Challenges
- Particulate Toxicology Certification:ECHA review of nanomaterial classifications is extending compliance timelines for personal care applications, requiring toxicological dossiers that strain mid-tier R&D budgets.
- Process Technology Retrofit Costs:Transitioning from French Process to wet chemical methods for sub-micron particle distribution requires capital expenditure in precipitation and calcination equipment.
- Dual Standard Navigation:Producers must simultaneously satisfy China's GB standards and SAMR oversight for domestic consumption while meeting REACH and FDA requirements for export markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zinc Oxide Market |
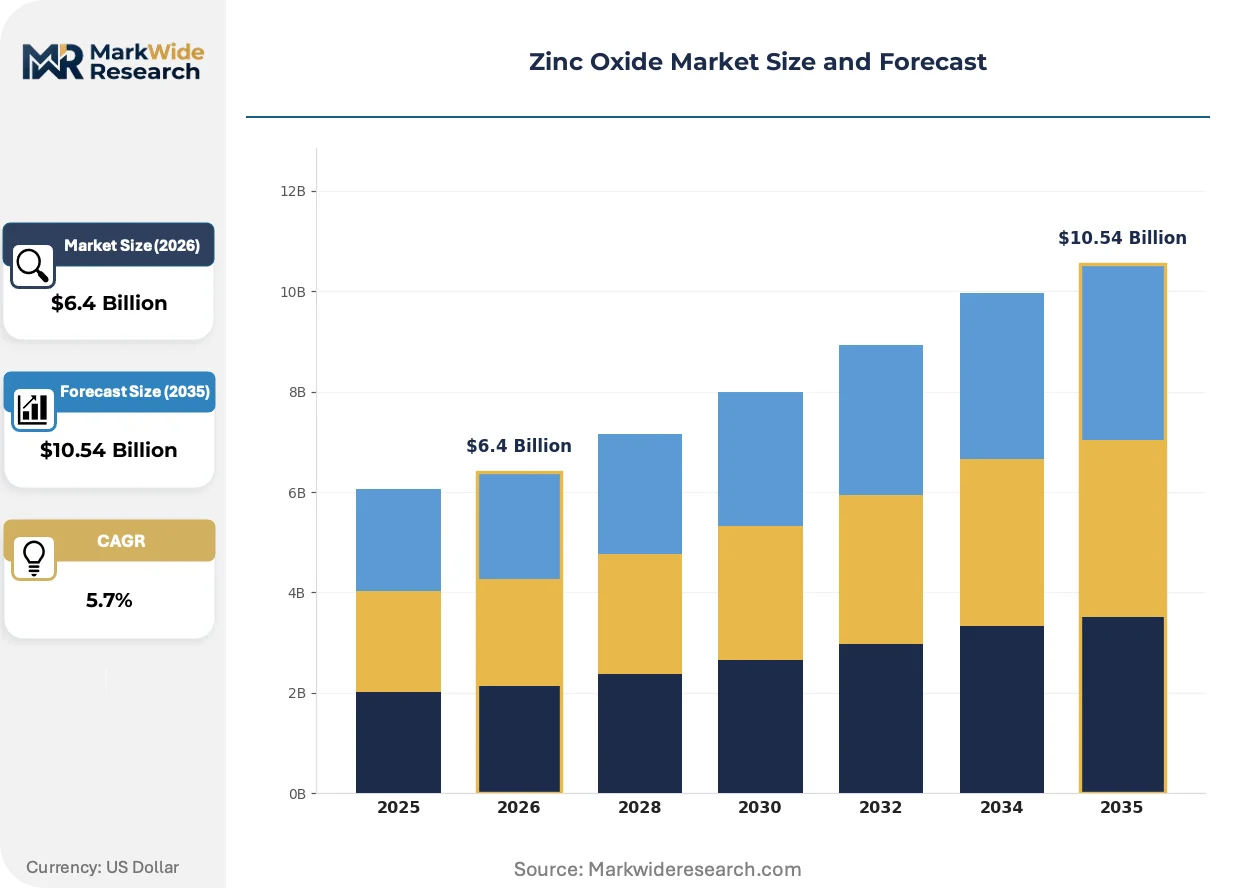
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $10.54 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Micronized, Coated, Uncoated, Bulk Application: Rubber Manufacturing, Cosmetics, Paints & Coatings, Ceramics, Pharmaceuticals Manufacturing Process: French Process, American Process, Wet Chemical Process, Direct Synthesis, Vapor Phase Transport End User Industry: Paint Producers, Cosmetic Manufacturers, Pharmaceutical Companies, Rubber Producers, Ceramic Fabricators |
| Companies Covered | RUBAMIN, Hindustan Zinc, EverZinc, SILOX SA, American Chemet Corporation, Zochem, Akrochem Corporation, HANIL, Zinc Nacional S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zinc Oxide Market Strategic Shifts & Innovations
Direct synthesis and vapor phase transport methods are narrowing the purity gap between commodity and specialty grades. Manufacturing innovation is compressing the traditional tier structure while regulatory differentiation is creating new certification-based segmentation.
Continuous precipitation systems with inline particle size monitoring are rendering obsolete batch-processed French Process material for cosmetic and pharmaceutical applications. Korean and Japanese sunscreen manufacturers are specifying real-time-controlled particle distribution to achieve transparency thresholds. This technology shift is compressing the addressable market for uncoated bulk grades in premium personal care channels.
ECHA's evolving particulate toxicity classifications under REACH are mandating comprehensive toxicological dossiers for nanoparticle zinc oxide in personal care. The industrial consequence is a bifurcation between registered suppliers with dossier completeness and non-compliant producers facing market access restrictions. Cosmetic formulators in Germany and France are accelerating substitution toward coated grades with established safety profiles.
Long-term supply agreements with vulcanization chemical distributors are displacing spot market procurement in North American rubber compounding. Major tire manufacturers are consolidating supplier panels to secure volume commitments and technical service integration. This consolidation pattern is most visible in the Ohio and Tennessee manufacturing corridors where domestic automotive production anchors demand concentration.
Zinc Oxide Market Segmentation
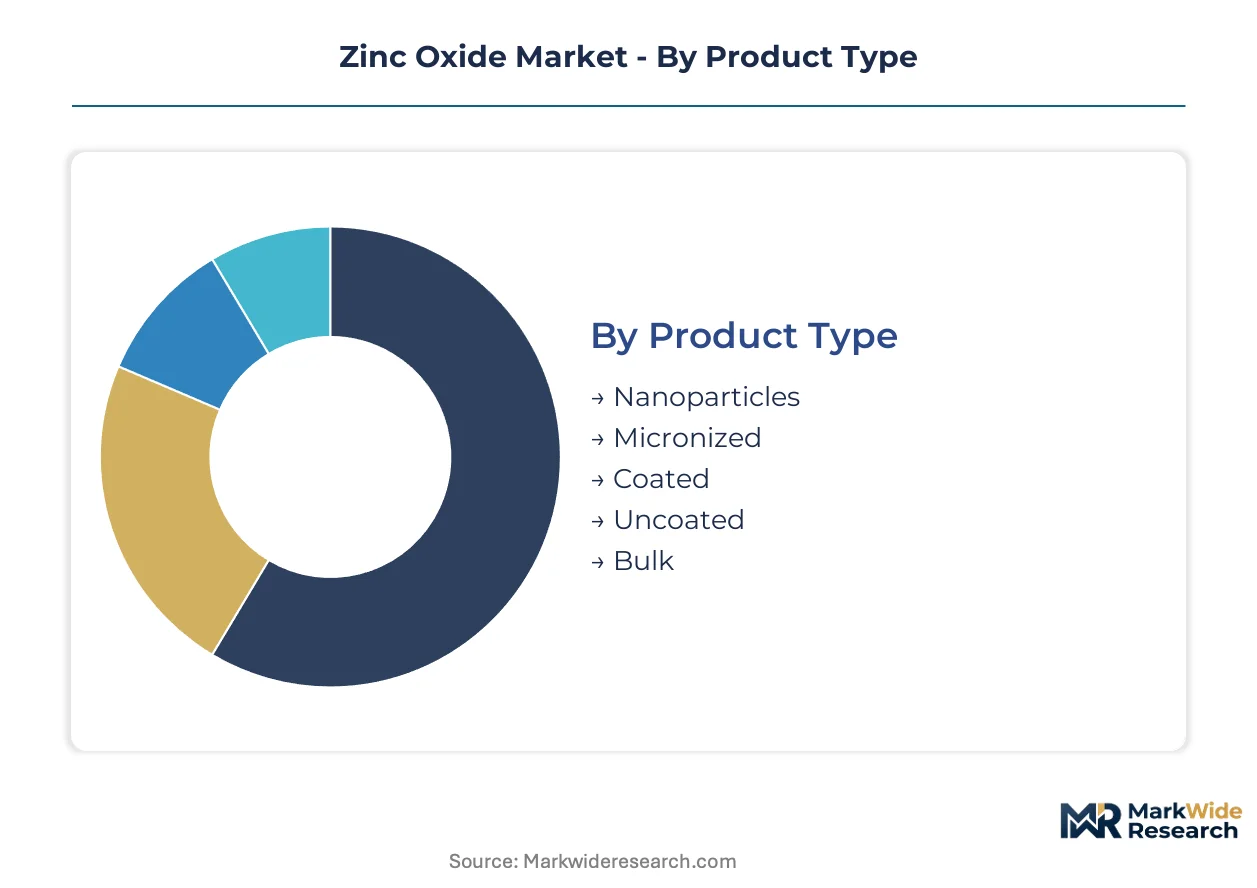
Zinc oxide segmentation operates on a velocity spectrum where tire rubber cycles inventory weekly while pharmaceutical certification spans years. Understanding these turnover differentials shapes capacity planning and margin capture strategies across producer portfolios.
Product Type:
Cycle times compress from commodity bulk grades turning monthly to cosmetic nanoparticles requiring quarterly batch validation.
- Nanoparticles:Sub-100nm particle distribution delivers transparency in sun care formulations. South Korean beauty manufacturers specify real-time-controlled distribution for premium positioning. REACH dossier requirements extend compliance timelines and elevate entry barriers.
- Micronized:0.1-1.0μm particle range bridges performance and cost in industrial coatings. Paint producers in Germany and France specify micronized grades for opacity control where TiO2 substitution pressures operate.
- Coated:Surface-treated variants for enhanced dispersion in polymer matrices.
- Uncoated:Standard grades for cost-sensitive rubber vulcanization applications.
- Bulk:High-volume commodity material for tire manufacturing and general industrial use.
Bulk grades dominate installed base. Nanoparticles are where expansion concentrates.
Application:
Margin tiers separate from volume tiers — rubber consumes tonnage while cosmetics and pharmaceuticals capture value per kilogram.
- Rubber Manufacturing:Vulcanization activation consumes the largest tonnage globally. Tire producers in China and Thailand anchor demand concentration as automotive production scales. Long-term supply agreements are displacing spot procurement in North American compounding channels.
- Cosmetics:Sunscreen transparency requirements drive specification intensity. Japanese and South Korean formulators mandate sub-50nm particle distribution for aesthetic performance. ECHA nanomaterial classifications are accelerating substitution toward coated grades with established safety profiles.
- Paints & Coatings:UV absorption and antimicrobial functionality in architectural and industrial formulations.
- Ceramics:Electronic and structural ceramic applications leveraging piezoelectric properties.
- Pharmaceuticals:USP-grade material for dermatological and nutritional applications. FDA oversight creates premium positioning for compliant producers.
Rubber Manufacturing anchors volume concentration. Pharmaceuticals deliver the steepest expansion trajectory.
Manufacturing Process:
Capital intensity and energy consumption stratify competitive positions across production routes.
- French Process:Thermal oxidation of zinc metal yields high-purity grades. Hindustan Zinc leverages captive smelter supply to anchor Asian cost positions. LME price volatility compresses margins for non-integrated operators.
- American Process:Reduction of zinc ore with subsequent oxidation. Long-standing installations in North American rubber channels sustain geographic supplier relationships.
- Wet Chemical Process:Precipitation routes with lower thermal energy requirements. EU Green Deal frameworks favor these methods for carbon intensity reduction.
- Direct Synthesis:Emerging routes narrowing purity gaps between commodity and specialty grades.
- Vapor Phase Transport:Advanced methods for ultrafine particle distribution in electronics and photonics applications.
French and American Processes dominate installed base. Wet Chemical routes are where expansion concentrates.
End User Industry:
Procurement sophistication varies from specification-driven pharmaceutical qualification to price-sensitive bulk rubber tendering.
- Paint Producers:Formulation flexibility permits TiO2 substitution where opacity requirements allow. German and French architectural coatings manufacturers specify particle distribution for weathering performance.
- Cosmetic Manufacturers:South Korean and Japanese beauty markets drive the most stringent transparency and safety specifications globally. ECHA compliance dossiers are consolidating supplier panels toward registered producers.
- Pharmaceutical Companies:FDA USP monograph compliance creates premium tier access. Toxicological certification timelines strain mid-tier R&D budgets.
- Rubber Producers:Tire manufacturers in Ohio and Tennessee corridors consolidate supplier relationships for volume security.
- Ceramic Fabricators:Electronic substrate and structural ceramic applications with specialized purity requirements.
Rubber Producers dominate installed base. Cosmetic Manufacturers are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese zinc oxide shipments dominate export flows to Southeast Asian tire plants and European cosmetic formulators. Shandong and Hunan processing clusters anchor this trade corridor. Regulatory divergence between REACH jurisdictions and China's GB standards fragments compliance pathways.
China
Automotive production scaling in Shanghai and Wuhan drives vulcanization chemical consumption. SAMR oversight of GB standards for zinc oxide purity operates alongside MEE environmental enforcement. Shandong province concentrates wet chemical process capacity expansion serving both domestic tire makers and export-oriented cosmetic manufacturers.
United States
FDA USP monograph compliance creates premium tier access for pharmaceutical-grade material. Ohio and Tennessee tire manufacturing corridors consolidate supplier relationships through long-term distribution agreements. EPA oversight of particulate emissions shapes manufacturing process choices in domestic production facilities.
Germany
ECHA REACH dossier requirements extend compliance timelines for nanoparticle grades in personal care applications. BASF and Lanxess formulation laboratories in Ludwigshafen drive specification intensity for coated variants. North Rhine-Westphalia industrial clusters anchor procurement sophistication in European rubber compounding channels.
Japan
METI industrial standards and PMDA pharmaceutical oversight create dual certification requirements for cosmetic and dermatological applications. Osaka-Kobe manufacturing belt specifies sub-50nm particle distribution for sunscreen transparency. JIS standard alignment with REACH classifications simplifies export-oriented production planning.
South Korea
MFDS cosmetic safety regulations mandate nanoparticle disclosure thresholds exceeding European baselines. Seoul-Incheon beauty manufacturing corridor drives the most stringent global specifications for zinc oxide transparency and reactivity. Domestic formulators specify real-time particle distribution monitoring as a procurement requirement.
Zinc Oxide Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered market positions. Integrated zinc smelters leverage captive metal supply to anchor cost positions in bulk rubber applications. Independent processors compete through formulation service intensity and certification completeness. Competitive moves concentrate on backward integration into zinc metal supply and forward integration into pharmaceutical-grade certification pathways.
Among Asia-Pacific integrated producers, Hindustan Zinc and HANIL exemplify smelter-captive cost structures. EverZinc occupies a position within the specialty-grade tier focused on nanoparticle formulation capabilities. American Chemet Corporation represents geographic channel control through established North American distributor relationships. Zochem and Zinc Nacional S.A. sit within regional supply positions serving Western Hemisphere rubber compounding demand. RUBAMIN and SILOX SA exemplify process-technology differentiation in European and Middle Eastern markets respectively.
| Leading Market Players |
|---|
| RUBAMIN |
| Hindustan Zinc |
| EverZinc |
| SILOX SA |
| American Chemet Corporation |
| Zochem |
| Akrochem Corporation |
| HANIL |
| Zinc Nacional S.A. |
| Others |
Cost & Logistics Intelligence
Shandong-to-Rotterdam container freight corridors carry zinc oxide cargo where bunker fuel surcharges and port congestion fees compound with LME zinc volatility to compress margins for non-integrated processors serving European cosmetic formulators while rewarding Shandong-based wet chemical producers with captive logistics contracts.
Pricing Analysis
The French Process-to-wet chemical pricing gap separates commodity bulk grades from sub-micron specialty tiers. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and rubber-grade levels reflects certification completeness and particle distribution control. Cost compression in uncoated bulk segments stems from Chinese capacity expansion and tire manufacturer consolidation. Rubber compounding procurement teams exhibit highest price sensitivity through annual tender processes, while South Korean cosmetic formulators prioritize transparency specifications over unit cost.
Supply Chain Analysis
Export-control scrutiny under REACH nanomaterial registrations limits unregistered Chinese producers from European personal care channels. Production concentrates in China, Germany, and India, with Shandong province anchoring wet chemical capacity expansion. Feedstock draws from LME-linked zinc metal, precipitating agents, and surface coating chemistries. Single-source vulnerability concentrates in Shandong processing clusters where environmental enforcement actions can disrupt export flows. Distribution runs through vulcanization chemical distributors in North American rubber corridors and direct technical sales for pharmaceutical-grade certification pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tire manufacturer procurement consolidation across Ohio and Tennessee corridors has shifted bargaining power toward volume buyers, forcing supplier panel reductions and long-term contract demands that squeeze mid-tier processors without backward integration.
For Market Incumbents: Build certification moats through USP monograph dossier completeness and ECHA REACH nanomaterial registration. Hindustan Zinc's captive smelter supply anchors cost positions against LME volatility. EverZinc's nanoparticle R&D intensity defends against titanium dioxide substitution in sunscreen channels. Capacity addition in pharmaceutical-grade wet chemical precipitation secures premium tier access as FDA oversight tightens. For New Entrants and Emerging Players: Southeast Asian tire plant corridors outside Chinese supply dominance offer underpenetrated procurement channels. Thai and Indonesian rubber compounding facilities seek supply diversification beyond Shandong concentration. Pharmaceutical-grade certification in North American dermatological applications presents the most penetrable white-space. Go-to-market through technical service partnerships with regional distributors displaces direct sales investment. For Investors and Strategic Acquirers: Process-technology specialists with wet chemical precipitation capabilities and existing REACH dossier completeness represent the highest-conviction acquisition archetype. Long-term viability hinges on regulatory compliance infrastructure rather than commodity scale. The signal to watch is ECHA nanomaterial classification finalization timing, which would accelerate supplier panel consolidation toward registered producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Zinc Metal Supply | Hindustan Zinc's captive smelter access eliminates LME price exposure for French Process output. |
| Pharmaceutical-Grade Certification Investment | FDA USP monograph compliance opens premium pricing tiers in dermatological applications. |
| Wet Chemical Process Capacity Expansion | EU Green Deal carbon intensity frameworks favor precipitation routes over thermal oxidation. |
| Long-term Supply Agreement with Tire Manufacturers | Ohio and Tennessee corridor consolidation demands volume security through distributor relationships. |
| Nanoparticle Surface Coating R&D Program | South Korean MFDS disclosure thresholds mandate enhanced dispersion chemistry for sunscreen transparency. |
Research Approach
A standing panel of zinc oxide plant managers, tire manufacturer procurement leads, cosmetic formulator R&D directors, and pharmaceutical regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, FDA USP monograph filings, LME zinc price series, and Shandong provincial environmental enforcement disclosures. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Scenario-bracketing around ECHA nanomaterial classification timing, Chinese environmental policy enforcement intensity, and tire manufacturer procurement consolidation pace shaped projection ranges across the analysis window. Segmentation dimensions modeled include product grade tier, manufacturing process route, end-use industry, and regional regulatory cluster. CAGRs derived from installed capacity utilization trajectories and substitution elasticity estimates for titanium dioxide in paint applications.
Practitioners should monitor REACH dossier completion rates and SAMR GB standard revision timelines for early signals of supplier panel consolidation. Forecasts reflect assumptions on sustained automotive production scaling in China and continued ECHA regulatory stringency. Material shifts in zinc metal price volatility regimes or sudden environmental enforcement suspensions in Shandong would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Terbium Oxide Market
Semiconductor Material
Semiconductor Grade Neon Gas Market
Semiconductor Material
Dicing Die Attach Film Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Silicon Nitride Balls Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
North America Semiconductor Materials Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Indium Market
Semiconductor Material
OLED Materials Market
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
High Purity Germanium (Ge) Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Solar Silicon Ingots Market