

Solid-State Relay and Fuse Box Component Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Solid-State Relay and Fuse Box Component Platforms Market Insights
Software-defined overcurrent protection is decoupling hardware sales from recurring service revenue in the fuse box segment. TE Connectivity leverages its sensor-to-connector portfolio to anchor integrated power distribution platforms for EV architectures. Robert Bosch sustains R&D intensity across semiconductor-based switching modules through its automotive electronics division. OMRON Corporation differentiates in industrial automation with photovoltaic coupler-based relay families that compete on switching speed and lifecycle durability.
Solid-state relay and fuse box component platforms comprise semiconductor-based switching devices and modular circuit protection assemblies that replace electromechanical counterparts in power distribution systems, typically rated for 5A to 100A load currents with isolation voltages exceeding 2.5kV, serving to eliminate mechanical wear and enable faster fault response in high-cycle applications. Fuse box modules incorporating MOSFET and IGBT technologies command the dominant share of unit volume as OEM manufacturers standardize on solid-state replacements for traditional thermal fuses in battery management systems. Photovoltaic coupler technology represents the fastest-expanding segment as data center operators adopt galvanically isolated drive circuits for server rack power distribution, while electromechanical relay categories face margin compression from silicon-controlled rectifier alternatives in heating, ventilation, and air conditioning control panels.
The US NHTSA and EPA jointly shape automotive fuse box specifications through crash safety and electromagnetic compatibility mandates that force component redesigns for electric vehicle platforms. ECHA REACH restrictions on lead and cadmium in electrical contacts compel European suppliers to reformulate terminal alloys and solder compositions. Japan's METI energy efficiency standards for industrial equipment accelerate MOSFET relay substitution in machinery builder supply chains. Stakeholders must monitor how IEC 60947-4-3 semiconductor relay standards evolve to address wide-bandgap device qualification before committing next-generation product roadmaps.
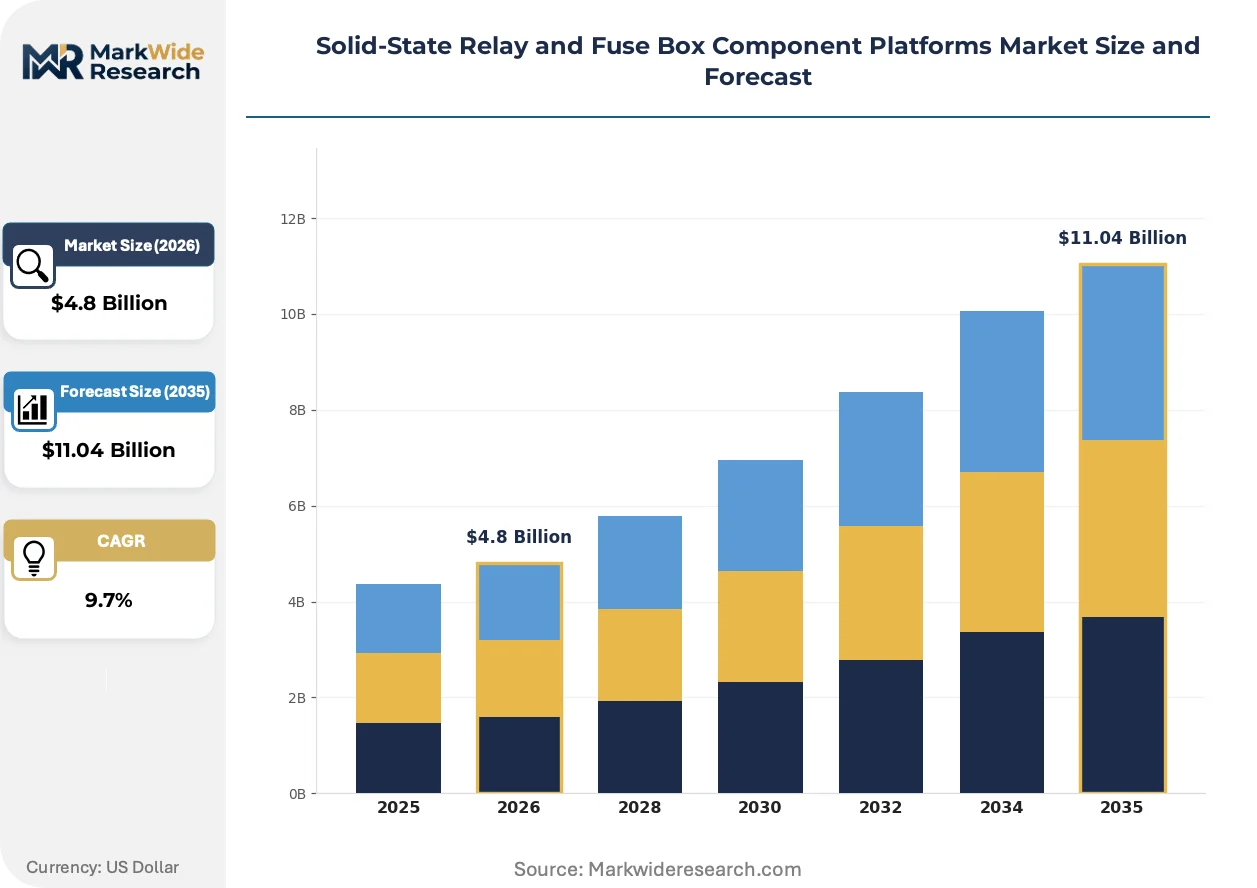
Market Dynamics
Automotive electrification is collapsing traditional power distribution hierarchies, forcing tier-one suppliers to redesign fuse box architectures around solid-state semiconductor switches that eliminate mechanical wear points and enable software-configurable protection curves.
Growth Catalysts
- EV Platform Standardization:Battery management systems in electric vehicles now mandate solid-state relay assemblies to handle high-cycle switching loads without thermal degradation.
- IEC 60664 Coordination:Insulation coordination standards are compelling industrial equipment manufacturers to upgrade from electromechanical to semiconductor-based protection modules.
- Data Center Rack Density:Hyperscale operators in Northern Virginia and Frankfurt are specifying photovoltaic coupler relays for galvanically isolated server power distribution.
Market Restraints
- Wide-Bandgap Material Costs:Silicon carbide substrate prices remain elevated versus silicon alternatives, compressing margins on high-current relay designs.
- German Supplier Concentration:Stuttgart-Munich corridor suppliers control critical semiconductor packaging capacity, creating single-source vulnerability for automotive OEMs.
- Thermal Management Complexity:Solid-state devices generate concentrated heat flux requiring advanced ceramic substrates, adding engineering cost to fuse box redesigns.
Strategic Opportunities
- Indian Industrial Automation:Machinery builders under BIS energy efficiency mandates present underpenetrated demand for MOSFET relay substitution.
- Software-Defined Protection:Overcurrent algorithms are unbundling hardware sales from recurring firmware update revenue streams.
- China Dual Carbon Goals:MIIT efficiency standards are accelerating solid-state adoption in HVAC control panels previously served by electromechanical relays.
Industry Challenges
- AEC-Q200 Qualification Timelines:Automotive semiconductor certification cycles extend 18-24 months, delaying product launches for EV platform bids.
- Legacy Electromechanical Integration:Hybrid architectures requiring signal compatibility between solid-state and mechanical relays introduce interface engineering complexity.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid-State Relay and Fuse Box Component Platforms Market Trends and Innovations
Power distribution architectures are fragmenting into modular, software-configurable subsystems that separate protection logic from physical switching elements. This decoupling is rewriting competitive boundaries between component suppliers and system integrators.
Photovoltaic coupler technology is decentralizing drive circuit isolation in server rack power distribution. Data center operators in Ashburn and Amsterdam are deploying these devices at 10kW-per-rack densities. The shift is compressing demand for traditional optocoupler arrays while enabling faster fault isolation.
Japan's METI energy efficiency standards are forcing machinery builders to abandon electromechanical thermal relays in favor of MOSFET-based alternatives. Industrial equipment OEMs in Osaka and Nagoya are redesigning control panels to meet 2025 compliance deadlines. The transition is accelerating procurement of semiconductor modules with integrated current sensing.
Automotive purchasing departments are consolidating fuse box procurement under platform-level contracts rather than component spot buying. Tier-one suppliers in Germany now negotiate multi-year supply agreements covering relay, fuse, and busbar assemblies. The pattern is most pronounced in Stuttgart, where OEMs are reducing qualified supplier lists from twelve to four per vehicle program.
Solid-State Relay and Fuse Box Component Platforms Market Segmentation
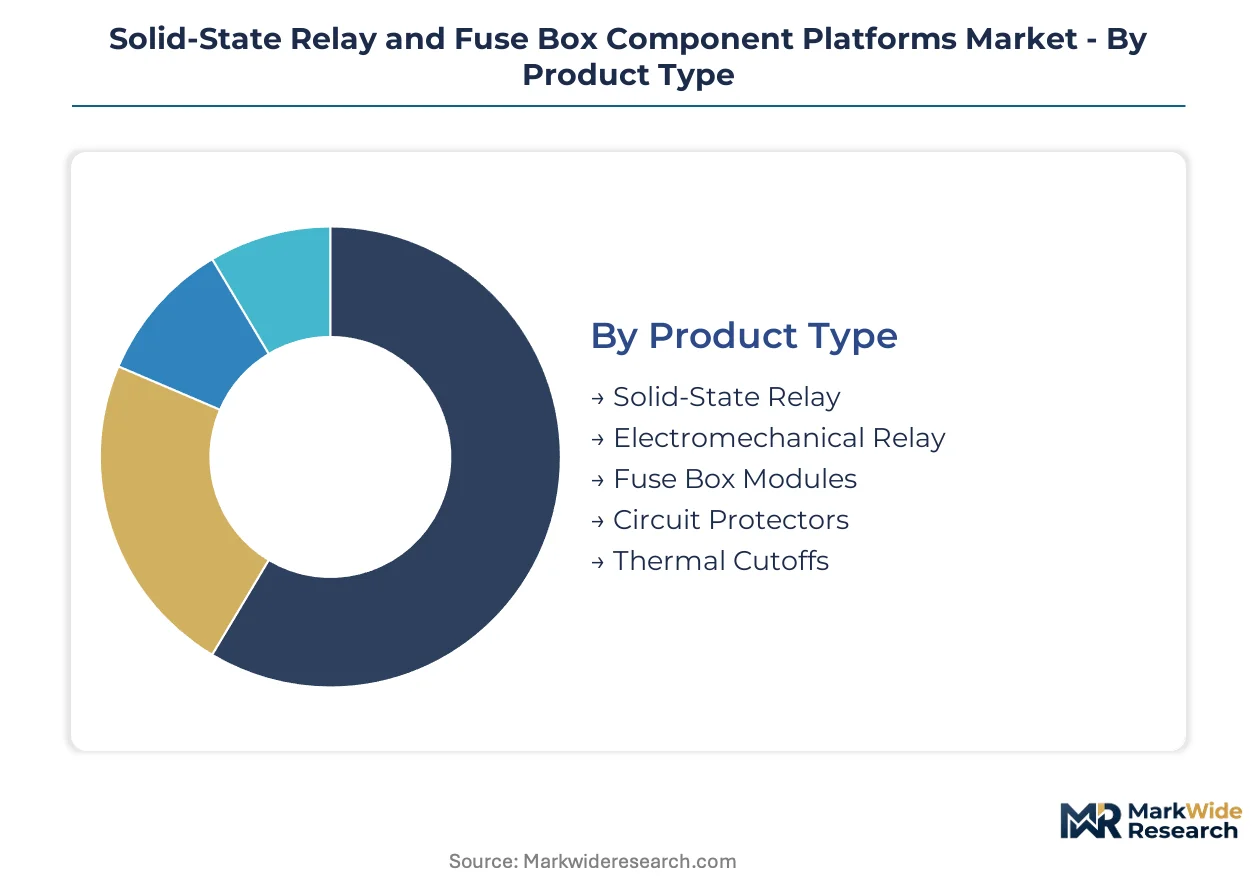
Solid-state relay and fuse box component platforms fragment across four critical dimensions. Each category reflects distinct procurement patterns, certification requirements, and supply chain configurations that shape vendor positioning.
Product Type:
Supply concentration for finished assemblies tilts heavily toward semiconductor-based switching modules as tier-one suppliers consolidate procurement under platform-level contracts.
- Solid-State Relay:Semiconductor-based switching devices rated for 5A to 100A loads with isolation voltages exceeding 2.5kV. Battery management systems in electric vehicles now mandate these assemblies to handle high-cycle switching without thermal degradation.
- Fuse Box Modules:Modular circuit protection assemblies incorporating MOSFET and IGBT technologies. OEM manufacturers in Germany's Stuttgart-Munich corridor are standardizing on these solid-state replacements for traditional thermal fuses.
- Electromechanical Relay:Traditional switching devices facing margin compression from silicon alternatives. HVAC control panels are accelerating substitution as China MIIT efficiency standards tighten.
- Circuit Protectors:Overcurrent protection devices with software-configurable trip curves. Data center operators in Northern Virginia specify these for rack-level fault isolation.
- Thermal Cutoffs:Temperature-sensitive disconnect devices for consumer appliance safety. Japan's METI energy efficiency standards are forcing machinery builders toward semiconductor alternatives.
Fuse box modules absorb the bulk of installed capacity; solid-state relay categories are expanding most quickly.
Technology:
Cost tier stratification separates silicon-based mainstream options from wide-bandgap premium alternatives where substrate pricing compresses margins.
- MOSFET:Metal-oxide-semiconductor field-effect transistors dominate mid-current switching applications. Industrial automation OEMs in Osaka and Nagoya are redesigning control panels to meet Japan METI compliance deadlines.
- Photovoltaic Couplers:Galvanically isolated drive circuits using LED-photodiode pairs. Hyperscale operators in Ashburn and Amsterdam deploy these at 10kW-per-rack densities for server power distribution.
- Insulated-Gate Bipolar Transistor:High-current switching devices combining MOSFET input characteristics with bipolar output capability. EV powertrain applications favor these for traction inverter protection.
- Silicon-Controlled Rectifier:Thyristor-based phase control devices for heating and motor drive applications. HVAC control panels are accelerating procurement as electromechanical alternatives face displacement.
- Bipolar Junction Transistor:Legacy current amplification devices retaining niche presence in cost-sensitive consumer appliances.
MOSFET technology captures the dominant share of unit volume; photovoltaic couplers are gaining share fastest.
Application:
Volume concentration clusters around electrification-driven end-uses where fault response speed and cycle durability override upfront cost considerations.
- Industrial Automation:Factory equipment and process control systems requiring high-cycle reliability. Machinery builders under India's BIS energy efficiency mandates present underpenetrated demand for MOSFET relay substitution.
- Renewable Energy Systems:Solar inverters and wind turbine power conversion equipment. IEC 60664 insulation coordination standards are compelling manufacturers to upgrade from electromechanical to semiconductor-based protection modules.
- Data Center Operators:Server rack and hyperscale facility power distribution. Frankfurt and Northern Virginia clusters specify photovoltaic coupler relays for galvanic isolation at density levels.
- Consumer Appliances:White goods and small electronics with cost-optimized protection requirements. Thermal cutoff integration persists where semiconductor substitution economics remain unfavorable.
- Marine Vessels:Shipboard power distribution with salt corrosion and vibration resistance requirements. Classification society rules shape certification timelines for solid-state alternatives.
- Telecommunications Equipment:Base station and network infrastructure power protection. FCC electromagnetic compatibility mandates influence component selection for US deployments.
Industrial automation absorbs the bulk of installed capacity; renewable energy systems are climbing the fastest.
End User:
Customer type determines contract structure, with OEM manufacturers consolidating procurement under multi-year platform agreements while electrical contractors remain fragmented spot buyers.
- OEM Manufacturers:Original equipment producers integrating protection components into finished products. Automotive purchasing departments in Germany have reduced qualified supplier lists from twelve to four per vehicle program.
- Data Center Operators:Hyperscale and colocation facility managers specifying rack-level power distribution. Ashburn and Amsterdam clusters drive photovoltaic coupler specification at 10kW densities.
- Machinery Builders:Industrial equipment OEMs assembling control panels and automation systems. Osaka and Nagoya manufacturers are redesigning to meet Japan METI 2025 compliance deadlines.
- Utility Providers:Grid operators and renewable project developers procuring substation and inverter protection. FERC interconnection standards shape US procurement specifications.
- Electrical Contractors:Installation and retrofit service providers with project-based purchasing patterns. Fragmented demand concentrates in commercial and residential construction cycles.
OEM manufacturers absorb the bulk of installed capacity; data center operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German suppliers dominate semiconductor packaging capacity for automotive-grade solid-state relays, while Chinese industrial automation demand outpaces domestic production. Japanese machinery builders drive MOSFET substitution under efficiency mandates. Data center construction in Northern Virginia and Frankfurt pulls photovoltaic coupler procurement toward these clusters.
Germany
Automotive OEMs in Stuttgart and Munich consolidate fuse box procurement under platform-level contracts, reducing qualified supplier lists from twelve to four per vehicle program. KBA vehicle safety regulations and AEC-Q200 automotive qualification protocols tighten certification timelines for semiconductor-based switching modules. The Stuttgart-Munich corridor controls critical packaging capacity for high-current relay designs serving European EV platforms.
United States
Hyperscale data center operators in Northern Virginia specify photovoltaic coupler relays at 10kW-per-rack densities for galvanic isolation. NHTSA and EPA crash safety and electromagnetic compatibility mandates force component redesigns for electric vehicle fuse box architectures. Ashburn cluster procurement patterns now influence relay specification standards for server rack power distribution across North American facilities.
China
MIIT energy efficiency standards accelerate solid-state adoption in HVAC control panels previously served by electromechanical relays. Dual carbon goals compel industrial equipment manufacturers to substitute MOSFET-based protection for thermal cutoffs. Yangtze River Delta machinery builders represent underpenetrated demand for semiconductor relay modules as BIS-equivalent efficiency mandates expand.
Japan
Industrial equipment OEMs in Osaka and Nagoya redesign control panels to meet METI 2025 energy efficiency compliance deadlines. METI standards force abandonment of electromechanical thermal relays in favor of MOSFET alternatives with integrated current sensing. Kanto and Kansai manufacturing belts concentrate procurement of semiconductor modules for factory automation retrofits.
Solid-State Relay and Fuse Box Component Platforms Market Competitive Landscape
Top-tier vendors anchor automotive platform contracts, while mid-tier specialists compete on switching speed and thermal performance. Semiconductor-based switching modules concentrate procurement power among tier-one suppliers with AEC-Q200 qualification capabilities. Three archetypes dominate: diversified automotive electronics conglomerates, industrial automation specialists with photovoltaic coupler portfolios, and connector-to-sensor integrators bundling power distribution platforms. Capacity expansion in ceramic substrate packaging and strategic partnerships for wide-bandgap device sourcing represent the dominant competitive vectors.
Within the automotive electronics tier, Yazaki Corporation, Robert Bosch, and Continental AG exemplify diversified conglomerates with platform-level contract access. TE Connectivity occupies a position among connector-to-sensor integrators leveraging portfolio breadth for bundled power distribution offerings. OMRON Corporation represents the industrial automation specialist archetype with photovoltaic coupler-based relay families. Japanese-origin corporations including Sumitomo Electric Industries and Furukawa Electric sit within the precision component fabricator tier serving both automotive and industrial demand clusters. ABB and HELLA exemplify European-based competitors navigating AEC-Q200 qualification timelines for EV platform bids.
| Leading Market Players |
|---|
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Furukawa Electric |
| Robert Bosch |
| TE Connectivity |
| Continental AG |
| HELLA |
| OMRON Corporation |
| ABB |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide substrate pricing cascades through automotive relay supply chains into three distinct tiers: AEC-Q200 qualified modules for EV platforms, industrial-grade photovoltaic couplers for data centers, and cost-optimized MOSFET assemblies for HVAC retrofits. German packaging capacity constraints prop pricing power toward Stuttgart-Munich corridor suppliers while compressing margins for second-source qualified alternatives.
Pricing Analysis
Margin tightening in wide-bandgap tiers reflects silicon carbide wafer supply scarcity against EV platform procurement surges. Three-tier pricing structure across automotive-qualified, industrial-performance, and economy-grade levels segments buyers by certification burden and volume commitment. Cost-down pressure on standard silicon MOSFET assemblies accelerates because Chinese machinery builders exploit spot-market purchasing power. Data center operators exhibit least price sensitivity, prioritizing galvanic isolation performance over per-unit cost in 10kW rack specifications.
Supply Chain Analysis
AEC-Q200 qualification timelines gate semiconductor packaging capacity, concentrating automotive-grade relay production in Germany, Japan, and South Korea where tier-one suppliers maintain captive test facilities. Ceramic substrate supply draws from Japanese and Taiwanese material specialists, while copper terminal alloys hinge on ECHA REACH compliant European smelters. Single-source vulnerability persists in wide-bandgap epitaxial wafer supply. Distribution runs through platform-level contracts directly to OEM procurement departments, bypassing traditional component distributors for EV and data center segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ceramic substrate packaging capacity scarcity props pricing power for qualified suppliers while extending lead times for new entrants seeking automotive platform access. This supply-constrained structure favors incumbents with existing AEC-Q200 certification pipelines.
For Market Incumbents: Deepen backward integration into ceramic substrate manufacturing to defend margin position against silicon carbide cost volatility. Lock multi-year platform contracts with Stuttgart and Munich automotive OEMs before qualification timelines extend further. Prioritize capacity expansion in wide-bandgap packaging to capture EV power distribution procurement waves. For New Entrants and Emerging Players: Photovoltaic coupler technology for data center rack density specifications offers the most penetrable entry vector, as Ashburn and Amsterdam operators prioritize switching speed over incumbent brand recognition. Target Indian machinery builders under BIS efficiency mandates with MOSFET relay substitution kits. Pursue direct technical sales to bypass entrenched automotive supplier lists. For Investors and Strategic Acquirers: Distressed-cycle entries favor industrial automation specialists with photovoltaic coupler portfolios in Japan and Taiwan, where METI compliance deadlines force control panel redesigns. Long-term viability centers on qualification asset duration and platform contract renewal rates. Monitor IEC 60947-4-3 wide-bandgap device standard evolution as inflection signal for next-generation product roadmap commitments.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q200 Qualification Investment | 18-24 month certification cycles gate automotive platform access for EV fuse box architectures. |
| Photovoltaic Coupler R&D Expansion | Data center operators in Northern Virginia specify these devices for 10kW-per-rack galvanic isolation. |
| Ceramic Substrate Backward Integration | Captive packaging capacity insulates margin from silicon carbide substrate price volatility. |
| Software-Defined Protection Development | Overcurrent algorithm licensing unbundles hardware sales from recurring firmware revenue streams. |
| Indian Market Direct Sales Buildout | BIS energy efficiency mandates present underpenetrated demand for MOSFET relay substitution. |
Research Methodology
Document review covered IEC 60664 insulation coordination standards, AEC-Q200 automotive qualification protocols, and ECHA REACH substance restrictions, complemented by interviews with tier-one supplier procurement managers, data center facility engineers, industrial automation OEM technical directors, and semiconductor packaging specialists. Secondary validation drew from customs trade databases, SEC filings of listed component manufacturers, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down market aggregation.
Unit volume and value projections across the analysis window employed a demand-side model incorporating EV platform adoption curves, data center construction permits in Northern Virginia and Frankfurt, and industrial machinery retrofit cycles under Japan METI and India BIS efficiency mandates. Segmentation dimensions included product type, switching technology, application end-use, and customer archetype. CAGRs derived from regression against historical procurement patterns and regulatory compliance deadline clustering.
Several conditions sit outside the modeled scope, including potential IEC 60947-4-3 standard revisions for wide-bandgap devices, tariff disruptions affecting ceramic substrate trade flows, and unanticipated electromechanical relay substitution economics in cost-sensitive consumer appliance segments. Forecasts reflect documented assumptions regarding qualification timeline stability and OEM supplier list consolidation trajectories. A model refresh is warranted upon material change in silicon carbide substrate pricing or AEC-Q200 certification cycle duration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.