
 Global Battery Thermal Management System Market | 2026-2036
Global Battery Thermal Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Battery Thermal Management System Market Analysis
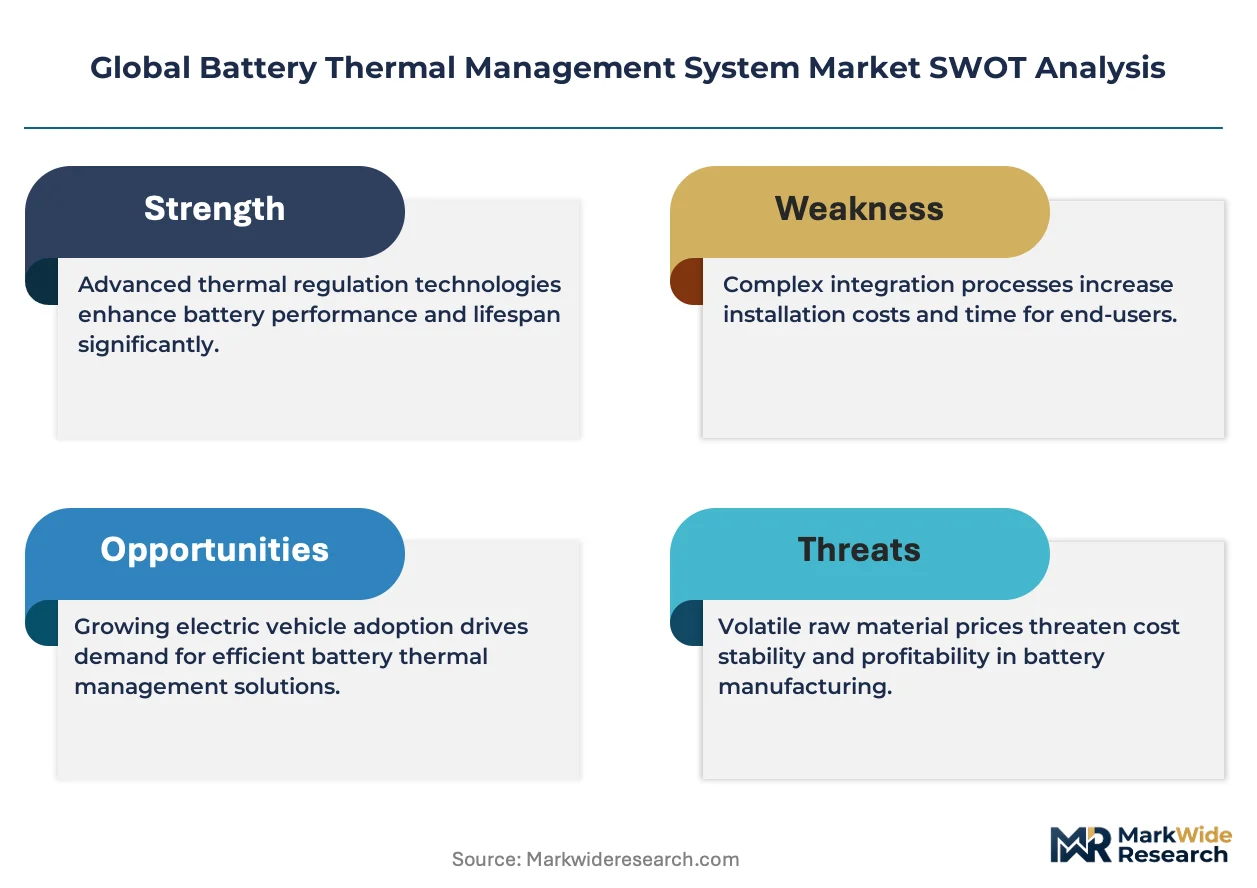
A capital-intensity divergence between integrated thermal module suppliers and component vendors is redrawing competitive boundaries in battery thermal management. Robert Bosch leverages its powertrain electronics heritage to bundle thermal control with battery management software. Continental AG anchors its position through in-house production of coolant valves and sensors. Denso competes via manufacturing scale inherited from Toyota Group supply relationships.
Battery thermal management systems regulate cell and pack temperatures through active circulation, passive dissipation, or hybrid architectures combining both approaches, typically maintaining operating windows between 15°C and 35°C to prevent lithium-ion degradation and thermal runaway. Liquid cooling dominates electric vehicle applications due to higher heat flux capacity, while air cooling retains cost advantages in consumer electronics and light-duty energy storage. Phase change materials represent the fastest-growing technology segment as automakers seek passive safety buffers for fast-charging architectures.
EPA tailpipe regulations, NHTSA battery safety standards, and China's MIIT new-energy vehicle technical guidelines collectively mandate thermal monitoring and fail-safe cooling protocols that shape product design requirements. The EU Green Deal and REACH chemical restrictions additionally constrain coolant chemistry choices for European-bound systems. Stakeholders must monitor how solid-state cell chemistry transitions alter heat generation profiles and cooling duty cycles across vehicle platforms.
Market Dynamics
Electric vehicle platforms are engineering liquid-cooled battery packs as default architecture, forcing thermal management suppliers to reconfigure product portfolios around heat flux densities that air-cooled systems cannot safely handle. This technical mandate cascades through material selection, manufacturing footprint, and software integration requirements.
Growth Catalysts
- NHTSA thermal runaway protocols:United States safety mandates now require multi-layer thermal barriers and active cooling redundancy, compelling automakers to upgrade from passive to liquid-cooled architectures across new vehicle programs.
- Fast-charging infrastructure rollout:800V electrical architectures in premium electric vehicles generate heat loads exceeding 4C charge rates, creating procurement pull for advanced coolant circulation modules and predictive thermal algorithms.
- Cell production concentration:Manufacturing clusters in China, Germany, and South Korea co-locate thermal engineering talent with gigafactory buildouts, shortening development cycles for integrated pack-level solutions.
Market Restraints
- Coolant chemistry constraints:REACH restrictions in Europe and state-level chemical disclosure rules in California limit formulating options for dielectric fluids, raising R&D costs for compliant thermal transfer media.
- Valve and sensor supply concentration:Precision coolant control components rely on specialized machining capacity concentrated in Japanese and German automotive tier-one networks, creating bottleneck risk during demand surges.
- Air cooling substitution in light-duty storage:Stationary energy systems and consumer electronics retain cost-optimized air-cooled designs, capping addressable market expansion in segments below 50 kWh pack capacities.
Strategic Opportunities
- India electric two-wheeler thermal systems:The country's PLI scheme for advanced chemistry cell manufacturing is attracting pack assembly investments where simplified liquid cooling modules face limited incumbent competition.
- Solid-state battery pre-conditioning:Next-generation cell chemistries require narrower temperature bands during formation cycling, opening white space for precision thermal conditioning equipment in pilot production lines.
- Second-life battery repurposing:Degraded automotive packs entering stationary storage applications need refurbished thermal management, creating aftermarket service revenue streams for diagnostic and cooling system retrofit specialists.
Industry Challenges
- Systems integration engineering shortage:Cross-functional talent combining thermal fluid dynamics with battery management software is concentrated among legacy automaker spinoffs and select engineering consultancies, constraining supplier scaling.
- Multi-standard certification timelines:Simultaneous homologation against UN ECE R100, UL 2580, and GB/T requirements extends product validation cycles, delaying revenue recognition for platform-specific thermal module designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Battery Thermal Management System Market |
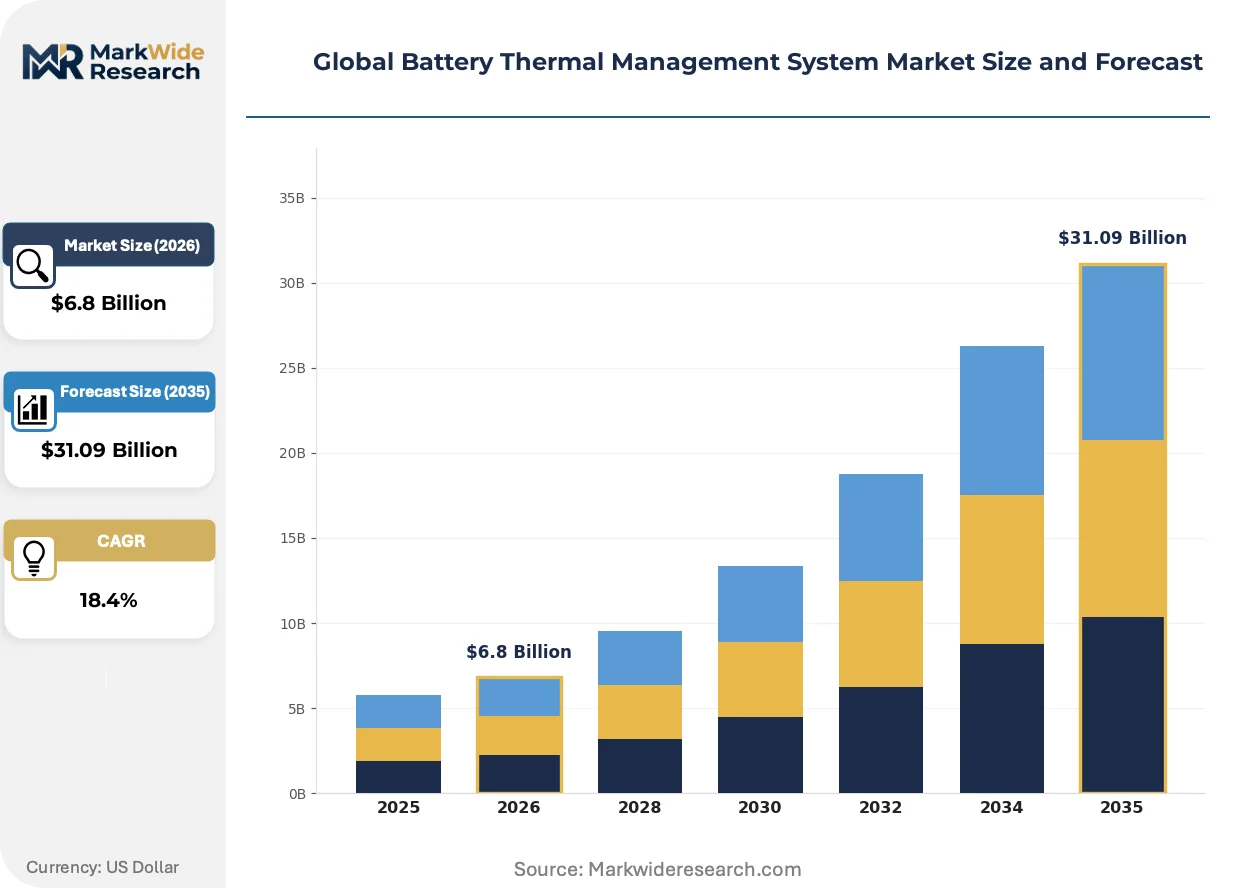
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.09 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Systems, Passive Systems, Hybrid Systems, Thermal Interface Materials Technology: Liquid Cooling, Air Cooling, Phase Change Materials, Heat Pipes Application: Electric Vehicles, Energy Storage Systems, Consumer Electronics, Industrial Applications End User: Automobile Manufacturers, Electronics Manufacturers, Renewable Energy Companies, Aerospace Firms |
| Companies Covered | Robert Bosch, Gentherm, Continental AG, Denso, BorgWarner Inc., Webasto Group, Valeo, Mahle GmbH, Hanon Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Battery Thermal Management System Market Emerging Trajectories
Phase change materials are migrating from research prototypes to production vehicle programs, creating passive thermal buffers that complement active liquid cooling without adding electrical load. This material transition is redrawing supplier capabilities around chemical formulation rather than mechanical engineering alone.
Immersion cooling using dielectric fluids is decomposing the traditional separation between cell housing and thermal management hardware. Battery engineers at several European luxury electric vehicle programs are adopting direct-contact cooling architectures that eliminate cold plates and interface materials. This convergence is compressing bill-of-material counts while raising purity requirements for coolant chemistry.
EPA tailpipe standards tightening through 2027 model years are accelerating powertrain electrification timelines across light-truck segments previously dominated by internal combustion. Commercial vehicle divisions at major Detroit manufacturers are advancing thermal system specifications for electric pickup and delivery van platforms. The medium-duty segment is responding with modular cooling architectures that scale across multiple vehicle classes.
Fleet operators are consolidating thermal system procurement through vehicle-as-a-service contracts that bundle battery conditioning with charging infrastructure management. Logistics providers running electric last-mile delivery in California and the Netherlands are selecting platform providers based on guaranteed battery thermal performance metrics rather than component specifications. This performance-based contracting is most visible in temperature-sensitive cargo applications where cell degradation directly impacts route planning algorithms.
Global Battery Thermal Management System Market Segmentation
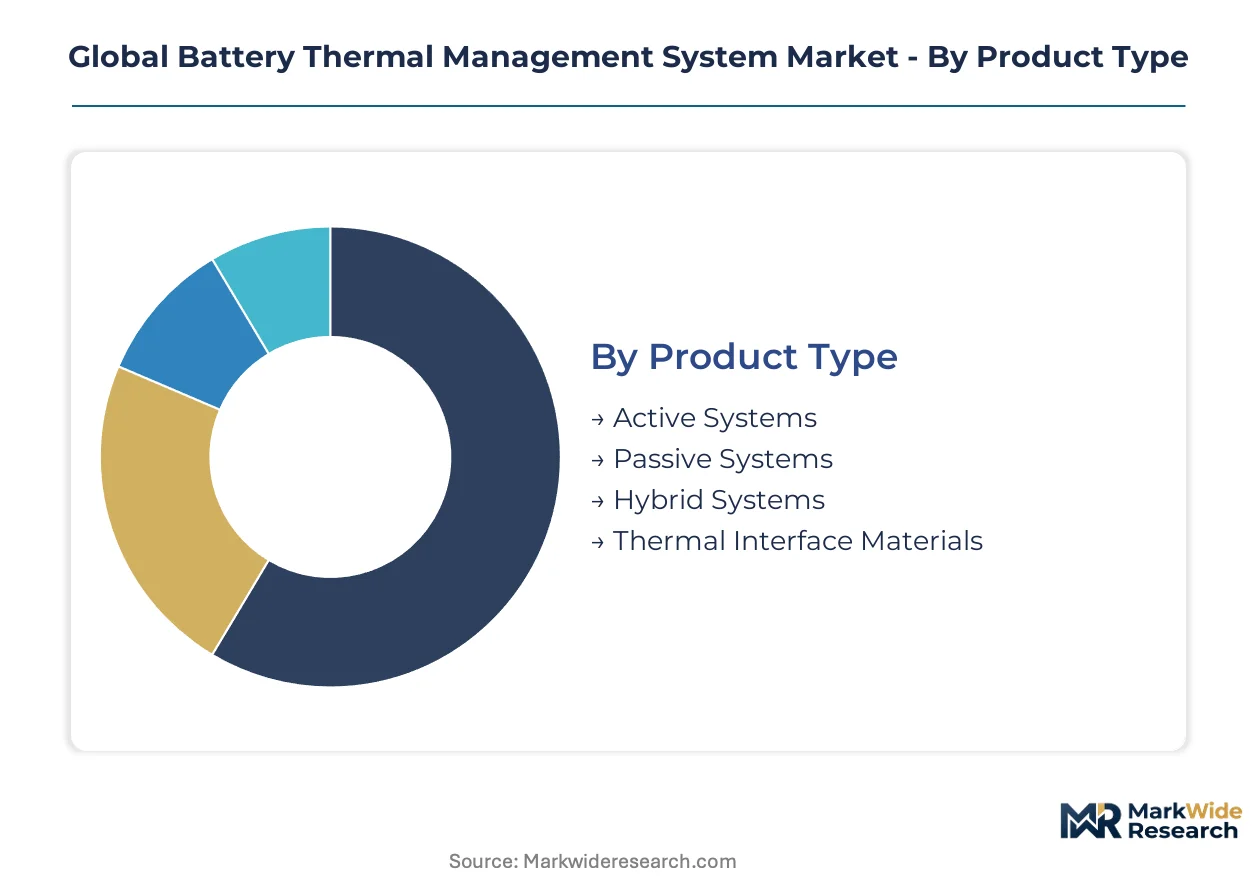
Segmentation reveals how thermal management architectures diverge across power density requirements and regulatory exposure. Procurement patterns cluster around cooling capacity thresholds rather than simple cost optimization, with liquid-cooled platforms commanding premium positioning in automotive programs.
Product Type:
Margin pools concentrate in integrated active systems where software-controlled circulation commands recurring engineering service revenue.
- Active Systems:Pump-driven liquid circulation with real-time temperature modulation dominates electric vehicle platforms above 50 kWh capacity. Automotive OEMs in Germany and South Korea specify these for NHTSA thermal runaway compliance and 800V fast-charging duty cycles.
- Passive Systems:Conductive heat sinks and natural convection architectures serve cost-constrained consumer electronics and light-duty storage below 20 kWh. Air-cooled designs retain share in India electric two-wheeler segments where battery pack costs dominate purchasing decisions.
- Hybrid Systems:Combining active liquid loops with passive thermal mass buffers for redundancy-critical applications.
- Thermal Interface Materials:Gap pads and phase-change compounds bridging cell-to-cold-plate conductivity.
The dominant share belongs to Active Systems, while Hybrid Systems is closing the gap fastest as automakers add passive safety buffers to liquid-cooled architectures.
Technology:
Technology selection tracks directly with heat flux density requirements across vehicle classes and charging speeds.
- Liquid Cooling:Ethylene-glycol and dielectric fluid circulation through cold plates or immersion baths handles continuous loads above 200 W/kg. European luxury electric vehicle programs are eliminating interface materials entirely through direct-contact immersion designs.
- Phase Change Materials:Paraffin and salt-hydrate formulations absorb transient heat spikes during 4C fast-charging events without electrical load. PCM integration is accelerating in premium battery packs where passive thermal buffering reduces active cooling energy consumption.
- Air Cooling:Forced convection through finned heat sinks in low-density applications.
- Heat Pipes:Two-phase vapor chamber transfer for compact electronics thermal management.
Liquid Cooling retains the largest installed base, though Phase Change Materials is expanding most quickly as fast-charging infrastructure spreads.
Application:
Application segmentation reflects divergent duty cycles and safety certification requirements across mobility and stationary markets.
- Electric Vehicles:Passenger cars, commercial vans, and medium-duty trucks with continuous dynamic thermal loads. EPA tailpipe tightening through 2027 model years is electrifying light-truck segments previously served by internal combustion, expanding procurement for modular cooling architectures.
- Energy Storage Systems:Grid-scale and commercial stationary batteries with slower thermal transients but extended calendar life requirements. California fleet operators are bundling thermal performance guarantees into vehicle-as-a-service contracts for last-mile delivery electrification.
- Consumer Electronics:Smartphones, laptops, and power tools with space-constrained passive solutions.
- Industrial Applications:Forklifts, mining equipment, and material handling systems with harsh environment exposure.
Electric Vehicles captures the majority of current revenue, while Energy Storage Systems is gaining share fastest as grid-scale deployments accelerate.
End User:
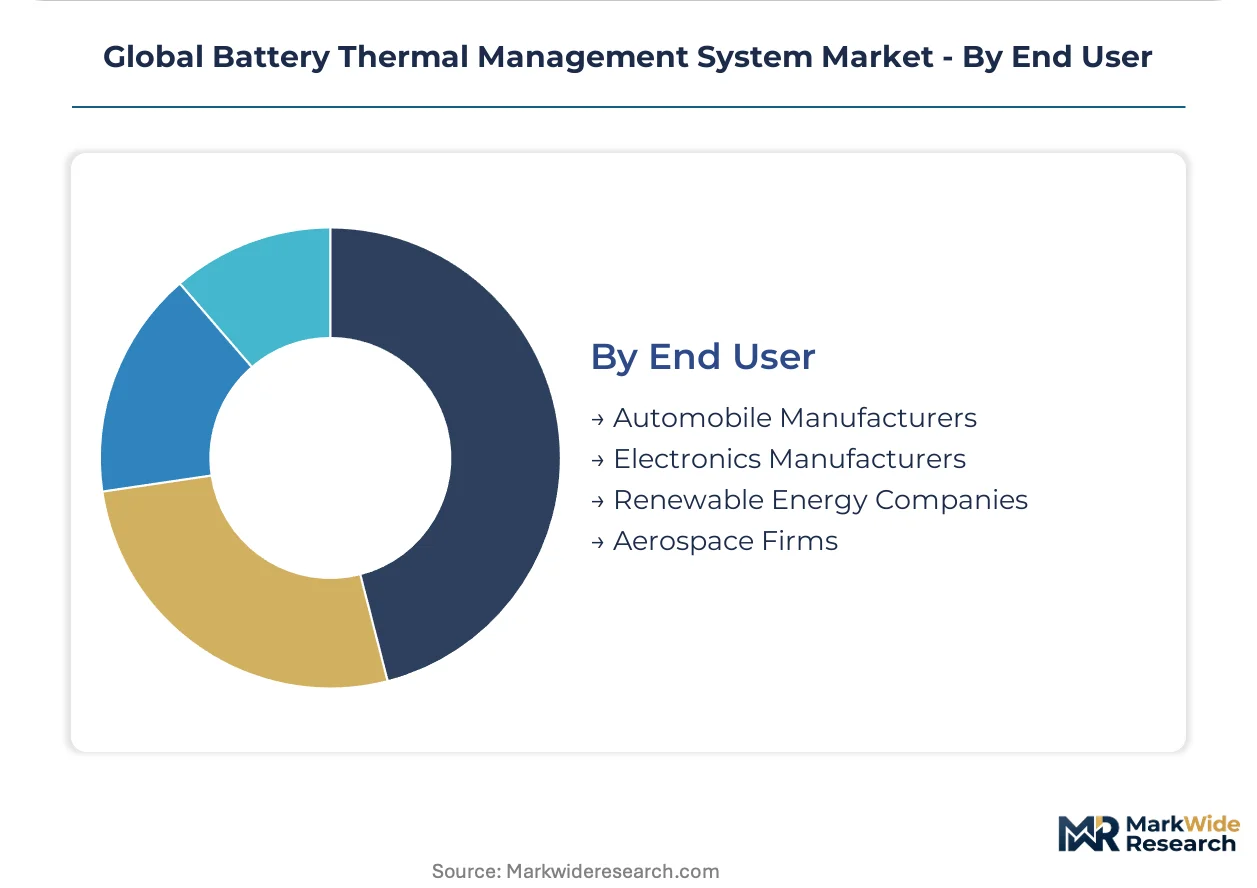
End user structure shows how procurement authority concentrates with platform integrators versus component suppliers.
- Automobile Manufacturers:Volkswagen, Toyota, and BYD-scale OEMs specifying pack-level thermal modules through tier-one supply contracts. These buyers integrate thermal management with battery management software, favoring suppliers with powertrain electronics heritage like Robert Bosch and Denso.
- Renewable Energy Companies:NextEra, Ørsted, and state-owned utilities procuring containerized storage with guaranteed thermal performance. Performance-based contracting is standard in temperature-sensitive cargo applications where cell degradation impacts route planning algorithms.
- Electronics Manufacturers:Consumer device brands specifying compact passive solutions.
- Aerospace Firms:Satellite and electric aircraft programs with extreme reliability requirements.
Automobile Manufacturers hold the dominant procurement volume, while Renewable Energy Companies is climbing the fastest as utility-scale storage buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German engineering clusters while cost-competitive manufacturing scales through Chinese coastal provinces. This asymmetry redistributes margin capture across the battery thermal management value chain.
United States
Electric pickup and delivery van electrification accelerates thermal system procurement from Detroit manufacturers. NHTSA thermal runaway protocols mandate multi-layer barriers and active cooling redundancy across new vehicle programs. California fleet operators bundle thermal performance guarantees into vehicle-as-a-service contracts for last-mile logistics.
Germany
Premium electric vehicle programs specify direct-contact immersion cooling architectures eliminating cold plates entirely. EU Green Deal and REACH chemical restrictions constrain dielectric fluid formulation options for European-bound systems. Stuttgart and Munich engineering clusters concentrate thermal fluid dynamics talent alongside automotive OEM headquarters.
China
Cell production concentration in Fujian and Jiangsu provinces co-locates thermal engineering talent with gigafactory buildouts. MIIT new-energy vehicle technical guidelines mandate thermal monitoring and fail-safe cooling protocols shaping product design. Shenzhen and Shanghai suppliers shorten development cycles for integrated pack-level solutions through proximity to BYD-scale OEMs.
South Korea
Battery cell manufacturing in Gyeonggi-do and Chungcheong provinces anchors thermal module development for 800V fast-charging architectures. GB/T certification requirements extend validation timelines for platform-specific designs entering Chinese-bound vehicle programs. Seoul Capital Area engineering consultancies concentrate cross-functional talent combining thermal simulation with battery management software.
India
Electric two-wheeler thermal systems face limited incumbent competition as PLI scheme investments attract pack assembly capacity. Central Electricity Authority guidelines shape grid-connected storage thermal specifications for utility-scale deployments. Tamil Nadu and Gujarat manufacturing corridors host simplified liquid cooling module production for price-sensitive mobility applications.
Global Battery Thermal Management System Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the battery thermal management system market. Consolidation around automotive tier-one networks creates tiered supply structures with premium positioning for integrated module suppliers and commodity pricing for component vendors. Two strategic archetypes dominate: powertrain electronics heritage firms bundling thermal control with battery management software, and manufacturing-scale specialists leveraging captive automotive group relationships. Competitive moves concentrate on backward integration into coolant valve and sensor production, plus geographic co-location with cell manufacturing clusters.
Within the integrated systems tier, Robert Bosch and Denso occupy positions exemplifying powertrain electronics heritage applied to thermal-battery management convergence. Continental AG anchors the component-vertically-integrated archetype through in-house production of coolant valves and sensors. Among Korean thermal specialists, Hanon Systems represents manufacturing-scale positioning inherited from automotive group supply relationships. These three company structures illustrate how competitive positioning diverges between software-integrated and hardware-captive strategies.
| Leading Market Players |
|---|
| Robert Bosch |
| Gentherm |
| Continental AG |
| Denso |
| BorgWarner Inc. |
| Webasto Group |
| Valeo |
| Mahle GmbH |
| Hanon Systems |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between automotive OEMs and thermal module suppliers lock in dielectric fluid volumes and cold plate capacity, binding price visibility to gigafactory construction timelines in China, Germany, and South Korea. These contracts transfer commodity volatility risk upstream while securing NHTSA-compliant thermal runaway protection for vehicle platforms.
Pricing Analysis
Configured-to-order pricing for direct-contact immersion cooling commands a 40-60% premium over standard cold plate architectures, driven by purity-grade dielectric fluid requirements and precision machining tolerances. Pricing stratifies across premium, standard, and economy tiers based on UL 2580 certification level and software integration depth. Cost compression in economy-tier air-cooled modules is intensifying because Indian electric two-wheeler manufacturers prioritize pack cost over thermal performance. Fleet operators running temperature-sensitive cargo exhibit the lowest price sensitivity, while consumer electronics brands remain most responsive to unit cost.
Supply Chain Analysis
Port congestion on the Shanghai-Rotterdam trade lane extends inbound logistics cycles for precision-machined coolant valves and sensor housings sourced from Japanese and German tier-one networks. Manufacturing concentrates in China, South Korea, and Germany, with raw material dependencies spanning high-purity ethylene glycol, aluminum alloys for cold plates, and specialized paraffin formulations for phase change materials. Single-source vulnerability concentrates in precision machining capacity for coolant control components. Distribution runs through automotive tier-one supplier networks with co-located engineering support at cell manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Battery Thermal Management System Market is entering a cyclical recovery phase as automakers restock thermal module inventory following two years of destocking through the EV demand correction. Capital expenditure on liquid-cooled pack architectures accelerates with NHTSA thermal runaway compliance deadlines tightening across 2027 model year programs.
For Market Incumbents: Fortify backward integration into coolant valve and sensor production to defend margin position against emerging Asian component specialists. Secure captive supply of high-purity dielectric fluids through long-term chemical offtake agreements, as REACH restrictions in Europe and California disclosure rules constrain formulating options and amplify input cost volatility. For New Entrants and Emerging Players: Aftermarket thermal system refurbishment for second-life battery repurposing represents an underserved service layer where diagnostic tooling and cooling retrofit expertise face limited incumbent competition. Target India's electric two-wheeler segment through simplified liquid cooling modules optimized for PLI scheme pack assembly investments, leveraging price-sensitive procurement patterns and absence of established thermal suppliers. For Investors and Strategic Acquirers: Capital is best deployed toward precision thermal conditioning equipment specialists serving solid-state battery pilot production lines, where narrower temperature band requirements during formation cycling create durable differentiation. Monitor 800V fast-charging infrastructure rollout velocity as the inflection signal for advanced coolant circulation module demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks in thermal module capacity alongside cell procurement, securing NHTSA compliance pathways for OEM platform launches. |
| Backward Integration into Coolant Chemistry | Captures margin pools in dielectric fluid formulation while mitigating REACH and California disclosure regulatory exposure. |
| Software-Defined Thermal Control Investment | Integrates predictive thermal algorithms with battery management systems, commanding recurring engineering service revenue. |
| Geographic Manufacturing Footprint Expansion | Co-locates production with gigafactory buildouts in China, Germany, and South Korea to shorten development cycles. |
| Charging Infrastructure Partnership | Bundles thermal performance guarantees with fleet vehicle-as-a-service contracts for temperature-sensitive logistics applications. |
Methodological Framework
The analysis maps active liquid cooling, passive air cooling, phase change materials, and hybrid thermal architectures, each validated through thermal system design engineers, OEM platform procurement managers, and tier-one supplier account directors. Primary interviews with battery pack integration specialists and aftermarket service technicians combined with secondary validation against EPA tailpipe regulation filings, NHTSA safety standard databases, UN ECE R100 homologation records, and MIIT new-energy vehicle technical guidelines. Bottom-up thermal module shipment data triangulates against top-down electric vehicle production forecasts across the analysis window.
Consistency checks against IHS Markit vehicle registration databases and EIA grid-scale storage deployment records validate volume and value outputs. The forecast framework models technology type, application segment, vehicle class, cooling capacity tier, and regional production cluster dimensions throughout the projection horizon. CAGRs derive from fitted growth curves incorporating cell chemistry transition timelines, fast-charging infrastructure buildout velocity, and regulatory compliance phase-in schedules.
Underlying assumptions cover NHTSA thermal runaway protocol adherence, REACH chemical restriction continuity, and 800V electrical architecture penetration rates, with deviation risk concentrated in solid-state battery commercialization timelines and air cooling substitution in light-duty storage below 50 kWh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
HVDC Converters Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Global Flexible Batteries Market
Power Systems
Integrated UPS Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
USB Power Adapters Market
Power Systems
US Variable Frequency Drive Market
Power Systems
AC DC Power Adapter Market
Power Systems
Power Electronics Market
Power Systems
Power Electronics for Electric Vehicle Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Synchrophasors Market
Power Systems
High Current Power Supply for Electrophoresis Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
Laptop Battery Market