
 Global Power Semiconductor Switches Market | 2026-2036
Global Power Semiconductor Switches Market Size, Share, and Industry Trends Forecast 2026-2036
Global Power Semiconductor Switches Market Intelligence
Distribution through specialized electronics component suppliers is tilting toward platforms offering integrated design support and rapid prototyping services. Infineon Technologies leverages its manufacturing scale to secure large-volume contracts in the automotive sector across Germany and China. STMicroelectronics differentiates with a broad portfolio of silicon carbide and gallium nitride devices for industrial and consumer electronics. Texas Instruments competes on the strength of its integrated power management ICs and extensive developer ecosystem.
Power semiconductor switches are electronic components designed to control the flow of high levels of electrical current and voltage. Operating at high frequencies with minimal energy loss, they are fundamental to modern power conversion, motor control, and energy management systems. Silicon Carbide (SiC) and Gallium Nitride (GaN) technologies are displacing traditional Silicon in high-performance applications due to superior thermal and efficiency characteristics. The electric transportation and renewable energy sectors represent the fastest-growing application areas, demanding higher power density and reliability from these components.
Regulatory frameworks such as the EU's RoHS directive and China's GB standards for electronics mandate specific material compositions and energy efficiency levels. In the United States, EPA vehicle efficiency targets directly influence the adoption of advanced power switches in electric and hybrid powertrains. Stakeholder success will depend on navigating the complex supply chains for wide-bandgap materials like silicon carbide and securing access to fabrication capacity.
Market Dynamics
The fundamental market dynamic is the material science transition from silicon to wide-bandgap semiconductors like Silicon Carbide and Gallium Nitride. This shift is driven by the urgent need for higher power density, thermal efficiency, and faster switching speeds in electric vehicles and renewable energy systems.
Growth Catalysts
- EV Powertrain Electrification:The accelerated adoption of electric vehicles, particularly in China and Germany, creates substantial volume demand for SiC-based inverters and onboard chargers to improve range and charging speed.
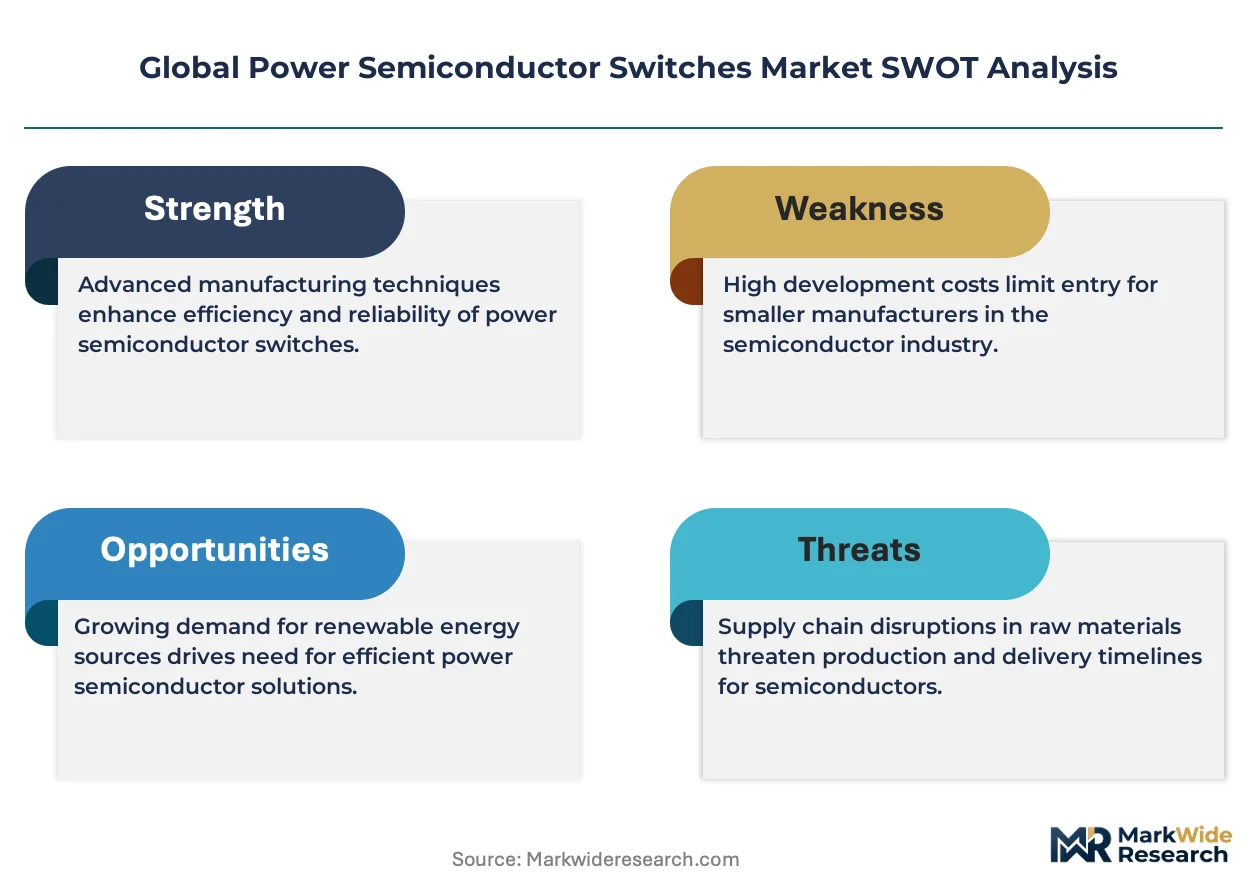
- Renewable Energy Mandates:Policies like the EU Green Deal and national renewable energy targets necessitate more efficient power conversion in solar and wind energy systems, favoring the superior performance of SiC and GaN devices.
- Industrial Automation:The expansion of smart factories and robotics in manufacturing hubs like Japan requires advanced motor drives and power supplies that utilize high-frequency power switches for precision and energy savings.
Market Restraints
- Substrate Cost and Availability:The high manufacturing cost and limited global supply of high-quality silicon carbide substrates act as a primary constraint on production scalability and create price pressure for device makers.
- Technical Integration Hurdles:Designing with wide-bandgap devices requires specialized gate drivers and passive components, posing a technical challenge and increasing system complexity for engineers accustomed to traditional silicon.
- Reliability Data Scarcity:For mission-critical applications like aerospace and grid infrastructure, the relative lack of long-term field reliability data for newer SiC and GaN technologies can slow qualification and adoption cycles.
Strategic Opportunities
- Next-Generation Grid Infrastructure:Modernization of electrical grids in North America and Europe presents an opportunity for SiC-based solid-state transformers and high-voltage DC transmission systems, creating a new high-value market.
- Gallium Nitride in Consumer Electronics:The demand for smaller, faster-charging power adapters for laptops and smartphones opens a volume opportunity for GaN technology to displace silicon in the consumer power supply segment. *Advanced Power Module Packaging: Developing innovative packaging solutions that improve thermal management and reduce parasitic inductance for high-frequency SiC and GaN devices offers a path to significant performance differentiation.
Industry Challenges
- Specialized Engineering Talent:A shortage of power electronics engineers with deep expertise in wide-bandgap semiconductor physics, circuit design, and application integration hampers product development across the industry.
- Manufacturing Yield and Defects:Achieving high-yield, low-defect manufacturing for large-diameter SiC wafers remains a significant technical and capital-intensive challenge, impacting cost and supply stability.
- Standardization of Testing Protocols:The absence of universally accepted standards for testing the dynamic performance and long-term reliability of SiC and GaN devices creates uncertainty for system designers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Power Semiconductor Switches Market |
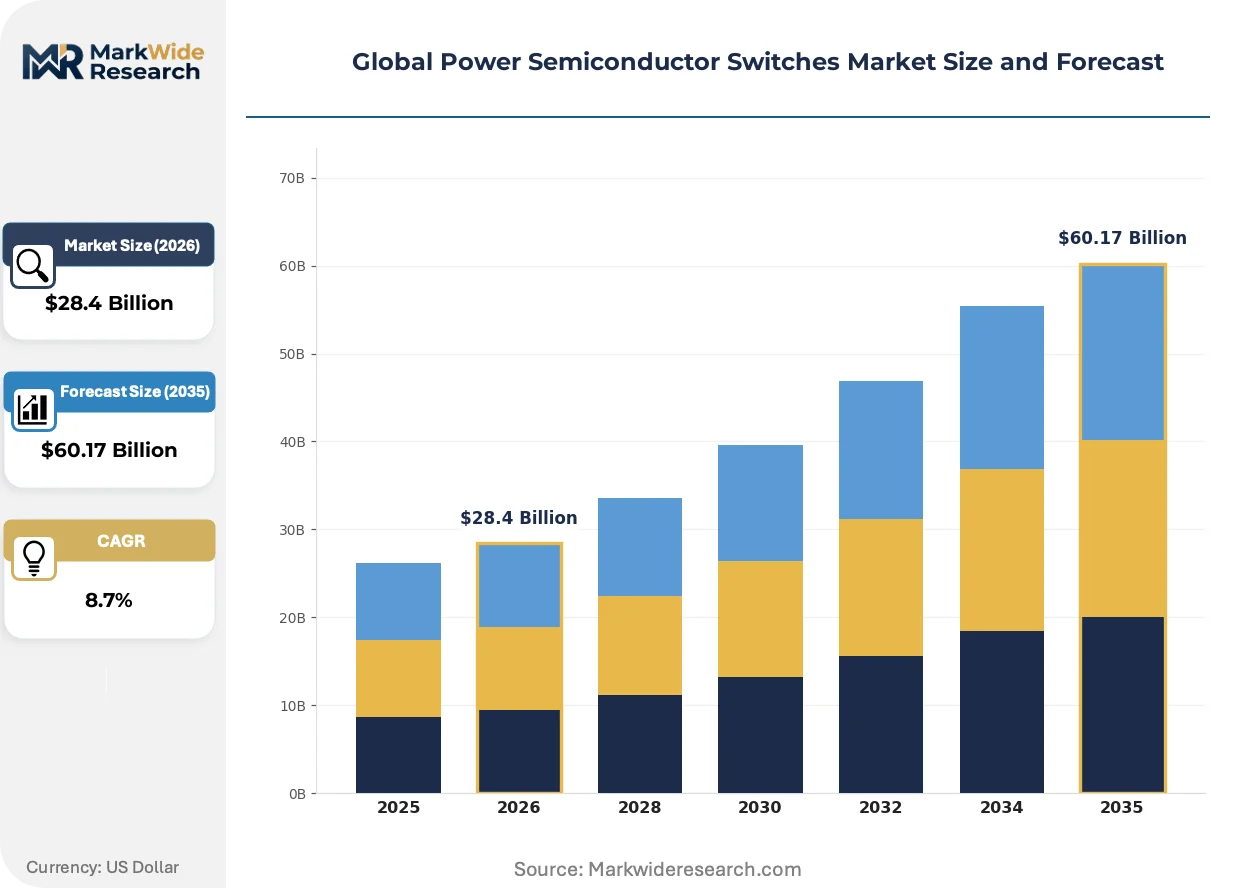
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IGBT, MOSFET, Thyristor, Gate Turn-Off Thyristor, Integrated Circuits Technology: Silicon Carbide, Gallium Nitride, Silicon, Germanium, Diamond-Based Application: Renewable Energy, Electric Transportation, Consumer Electronics, Industrial Automation, Power Grid Management End User: OEMs, Equipment Manufacturers, Energy Providers, Transportation Systems, Consumer Device Makers |
| Companies Covered | Infineon Technologies, STMicroelectronics, ON Semiconductor, Texas Instruments, ROHM Semiconductor, NXP Semiconductors, Renesas Electronics, Mitsubishi Electric, Toshiba Electronic Devices & Storage, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Power Semiconductor Switches Market Strategic Shifts & Innovations
Performance demands from the automotive and industrial sectors are converging with energy efficiency regulations to accelerate innovation in materials, device architecture, and system integration. The market's evolution is defined by the pursuit of higher power density and reduced energy loss in power conversion applications.
Gallium Nitride technology enables significantly higher switching frequencies compared to silicon, which is critical for compact power supply designs. This technology is being rapidly adopted by manufacturers of consumer electronics chargers and data center power solutions seeking to improve efficiency and reduce physical footprint. As a result, power system design is migrating from bulky, discrete silicon-based circuits to highly integrated, compact GaN-based power modules.
Regulatory frameworks are a primary force shaping technology adoption, particularly in transportation. The United States EPA's vehicle efficiency standards directly incentivize automakers to reduce energy losses in electric vehicle powertrains. This pressure compels Tier 1 automotive suppliers and OEMs to accelerate the integration of high-efficiency silicon carbide inverters, with the North American automotive market becoming a key battleground for SiC component qualification.
Component selection is evolving from transactional purchases to a more integrated, platform-based approach, especially for complex systems. Engineers are increasingly favoring suppliers that offer comprehensive design ecosystems, including simulation models, reference designs, and evaluation kits that shorten development cycles. This trend is most pronounced in the competitive industrial automation and medical device sectors in Europe, where rapid prototyping confers a significant market advantage.
Global Power Semiconductor Switches Market Segmentation
Understanding the segmentation of the global power semiconductor switches market is critical for identifying specific growth vectors and technological shifts. This analysis categorizes components by their fundamental characteristics, material science, and their diverse deployment across various industries. Each segment reflects distinct performance requirements and market dynamics.
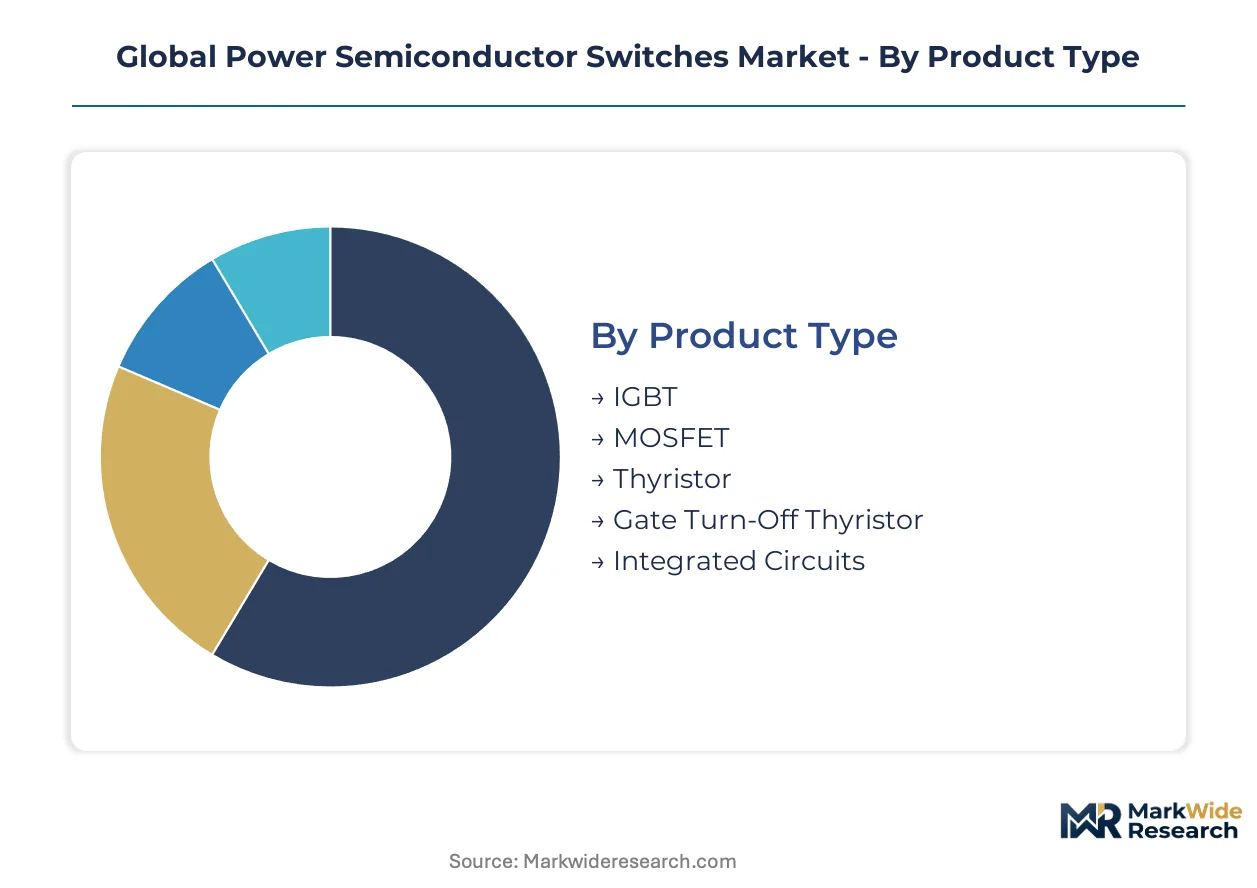
Product Type:
The product type dimension categorizes power semiconductor switches based on their core functionality and operational characteristics.
- IGBT:Insulated Gate Bipolar Transistors combine high-speed switching of MOSFETs with high-power handling of bipolar transistors, essential for high-voltage applications. Demand concentrates in electric vehicle inverters and industrial motor drives across Germany and China, driven by the need for efficient power conversion.
- MOSFET:Metal-Oxide-Semiconductor Field-Effect Transistors offer fast switching speeds and low conduction losses at moderate voltage levels, making them suitable for many power management circuits. Global demand focuses on onboard chargers in electric vehicles and power supplies for data centers, driven by efficiency and compactness requirements.
- Thyristor:These are four-layer solid-state devices primarily used for high-power switching applications, particularly in industrial controls and power transmission systems.
- Gate Turn-Off Thyristor:GTOs are high-power semiconductor devices capable of being turned on and off by gate signals, finding use in high-voltage DC transmission systems.
- Integrated Circuits:These combine multiple power semiconductor functions onto a single chip, offering compact and efficient power management solutions for consumer electronics.
Thyristor technology commands the established base. The steepest expansion runs through IGBTs.
Technology:
Technological advancements define the performance envelope for power semiconductor switches, driving efficiency gains.
- Silicon Carbide:SiC devices offer superior thermal conductivity, higher breakdown voltage, and faster switching speeds compared to traditional silicon. Automotive manufacturers in Japan and North America demand SiC for traction inverters, driven by vehicle range and charging speed improvements.
- Gallium Nitride:GaN technology enables significantly higher switching frequencies and smaller form factors, reducing energy loss in high-frequency applications. Consumer electronics brands globally integrate GaN into compact fast chargers, driven by portability and efficiency.
- Silicon:Traditional silicon-based power semiconductors remain a cost-effective solution for a wide range of lower-power and less demanding applications.
- Germanium:Germanium devices offer specific performance characteristics for specialized high-frequency or low-noise applications, though less common than silicon.
- Diamond-Based:Diamond-based semiconductors represent an emerging technology with potential for extreme power and temperature handling, currently in research and development phases.
Silicon devices continue to hold significant volume. However, Gallium Nitride technology exhibits the fastest market penetration.
Application:
The application landscape for power semiconductor switches spans critical sectors requiring precise power control.
- Electric Transportation:This segment includes powertrain inverters, onboard chargers, and DC-DC converters for electric and hybrid vehicles. Demand for high-efficiency SiC and GaN devices is surging in China and Germany, propelled by stringent vehicle emission standards and consumer preference for longer range.
- Renewable Energy:Power semiconductor switches are vital for efficient power conversion in solar inverters, wind turbine converters, and energy storage systems. European energy providers are increasingly adopting SiC devices to meet EU Green Deal targets for grid stability and efficiency.
- Consumer Electronics:This segment encompasses power adapters, chargers, and power management units for devices like smartphones, laptops, and home appliances.
- Industrial Automation:Power switches control motors, robotics, and power supplies in smart factories and manufacturing processes, particularly in Japan and Germany.
- Power Grid Management:These components are used in high-voltage DC transmission, flexible AC transmission systems, and smart grid infrastructure for efficient power distribution.
Industrial Automation remains a foundational application. Electric Transportation is rapidly gaining market share.
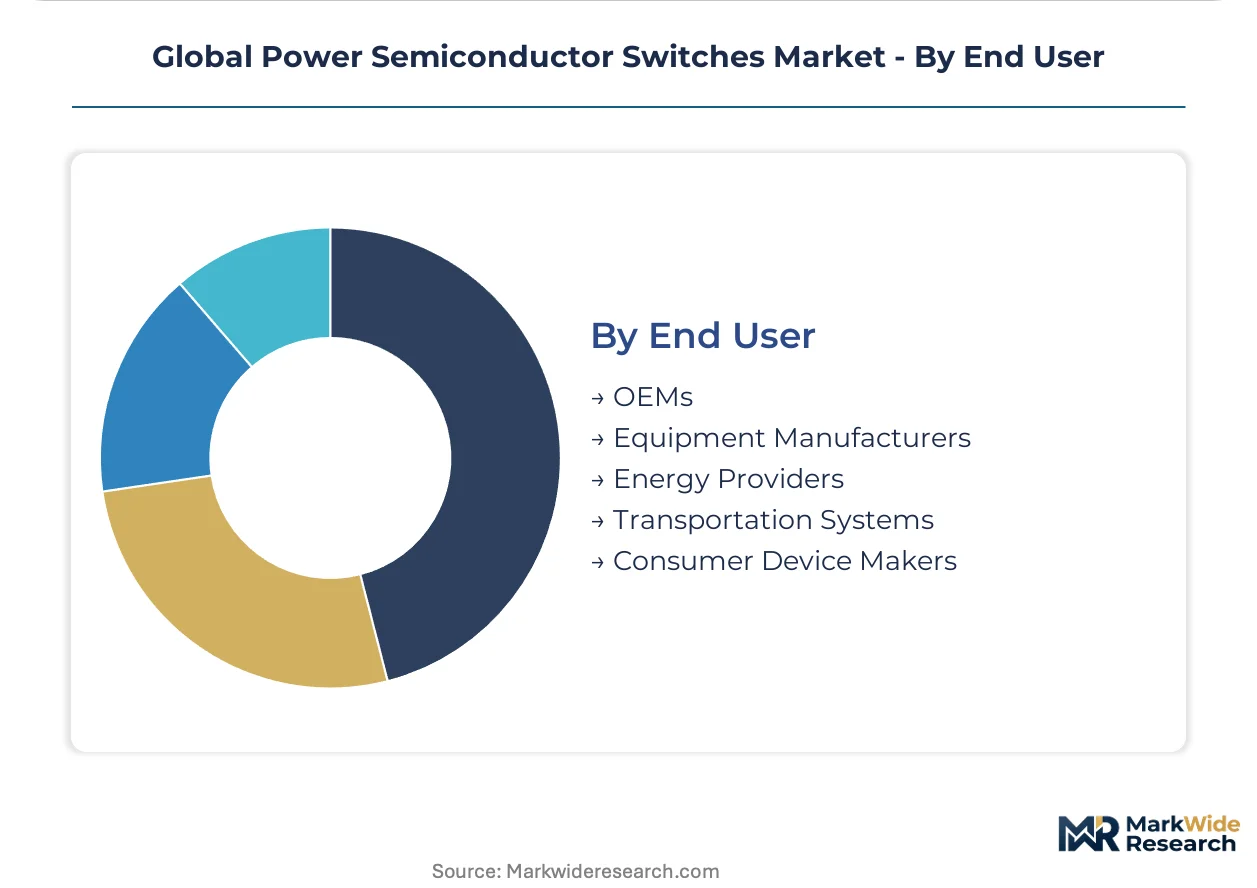
End User:
Demand for power semiconductor switches originates from diverse end-user segments integrating these components into complex systems.
- OEMs:Original Equipment Manufacturers integrate power semiconductor switches directly into their final products, such as electric vehicles, industrial machinery, and renewable energy systems. Automotive OEMs in North America and Europe are driving significant volume for advanced SiC modules.
- Equipment Manufacturers:These companies produce specialized equipment like power supplies, motor drives, and inverters that incorporate power semiconductor switches. Industrial equipment makers in Germany and Japan require high-reliability components for their automation solutions.
- Energy Providers:Utilities and power generation companies utilize power switches in grid infrastructure, substations, and renewable energy installations.
- Transportation Systems:This segment includes rail, marine, and aerospace sectors requiring robust power electronics for propulsion and auxiliary systems.
- Consumer Device Makers:Manufacturers of smartphones, laptops, and other consumer gadgets are key buyers for compact and efficient GaN-based power solutions.
Energy Providers represent a stable, long-term procurement channel. Consumer Device Makers are driving rapid volume shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The expansion of advanced electrical grid infrastructure across industrialized nations underpins regional growth for power semiconductor switches. This infrastructure modernization enables efficient power distribution, creating substantial demand for high-voltage silicon carbide devices. Global manufacturing hubs also drive localized procurement for advanced power solutions.
Germany
German industrial manufacturing requires advanced motor drives and power supplies, creating strong demand for IGBTs. The EU Green Deal mandates efficient power conversion in renewable energy systems, favoring SiC devices. Automotive manufacturing centers in Stuttgart and Munich actively integrate SiC inverters for electric vehicles.
China
Chinese electric vehicle production drives substantial volume demand for SiC-based inverters and onboard chargers. China's GB standards for electronics mandate specific energy efficiency levels, accelerating GaN adoption. The Yangtze River Delta region concentrates significant electronics manufacturing for power components.
Japan
Japanese manufacturers require high-frequency power switches for industrial automation and robotics, utilizing advanced SiC devices. METI policies support domestic semiconductor production and advanced material research. Kyushu serves as a key semiconductor production cluster, supplying global automotive OEMs.
United States
American regulatory frameworks, including EPA vehicle efficiency targets, directly influence the adoption of advanced power switches in electric powertrains. Grid modernization efforts in North America present opportunities for SiC-based solid-state transformers. Silicon Valley remains a hub for power management IC design and system integration.
South Korea
South Korean consumer electronics brands integrate GaN into compact fast chargers, driven by portability and efficiency requirements. Government initiatives support the domestic semiconductor industry through R&D funding. Gyeonggi Province hosts major electronics manufacturing facilities requiring high-performance power components.
Global Power Semiconductor Switches Market Key Industry Players
On the supply side, the industry is characterized by a mix of highly scaled integrated device manufacturers and specialized component providers. Strategic archetypes include large-scale IDMs with broad portfolios, focused wide-bandgap material specialists, and integrated power management IC developers. Dominant competitive moves involve capacity expansion for wide-bandgap materials and strategic partnerships for system-level integration.
Integrated device manufacturers like Infineon Technologies and STMicroelectronics leverage extensive portfolios across diverse applications. These companies occupy a position providing comprehensive solutions for automotive and industrial sectors. Texas Instruments exemplifies a specialist in integrated power management ICs, fostering an extensive developer ecosystem for its solutions.
| Leading Market Players |
|---|
| Infineon Technologies |
| STMicroelectronics |
| ON Semiconductor |
| Texas Instruments |
| ROHM Semiconductor |
| NXP Semiconductors |
| Renesas Electronics |
| Mitsubishi Electric |
| Toshiba Electronic Devices & Storage |
| Others |
Cost & Logistics Intelligence
Single-source dependency on wide-bandgap material suppliers determines both pricing tier spreads and the structural shape of the power semiconductor switches supply chain. This concentration creates specific vulnerabilities for device manufacturers seeking to scale production. Downstream, distribution channels are evolving to offer more integrated design support.
Pricing Analysis
Contract-based long-term offtake agreements define the dominant pricing model, featuring volume-discount tiering. Price differentiation stems from the performance tier of the technology, such as Silicon Carbide versus traditional Silicon, and the level of integrated design support offered. Pricing softness runs through commoditized silicon-based devices due to intense competition. Consumer electronics device makers exhibit the highest price sensitivity, while aerospace and grid infrastructure OEMs prioritize reliability over cost.
Supply Chain Analysis
Upstream feedstock for wide-bandgap materials is geographically concentrated. Silicon carbide substrate production concentrates in Japan and the United States, while gallium nitride epitaxial wafer supply is centered in China and Japan. High-purity silicon, SiC substrates, and GaN epitaxy are critical inputs. Limited global supply of high-quality wide-bandgap substrates creates a single-source vulnerability for device manufacturers. Distribution runs through specialized electronics component suppliers and direct OEM engagement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The power semiconductor switches market presents a fragmentation opportunity. The rapid diversification of electric vehicle architectures creates specific niches for optimized power module designs.
For Market Incumbents: Build intellectual property moats around advanced packaging and gate driver integration. Secure long-term supply agreements for SiC substrates and invest in proprietary fabrication capacity. Emerging wide-bandgap specialists threaten market share in high-growth segments. Leverage extensive R&D in thermal management and system-level integration.
For New Entrants and Emerging Players: Establish a beachhead in the consumer electronics fast charger segment. Focus on GaN-based power solutions for compact power adapters and data center power supplies. Offer comprehensive design support and rapid prototyping services to accelerate adoption among consumer device makers.
For Investors and Strategic Acquirers: The market sits at a high-growth transition phase that favors specialized wide-bandgap material producers. Long-term viability for power semiconductor switches remains strong over the next decade. Identify mid-cap firms with proprietary SiC substrate manufacturing or advanced GaN epitaxy capabilities. Watch for increased standardization of SiC and GaN testing protocols as an inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for SiC Wafers | Increases material availability and reduces cost pressure for automotive OEMs. |
| Strategic Partnership in GaN Power Modules | Accelerates market penetration into compact consumer electronics applications globally. |
| Investment in Advanced Packaging Technology | Improves thermal management and reliability for high-power density devices. |
| Development of Integrated Power Management ICs | Offers system-level solutions, reducing design complexity for industrial clients. |
| Acquisition of Specialized Gate Driver Firms | Enhances performance and simplifies integration of wide-bandgap semiconductors. |
Research Approach
A spread of perspectives from power electronics engineers, automotive OEM procurement leads, industrial automation system integrators, and wide-bandgap material scientists converged on the working assumptions. Primary interviews were combined with secondary validation from regulatory filings and technical journals. National energy agency reports, semiconductor industry association data, and patent databases provided critical insights. Bottom-up market sizing was triangulated with top-down industry revenue analysis.
Demand-supply balance for power semiconductor switches was modeled, considering material availability and fabrication capacity constraints. The analytical framework projected market evolution across the analysis window. Segmentation dimensions included product type, technology, application (e.g., electric transportation, renewable energy), and regional manufacturing hubs. Compound annual growth rates were derived from historical trends and projected technological adoption curves. Electric vehicle production forecasts and renewable energy installation targets served as key inputs.
Stress conditions across wide-bandgap material cost and fabrication yield were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory stability and technological development trajectories. Geopolitical trade policies could significantly revise these projections. Cross-checking against national semiconductor policy benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
AC DC Power Adapter Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Grid Forming Inverters Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Superconducting Magnet Systems Market
Power Systems
Global Inverter Market
Power Systems
Power Integrated Modules Market
Power Systems
Global Data Center Transformer Market
Power Systems
Global Plasma Generators Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Telecom Power Systems Market
Power Systems
South America Battery Management System Market