
 Wireless Battery Monitoring System Market | 2026-2036
Wireless Battery Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Battery Monitoring System Market Outlook
Silicon carbide is hardening as the preferred substrate for power-conditioning circuitry inside wireless battery monitoring nodes, trimming thermal losses and extending sensor longevity in high-voltage packs. Texas Instruments leverages its analog front-end portfolio to dominate precision voltage sensing for electric vehicle modules. Schneider Electric anchors its position through integrated building-energy platforms that embed battery telemetry alongside HVAC and power distribution. NXP Semiconductors differentiates via automotive-grade wireless transceivers certified to ASIL functional-safety thresholds.
A wireless battery monitoring system comprises distributed sensor arrays, microcontrollers, and radio-frequency communication modules that measure cell voltage, temperature, and impedance without hardwired data buses, typically operating at sampling rates between one hertz and one kilohertz depending on chemistry criticality. The architecture serves to prevent thermal runaway, optimize charge cycles, and forecast remaining useful life in electrochemical storage installations. LoRaWAN dominates utility-scale grid storage deployments where kilometre-range links and sub-milliwatt standby power justify lower bandwidth. The automotive end-user segment leads absolute spending as OEMs mandate cell-level monitoring for warranty compliance and over-the-air diagnostics. Software components capture expanding margin pools as analytics shift from threshold alarms toward physics-informed predictive models.
The EU Battery Regulation, EPA hazardous-material transport rules, and China's GB/T battery safety standards collectively mandate traceable state-of-health documentation, forcing manufacturers to embed wireless telemetry as a compliance substrate rather than an optional upgrade. ISO 26262 functional-safety certification and UN 38.3 lithium-ion testing protocols further shape product design cycles and supplier qualification timelines. Stakeholders must weigh whether to develop proprietary wireless stacks or adopt standardized protocols that simplify cross-border certification but erode hardware differentiation.
Market Dynamics
The EU Battery Regulation's digital passport mandate is compressing product development timelines, forcing manufacturers to embed wireless telemetry as a compliance substrate rather than an optional upgrade across all battery chemistries and form factors.
Growth Catalysts
- EU Battery Regulation:The digital passport requirement mandates real-time state-of-health tracking for industrial batteries entering European markets, creating baseline demand for wireless monitoring hardware.
- Electric vehicle fleet operators:Distributed charging network operators are expanding wireless deployments to manage lithium-ion cell degradation remotely, reducing manual inspection costs.
- Silicon carbide substrates:Adoption of SiC power-conditioning circuitry in high-voltage packs trims thermal losses and extends sensor longevity, enabling harsher operating environments.
Market Restraints
- ASIL functional-safety certification:Automotive-grade wireless transceiver qualification to ISO 26262 thresholds extends supplier development cycles and gates market entry.
- LoRaWAN bandwidth limitations:Sub-kilohertz sampling rates in utility-scale grid storage constrain impedance spectroscopy applications requiring higher data throughput.
- UN 38.3 lithium-ion testing:Pre-shipment certification protocols for wireless-enabled battery packs add documentation burden and logistics friction for cross-border trade.
Strategic Opportunities
- Second-life stationary storage:Retired electric vehicle batteries entering grid-buffer applications require continuous health monitoring without hardwired infrastructure.
- Over-the-air diagnostic services:OEM aftermarket platforms are unbundling predictive analytics from hardware sales, creating recurring software revenue streams.
- China's GB/T battery safety standards:Traceable state-of-health documentation requirements are accelerating domestic demand for compliant wireless telemetry systems.
Industry Challenges
- Physics-informed model development:Predictive battery analytics requires electrochemical engineering talent scarce in traditional electronics firms.
- Legacy BMS integration:Retrofitting wireless nodes into existing wired battery management architectures demands custom gateway development and validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Battery Monitoring System Market |
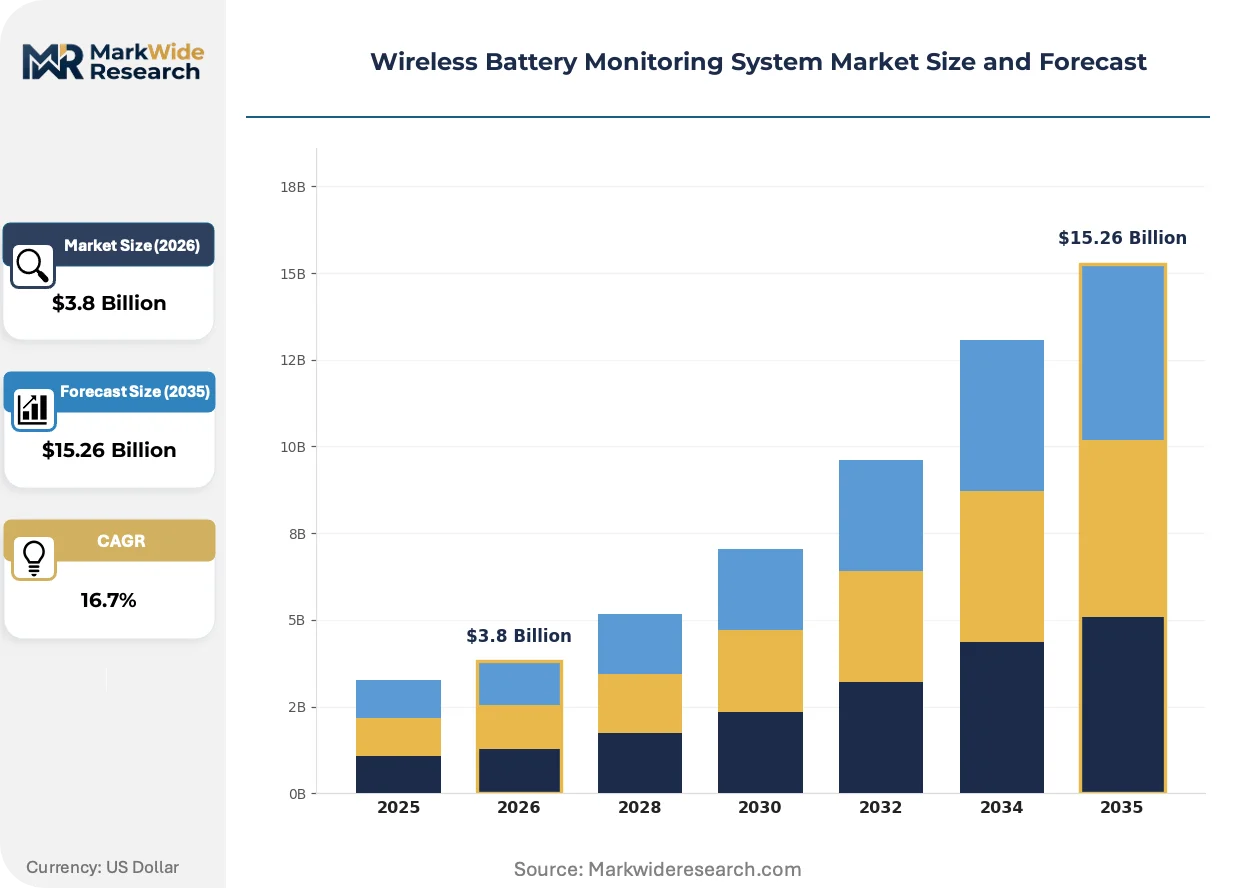
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: LoRaWAN, Zigbee, Bluetooth, Wi-Fi End User: Automotive, Telecom, Renewable Energy, Industrial Component: Sensors, Controllers, Communication Modules, Software Application: Grid Storage, Electric Vehicles, UPS, Telemetry |
| Companies Covered | Schneider Electric, Alber, Texas Instruments, Eagle Eye Power Solutions, Baker Hughes, NXP Semiconductors, Lithium Balance, Vecture, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Battery Monitoring System Market Strategic Shifts
Wireless battery monitoring is pivoting from threshold alarms toward predictive physics models, with three concurrent shifts reshaping hardware specifications, compliance frameworks, and service delivery economics.
Silicon carbide power semiconductors are converging with wireless sensor nodes to manage thermal dissipation in 800-volt electric vehicle architectures. German automotive OEMs are qualifying SiC-based conditioning circuits for cell-level monitoring modules. This convergence is compressing the performance gap between automotive-grade and industrial-grade monitoring hardware.
The EU Battery Regulation's state-of-health documentation requirements are forcing manufacturers to redesign product architectures around continuous data logging. Industrial battery suppliers must now embed wireless telemetry as standard equipment rather than premium options. Grid-scale storage deployments in Germany and the Netherlands are responding by specifying LoRaWAN-enabled systems for decade-long traceability.
Service unbundling is separating hardware procurement from predictive analytics subscriptions across fleet operator segments. Tier-one battery integrators are displacing bundled sales with metered diagnostic contracts. This shift is most visible in California and Texas, where electric vehicle fleet managers prioritize operational expenditure models over capital-intensive system purchases.
Wireless Battery Monitoring System Market Segmentation
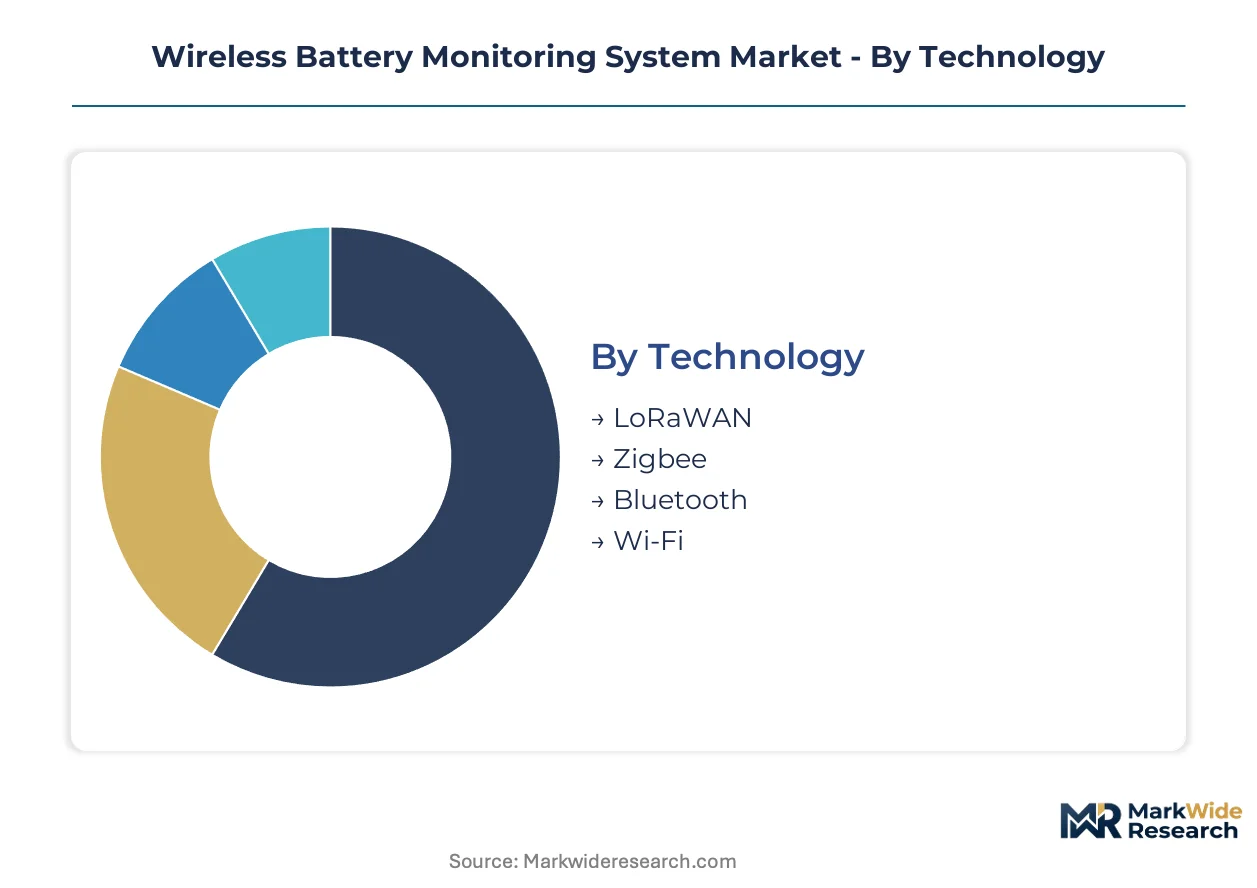
Wireless battery monitoring architectures diverge sharply across power levels, latency tolerances, and regulatory exposure zones. Buyers select technology stacks and component mixes based on whether their priority is kilometer-range grid telemetry or millisecond-critical automotive safety loops.
Technology:
Cost tier separates utility-scale deployments from consumer-adjacent installations, with link range and standby power drawing the sharpest dividing lines.
- LoRaWAN:Sub-gigahertz modulation achieves ten-kilometer reach in rural terrain while drawing microamperes during idle states. German grid operators specify LoRaWAN for decade-long battery passport compliance across distributed solar-storage clusters.
- Zigbee:Mesh-native protocol self-heals around node failures in dense industrial environments. Demand clusters in Japanese manufacturing facilities requiring sub-ten-millisecond latency for thermal runaway alerts.
- Bluetooth:Low-energy stacks dominate smartphone-tethered diagnostics in light electric vehicle fleets.
- Wi-Fi:High-throughput links serve indoor UPS installations with existing enterprise infrastructure.
Volume placements concentrate in LoRaWAN; the faster expansion belongs to Zigbee as industrial mesh requirements harden.
End User:
Application maturity shapes procurement sophistication, with warranty liability and fleet scale driving specification stringency.
- Automotive:ASIL-D functional-safety mandates force redundant wireless paths for cell-level voltage sensing. OEMs in Germany's automotive corridor integrate predictive analytics platforms to manage warranty exposure across million-unit battery fleets.
- Telecom:Tower operators mandate decade-long state-of-health logging to satisfy insurer requirements for lithium-ion backup systems. India's TRAI guidelines on telecom infrastructure reliability accelerate domestic specification adoption.
- Renewable Energy:Solar-plus-storage hybrids in California and Texas require continuous impedance tracking to optimize dispatch economics.
- Industrial:Forklift and material-handling fleets in US logistics hubs prioritize rapid retrofit over embedded design cycles.
Procurement volume tilts toward Automotive; Renewable Energy climbs fastest as grid interconnection queues lengthen.
Component:
Margin capture separates hardware suppliers from software platforms, with recurring revenue potential dictating strategic positioning.
- Sensors:Precision voltage and temperature transducers with automotive-grade calibration dominate bill-of-materials value. Silicon carbide conditioning circuits from German tier-one suppliers extend operating temperature ranges for 800-volt architectures.
- Software:Physics-informed predictive models command subscription pricing detached from hardware shipments. California fleet operators unbundle diagnostics from sensor procurement, creating metered revenue streams.
- Controllers:Microcontroller units integrate analog front-ends with protocol stacks in single-package designs.
- Communication Modules:Certified radio-frequency subsystems simplify regulatory approval for integrators lacking in-house wireless expertise.
Hardware shipments concentrate in Sensors; Software subscriptions expand most quickly as service unbundling accelerates.
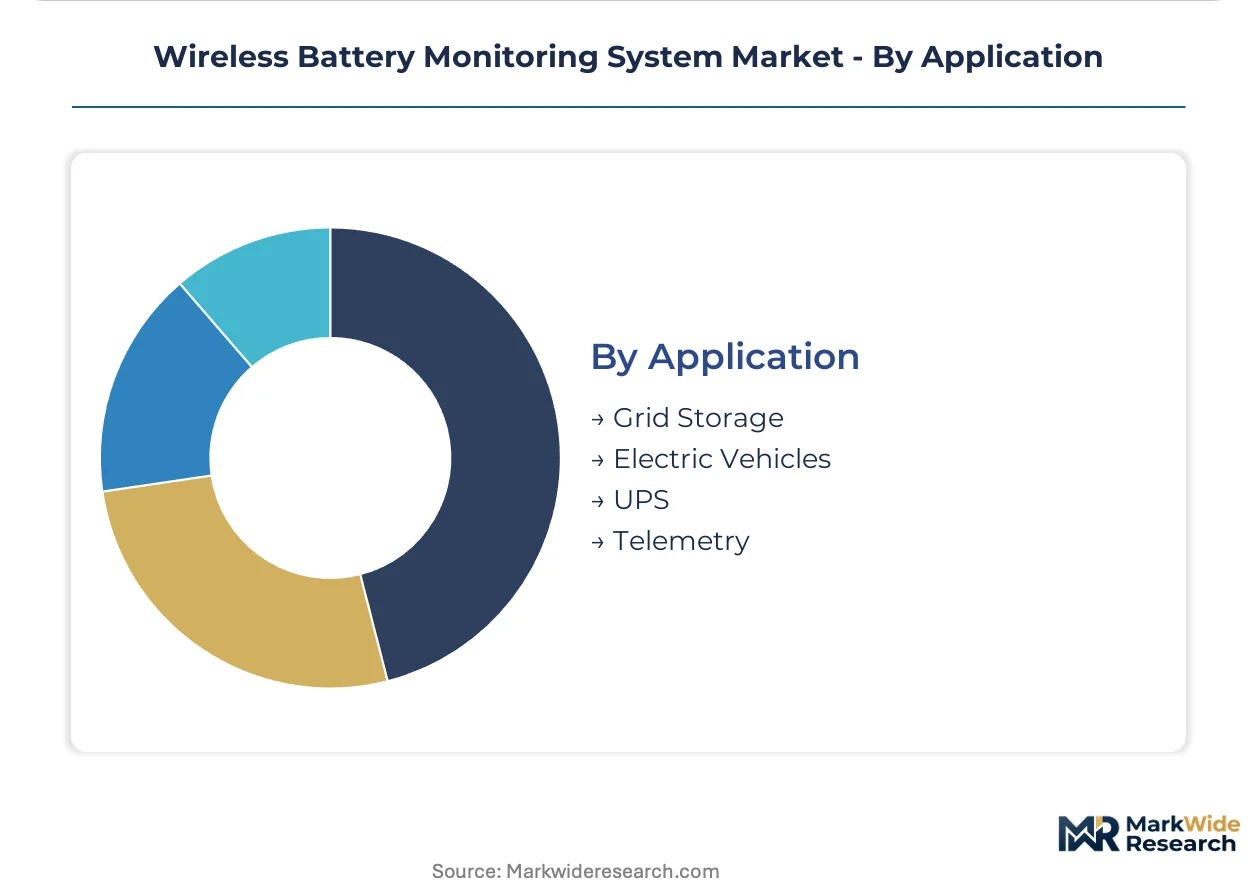
Application:
Regulatory intensity varies by deployment context, with passenger safety and grid stability codes imposing divergent certification burdens.
- Electric Vehicles:UN 38.3 pre-shipment testing and ISO 26262 functional-safety certification gate market entry. EU Battery Regulation digital passport requirements embed wireless telemetry as mandatory infrastructure across all chemistries.
- Grid Storage:FERC Order 2222 participation rules and decade-long asset depreciation schedules demand continuous health documentation. Dutch utility-scale installations specify LoRaWAN-enabled systems for regulatory traceability.
- UPS:Enterprise data center uptime requirements drive redundant monitoring paths in critical power infrastructure.
- Telemetry:Remote industrial sites lacking wired connectivity adopt satellite-backhauled wireless nodes for predictive maintenance.
Deployment scale favors Grid Storage; Electric Vehicles gain share fastest as OEM warranty terms tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle fleet operators and grid-scale storage developers concentrate wireless battery monitoring procurement in Germany, the United States, China, Japan, and India, with regulatory mandates in each jurisdiction dictating specification timelines and certification requirements.
Germany
Automotive OEMs and tier-one suppliers in Baden-Württemberg and Bavaria drive demand for ASIL-D certified wireless transceivers in 800-volt architectures. The EU Battery Regulation's digital passport mandate forces manufacturers to embed real-time state-of-health tracking as standard equipment. Stuttgart's automotive corridor hosts qualification programs for silicon carbide conditioning circuits in cell-level monitoring modules.
United States
Electric vehicle fleet operators in California and Texas prioritize operational expenditure models for predictive diagnostics over capital-intensive hardware purchases. FERC Order 2222 participation rules for distributed energy resources mandate continuous health documentation for grid-connected storage. Silicon Valley software platforms unbundle analytics subscriptions from sensor procurement across light electric vehicle fleets.
China
Domestic battery manufacturers accelerate wireless telemetry adoption to satisfy GB/T battery safety standards for traceable state-of-health documentation. The MIIT's dual carbon goals pressure industrial operators to optimize lithium-ion cell degradation management across distributed charging networks. Shenzhen and Shanghai host development programs for LoRaWAN-enabled systems in utility-scale solar-plus-storage hybrids.
Japan
Manufacturing facilities in the Chubu region specify Zigbee mesh protocols for sub-ten-millisecond thermal runaway alerts in dense industrial environments. METI guidelines on battery safety and recycling infrastructure mandate embedded monitoring for second-life stationary storage applications. Nagoya's industrial cluster drives demand for self-healing wireless architectures around node failures.
India
Telecom tower operators expand wireless monitoring deployments to satisfy TRAI guidelines on infrastructure reliability for lithium-ion backup systems. The CEA's grid interconnection standards for renewable-plus-storage projects require decade-long state-of-health logging. Maharashtra and Karnataka host procurement programs for kilometer-range telemetry in rural solar-storage clusters.
Wireless Battery Monitoring System Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with semiconductor suppliers and industrial automation groups commanding premium positions in automotive and grid storage respectively. The vendor base organizes around three archetypes: analog front-end specialists, integrated building-energy platforms, and automotive-grade wireless transceiver suppliers. Consolidation pressures concentrate among semiconductor suppliers where ASIL certification gates market entry. Dominant competitive moves include strategic partnerships for protocol certification and geographic expansion through tier-one battery integrator relationships.
Within the analog front-end tier, Texas Instruments represents precision voltage sensing specialization for electric vehicle modules. Schneider Electric exemplifies integrated platform positioning through building-energy systems that embed battery telemetry alongside power distribution infrastructure. NXP Semiconductors occupies a position within automotive-grade wireless transceivers certified to ASIL functional-safety thresholds. These three anchors illustrate divergent paths to margin capture across hardware, software, and certification-intensive segments.
| Leading Market Players |
|---|
| Schneider Electric |
| Alber |
| Texas Instruments |
| Eagle Eye Power Solutions |
| Baker Hughes |
| NXP Semiconductors |
| Lithium Balance |
| Vecture |
| ABB |
| Others |
Value Chain & Pricing Dynamics
ASIL certification tiers split the market into automotive-grade premium modules and industrial-grade commodity nodes, with the former commanding hardware-software bundles and the latter competing on per-unit sensor costs. This bifurcation concentrates margin capture among semiconductor suppliers with ISO 26262 qualification capabilities while compressing returns for undifferentiated LoRaWAN hardware vendors.
Pricing Analysis
Volume shipments concentrate in per-unit transactional sales of sensor arrays and communication modules, while margin pools accrue to subscription-based predictive analytics platforms. Price differentiation rests on ASIL-D functional-safety certification and silicon carbide substrate integration for 800-volt architectures. Cost compression in industrial-grade Zigbee nodes is intensifying because Chinese manufacturers are scaling LoRaWAN production for domestic grid storage deployments. Fleet operators in California and Texas exhibit the highest price sensitivity, prioritizing operational expenditure models over capital-intensive hardware procurement.
Supply Chain Analysis
Domestic-content mandates in China's GB/T compliance framework and India's PLI scheme for electronics manufacturing are forcing battery integrators to localize wireless module assembly. Geographic supply concentration centers on China for lithium-ion cell production, Germany for automotive-grade microcontroller fabrication, and Taiwan for silicon carbide wafer supply. Raw material dependencies include rare-earth elements for RF transceivers, high-purity silicon for carbide substrates, and cobalt-nickel chemistries for reference electrodes. Single-source vulnerability in automotive-grade foundry capacity poses structural risk. Distribution runs through tier-one battery integrators and industrial automation distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wireless battery monitoring is transitioning from wired legacy architectures to distributed RF-enabled nodes, with silicon carbide power conditioning displacing silicon-based thermal management in high-voltage electric vehicle packs.
For Market Incumbents: Cement ASIL-D certification moats by accelerating automotive-grade transceiver qualification programs ahead of EU Battery Regulation enforcement waves. Prioritize backward integration into silicon carbide substrate supply to defend margin position against commodity RF module vendors. Lock in decade-long service contracts with German OEMs to anchor recurring software revenue streams.
For New Entrants and Emerging Players: Cloud-native diagnostic platforms offer the lowest barrier to entry, enabling software-only market penetration ahead of hardware certification cycles. Target second-life stationary storage applications in Japan and India where legacy BMS retrofit demand outpaces embedded design capacity. Pursue white-label partnerships with telecom tower operators seeking TRAI-compliant monitoring without proprietary development.
For Investors and Strategic Acquirers: Re-rating potential sits with physics-informed analytics specialists given the shift toward predictive state-of-health modeling. Long-term viability favors platforms with electrochemical engineering talent depth rather than pure hardware manufacturers. Monitor GB/T standard adoption velocity in China as the inflection indicator for global protocol convergence.
| Strategic Initiative | Industry Significance |
|---|---|
| ASIL-D Certification Investment | Unlocks automotive OEM procurement pipelines requiring ISO 26262 functional-safety compliance. |
| SiC Substrate Integration | Extends sensor longevity in 800-volt electric vehicle architectures across Germany's automotive corridor. |
| Over-the-Air Platform Launch | Enables metered diagnostic subscriptions decoupled from hardware shipment economics. |
| Second-Life Storage Partnership | Captures demand from retired electric vehicle batteries entering grid-buffer applications. |
| LoRaWAN Protocol Certification | Accelerates utility-scale deployment approval under EU Battery Regulation traceability mandates. |
Study Parameters
Independent corroboration across primary interviews with BMS engineering directors, automotive platform procurement leads, and grid storage project developers, plus secondary validation through SEC filings of semiconductor suppliers, EIA battery deployment databases, and EU regulatory impact assessments, underwrites the qualitative findings. Bottom-up sensor shipment estimates and top-down addressable market calculations were triangulated to anchor volume projections.
Comparable historical deployment cycles in automotive electronics and utility telemetry informed the forecast window's baseline assumptions across the projection horizon. Segmentation dimensions modeled include wireless protocol type, end-user industry, component category, and application context, with CAGRs derived from fitted growth curves against documented installation ramps. Forecast inputs incorporated battery chemistry transition timelines and regulatory compliance phase-in schedules.
The model holds under stable lithium-ion cost curves and continued EU Battery Regulation enforcement; deviation in trade policy or ASIL certification backlogs would shift deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Static VAR Compensator (SVC) Market
Power Systems
Low Voltage Drives Market
Power Systems
Synchrophasors Market
Power Systems
Global Gan Power Device Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Central Battery Systems Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Grid Forming Inverters Market
Power Systems
Battery Charge Controller Market
Power Systems
Charge Controller System Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Three-Phase String Inverter Market
Power Systems
Hybrid Inverters Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Module-Level Power Electronics (MLPE) Market