
 Converter Modules Market | 2026-2036
Converter Modules Market Size, Share, and Industry Trends Forecast 2026-2036
Converter Modules Market Analysis
High-efficiency 98%-plus rating tiers is rotating toward the center of procurement specifications for hyperscale data centers. Vicor Corporation leverages proprietary factorized power architecture to sustain leadership in high-density vertical power delivery. Delta Electronics anchors its position through backward integration into magnetics and thermal management for telecom rectifiers. Texas Instruments competes by extending its portfolio of digitally controlled DC-DC converters with integrated telemetry.
Converter modules are electromechanical assemblies that transform electrical energy between AC and DC forms or between DC voltage levels, typically employing switch-mode topologies operating at frequencies from hundreds of kilohertz to several megahertz with efficiency targets exceeding 95 percent in commercial designs. Their primary purpose is to condition, isolate, and regulate power for sensitive electronic loads ranging from microprocessors to electric vehicle traction systems. DC-DC converters occupy the deepest margin pools as voltage regulation granularity becomes critical for AI processor power rails, while isolated converter variants lead in renewable energy inverter applications where galvanic separation protects downstream equipment. Switch mode technology dominates unit volume across industrial automation installations, though digital control architectures are displacing analog loops in telecommunications rectifiers requiring remote configurability.
The U.S. Department of Energy and EPA efficiency programs are tightening minimum load-point performance standards for external power supplies, compelling redesigns of AC-DC front ends across consumer and industrial product categories. The EU Ecodesign Directive and CE marking requirements are mandating standby power limits and harmonic current suppression that filter non-compliant module suppliers from European distribution channels. China's GB standards and MIIT efficiency classifications are creating parallel compliance tracks for modules serving domestic versus export equipment markets. Stakeholders must monitor how regional efficiency thresholds diverge and whether dual-certification architectures preserve market access without fragmenting product platforms.
Market Dynamics
Hyperscale data center operators are compressing power delivery architectures toward the processor package, eliminating intermediate voltage rails and forcing converter suppliers to relocate thermal and magnetic components into server sleds.
Growth Catalysts
- AI accelerator power rails:Voltage regulation granularity requirements below 0.5V at 1000A+ are mandating factorized power architectures in training clusters.
- EU Ecodesign Directive:Standby power limits below 0.5W and harmonic current suppression mandates are filtering non-compliant suppliers from European distribution channels.
- China domestic foundry expansion:Captive converter sourcing for semiconductor manufacturing equipment is concentrating procurement within vertically integrated supply chains.
Market Restraints
- Magnetic core material concentration:Ferrite and powder core supply concentrates among Japanese and Chinese specialty ceramic producers, creating input cost volatility.
- GaN device qualification timelines:Extended reliability testing for gallium nitride power switches delays product release cycles by 18-24 months versus silicon alternatives.
- Dual certification architectures:Diverging efficiency thresholds between China's GB standards and EU CE marking requirements fragment product platforms without volume scale.
Strategic Opportunities
- India data center buildout:PLI scheme incentives for electronics manufacturing are attracting module assembly investments to serve domestic cloud infrastructure demand.
- Vehicle-to-grid integration:Bidirectional onboard chargers requiring isolated DC-DC stages open new specification categories in electric vehicle power electronics.
- Solid-state transformer convergence:Medium-frequency power conversion at 10-20kHz enables direct MV-to-LV conversion, collapsing traditional distribution transformer and rectifier stages.
Industry Challenges
- Magnetics design specialization:Shortage of engineers proficient in planar transformer winding optimization and integrated inductor-heat sink co-design limits product development velocity.
- Digital controller firmware validation:Complex state machine verification for digitally controlled loops extends certification timelines with safety agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Converter Modules Market |
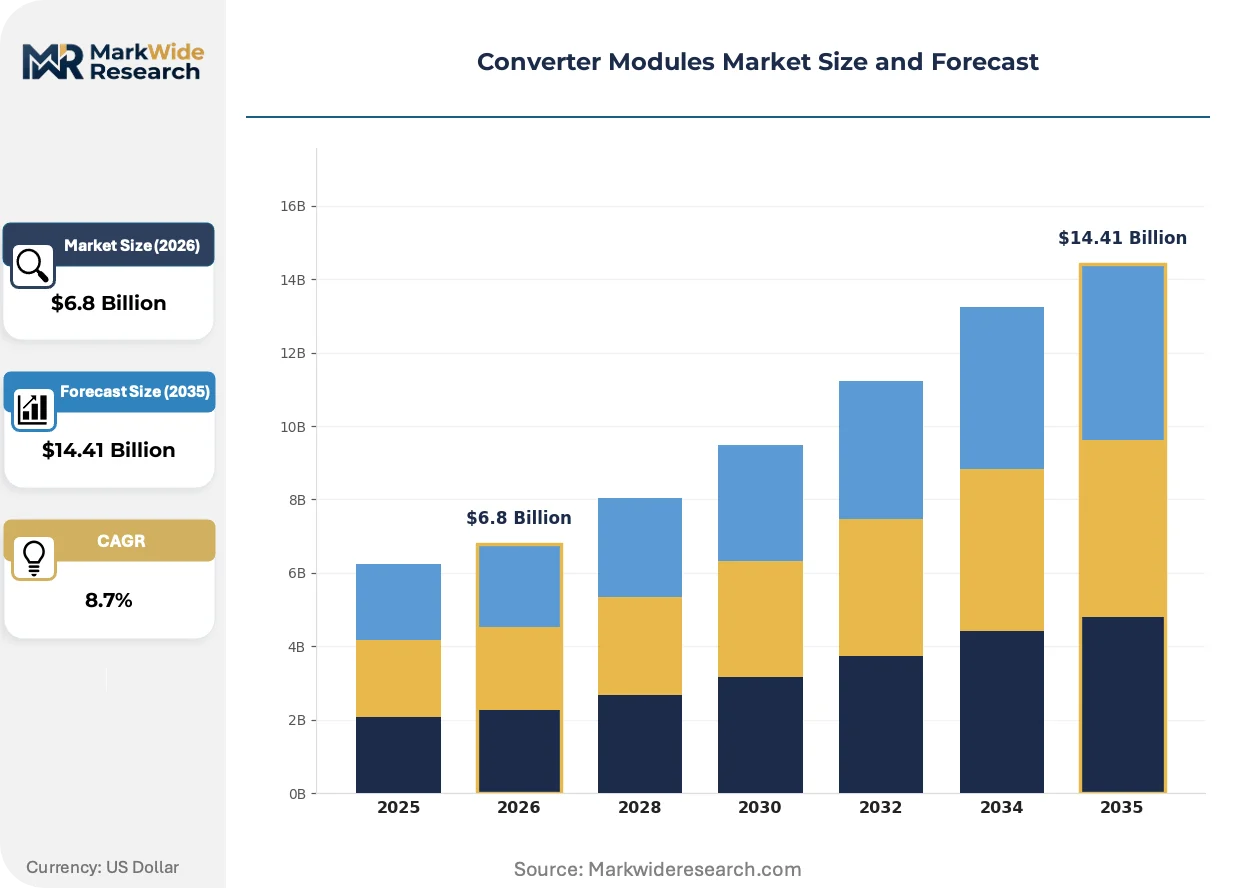
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: AC-DC Converters, DC-DC Converters, DC-AC Converters, Isolated Converters Technology: Analog Technology, Digital Technology, Power-Over-Ethernet, Switch Mode Technology End User: Telecommunications, Industrial Automation, Renewable Energy, Automotive Sector Installation: On-Premises, Rack-Mounted, Embedded, Desktop |
| Companies Covered | Vicor Corporation, Delta Electronics, Texas Instruments, Infineon Technologies, STMicroelectronics, ROHM Semiconductor, Analog Devices, TDK Corporation, Renesas Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Converter Modules Market Emerging Trajectories
Silicon carbide and gallium nitride wide-bandgap semiconductors are restructuring competitive positions by enabling megahertz switching frequencies that collapse passive component volumes. Three developments are compressing traditional design paradigms.
GaN-based active clamp flyback topologies are displacing quasi-resonant controllers in 65-150W adapter applications. Laptop and mobile device OEMs are adopting these designs at replacement cycle pace. The technology is displacing established magnetic component suppliers who lack high-frequency core material portfolios.
EPA ENERGY STAR Version 8.0 specifications for external power supplies tighten active-mode efficiency requirements at 25%, 50%, 75%, and 100% load points. Manufacturers must redesign front-end PFC stages and synchronous rectification controls. Consumer electronics and industrial gateway equipment categories face the steepest compliance cost gradients.
Direct rack-level battery backup integration is altering procurement patterns for data center operators. Traditional centralized UPS architectures are yielding to 48V DC distribution with lithium-ion battery strings collocated in server racks. North American hyperscale facilities and Nordic colocation campuses exhibit the most aggressive adoption timelines.
Converter Modules Market Segmentation
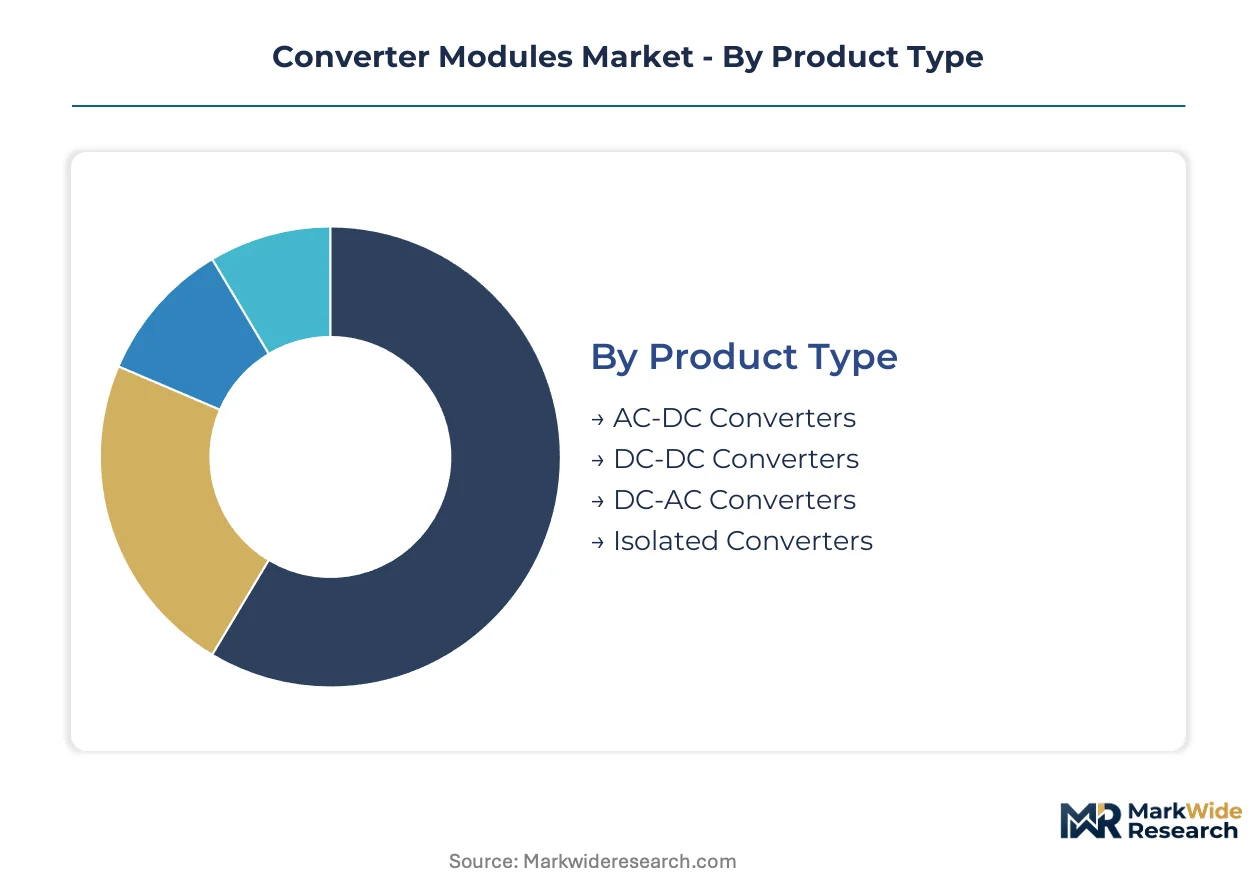
Converter module segmentation reveals how margin pools concentrate in voltage regulation granularity for AI workloads and isolation architectures for renewable integration. Suppliers configure product platforms around switching frequency, control topology, and thermal density to capture value across diverging end-use requirements.
Product Type:
DC-DC converters command the deepest margin pools as voltage regulation precision becomes critical for processor power rails, while AC-DC front ends face compliance cost pressures from efficiency mandates.
- AC-DC Converters:These modules transform alternating current from grid infrastructure into regulated direct current for electronic loads. Front-end PFC stages and synchronous rectification controls dominate redesign activity as EPA ENERGY STAR Version 8.0 tightens active-mode efficiency requirements at multiple load points.
- DC-DC Converters:Voltage level transformation between DC rails employs switch-mode topologies operating at hundreds of kilohertz to several megahertz. AI accelerator power rails below 0.5V at 1000A+ are mandating factorized power architectures in training clusters, concentrating procurement with suppliers offering vertical power delivery.
- DC-AC Converters:Inverter modules synthesize AC waveforms from DC sources for motor drives and grid-tied applications.
- Isolated Converters:Galvanic separation through transformers protects downstream equipment in renewable energy inverter applications and medical-grade power supplies.
DC-DC converters hold installed capacity. Isolated converters are rotating up the share rankings.
Technology:
Analog control loops retain volume leadership in cost-sensitive industrial installations, though digital architectures are capturing value in telecommunications and data center applications requiring telemetry and remote configurability.
- Analog Technology:Continuous feedback control through operational amplifiers and PWM comparators delivers deterministic response in motor drive and industrial automation contexts. Mature magnetics design practices and established safety certifications preserve this technology's position in legacy equipment refresh cycles.
- Digital Technology:Microcontroller-based state machines enable adaptive compensation, firmware-upgradable features, and integrated telemetry reporting. Complex verification requirements with safety agencies extend certification timelines, filtering suppliers lacking firmware validation expertise.
- Power-Over-Ethernet:Integrated power and data delivery through standard Ethernet cabling targets IP cameras, wireless access points, and IoT edge devices.
- Switch Mode Technology:High-frequency switching with inductive energy storage dominates unit volume across all commercial converter categories.
Analog technology anchors current revenue. Digital technology is climbing the fastest as remote management requirements proliferate.
End User:
Telecommunications and data center operators drive specification intensity through compressed power delivery architectures, while automotive electrification opens new isolated DC-DC categories for bidirectional charging.
- Telecommunications:Base station power systems and central office rectifiers demand high reliability and remote configurability. Rack-mounted 48V distribution with lithium-ion battery backup is displacing centralized UPS architectures in facilities across North America and Nordic colocation campuses.
- Industrial Automation:Motor drives, programmable logic controllers, and robotic systems require ruggedized converters with extended temperature ranges. Switch mode technology dominates unit volume in factory floor installations where deterministic control response takes priority over telemetry features.
- Renewable Energy:Solar inverters and wind turbine power conditioning rely on isolated converter variants for galvanic separation protecting grid-tied equipment.
- Automotive Sector:Electric vehicle onboard chargers and DC-DC stages for auxiliary systems create new specification categories as vehicle-to-grid integration requires bidirectional power flow.
Telecommunications holds installed capacity. Automotive sector is gaining share fastest as electrification accelerates power electronics content per vehicle.
Installation:
Rack-mounted configurations concentrate value capture in hyperscale data center buildouts, while embedded modules face thermal density constraints as power delivery compresses toward processor packages.
- Rack-Mounted:Standardized 19-inch chassis housings accommodate hot-swappable redundant configurations for data center and telecommunications central office applications. Direct battery backup integration at the rack level is altering procurement patterns as operators eliminate intermediate voltage rails.
- Embedded:Compact modules mount directly on printed circuit boards within server sleds, industrial controllers, and automotive power distribution units. Thermal and magnetic component relocation into confined spaces forces magnetics design specialization in planar transformer winding optimization.
- On-Premises:Standalone enclosures for facility-scale power conditioning and backup systems.
- Desktop:External power supplies for consumer electronics and laboratory equipment face steep compliance cost gradients from EPA and EU efficiency mandates.
Rack-mounted configurations hold installed capacity. Embedded modules are rotating up the share rankings as power delivery architectures compress toward processor packages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances are tilting toward net surplus positions in Asian manufacturing hubs while advanced economies deepen reliance on specialized converter imports for data center and automotive applications.
United States
Hyperscale cloud infrastructure buildouts in Northern Virginia and Oregon are driving procurement of high-density DC-DC modules for AI training clusters. EPA ENERGY STAR Version 8.0 mandates are tightening efficiency thresholds for external power supplies across consumer electronics categories. Phoenix and Dallas-Fort Worth metro areas are concentrating rack-mounted converter deployments as secondary data center markets expand.
China
Domestic semiconductor foundry expansion in Shanghai and Hefei is accelerating captive sourcing of precision power converters for lithography equipment. MIIT efficiency classifications under GB standards are creating parallel compliance tracks for modules serving domestic versus export equipment markets. Yangtze River Delta manufacturing clusters are consolidating magnetics supply chains for AI accelerator power delivery systems.
Germany
Industrial automation modernization across Baden-Württemberg and Bavaria is sustaining demand for ruggedized AC-DC converters in motor drive applications. EU Ecodesign Directive standby power limits below 0.5W are filtering non-compliant module suppliers from European distribution channels. Stuttgart automotive electronics corridor is expanding isolated DC-DC sourcing for electric vehicle onboard charger platforms.
Japan
Telecommunications infrastructure upgrades in Tokyo and Osaka are requiring remote-configurable rectifiers with integrated telemetry capabilities. METI efficiency programs are accelerating displacement of analog control loops with digital architectures in central office power systems. Nagoya industrial belt maintains concentration in ferrite and powder core materials for high-frequency magnetic components.
India
Data center construction in Mumbai and Bengaluru is attracting module assembly investments under PLI scheme incentives for electronics manufacturing. Central Electricity Authority regulations are harmonizing power quality standards for grid-tied converter installations. Delhi-NCR corridor is emerging as a secondary hub for rack-mounted configurations serving domestic cloud infrastructure demand.
Converter Modules Market Vendor Landscape
Listed leaders compete with private specialists across technology licensing and magnetics integration dimensions. The vendor base clusters around three tiers: diversified semiconductor conglomerates with broad converter portfolios, power-focused specialists with proprietary architectures, and component suppliers extending into module assembly. Two strategic archetypes dominate competitive positioning—suppliers with backward integration into magnetic materials and those with digital control firmware capabilities. M&A activity concentrates on GaN device startups and planar transformer design houses, while capacity expansion targets India and Vietnam for tariff-advantaged assembly.
Among US-based power specialists, Vicor Corporation exemplifies the high-density vertical delivery archetype through its factorized power architecture positioning. Delta Electronics, a Taiwan-based Co., Ltd., anchors the integrated magnetics-and-thermal tier with in-house control over core component supply. Texas Instruments represents the digitally controlled converter segment, extending telemetry-enabled portfolio breadth across industrial and telecommunications applications.
| Leading Market Players |
|---|
| Vicor Corporation |
| Delta Electronics |
| Texas Instruments |
| Infineon Technologies |
| STMicroelectronics |
| ROHM Semiconductor |
| Analog Devices |
| TDK Corporation |
| Renesas Electronics Corporation |
| Others |
Supply Flow & Price Mechanics
Wide-bandgap semiconductor substitution for silicon MOSFETs is simultaneously shifting procurement geography toward Asian foundry clusters and compressing pricing economics across efficiency tiers. This materials transition collapses passive component volumes while elevating qualification costs that stratify supplier tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with volume-scaled pricing stratifying across premium, standard, and economy tiers. Price differentiation rests on certification level — UL/CE marking tiers versus unqualified alternatives — and customization depth for magnetics integration. Cost compression in standard-tier modules is intensifying because GaN device qualification timelines extend development cycles without commensurate efficiency premiums. Hyperscale data center operators exhibit lowest price sensitivity due to thermal density requirements, while consumer electronics OEMs face steep compliance cost gradients from EPA and EU mandates.
Supply Chain Analysis
Ferrite core supply from Nagoya industrial belt underwrites high-frequency magnetic component availability for megahertz switching applications. Manufacturing concentrates in China, Taiwan, and Japan with raw material dependencies on rare-earth ferrite powders, copper magnet wire, and ceramic substrates. Single-source vulnerability concentrates in Japanese specialty ceramic producers for powder core materials. Distribution runs through authorized distributor networks serving industrial automation and telecommunications verticals with consolidated logistics hubs in Shenzhen and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetics design specialization scarcity constrains product development velocity, with planar transformer winding optimization and integrated inductor-heat sink co-design skills commanding premium compensation across the vendor base.
For Market Incumbents: Compound backward integration into magnetic materials to secure ferrite and powder core supply against Japanese and Chinese ceramic producer concentration. Add certification investment in dual GB standards and EU CE marking architectures to preserve market access without fragmenting product platforms. Defensive positioning against GaN device startups requires accelerated reliability testing partnerships to compress 18-24 month qualification timelines. For New Entrants and Emerging Players: Lead with digitally controlled converter architectures targeting India's PLI scheme-attracted data center buildouts in Mumbai and Bengaluru. The vehicle-to-grid integration specification category offers penetrable white space as bidirectional onboard charger requirements outpace established automotive supplier capacity. Go-to-market execution should anchor in planar transformer design house acquisition or licensing to bypass magnetics engineering scarcity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed power electronics specialists holding proprietary factorized power architectures but lacking digital control firmware capabilities. Long-term viability across a 5-10 year window hinges on telemetry integration and remote configurability adoption in telecommunications and data center verticals. The signal to watch is EPA ENERGY STAR Version 8.0 compliance cost gradients forcing consolidation among external power supply module suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnetics | Captive ferrite core supply insulates against Nagoya ceramic producer concentration and input cost volatility. |
| Dual Certification Architecture Investment | Parallel GB standards and EU CE marking compliance preserves market access across China's domestic foundry expansion and European distribution channels. |
| GaN Device Qualification Acceleration | Compressed reliability testing timelines enable earlier product release against silicon alternatives in 65-150W adapter applications. |
| Planar Transformer Design House Acquisition | Magnetics engineering capability scarcity limits product development velocity without specialized winding optimization expertise. |
| India Assembly Footprint Expansion | PLI scheme incentives attract module assembly investments to serve domestic cloud infrastructure demand in Mumbai and Bengaluru. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across power electronics procurement, magnetics engineering, and semiconductor device qualification functions. Primary interviews with data center infrastructure planners, telecommunications rectifier procurement leads, automotive power electronics engineers, and industrial automation OEM sourcing managers combined with secondary validation from EPA ENERGY STAR filings, MIIT GB standard documentation, EU Ecodesign Directive regulatory texts, and customs trade data for ferrite core and wide-bandgap semiconductor imports. Bottom-up unit economics triangulated against top-down market sizing across voltage regulation granularity tiers.
Across the analysis window, the analytical framework modeled segmentation dimensions including converter topology, control architecture, isolation requirement, switching frequency tier, and end-use vertical intensity. CAGRs derived from installed base replacement cycles, efficiency mandate compliance deadlines, and AI accelerator power rail proliferation trajectories. Forecast inputs incorporated hyperscaler capex disclosures for data center buildouts, semiconductor lithography equipment procurement patterns, and electric vehicle onboard charger content per vehicle trends.
Forecasts assume regulatory continuity in EPA efficiency programs, EU Ecodesign Directive standby power limits, and China MIIT efficiency classifications; material policy shifts would require re-modeling across compliance cost gradients and dual-certification architecture viability. Practitioners should keep alternative scenarios live as GaN device qualification standardization and solid-state transformer convergence timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Inverter Market
Power Systems
Pulse Generator Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Grid Forming Inverters Market
Power Systems
Shunt Reactor Market
Power Systems
Global Chip Power Inductor Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Global Plasma Generators Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
Voltage Stabilizer System Market
Power Systems
Power Diode Market
Power Systems
Global Flexible Batteries Market
Power Systems
Solid State Power Controller Market
Power Systems
Solid-State Relay and Fuse Box Component Platforms Market
Power Systems
Wireless Battery Monitoring System Market