
 Three-Phase String Inverter Market | 2026-2036
Three-Phase String Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
Three-Phase String Inverter Market Insights
Modular inverter packaging is expanding buyer choice across commercial and utility segments. SMA Solar Technology AG leverages its European manufacturing footprint to sustain premium positioning in grid-tied configurations. Huawei Technologies Co. Ltd. anchors its competitive stance through integrated smart-inverter platforms with embedded monitoring. Sungrow Power Supply Co. Ltd. competes aggressively on cost-engineered solutions for emerging-market utility projects.
Three-phase string inverters convert DC photovoltaic output into three-phase AC power at voltages typically spanning 400–800 V, with rated capacities from 10 kW to 250 kW serving commercial rooftops and utility-scale arrays. Grid-tied technology dominates installed base economics where feed-in tariffs or net-metering regimes apply, while smart inverters with reactive-power capability and ride-through functions represent the fastest-growing technology segment as grid codes tighten. Utility providers command the largest end-user volume pool, though commercial establishments offer higher margin per megawatt due to project complexity and service bundling.
Grid interconnection standards from IEEE 1547 in the United States, CE marking under Europe's Low Voltage Directive, and India's CEA technical standards for connectivity shape product certification requirements and market access timelines. Germany's KBA and France's national energy regulator enforce evolving efficiency benchmarks that manufacturers must meet for system eligibility. Stakeholders should monitor how distributed energy resource aggregations and dynamic tariff structures reshape inverter specification priorities across key procurement channels.
Market Dynamics
Grid-code tightening across major solar markets is forcing three-phase string inverter manufacturers to embed reactive-power control and fault-ride-through capability as baseline features rather than premium add-ons.
Growth Catalysts
- EU Green Deal efficiency mandates:Conversion-loss thresholds under the European Commission's framework are pushing procurement toward next-generation topologies.
- Utility-scale solar farms in India:CEA technical standards for grid connectivity are accelerating replacement cycles in existing installations.
- Smart-inverter platforms:Embedded monitoring and predictive maintenance capabilities are compressing operational expenditure for commercial rooftop operators.
Market Restraints
- IGBT and silicon carbide supply concentration:China's semiconductor foundries control critical power-electronics substrate capacity, creating input-cost volatility.
- BIS certification timelines:India's Bureau of Indian Standards testing backlog extends product launch windows by six to nine months.
- Central inverter substitution:Large-scale utility projects above 100 MW increasingly favor centralized architectures over string configurations.
Strategic Opportunities
- Brazil's distributed generation framework:Net-metering expansion in Minas Gerais and São Paulo states is opening commercial rooftop demand.
- Dynamic tariff structures:Time-of-use pricing in Germany's industrial solar corridor is creating pull for storage-ready inverter configurations.
- Power-electronics and battery convergence:Hybrid inverters combining PV conversion with DC-coupled storage are penetrating commercial segments.
Industry Challenges
- Power-electronics engineering talent scarcity:Specialist design capabilities for wide-bandgap semiconductor integration remain concentrated in Germany and China.
- Multi-jurisdiction certification burden:Simultaneous IEEE 1547, CE marking, and CEA compliance creates redundant testing expenditure.
- Legacy SCADA integration complexity:Retrofitting smart-inverter communication protocols into existing utility monitoring systems requires custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three-Phase String Inverter Market |
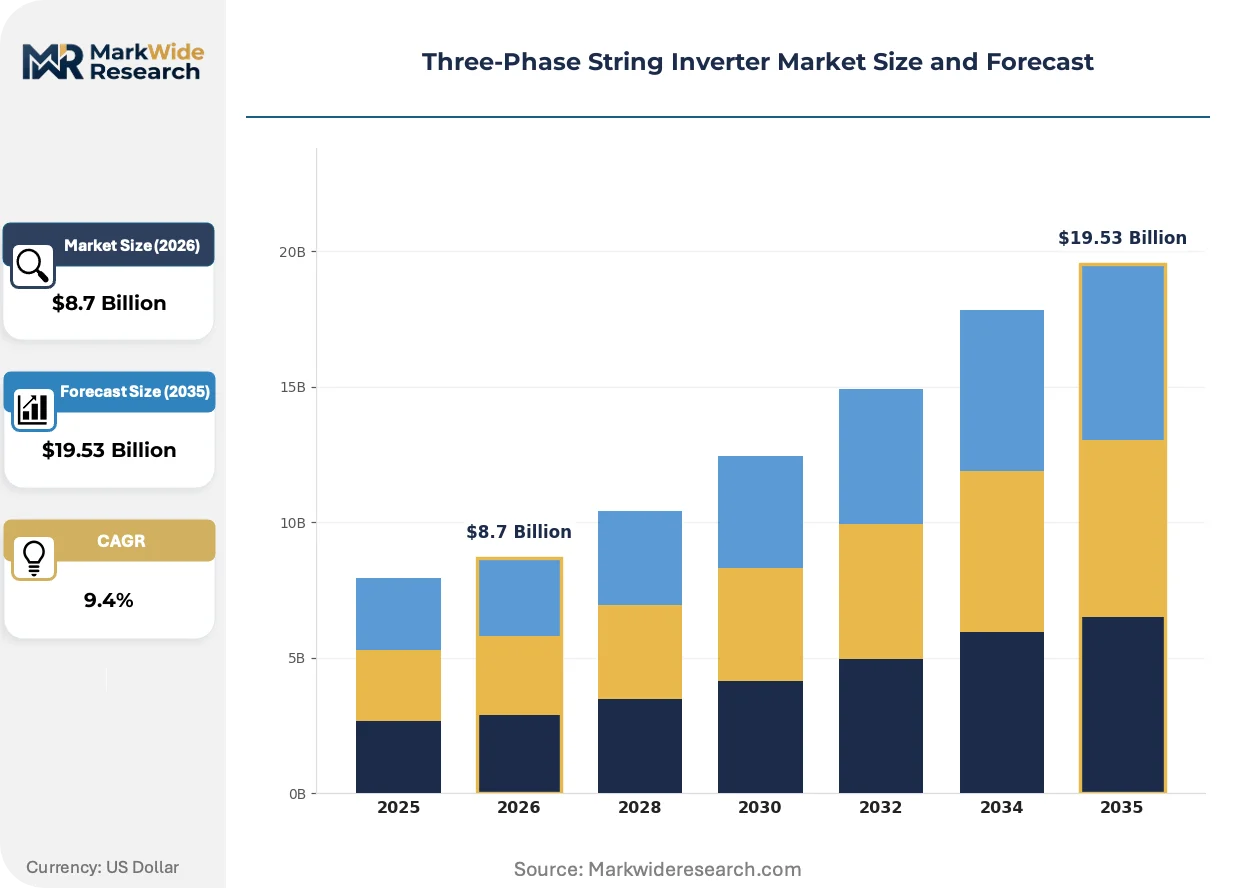
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Central Inverters, Modular Inverters, Micro Inverters, Hybrid Inverters Technology: Grid-Tied, Off-Grid, Battery-Based, Smart Inverters End User: Residential Users, Commercial Establishments, Utility Providers, Industrial Facilities Installation Type: Roof-Mounted Systems, Ground-Mounted Systems, Building Integrated, Floating Solar |
| Companies Covered | SMA Solar Technology AG, Huawei Technologies Co. Ltd., Sungrow Power Supply Co. Ltd., ABB Ltd., Fronius International GmbH, SolarEdge Technologies Inc., Ginlong Technologies Co. Ltd., Chint Power Systems, Ingeteam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three-Phase String Inverter Market Trends and Innovations
Silicon carbide power semiconductors and AI-driven predictive algorithms are compressing inverter form factors while expanding grid-support functionality. These shifts are redefining competitive differentiation beyond raw conversion efficiency.
Silicon carbide MOSFETs replace traditional silicon IGBTs in high-frequency switching applications, cutting thermal losses by one-third. Utility-scale developers in India and Brazil are specifying SiC-based units for 150 kW-plus installations despite 15-20% capital-cost premiums. This transition is electrifying demand for domestic module-assembly capacity outside China's manufacturing clusters.
CE marking under Europe's Low Voltage Directive now mandates cyber-resilience testing for grid-tied inverters with remote-monitoring capability. Manufacturers must demonstrate encrypted firmware-update channels and intrusion-detection systems to maintain market access. Germany's KBA and France's national energy regulator are enforcing these provisions most aggressively, compressing certification timelines for European-sourced supply.
Asset-management contracts are displacing equipment-only sales in commercial segments above 500 kW. Developers in Germany's industrial solar corridor now procure inverter functionality through performance-guarantee arrangements with ten-year service bundles. This restructuring concentrates vendor selection criteria on predictive-maintenance capability and spare-parts logistics rather than upfront capital cost.
Three-Phase String Inverter Market Segmentation
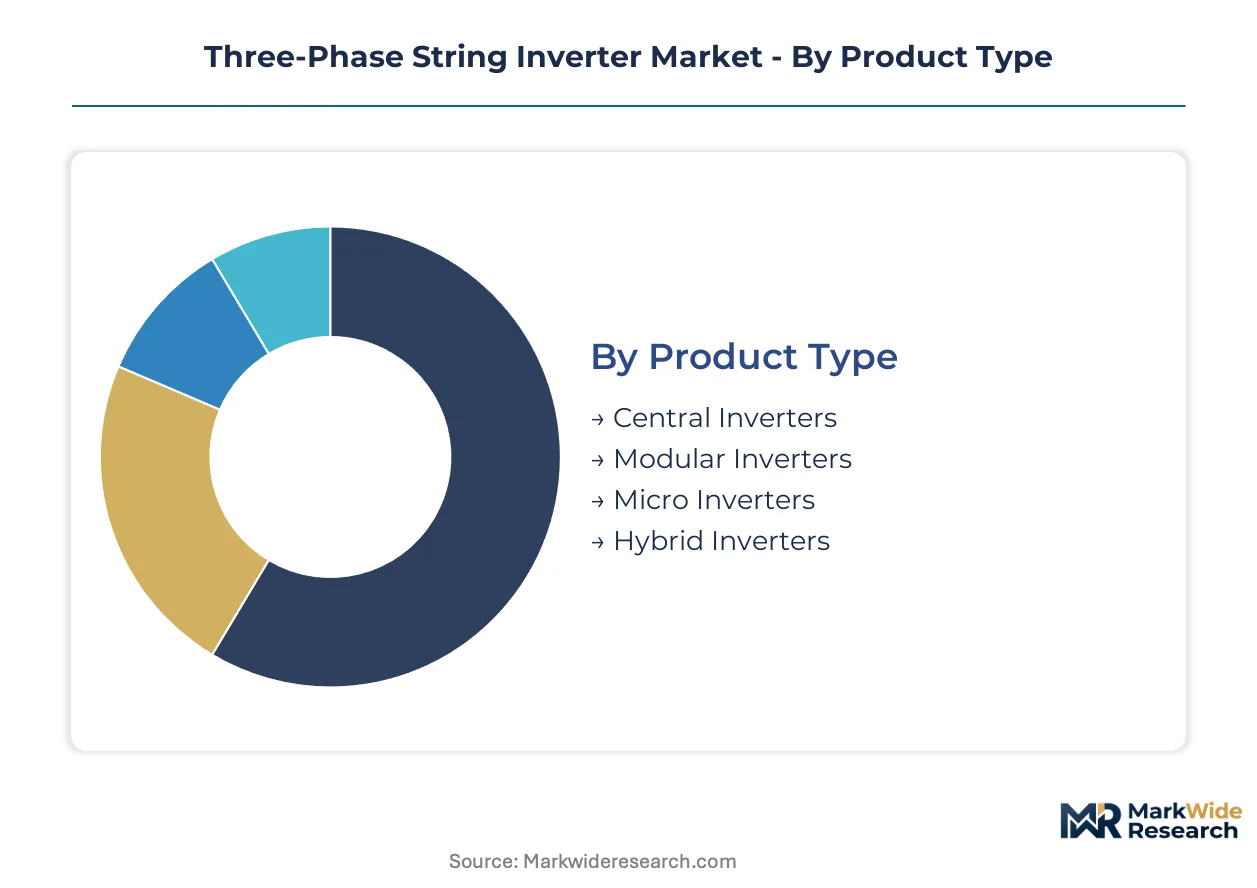
Three-phase string inverter procurement splits sharply between cost-engineered utility volumes and premium-featured commercial installations. Segment boundaries increasingly blur as hybrid architectures and smart-grid functionality become baseline requirements across voltage classes.
Product Type:
Volume concentration favors standardized architectures, while premium capture attaches to modular and hybrid configurations with embedded storage compatibility.
- Central Inverters:These units aggregate DC inputs from multiple strings into single conversion stages, typically rated above 250 kW. Utility-scale solar farms in India specify central architectures for installations exceeding 100 MW, though string substitution is eroding share in the 50-100 MW range.
- Hybrid Inverters:Combining PV conversion with DC-coupled battery integration, these systems enable time-shifting and grid-ancillary services. Germany's industrial solar corridor drives specification of storage-ready hybrids as dynamic tariff structures reward dispatch flexibility.
- Modular Inverters:Swappable power-stage designs reduce maintenance downtime for commercial rooftops above 500 kW.
- Micro Inverters:Panel-level conversion sees limited three-phase application, restricted to complex rooftop geometries with shading challenges.
Mature deployment sits with central inverters. Newer deployment is concentrated in hybrid configurations.
Technology:
Application context determines technology selection, with grid-interconnection standards and tariff structures driving specification divergence.
- Grid-Tied:Synchronous connection to distribution networks dominates installed economics where net-metering or feed-in tariffs apply. CE marking under Europe's Low Voltage Directive and India's CEA technical standards mandate reactive-power capability and fault-ride-through functions as baseline features.
- Smart Inverters:Embedded monitoring, predictive algorithms, and cyber-resilience protocols define this segment. IEEE 1547 compliance in the United States and encrypted firmware-update requirements under EU cyber-resilience testing are accelerating replacement of legacy units.
- Battery-Based:DC-coupled storage integration serves off-grid and backup-power applications in Brazil's distributed generation framework.
- Off-Grid:Standalone systems without grid interconnection apply to remote industrial facilities and rural electrification projects.
Grid-tied technology anchors current installed base. Smart inverters are gaining share fastest as grid-code tightening accelerates upgrade cycles.
End User:
Margin structure inverts volume hierarchy, with commercial complexity commanding premium pricing per megawatt against utility procurement scale.
- Utility Providers:Centralized procurement of 150 kW-plus units for ground-mounted solar farms drives volume concentration. Developers in India and Brazil specify silicon carbide-based topologies for conversion-loss reduction despite capital-cost premiums.
- Commercial Establishments:Rooftop and carport installations between 100 kW and 2 MW generate highest margin per megawatt through service bundling and performance guarantees. Asset-management contracts with ten-year maintenance bundles now displace equipment-only sales in Germany's industrial solar corridor.
- Industrial Facilities:C&I self-consumption models prioritize power-quality and ride-through capability for manufacturing continuity.
- Residential Users:Three-phase residential application remains limited to large estates and multi-dwelling units in European markets.
Utility providers command volume leadership. Commercial establishments concentrate margin capture.
Installation Type:
Mounting configuration directly shapes inverter environmental protection ratings, cooling requirements, and accessibility for maintenance.
- Ground-Mounted Systems:Utility-scale arrays on dedicated land parcels accommodate higher-capacity string inverters with passive cooling designs. India's CEA technical standards for connectivity and earthing apply most stringently to ground-mounted installations above 10 MW.
- Roof-Mounted Systems:Commercial and industrial building applications demand compact form factors, reduced weight, and rapid shutdown compliance. Brazil's net-metering expansion in Minas Gerais and São Paulo states is opening commercial rooftop demand for 30-100 kW string configurations.
- Floating Solar:FPV installations on reservoirs and quarry lakes require enhanced humidity protection and corrosion-resistant enclosures.
- Building Integrated:BIPV applications with facade-embedded modules impose stringent aesthetic and thermal constraints on inverter placement.
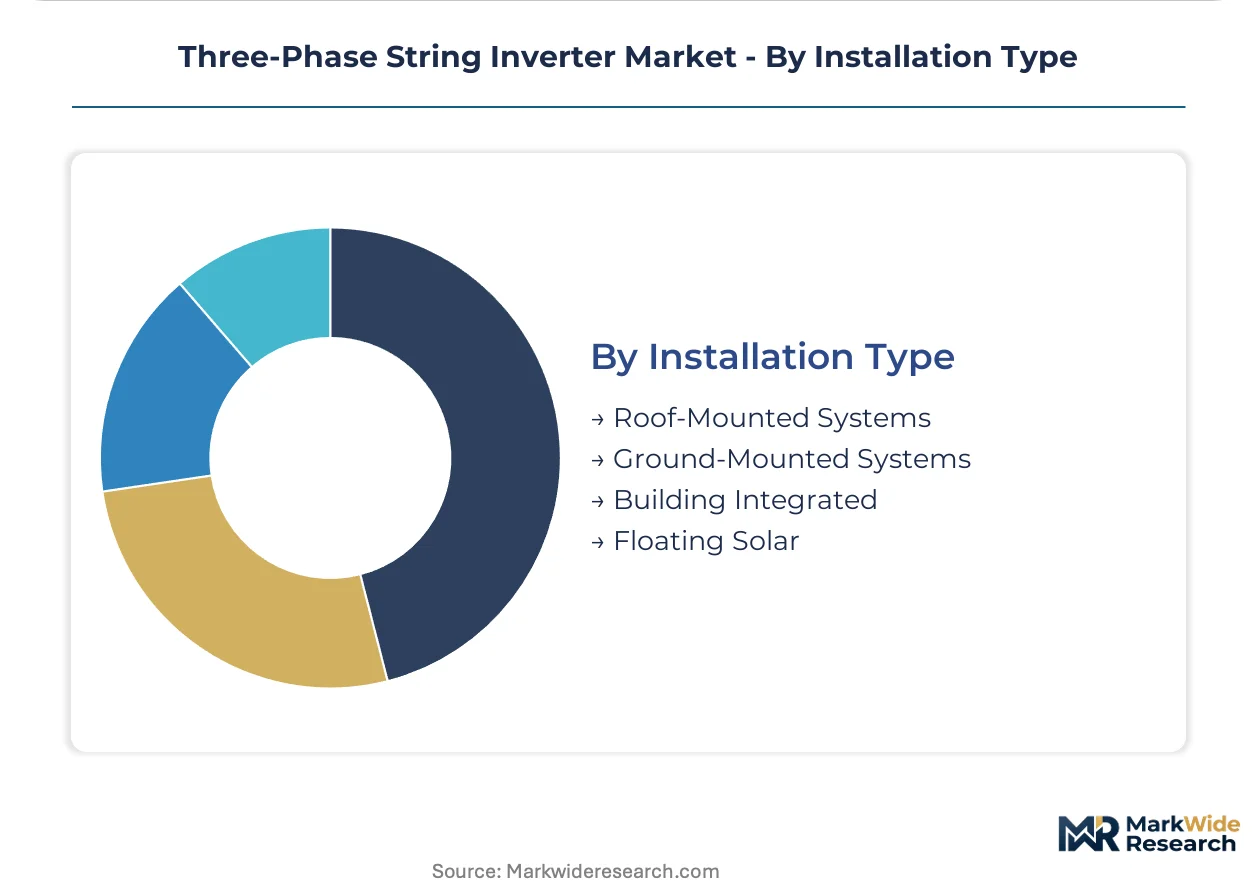
Ground-mounted systems anchor utility-scale deployment. Rooftop-mounted configurations are expanding most quickly in commercial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's solar parks and special economic zones are concentrating utility-scale procurement of three-phase string inverters as state-level renewable purchase obligations tighten. Manufacturing clusters in China and Germany's industrial corridor anchor supply-side capacity for high-efficiency units.
India
Gujarat and Rajasthan host the country's largest solar parks above 500 MW capacity. The Central Electricity Authority mandates reactive-power capability and fault-ride-through functions for all grid-tied installations. Manufacturing activity clusters in Pune and Bengaluru for power-electronics assembly serving domestic project pipelines.
Germany
Bavaria's industrial solar corridor drives specification of storage-ready hybrid inverters for commercial rooftops. The Kraftfahrt-Bundesamt enforces cyber-resilience testing for remote-monitoring capability under EU Green Deal efficiency mandates. Erfurt and Dresden host specialized engineering talent for wide-bandgap semiconductor integration.
Brazil
Minas Gerais and São Paulo states are expanding net-metering frameworks for commercial distributed generation. ANVISA coordinates with national energy regulators on equipment certification timelines. Manufacturing presence concentrates in São Paulo state's industrial belt for regional supply.
China
Yangtze River Delta manufacturing clusters control silicon carbide substrate capacity for next-generation power semiconductors. The Ministry of Industry and Information Technology oversees dual carbon goals driving domestic efficiency standards. Shenzhen and Hangzhou anchor integrated smart-inverter platform development.
United States
Texas and California utility-scale deployments specify IEEE 1547-compliant smart inverters with grid-support functions. FERC Order 2222 enables distributed energy resource aggregations reshaping procurement priorities. Phoenix and Austin host testing facilities for multi-jurisdiction certification compliance.
Three-Phase String Inverter Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: integrated technology platforms, cost-engineered volume suppliers, and premium European manufacturers with service bundling capabilities. Dominant competitive moves include geographic expansion into Brazil's distributed generation markets and portfolio diversification toward hybrid storage-ready configurations.
Among Germany-based manufacturers, SMA Solar Technology AG exemplifies premium positioning through European manufacturing footprint and extended service contracts. Huawei Technologies Co. Ltd. and Sungrow Power Supply Co. Ltd. represent divergent competitive approaches within Chinese supply, with the former anchoring integrated smart-platform development and the latter occupying cost-engineered utility-scale positioning. These three companies collectively illustrate how geographic origin and corporate structure shape strategic differentiation in grid-tied and smart-inverter segments.
| Leading Market Players |
|---|
| SMA Solar Technology AG |
| Huawei Technologies Co. Ltd. |
| Sungrow Power Supply Co. Ltd. |
| ABB Ltd. |
| Fronius International GmbH |
| SolarEdge Technologies Inc. |
| Ginlong Technologies Co. Ltd. |
| Chint Power Systems |
| Ingeteam |
| Others |
Pricing and Supply Chain Analysis
Utility-scale procurement mandates for silicon carbide-based topologies in India and Brazil are forcing supply-side reconfiguration toward wide-bandgap semiconductor capacity, compressing margins on legacy silicon IGBT configurations while extracting premiums for qualified SiC supply.
Pricing Analysis
Lead-time-driven pricing stratification separates spot inventory discounts from six-to-nine-month qualified supply premiums. Three-tier pricing structure across premium SiC-enabled, standard silicon IGBT, and economy refurbished tiers reflects certification grade differentiation under IEEE 1547 and CE marking. Cost compression in the standard tier intensifies because China's semiconductor foundries anchor substrate supply. Commercial rooftop operators demonstrate highest price sensitivity, while utility developers absorb capital-cost premiums for grid-code compliance.
Supply Chain Analysis
Single-source vulnerability sits with Yangtze River Delta silicon carbide substrate capacity, where China's MIIT oversees dual carbon goals driving domestic allocation priorities. Power-electronics assembly draws from Germany's Erfurt-Dresden corridor, India's Pune-Bengaluru clusters, and São Paulo state's industrial belt. Tariff exposure on semiconductor substrates creates input-cost volatility. Distribution runs through EPC contractor networks and direct utility procurement channels with ten-year service bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
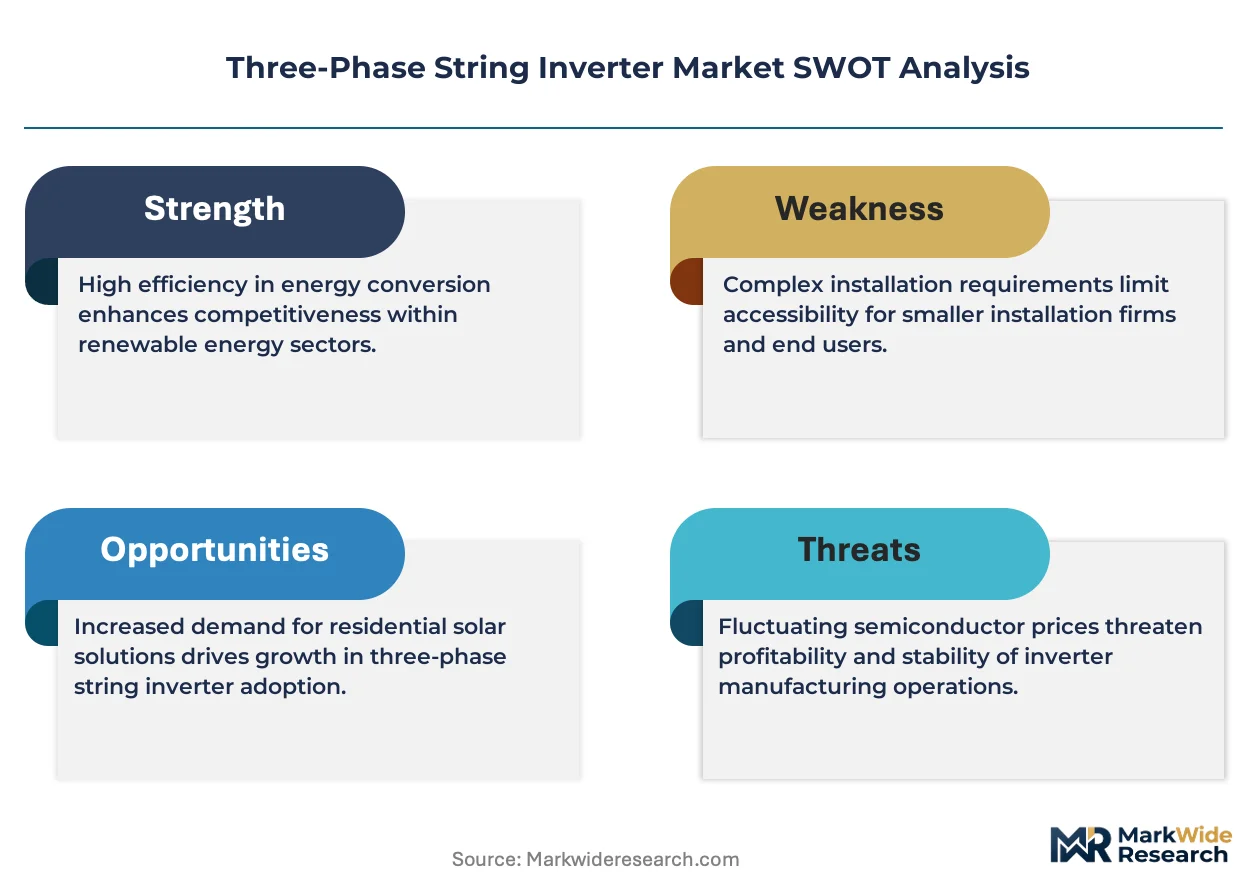
This market consolidates around integrated smart-platform capabilities as multi-jurisdiction certification burdens force sub-scale players toward exit or acquisition.
For Market Incumbents: Lock in grid-code compliance advantages by embedding predictive-maintenance algorithms and encrypted firmware channels ahead of EU cyber-resilience enforcement. Vertical integration into silicon carbide module assembly insulates against China's substrate allocation volatility. SMA Solar Technology AG and Huawei Technologies Co. Ltd. demonstrate how European manufacturing footprint and integrated platform development respectively defend positioning. For New Entrants and Emerging Players: AI-driven thermal management algorithms offer technology-first wedge into Brazil's distributed generation framework, where ANVISA certification timelines create incumbent vulnerability. Target commercial rooftop segments in Minas Gerais and São Paulo states with storage-ready hybrid configurations. Partner with regional EPC contractors for channel access rather than competing on utility-scale procurement. For Investors and Strategic Acquirers: Re-rating potential sits with power-electronics engineering specialists given silicon carbide integration capability scarcity. Long-term viability over the next decade hinges on backward integration into wide-bandgap semiconductor design or captive service contract portfolios. Watch India's CEA technical standard revision cycles as inflection indicators for replacement demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Module Assembly Capacity | Captive substrate processing reduces dependence on China's Yangtze River Delta foundries. |
| Cyber-Resilience Certification Investment | Encrypted firmware channels satisfy Germany's KBA and France's national energy regulator mandates. |
| Predictive Maintenance Platform Development | Asset-management contracts with ten-year bundles displace equipment-only sales in Germany's industrial corridor. |
| Brazil Distributed Generation Partnership | Net-metering expansion in Minas Gerais and São Paulo states opens commercial rooftop demand. |
| Hybrid Storage-Ready Configuration Launch | DC-coupled battery integration serves Germany's dynamic tariff structures and India's CEA grid-ancillary requirements. |
Research Methodology
Document review covered EIA project databases, IEA renewable energy reports, FERC interconnection filings, and CEA technical standards, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across India, Germany, Brazil, China, and the United States. Secondary validation drew from customs trade data, SEC 10-K disclosures, and national regulator certification records. Bottom-up installation data triangulated against top-down market sizing from equipment shipment tracking.
Historical capacity deployment patterns cross-referenced against panel input from industry stakeholders informed the analytical framework across the projection horizon. Segmentation modeling spanned product type, technology class, end-user category, installation configuration, and regional regulatory cluster. CAGRs derived from unit shipment trajectories and average selling price evolution, with silicon carbide adoption curves and grid-code tightening schedules as sector-specific inputs.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts on semiconductor substrates, unanticipated breakthroughs in central inverter architectures above 100 MW, and sovereign subsidy program suspensions. Forecasts reflect documented assumptions about efficiency mandate enforcement continuity and supply chain regionalization pace. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Harmonic Generators Market
Power Systems
Low Voltage DC Circuit Breaker Market
Power Systems
Asia Pacific Low Voltage Drives Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
Global Frequency Converter Market
Power Systems
High Voltage Ceramic Zinc Oxide Surge Arrester Market
Power Systems
Japan Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
Series Reactor Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
Telecom Power Systems Market
Power Systems
Europe Variable Frequency Drive Market
Power Systems
Space DC-DC Converters Market
Power Systems
BCD Power IC Market
Power Systems
MCR Based Static VAR Compensator Market