
 Powered Wheelchair Market | 2026-2036
Powered Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
Powered Wheelchair Market Analysis
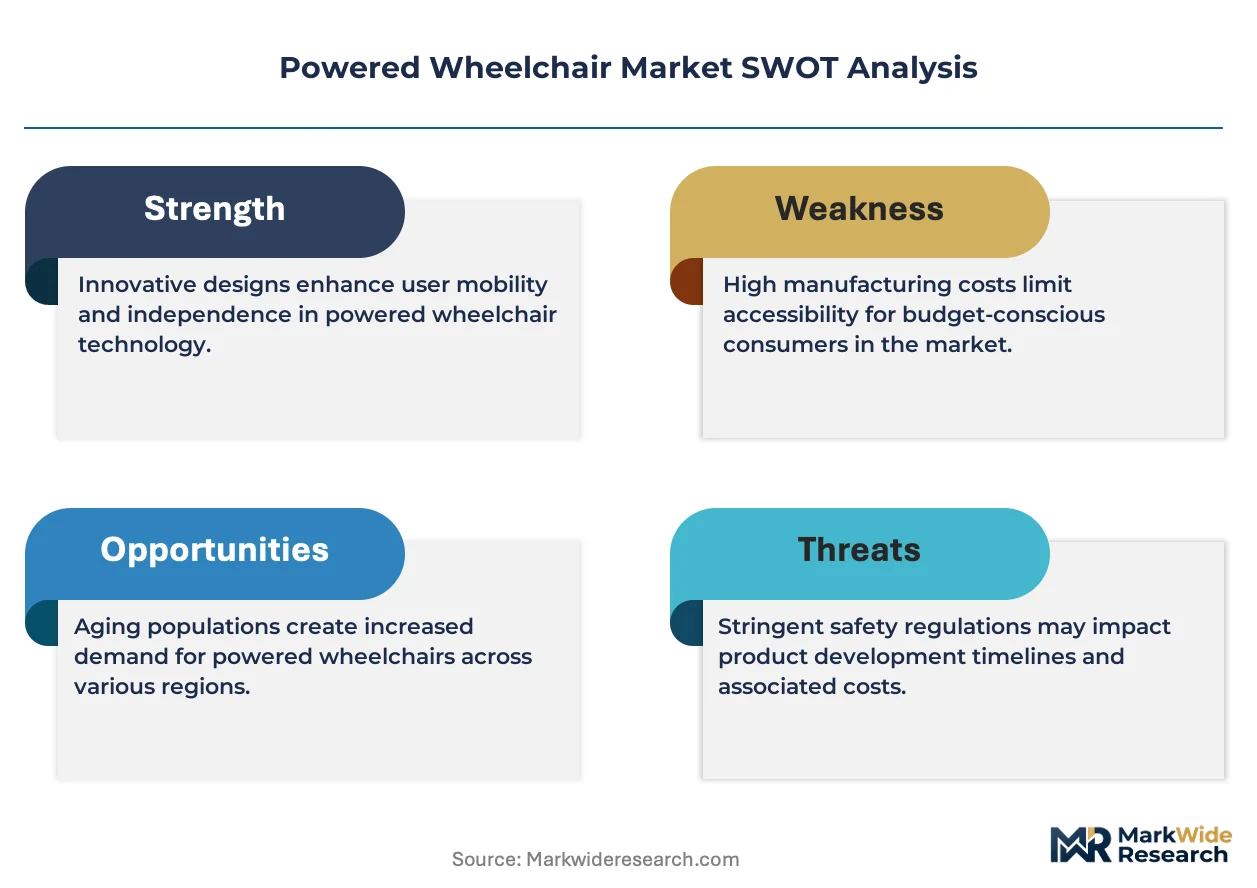
MDR compliance in Europe is recalibrating the cost-of-entry calculus for powered wheelchair manufacturers seeking CE marking. Permobil AB leverages its Swedish manufacturing base to sustain premium positioning across reimbursement-heavy Nordic markets. Sunrise Medical competes through broad portfolio coverage spanning pediatric to bariatric segments. Golden Technologies anchors its presence in North American retail channels with Medicare-contracted pricing structures.
A powered wheelchair is an electrically motorized mobility device incorporating battery packs, drive systems, and programmable control interfaces to enable independent locomotion for users with limited upper or lower limb function. These devices typically integrate dual-motor configurations, lithium-ion or lead-acid power cells, and customizable seating systems to accommodate diverse anatomical requirements and terrain conditions. Traditional wheelchairs retain the largest installed base due to established reimbursement codes and proven clinical acceptance, though standing wheelchairs command premium pricing through specialized pressure-relief and circulatory benefits. Gesture control technology represents the fastest-evolving interface category as sensor miniaturization reduces hardware costs for hands-free operation.
FDA 510(k) premarket notification requirements and the EU MDR clinical evaluation obligations collectively shape product development timelines and market access pathways for powered mobility manufacturers. ISO 7176 technical standards govern electromagnetic compatibility, dynamic stability, and fatigue testing protocols that determine commercial viability across regulated jurisdictions. Stakeholders must monitor evolving reimbursement thresholds from CMS and national health authorities, as coverage decisions directly gate addressable volume for advanced control technologies and standing configurations.
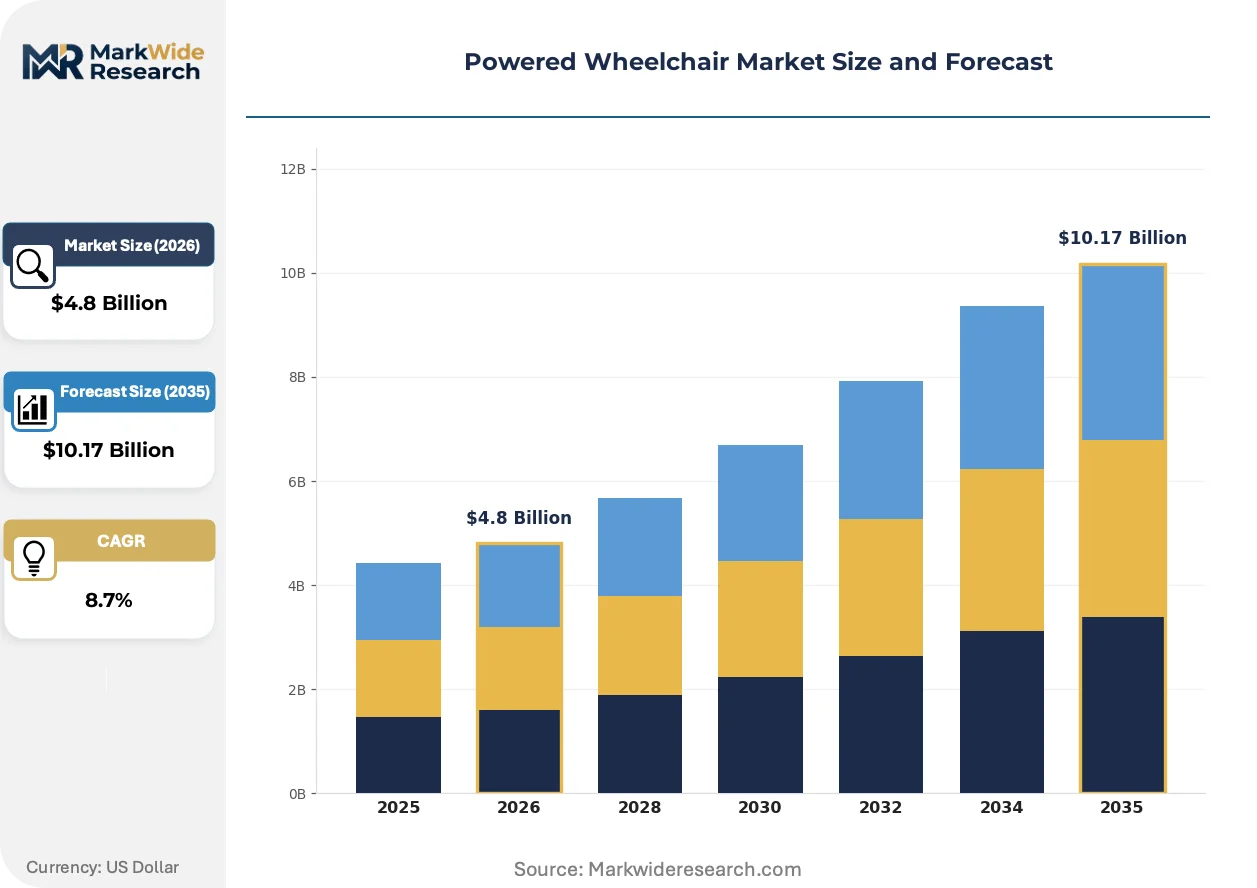
Market Dynamics
The powered wheelchair market is undergoing structural recalibration as FDA 510(k) clearance pathway revisions compress development timelines while EU MDR clinical evaluation obligations extend certification cycles, creating divergent regulatory arbitrage opportunities across jurisdictions.
Growth Catalysts
- Medicare reimbursement expansion:CMS coverage decisions for advanced control interfaces and standing configurations are unlocking institutional purchasing volumes across VA procurement programs and home healthcare networks.
- Lithium-ion battery chemistry maturation:Energy density improvements and cost curves in power cell technology are extending operational range and reducing total cost of ownership for daily-use devices.
- Aging demographic concentration:Cohort expansion among adults over 75 in the United States and Nordic markets is generating sustained replacement demand for independent living solutions.
Market Restraints
- Input cost volatility:Rare earth magnet and semiconductor shortages are pressuring motor assembly and programmable controller production economics.
- Supply concentration risk:Lithium-ion cell manufacturing concentrates in East Asian contract suppliers, exposing finished goods producers to tariff and logistics disruptions.
- Technical limitation:Gesture control sensor miniaturization has plateaued against power consumption constraints, delaying hands-free interface mainstreaming.
Strategic Opportunities
- Underpenetrated geography:India's PLI scheme for medical device manufacturing offers tariff-advantaged production positioning for export into Southeast Asian markets.
- Regulatory tailwind:The EU Green Deal circular economy mandates are creating preferential procurement status for repairable, upgradeable wheelchair architectures.
- Technology convergence:Integration of IoT connectivity with predictive maintenance algorithms is enabling subscription-based fleet management models for institutional buyers.
Industry Challenges
- Certification timeline compression:ISO 7176 electromagnetic compatibility testing bottlenecks are colliding with accelerated FDA 510(k) review schedules, squeezing launch windows.
- Talent scarcity:Rehabilitation engineering and assistive technology specialist shortages are constraining R&D throughput and clinical validation capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powered Wheelchair Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standing Wheelchairs, Sports Wheelchairs, Traditional Wheelchairs, All-Terrain Wheelchairs Technology: Joystick Control, Touchscreen Control, Gesture Control, Voice Control End User: Individuals with Disabilities, Elderly Users, Rehabilitation Centers, Hospitals Distribution Channel: Online Stores, Medical Supply Stores, Specialty Retailers, Direct Sales |
| Companies Covered | Invacare Corporation, Sunrise Medical, Permobil AB, Pride Mobility Products Corp., OttoBock Healthcare, MEYRA GmbH, Drive DeVilbiss Healthcare, Golden Technologies, Numotion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powered Wheelchair Market Emerging Trajectories
Gesture control interfaces and predictive connectivity are converging to redefine user interaction paradigms, while regulatory divergence between FDA and EU MDR pathways is fragmenting product development strategies.
Sensor fusion arrays combining accelerometers, gyroscopes, and capacitive proximity detectors are electrifying hands-free wheelchair navigation. Home healthcare providers are piloting these interfaces for users with progressive neuromuscular conditions, prioritizing retention of independent mobility. The technology is electrifying competitive differentiation, compressing hardware cost premiums from specialized positioning to standard feature inclusion.
The EU MDR clinical evaluation obligation is extending CE marking timelines for powered mobility devices, forcing manufacturers to front-load clinical evidence generation. This regulatory friction is diverting R&D budgets toward documentation and notified body engagement. Pediatric and bariatric segments face the steepest compliance burden, prompting portfolio rationalization toward higher-volume standard configurations.
Institutional procurement is consolidating through integrated health system contracts, displacing fragmented distributor relationships. Hospital networks and long-term care chains are centralizing assistive technology acquisition through single-source agreements with outcome-based service commitments. The United States exhibits the most pronounced consolidation, with Medicare Advantage plans driving standardization across affiliated provider groups.
Powered Wheelchair Market Segmentation
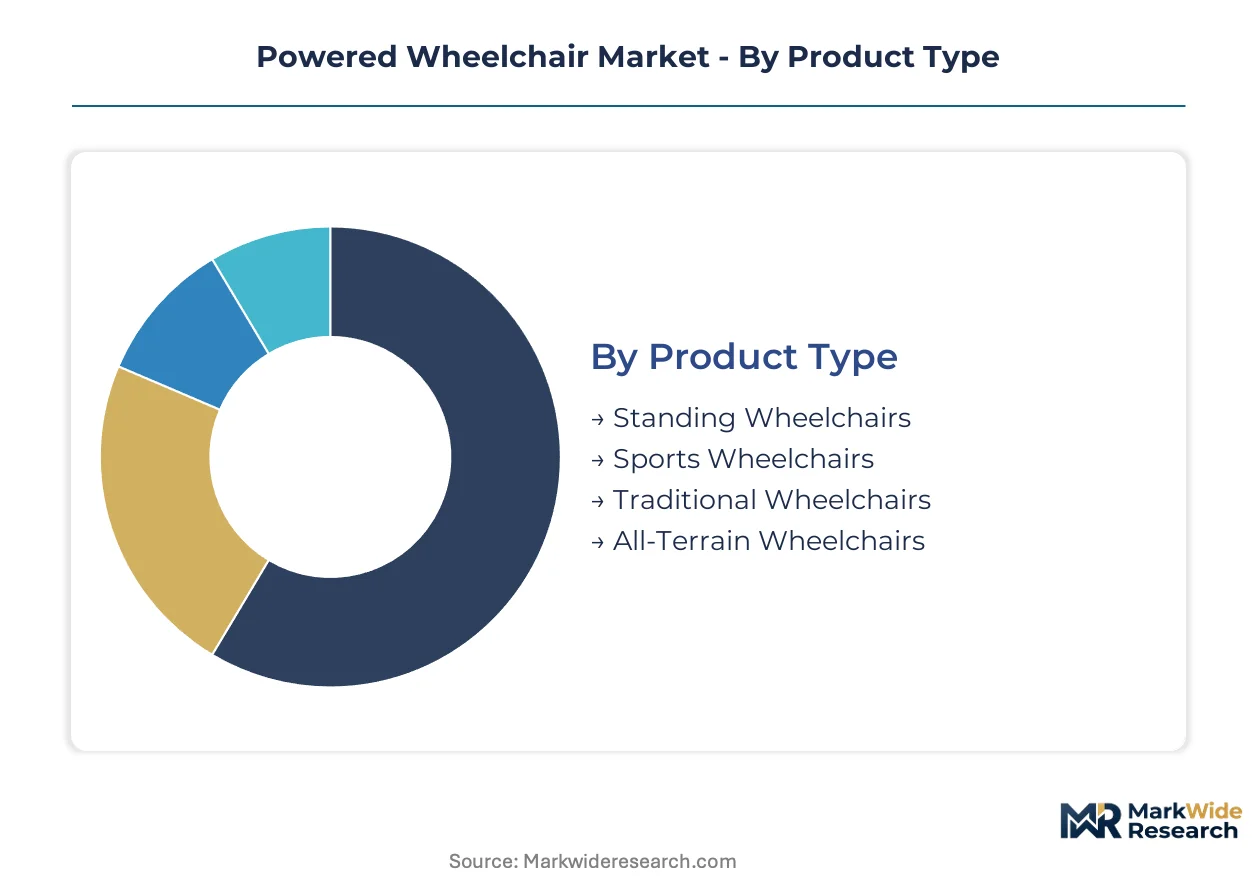
Powered wheelchair segmentation reveals divergent upgrade cycles across user populations. Clinical settings demand rapid technology refresh while individual users extend replacement intervals through component upgrades.
Product Type:
Replacement cycles vary dramatically by chassis architecture and reimbursement eligibility for whole-unit versus component upgrades.
- Traditional Wheelchairs:Dual-motor configurations with standardized seating systems constitute the installed base majority. Demand concentrates in United States Medicare networks and VA procurement channels where established reimbursement codes sustain predictable replacement scheduling for aging cohorts.
- Standing Wheelchairs:Hydraulic or electromechanical elevation mechanisms enable vertical positioning for pressure relief and circulatory benefit. Rehabilitation centers in Nordic markets prioritize these configurations for spinal cord injury protocols despite premium pricing tiers that limit individual purchaser penetration.
- Sports Wheelchairs:Lightweight carbon fiber frames with cambered wheel geometry optimize maneuverability for athletic competition.
- All-Terrain Wheelchairs:Extended-travel suspension and knobby tread patterns navigate unpaved surfaces for rural users.
Volume placements concentrate in Traditional Wheelchairs; the faster expansion belongs to Standing Wheelchairs.
Technology:
Control interface selection directly determines manufacturing cost structures and service revenue potential across distribution channels.
- Gesture Control:Sensor fusion arrays combining accelerometers, gyroscopes, and capacitive proximity detectors enable hands-free navigation. Home healthcare providers in United States pilot programs for progressive neuromuscular conditions prioritize retention of independent mobility as hardware costs compress toward standard feature inclusion.
- Joystick Control:Proportional electromechanical interfaces with programmable sensitivity curves dominate institutional procurement. Hospital networks standardize on these configurations for reliability metrics and technician familiarity that reduce training burden across rotating clinical staff.
- Touchscreen Control:Capacitive displays with customizable icon arrays serve cognitively intact users seeking intuitive menu navigation.
- Voice Control:Natural language processing modules integrate with environmental smart home systems for hands-free operation.
Joystick Control retains volume dominance; Gesture Control is climbing the fastest as sensor miniaturization advances.
End User:
Purchasing authority and reimbursement pathway shape product specification requirements across user categories.
- Elderly Users:Adults over 75 seeking independent living solutions drive replacement demand through Medicare Advantage plans and long-term care insurance riders. Nordic markets exhibit concentrated penetration where municipal home care subsidies reduce out-of-pocket exposure for daily-use device acquisition.
- Individuals with Disabilities:Congenital or acquired mobility limitations require customized seating and control configurations matched to specific anatomical presentations. United States vocational rehabilitation programs and private disability insurers fund these procurements with outcome-based independence metrics.
- Rehabilitation Centers:Outpatient and inpatient therapy facilities maintain fleet inventories for temporary patient use during recovery protocols.
- Hospitals:Acute care settings deploy bariatric-capable units for inpatient mobility with rapid-sanitization surface specifications.
Elderly Users generate the largest addressable volume; Individuals with Disabilities show the steepest technology adoption trajectory for advanced interfaces.
Distribution Channel:
Channel selection determines pricing transparency, service bundling, and regulatory documentation burden for manufacturers.
- Medical Supply Stores:Brick-and-mortar durable medical equipment dealers combine product demonstration with Medicare billing assistance. United States retail networks anchor regional market presence through contracted pricing structures that align with CMS reimbursement schedules.
- Direct Sales:Manufacturer-employed assistive technology specialists conduct home assessments and deliver customized fitting services. This channel captures complex seating configurations where clinical documentation requirements exceed standard retail capability.
- Online Stores:E-commerce platforms serve replacement part procurement and standardized model comparison for informed consumers.
- Specialty Retailers:Mobility-focused chains concentrate product selection for comparison shopping in metropolitan markets.
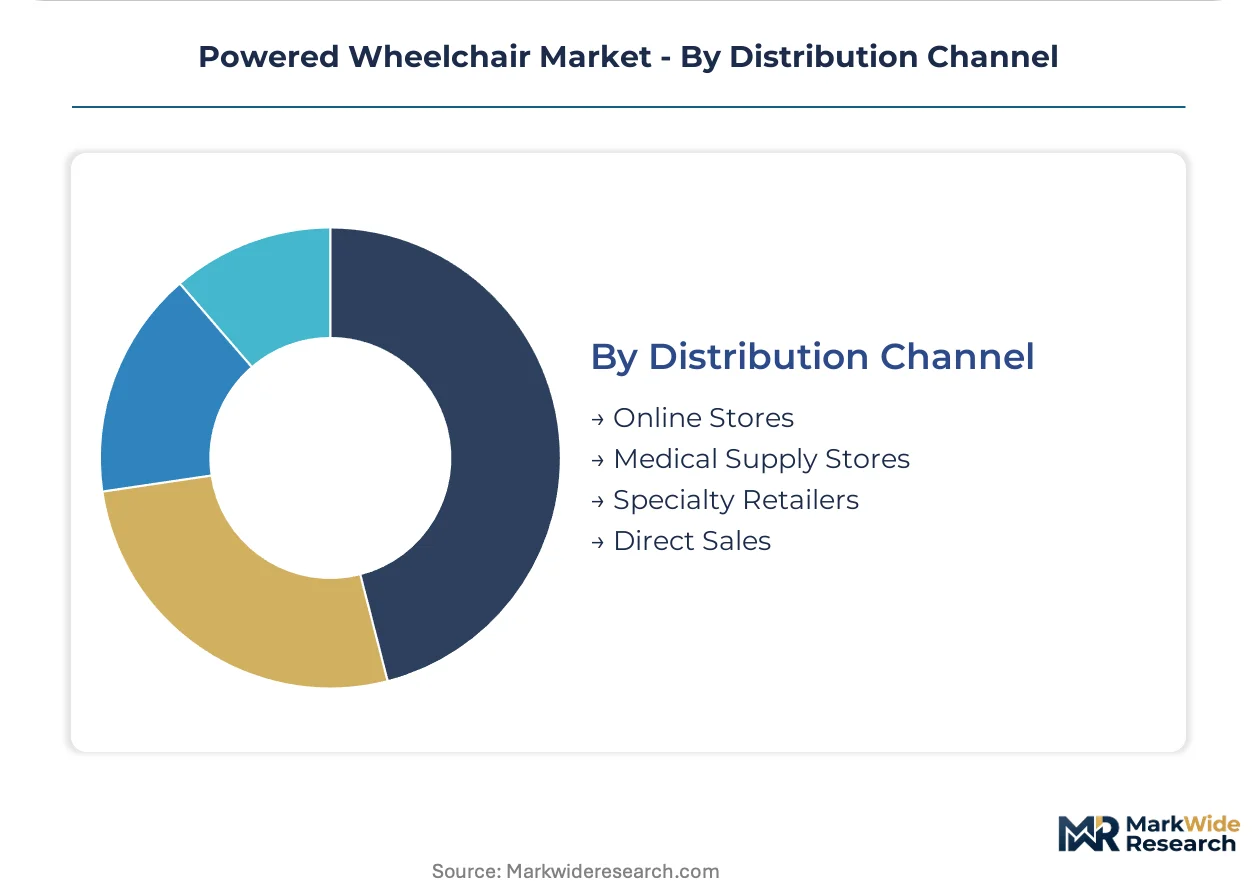
Medical Supply Stores handle the greatest transaction volume; Direct Sales is expanding most quickly for high-complexity configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized medical device zones in Sweden and the United States concentrate powered wheelchair manufacturing and R&D activity through targeted tax incentives and reimbursement infrastructure.
United States
Medicare Advantage expansion and VA procurement programs sustain institutional purchasing volumes for dual-motor configurations and advanced control interfaces. FDA 510(k) clearance pathway revisions compress development timelines while CMS coverage decisions gate addressable volume for standing configurations. The Ohio-Michigan industrial corridor hosts concentrated manufacturing and clinical validation facilities serving domestic distribution networks.
Germany
Rehabilitation engineering clusters and statutory health insurance reimbursement frameworks support premium product penetration across bariatric and pediatric segments. EU MDR clinical evaluation obligations extend CE marking timelines, forcing manufacturers to front-load documentation investments. The North Rhine-Westphalia medical technology belt anchors component supply and notified body engagement for continental market access.
Sweden
Municipal home care subsidies reduce out-of-pocket exposure for elderly users seeking independent living solutions with premium seating configurations. The country's national medical device regulator aligns with EU MDR implementation, sustaining Nordic market premium positioning. Stockholm-Uppsala medtech clusters concentrate rehabilitation engineering talent and clinical validation partnerships.
Japan
Super-aging demographic concentration generates replacement demand for gesture control interfaces and lithium-ion powered daily-use devices. METI standards harmonization with ISO 7176 protocols streamlines electromagnetic compatibility certification for domestic manufacturers. The Kanto region surrounding Tokyo hosts assistive technology R&D centers and hospital network procurement headquarters.
India
PLI scheme for medical device manufacturing offers tariff-advantaged production positioning for export into Southeast Asian markets. CDSCO regulatory alignment with international standards is accelerating import substitution for programmable controller assemblies. The Maharashtra-Gujarat industrial corridor concentrates contract manufacturing and lithium-ion cell integration facilities.
Powered Wheelchair Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across reimbursement-heavy and retail-channel segments. Market structure exhibits tiered consolidation with premium positioning anchored by Scandinavian manufacturers and volume penetration driven by North American distributors. Three archetypes dominate: integrated health system contractors, Medicare-anchored retail networks, and specialized rehabilitation engineering houses. Competitive moves concentrate on geographic licensing arrangements and component supply partnerships that secure battery chemistry and sensor fabrication access.
Among North American distributors, Golden Technologies and Pride Mobility Products Corp. exemplify Medicare-contracted pricing structures that anchor retail channel presence. Sunrise Medical occupies a position spanning pediatric to bariatric portfolio coverage. Swedish-based Permobil AB represents premium-tier positioning sustained through Nordic reimbursement infrastructure and specialized seating engineering.
| Leading Market Players |
|---|
| Invacare Corporation |
| Sunrise Medical |
| Permobil AB |
| Pride Mobility Products Corp. |
| OttoBock Healthcare |
| MEYRA GmbH |
| Drive DeVilbiss Healthcare |
| Golden Technologies |
| Numotion |
| Others |
Supply Flow & Price Mechanics
Captive lithium-ion cell integration anchors supply positioning and pricing power for finished goods producers navigating East Asian contract dependencies. Medicare reimbursement schedules and VA procurement thresholds compress margin elasticity for manufacturers serving United States institutional channels.
Pricing Analysis
Short lead-time premiums attach to standing wheelchair configurations with EU MDR clinical documentation complete, while spot inventory discounts concentrate in traditional dual-motor models with standardized seating. Three-tier pricing structure across premium standing configurations, standard traditional models, and economy basic mobility tiers separates reimbursement-eligible from retail-cash purchasers. Pricing pressure stems from rare earth magnet and semiconductor input cost volatility pressuring motor assembly economics. Home healthcare providers exhibit highest price sensitivity due to Medicare Advantage plan reimbursement ceilings; rehabilitation centers show lowest sensitivity given outcome-based independence metrics.
Supply Chain Analysis
Direct-to-health-system channels handle hyperscale demand from consolidated hospital networks and long-term care chains displacing fragmented distributor relationships. Lithium-ion cell manufacturing concentrates in China, South Korea, and Japan, exposing finished goods producers to tariff and logistics disruptions. Rare earth magnet and semiconductor dependencies feed from East Asian foundries and wafer fabs. Single-source vulnerability in programmable controller assemblies creates procurement risk. Distribution runs through Medicare-contracted medical supply stores anchoring United States retail presence alongside manufacturer direct sales for complex seating configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powered wheelchair market structure favors consolidation plays as EU MDR clinical evaluation obligations extend certification timelines beyond smaller manufacturer R&D capacity. Regulatory compliance burdens force portfolio rationalization toward higher-volume standard configurations.
For Market Incumbents: Lock in battery chemistry supply partnerships securing lithium-ion cell allocation and rare earth magnet sourcing before tariff escalations disrupt motor assembly economics. Deepen clinical validation partnerships with Stockholm-Uppsala medtech clusters to accelerate EU MDR documentation throughput. Gesture control sensor miniaturization plateaus create defensive moat for proprietary interface portfolios. For New Entrants and Emerging Players: E-commerce direct channels offer white-space penetration for replacement part procurement and standardized model comparison serving informed consumers outside Medicare-contracted networks. India's PLI scheme for medical device manufacturing presents tariff-advantaged production positioning for Southeast Asian export. Target pediatric and bariatric segments facing steepest incumbent portfolio rationalization pressure under EU MDR burden. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified health technology conglomerates seeking rehabilitation engineering capabilities and Nordic reimbursement infrastructure access. Five-to-ten year viability hinges on IoT connectivity integration enabling subscription-based fleet management models for institutional buyers. Watch CMS coverage decisions for advanced control interfaces as inflection signal for addressable volume expansion.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compressed review timelines unlock faster market entry for dual-motor configurations with programmable controllers. |
| CE Marking Pathway Investment | Front-loaded clinical evidence generation defends Nordic premium positioning against MDR timeline extensions. |
| Hospital System Partnership | Single-source agreements with outcome-based service commitments displace fragmented distributor relationships. |
| Software Companion Development | Predictive maintenance algorithms enable subscription-based fleet management for Medicare Advantage networks. |
| Reimbursement Strategy Alignment | CMS coverage decisions for standing configurations gate institutional purchasing volumes across VA procurement programs. |
Methodological Framework
Multi-period observation of Medicare reimbursement schedule revisions, FDA 510(k) clearance velocity, and EU MDR notified body queue lengths anchored the trend analysis, supplemented by interviews with rehabilitation engineers, hospital purchasing committee members, biomedical equipment specialists, and GPO contracts managers. Secondary validation drew from CMS Medicare data, FDA 510(k) database filings, EU MDR notified body documentation, and hospital procurement databases. Bottom-up segmentation modeling and top-down macroeconomic triangulation converged on volume and value estimates.
Input-output matrices mapped lithium-ion battery cost curves, rare earth magnet pricing indices, and semiconductor lead times against finished goods pricing elasticity across product type, control interface technology, end user category, and distribution channel dimensions. CAGRs were derived from cohort-based replacement demand modeling and reimbursement pathway expansion scenarios. Gesture control sensor miniaturization trajectories and standing configuration clinical evidence generation timelines served as technology-specific forecast inputs.
The model holds under stable Medicare reimbursement thresholds and EU MDR implementation timelines; deviation in CMS coverage decisions for advanced interfaces or notified body capacity constraints would shift volume trajectories. Practitioners should monitor FDA 510(k) review schedule acceleration and lithium-ion cell tariff developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Pacemakers Market
Medical Devices
Pathology Devices Market
Medical Devices
Spain Artificial Organs and Bionic Implants Market
Medical Devices
Veterinary Arthroscopy Device Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Wearable Defibrillators Market
Medical Devices
Transcatheter Aortic Valve Implantation (TAVI) Market
Medical Devices
United Kingdom Spinal Surgery Devices Market
Medical Devices
Global IVF Devices Market
Medical Devices
Peritoneal Catheter Systems Market
Medical Devices
Partial Ossicular Replacement Prosthesis Market
Medical Devices
Cyberknife Technology Market
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Brazil Medical Devices Market
Medical Devices
Next Generation Infusion Pump Market