
 Venous Device Market | 2026-2036
Venous Device Market Size, Share, and Industry Trends Forecast 2026-2036
Venous Device Market Analytics
The premium-commodity split in venous devices is shifting toward procedure-specific customization, with antimicrobial-coated catheters commanding differentiated positioning against standard peripherally inserted lines. Becton Dickinson and Company leverages its integrated vascular access portfolio to anchor hospital formulary decisions across North America. Teleflex Incorporated competes through specialized dialysis catheter platforms that sustain recurring revenue in nephrology centers. B. Braun SE dominates European manufacturing scale for infusion therapy sets, extending its channel control into home care distribution.
Venous devices encompass implantable and percutaneous instruments engineered for vascular access, fluid administration, thrombus management, and venous return modulation, typically manufactured from biocompatible polymers or nitinol alloys with specified French sizes and luminal flow rates calibrated for hemodynamic performance. Their primary purpose centers on sustaining therapeutic delivery and hemodynamic intervention across acute and chronic care settings. Catheters occupy the largest installed base within product type segmentation, though radiofrequency ablation systems command superior margin pools due to disposable catheter dependency and outpatient procedural economics. End user concentration tilts toward hospitals for complex interventional cases, while home care represents the fastest-growing channel as peripherally inserted central catheter protocols expand beyond institutional boundaries.
The FDA's 510(k) premarket notification framework governs device safety and substantial equivalence benchmarks in the United States, while the EMA's Medical Device Regulation imposes stricter clinical evidence requirements for CE marking across European markets. These regulatory architectures shape R&D allocation, prolong time-to-market for novel stent geometries, and elevate quality management system investments for market access eligibility. Stakeholders must monitor evolving reimbursement parity between hospital-based and ambulatory procedural settings, as site-of-service economics increasingly determine technology adoption velocity and manufacturer channel strategy.
Market Dynamics
The FDA's updated 510(k) pathway for vascular access devices is compressing time-to-market timelines while elevating clinical evidence requirements, forcing manufacturers to reallocate R&D budgets toward predicate device differentiation and quality management system upgrades.
Growth Catalysts
- Dialysis access protocols:Hospital systems are standardizing tunneled catheter placements for hemodialysis, creating sustained demand for antimicrobial-coated and split-tip configurations that reduce infection rates.
- EMA Medical Device Regulation:Stricter CE marking requirements under MDR are accelerating consolidation among manufacturers capable of funding clinical trials, advantaging scaled European producers.
- Outpatient procedural economics:Endovenous laser therapy adoption in German ambulatory surgical centers is displacing hospital-based vein stripping, expanding addressable volumes for disposable laser fiber manufacturers.
Market Restraints
- Nitinol alloy supply concentration:Superelastic wire feedstock for stent and catheter reinforcement depends on a limited supplier base in Western Europe, exposing device makers to input volatility.
- Biocompatibility testing bottlenecks:ISO 10993 cytotoxicity and sensitization studies require 14-26 week completion cycles, delaying product iterations for novel polymer formulations.
- Peripherally inserted central catheter substitution:Ultrasound-guided peripheral IV programs in US emergency departments are reducing unnecessary PICC placements, compressing standard line volumes.
Strategic Opportunities
- Home infusion therapy expansion:US reimbursement parity for hospital-at-home models under CMS waivers is extending catheter dwell times beyond institutional settings, requiring durable connector designs.
- Thrombus management convergence:Combination devices integrating aspiration catheters with pharmacomechanical thrombolysis are opening interventional radiology pathways previously served by open surgical embolectomy.
- Indian dialysis infrastructure:Central government PLI scheme incentives for medical device manufacturing are attracting catheter assembly investments to serve underpenetrated nephrology networks in tier-2 cities.
Industry Challenges
- Interventionalist training pipelines:Endovenous ablation certification requires 50-100 supervised cases, constraining procedure volume growth in markets with limited vascular surgery fellowship slots.
- Legacy EHR integration:Smart catheter connectivity protocols face interoperability friction with hospital information systems running outdated HL7 standards, delaying connected device launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venous Device Market |
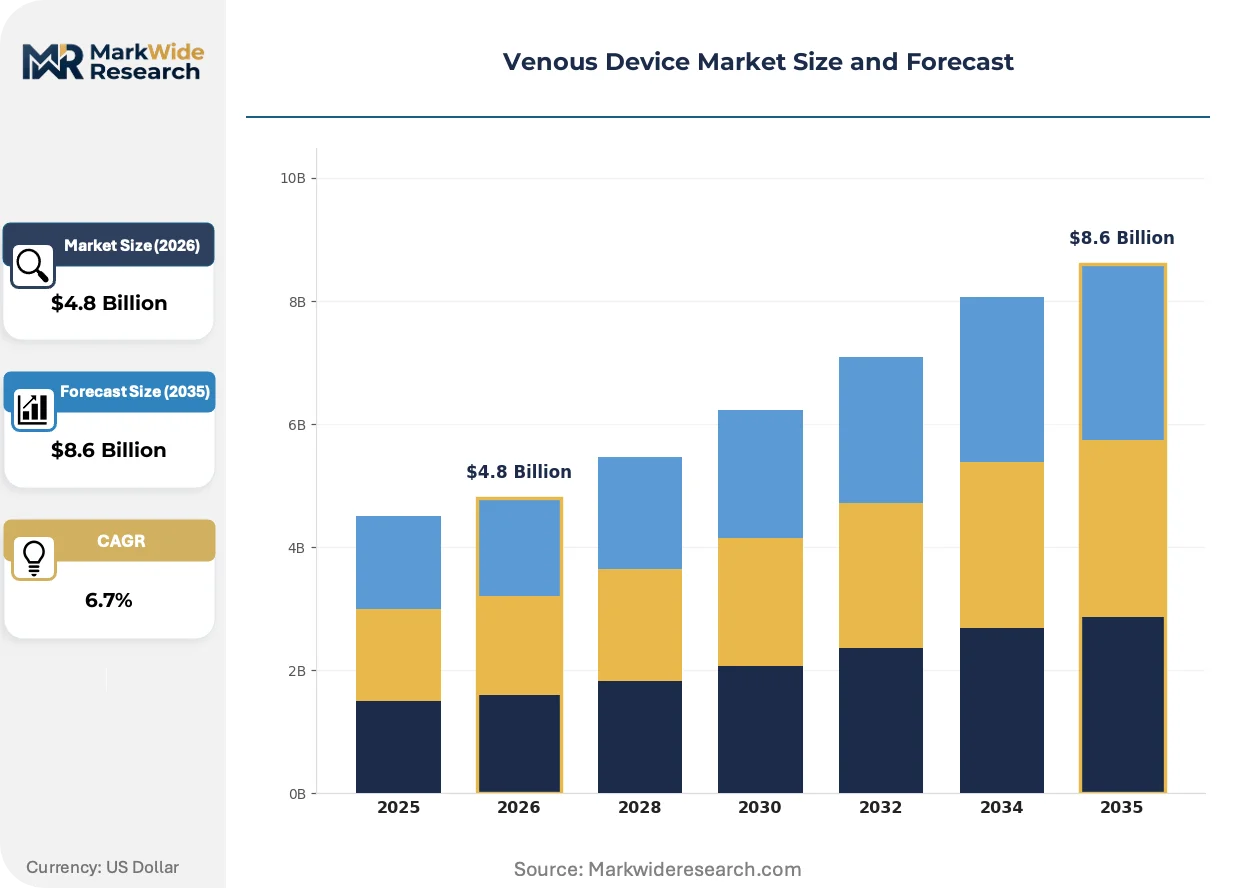
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Catheters, Ports, Stents, Filters Technology: Interventional Radiology, Endovenous Laser Therapy, Radiofrequency Ablation, Ultrasound End User: Hospitals, Clinics, Specialty Centers, Home Care Application: Chronic Venous Insufficiency, Deep Vein Thrombosis, Dialysis Access, Peripheral Vascular Disease |
| Companies Covered | Becton Dickinson and Company, Teleflex Incorporated, ICU Medical, B. Braun SE, Medtronic, AngioDynamics, Terumo Corporation, Cook Medical, Merit Medical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venous Device Market Evolving Landscape
Antimicrobial surface engineering and connected catheter technologies are redrawing competitive boundaries, while site-of-service migration is forcing manufacturers to redesign packaging and sterility assurance for non-hospital environments.
Photodynamic antimicrobial coatings incorporating chlorhexidine-silver complexes are expanding into oncology and critical care units seeking to reduce central line-associated bloodstream infections. Academic medical centers in the northeastern United States are piloting these surfaces in bone marrow transplant wards. The technology is expanding into premium catheter tiers previously dominated by standard polyurethane lines, compressing margin structures for commodity manufacturers.
EMA's Medical Device Regulation clinical evidence requirements are extending CE marking timelines from 12-18 months to 24-36 months for novel stent geometries. Manufacturers must now submit post-market clinical follow-up protocols as condition of approval, elevating registry maintenance costs. German and French notified bodies are prioritizing vascular access submissions, creating geographic bottlenecks that favor early MDR transition completers.
Hospital purchasing coalitions are consolidating venous device procurement across integrated delivery networks, displacing individual facility contracting autonomy. GPOs are demanding standardized SKU rationalization and compliance rebate structures that compress distributor margins. This concentration is most visible in the southeastern United States, where multi-hospital systems are consolidating infusion therapy spend under single-source agreements.
Venous Device Market Segmentation
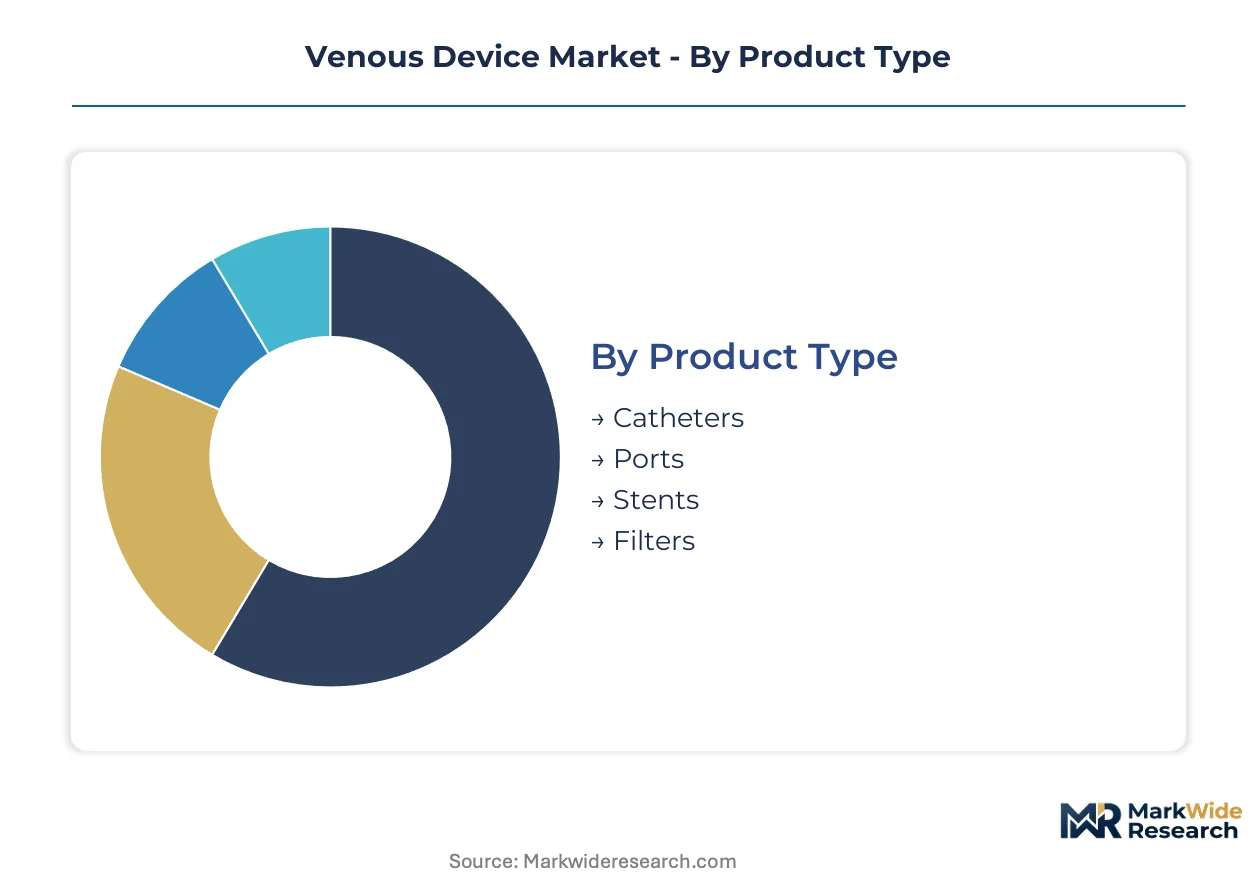
Venous device segmentation reveals distinct procurement patterns across acute and ambulatory settings. Product specifications diverge sharply between institutional bulk purchasing and home care durability requirements.
Product Type:
Customization intensity varies from commoditized infusion sets to patient-matched implantable ports, with antimicrobial coatings and French size granularity driving tiered positioning.
- Catheters:Polyurethane and silicone constructions dominate, with antimicrobial silver-ion surfaces penetrating oncology and critical care units in German hospital systems. Dialysis access protocols in US nephrology centers sustain demand for tunneled configurations with split-tip designs that reduce thrombosis rates.
- Ports:Titanium and plastic reservoir implants with silicone septa enable long-term chemotherapy delivery. French ambulatory surgical centers are expanding subcutaneous port placements for outpatient oncology regimens, displacing repeated peripheral cannulation.
- Stents:Nitinol alloy self-expanding designs address iliac and femoral vein obstructions.
- Filters:Cone-shaped and basket configurations trap emboli in vena cava placements.
Most installed capacity flows through Catheters. Expansion is steepest in Ports.
Technology:
Procedure economics separate capital-intensive platform technologies from disposable-dependent modalities, with reimbursement parity determining site-of-service migration.
- Interventional Radiology:Image-guided catheter manipulation enables thrombus aspiration and venous recanalization without surgical exposure. Academic medical centers in the northeastern United States are consolidating complex venous interventions under IR service lines, concentrating high-margin case volumes.
- Endovenous Laser Therapy:810-1470nm wavelength fibers deliver thermal energy to collapse saphenous veins. German outpatient clinics are displacing hospital-based stripping procedures, expanding disposable fiber consumption in ambulatory surgical centers.
- Radiofrequency Ablation:Segmental thermal delivery via catheter electrodes treats superficial venous reflux.
- Ultrasound:Real-time guidance for access placement and thrombus visualization.
Revenue concentrates in Interventional Radiology. Patient volume is climbing fastest in Endovenous Laser Therapy.
End User:
Channel economics fragment between high-acuity institutional purchasing and distributed home care logistics, with dwell time extension altering device durability specifications.
- Hospitals:Integrated delivery networks consolidate procurement for complex interventional cases requiring hybrid operating suites and 24-hour interventionalist coverage. Southeastern US health systems are standardizing vascular access protocols across multi-hospital footprints under single-source agreements.
- Home Care:Peripherally inserted central catheter protocols extend beyond institutional boundaries, requiring connector designs that withstand non-clinical environments. CMS hospital-at-home waivers in the United States are reimbursing extended dwell times, necessitating packaging and sterility assurance redesigns.
- Clinics:Ambulatory settings handle routine access and superficial vein procedures.
- Specialty Centers:Nephrology and oncology focused facilities concentrate recurring device consumption.
Procurement volume aggregates in Hospitals. Channel expansion is most rapid in Home Care.
Application:
Clinical indication segmentation aligns with chronic disease prevalence and procedure reimbursement codes, with dialysis access commanding dedicated supply chain infrastructure.
- Dialysis Access:Tunneled and non-tunneled catheters plus arteriovenous fistula maintenance devices sustain recurring consumption in nephrology networks. Indian tier-2 cities are attracting catheter assembly investments under central government PLI scheme incentives, building capacity for underpenetrated dialysis infrastructure.
- Chronic Venous Insufficiency:Endovenous ablation and sclerotherapy address venous reflux and varicose veins. German outpatient procedural economics favor laser and radiofrequency modalities over traditional stripping, expanding addressable volumes for disposable device manufacturers.
- Deep Vein Thrombosis:Thrombus aspiration and pharmacomechanical thrombolysis devices target clot burden reduction.
- Peripheral Vascular Disease:Venous stenting and angioplasty address iliofemoral obstructive pathology.
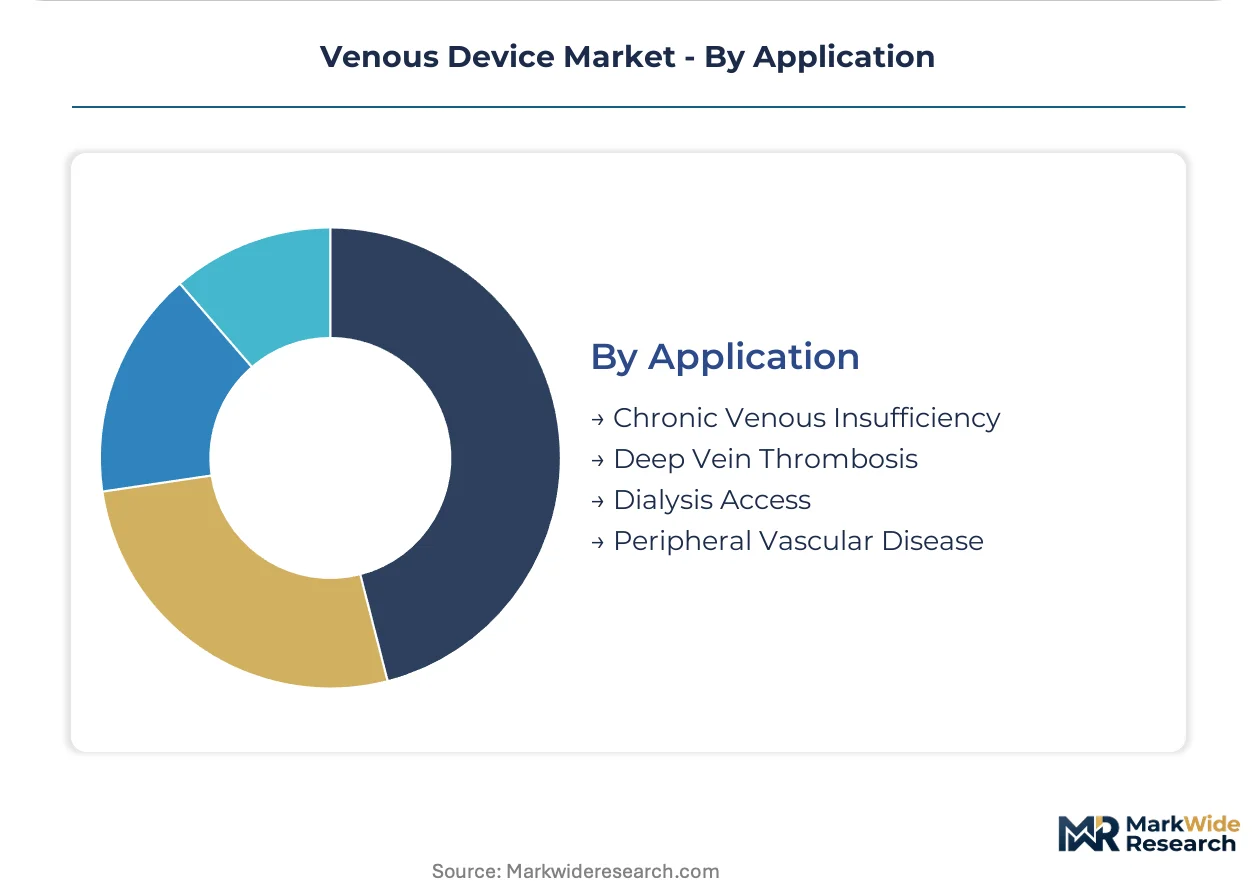
Device consumption concentrates in Dialysis Access. Procedure volume is expanding most quickly in Chronic Venous Insufficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's outpatient clinics outpace France in endovenous laser therapy adoption, while the United States concentrates dialysis access device procurement within integrated delivery networks. India attracts manufacturing investments under production-linked incentives, and Japan maintains stringent biocompatibility standards that extend regulatory timelines.
United States
Hospital-at-home waivers from CMS extend peripherally inserted central catheter dwell times beyond institutional boundaries, necessitating durable connector redesigns. FDA's updated 510(k) pathway compresses clearance timelines while elevating clinical evidence requirements for predicate device differentiation. Southeastern health systems consolidate vascular access procurement under single-source agreements across multi-hospital footprints.
Germany
Ambulatory surgical centers displace hospital-based vein stripping with endovenous laser therapy, expanding disposable fiber consumption. EMA's Medical Device Regulation extends CE marking timelines to 24-36 months for novel stent geometries. Notified bodies in Berlin and Munich prioritize vascular access submissions, creating geographic bottlenecks favoring early MDR transition completers.
India
Central government PLI scheme incentives attract catheter assembly investments to serve underpenetrated nephrology networks in tier-2 cities. CDSCO imposes biocompatibility testing requirements aligned with ISO 10993 standards for imported devices. Manufacturing clusters in Maharashtra and Gujarat expand capacity for dialysis access catheter production targeting domestic and export markets.
Japan
PMDA maintains rigorous post-market surveillance requirements for nitinol alloy stents used in venous interventions. METI promotes smart medical device connectivity standards that intersect with catheter monitoring technologies. Tokyo and Osaka academic medical centers consolidate complex venous interventions under interventional radiology service lines.
Venous Device Market Competitive Landscape
Top-tier vendors anchor hospital formulary decisions through integrated vascular access portfolios, while mid-scale specialists compete through dialysis catheter platforms and European manufacturing scale. The vendor base stratifies across diversified conglomerates with multi-therapy reach and focused players with nephrology or interventional radiology concentration. Two strategic archetypes dominate: integrated portfolio holders leveraging cross-selling leverage, and procedure-specific specialists sustaining recurring revenue in high-frequency clinical settings. Competitive moves concentrate on M&A for technology access and capacity expansion into Asian manufacturing zones.
Within the integrated portfolio tier, Becton Dickinson and Company and Teleflex Incorporated occupy positions that exemplify divergent strategic vectors. Becton Dickinson anchors North American hospital formulary decisions through breadth across vascular access categories. Teleflex represents the specialized platform approach, with its corporate structure organized around recurring revenue capture in nephrology centers. B. Braun SE sits within the European manufacturing scale archetype, leveraging German production infrastructure for infusion therapy distribution control.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Teleflex Incorporated |
| ICU Medical |
| B. Braun SE |
| Medtronic |
| AngioDynamics |
| Terumo Corporation |
| Cook Medical |
| Merit Medical Systems |
| Others |
Value Network & Pricing Analysis
Nitinol alloy spot prices in Western European commodity markets cascade through catheter and stent manufacturing tiers, compressing margin structures for mid-scale producers while amplifying pricing power among integrated manufacturers with captive wire-drawing capacity. This raw-material cost pressure stratifies procurement negotiations across hospital GPOs, ambulatory surgical centers, and home care distributors.
Pricing Analysis
Capacity additions in Maharashtra and Gujarat are reshaping price floors for standard polyurethane catheters, forcing legacy manufacturers to differentiate through antimicrobial coating premiums and split-tip dialysis configurations. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared predicate devices from MDR-transitioned CE-marked portfolios. Cost compression in commodity PICC lines is intensifying because ultrasound-guided peripheral IV programs reduce unnecessary placements. Dialysis access protocols in US nephrology centers show least price sensitivity due to infection-rate economics, while emergency department bulk purchasing exhibits highest sensitivity.
Supply Chain Analysis
Photoresist supply rests on Japanese specialty chemical producers, but nitinol superelastic wire feedstock draws from a concentrated Western European supplier base in Germany and France. Polyurethane resin and silicone elastomer formulations hinge on petrochemical derivatives subject to energy cost volatility. Single-source vulnerability in nitinol alloy exposes device makers to input disruption when geopolitical friction affects Western European trade flows. Distribution runs through hospital purchasing coalitions in the southeastern United States and German ambulatory surgical networks, with home care logistics expanding through specialized durable medical equipment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Venous Device Market functions as a stable compounder anchored by recurring dialysis access consumption and chronic venous insufficiency procedure expansion.
For Market Incumbents: Extend antimicrobial surface engineering leadership through chlorhexidine-silver complex R&D investments that defend against commoditization of standard polyurethane lines. Deepen backward integration into nitinol wire drawing to offset Western European feedstock concentration risk. Anchor hospital formulary decisions by bundling vascular access portfolios with interventional radiology training support. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer lower customer acquisition costs than traditional distributor relationships for penetrating German ambulatory surgical centers. Target underpenetrated nephrology networks in Indian tier-2 cities where PLI scheme incentives reduce capital barriers. Pursue white-label manufacturing partnerships with Maharashtra-based assembly clusters to establish cost positioning before brand building. For Investors and Strategic Acquirers: Consolidation pressure builds where EMA MDR clinical evidence requirements exceed mid-cap R&D budgets, creating acquisition opportunities among early MDR transition completers with notified body relationships. Five-to-ten year viability favors platforms with recurring revenue capture in dialysis and oncology infusion settings. Watch FDA 510(k) pathway enforcement shifts as the inflection indicator for predicate device differentiation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA MDR transition completion unlocks European hospital procurement eligibility ahead of mid-cap competitors. |
| Hospital System Partnership | Single-source agreements with southeastern US integrated delivery networks secure volume commitments and formulary anchoring. |
| Software Companion Development | Smart catheter connectivity protocols interoperating with HL7 FHIR standards differentiate premium tiers in academic medical centers. |
| Reimbursement Strategy | CMS hospital-at-home waiver alignment extends catheter dwell time economics into home care channel expansion. |
| Backward Integration | In-house nitinol wire drawing reduces Western European supplier concentration risk and stabilizes input cost volatility. |
Research Methodology
Direct dialogue with vascular access nurses, interventional radiologists, hospital GPO contracts managers, and nephrology center medical directors grounded qualitative findings in clinical workflow realities. Secondary validation drew from FDA 510(k) filings, EMA MDR submission databases, CMS Medicare reimbursement schedules, and German hospital procurement records. Bottom-up and top-down triangulation cross-checked catheter placement volume estimates against manufacturer shipment disclosures and distributor inventory turns.
Bottom-up modeling aggregated procedure volumes across dialysis access, chronic venous insufficiency, and thrombus management applications, then applied technology-specific device utilization rates. Segmentation dimensions included product type, technology modality, end user channel, and application indication. CAGRs were derived from fitted trend analysis calibrated to historical penetration curves and reimbursement parity shifts. Forecast inputs incorporated EMA MDR transition timelines and CMS site-of-service migration patterns.
The model assumes a particular technology adoption path; alternative pathways for endovenous laser therapy versus radiofrequency ablation would alter the outlook if reimbursement parity shifts favor thermal modality substitution. Forecasts reflect assumptions about interventionalist training pipeline expansion and nitinol alloy supply stability. A small set of triggers—FDA 510(k) enforcement stringency, EMA notified body capacity constraints, and Indian PLI scheme allocation revisions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
IV Poles Market
Medical Devices
Eye Sphere Implants Market
Medical Devices
South Korea Drug Delivery Devices Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Neurofeedback Systems Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Cardioscope Market
Medical Devices
India Drug Delivery Devices Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Japan Minimally Invasive Surgery Devices Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Contact Thermometer Market
Medical Devices
UK Artificial Organs and Bionic Implants Market