
 Thailand Construction Market | 2026-2036
Thailand Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Construction Market Outlook
Buyer concentration among Thai government agencies and state enterprises is decoupling from traditional private developer channels, fragmenting contract award patterns across municipal and provincial authorities. Italian-Thai Development PCL leverages its integrated EPC capabilities to anchor large-scale infrastructure bids. CH. Karnchang PCL sustains dominance in mass transit and water resource projects through specialized civil engineering expertise. Sino-Thai Engineering and Construction PCL competes aggressively on design-build tenders for industrial estate development.
Thailand construction encompasses the physical assembly of buildings, transport networks, and utilities using reinforced concrete, structural steel, and masonry systems governed by Thai Industrial Standards Institute specifications for seismic resistance and fire safety. The sector's primary purpose is delivering habitable, operational, and connective assets that enable commercial activity and public service delivery. Infrastructure project types currently lead awarded contract value, absorbing central government budget allocations for rail, road, and port modernization. Residential construction is accelerating fastest in Bangkok's peripheral zones and secondary cities where urban migration outpaces existing housing stock. Design-build service types capture disproportionate margin pools by compressing project timelines and reducing interface risk between designers and builders.
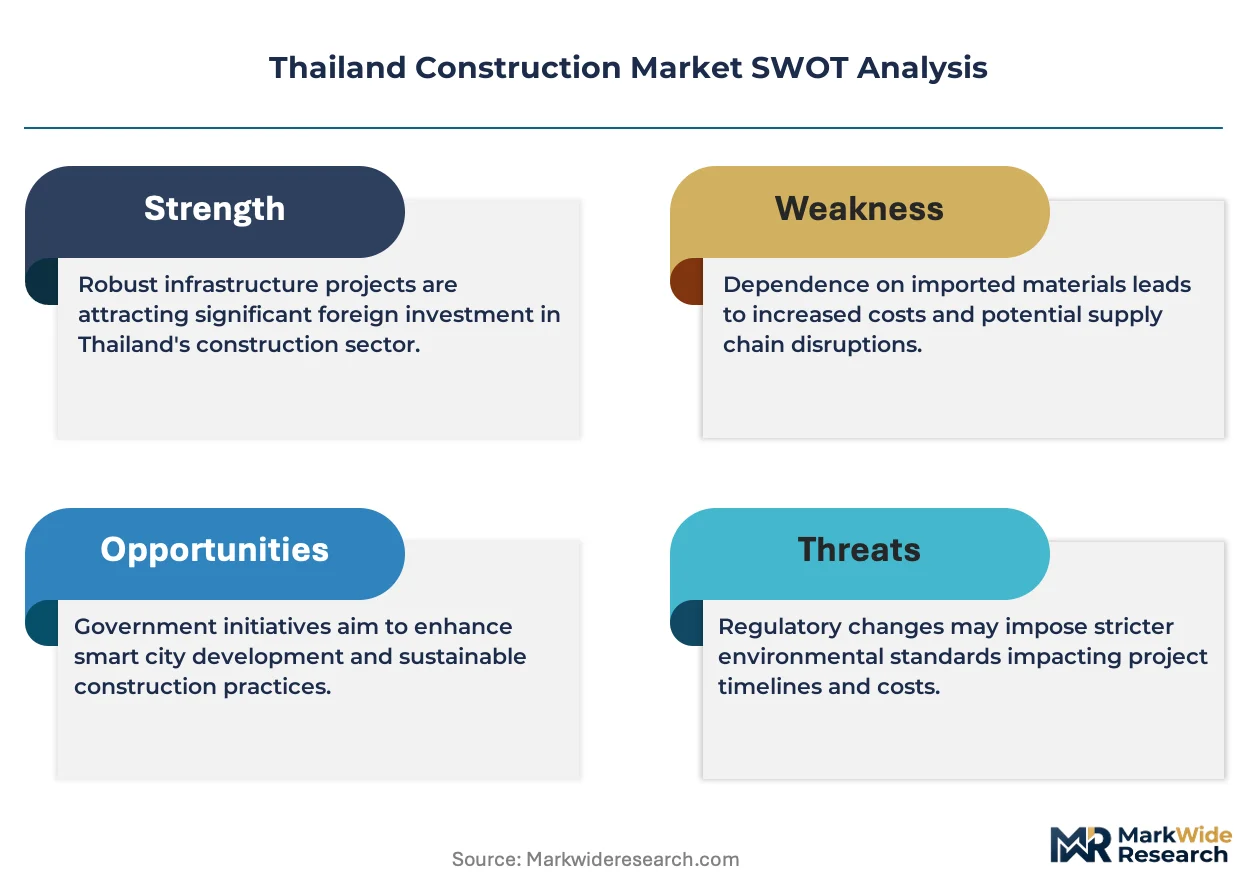
Thailand's Department of Public Works and Town & Country Planning enforces building control regulations that mandate environmental impact assessments for projects exceeding specified thresholds, while the Board of Investment administers construction-related tax privileges tied to smart city and logistics zone certifications. These frameworks elevate compliance costs for smaller contractors while creating preferential access for firms with in-house permitting and sustainability documentation capabilities. Stakeholders must monitor evolving land-use zoning amendments and green building code adoptions that will determine project feasibility and financing eligibility across Thailand's priority economic corridors.
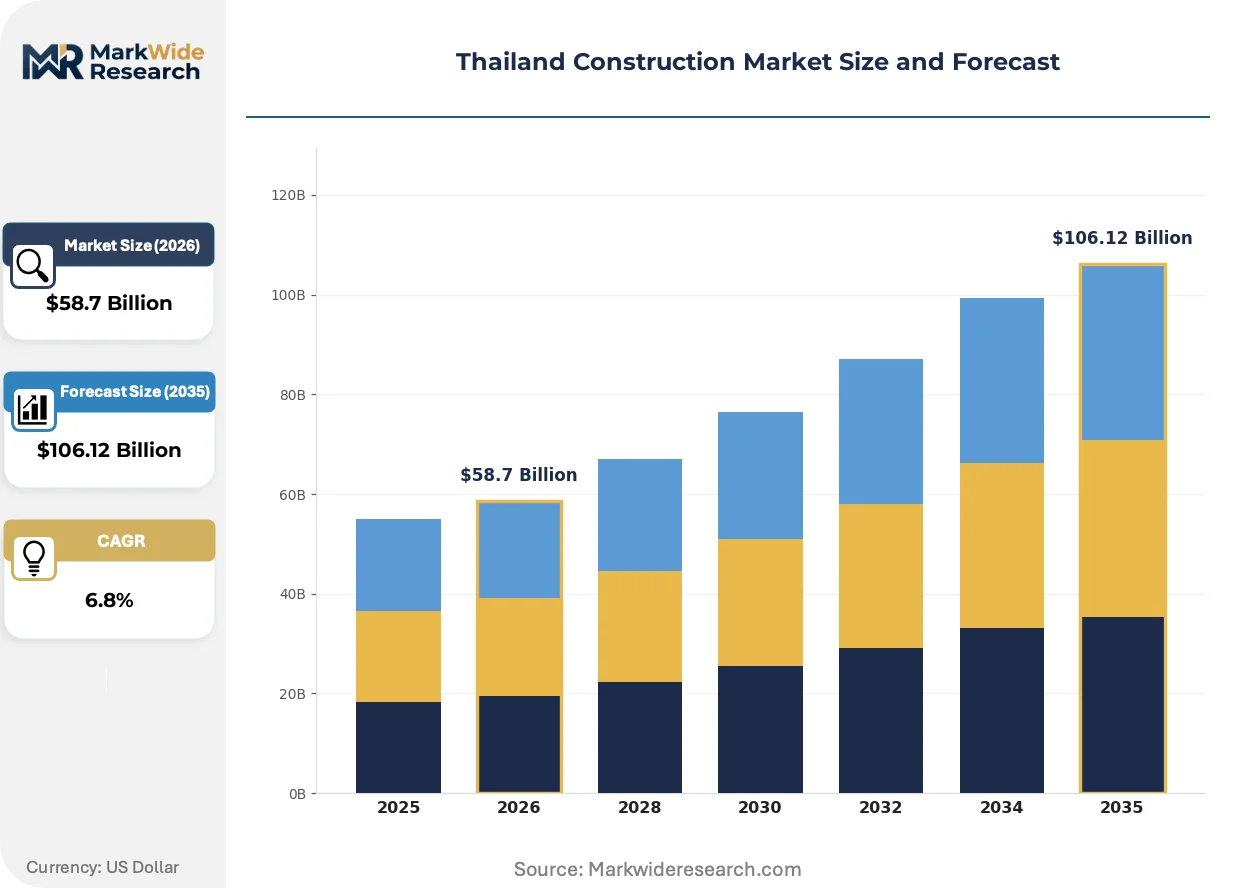
Market Dynamics
Thailand's construction sector is reconfiguring around public infrastructure primacy, as central government budget allocations for rail, road, and port modernization now outstrip private developer pipelines and reshape contractor specialization requirements.
Growth Catalysts
- Eastern Economic Corridor infrastructure mandate:State-directed investment in logistics zones and industrial estates is generating contiguous project clusters that favor contractors with integrated design-build capabilities.
- Smart city certification incentives:The Board of Investment's tax privileges for certified developments are redirecting private capital toward technology-integrated construction specifications.
- Mass transit expansion:Bangkok Metropolitan Administration's rail network extensions are sustaining specialized civil engineering demand across the metropolitan corridor.
Market Restraints
- Reinforced concrete input volatility:Energy-intensive cement production faces feedstock cost pressure from natural gas and coal price fluctuations, compressing margins on fixed-price public contracts.
- Skilled labor supply concentration:Migration patterns have concentrated experienced construction technicians in Bangkok and Chonburi provinces, creating wage inflation and project delays in secondary locations.
- Seismic code compliance friction:Thai Industrial Standards Institute's updated structural specifications for earthquake resistance are extending design review timelines and elevating engineering costs for mid-tier contractors.
Strategic Opportunities
- Peripheral Bangkok residential zones:Urban migration into Pathum Thani and Nonthaburi provinces is outpacing housing stock, creating demand for mid-rise residential construction with expedited permitting.
- Building-integrated photovoltaics:Convergence of solar panel technology with structural envelope systems is enabling net-zero certifications that qualify for preferential financing.
- Prefabrication channel innovation:Modular component manufacturing is compressing on-site assembly timelines and reducing labor dependency for standardized project types.
Industry Challenges
- Environmental impact assessment timelines:Department of Public Works and Town & Country Planning review processes for projects exceeding specified thresholds are extending pre-construction phases by 8-14 months.
- Digital design competency gaps:Building information modeling expertise remains concentrated among large integrated firms, excluding smaller contractors from design-build tender participation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Construction Market |
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $106.12 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Infrastructure, Industrial Material Type: Cement, Steel, Wood, Brick Service Type: General Contracting, Design-Build, Consulting, Project Management End User: Governments, Real Estate Developers, Private Investors, Contractors |
| Companies Covered | Unique Engineering and Construction PCL, Christiani And Nielsen (Thai) PCL, Italian-Thai Development PCL, Seafco PCL, Syntec Construction PCL, Sino-Thai Engineering and Construction PCL, TTCL Public Company Limited, Pre-Built Public Company Limited, CH. Karnchang PCL, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Construction Market Strategic Shifts
Digital fabrication methods and sustainability certification requirements are compressing traditional construction timelines while elevating technical entry barriers for project participation across Thailand's priority economic corridors.
Building information modeling platforms are converging with drone-based site surveying to enable real-time progress monitoring and clash detection before physical construction begins. Large infrastructure contractors in the Eastern Economic Corridor are adopting these integrated workflows to compress project handover schedules. The structural consequence is a bifurcation between technology-capable firms winning design-build tenders and traditional contractors relegated to subcontractor roles.
The Department of Public Works and Town & Country Planning is tightening environmental impact assessment enforcement for projects exceeding specified scale thresholds, extending pre-construction approval timelines. Industrial estate developers are responding by embedding sustainability documentation specialists within project teams from conceptual design phases. Mass transit and water resource projects face the most acute compliance burden, with some contractors withdrawing from public tenders due to extended capital lock-up periods.
Buyer concentration among Thai government agencies and state enterprises is fragmenting contract award patterns across municipal and provincial authorities rather than centralizing through traditional private developer channels. Design-build service contracts are displacing conventional design-bid-build procurement for rail and logistics zone projects, compressing interface risk but concentrating margin capture among integrated firms. This pattern is most visible in Bangkok's metropolitan expansion corridor and Chonburi province, where public infrastructure budgets dominate awarded contract value.
Thailand Construction Market Segmentation
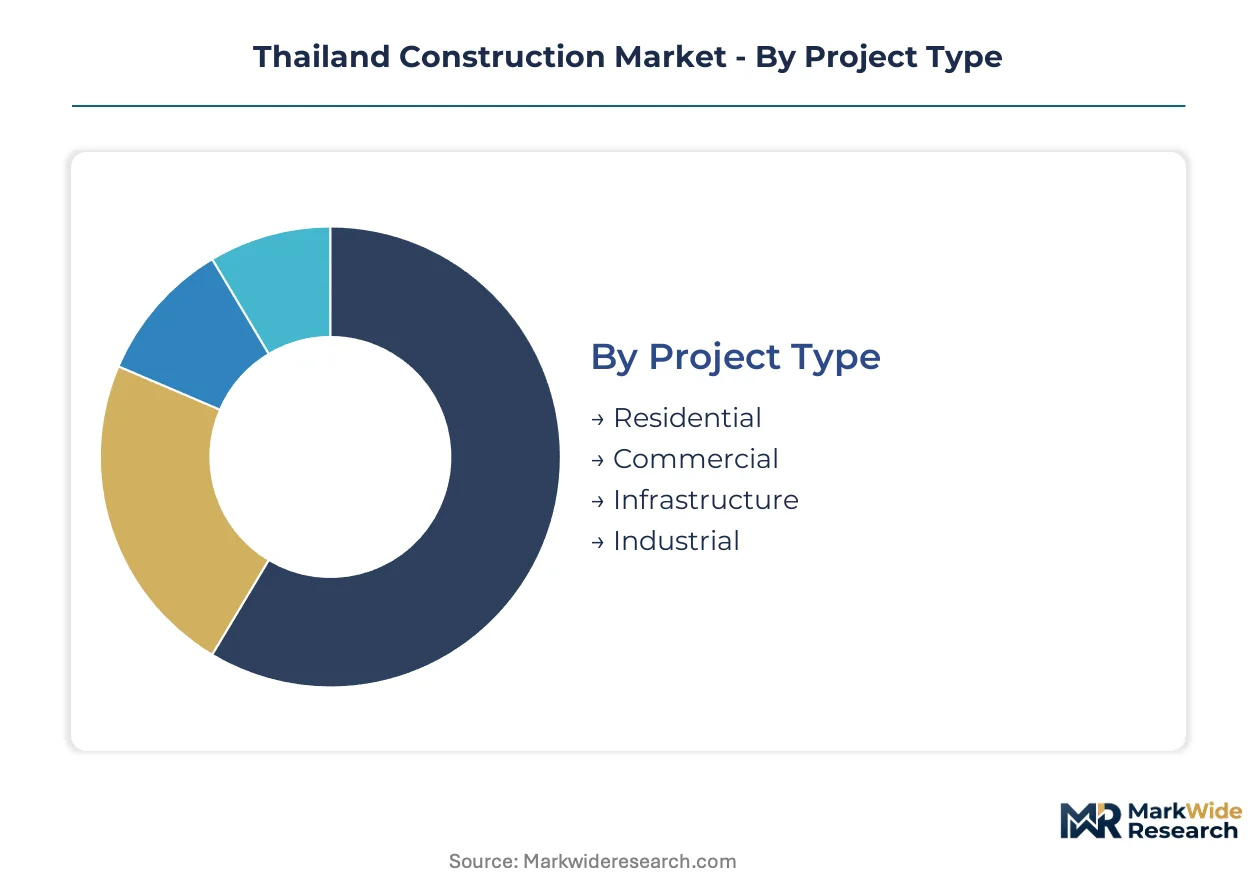
Construction procurement in Thailand fragments across project scale, material specifications, and service delivery models. Government agencies and private developers apply divergent vendor qualification criteria, creating distinct competitive arenas within each segment category.
Project Type:
Government budget allocation cycles determine contract award timing and scale thresholds across project categories.
- Infrastructure:Rail, road, and port modernization projects absorb central government allocations governed by Thailand's national development plans. Bangkok Metropolitan Administration and Eastern Economic Corridor provinces concentrate awarded contract value where state-directed investment flows heaviest.
- Residential:Mid-rise housing construction in Bangkok's peripheral zones—Pathum Thani and Nonthaburi—responds to urban migration outpacing existing stock. Developers prioritize expedited permitting to capture demand from first-time buyers and rental investors.
- Commercial:Office and retail development concentrates in Bangkok's metropolitan expansion corridor, with smart city certification incentives from the Board of Investment redirecting capital toward technology-integrated specifications.
- Industrial:Logistics zones and manufacturing facilities cluster in Eastern Economic Corridor provinces, favoring contractors with integrated design-build capabilities for contiguous project execution.
Volume sits with Infrastructure; growth tilts toward Residential.
Material Type:
Input cost volatility and seismic compliance requirements reshape material procurement strategies for fixed-price public contracts.
- Cement:Energy-intensive production faces feedstock pressure from natural gas and coal price fluctuations. Thai Industrial Standards Institute specifications for seismic resistance mandate grade-specific formulations that compress margins on large infrastructure pours.
- Steel:Structural steel framing dominates high-rise commercial and industrial estate construction where earthquake resistance codes are most stringent. Fabrication lead times extend when mills prioritize export orders over domestic project supply.
- Wood:Timber construction retains niche application in low-rise residential and resort developments, constrained by fire safety regulations and tropical climate durability requirements.
- Brick:Masonry systems persist in perimeter walls and aesthetic facades, with demand fragmenting across provincial contractors lacking integrated structural steel capabilities.
Steel commands the premium tier; cement dominates tonnage throughput.
Service Type:
Risk allocation preferences between public and private buyers drive procurement model selection and margin distribution.
- Design-Build:Single-source contracting compresses project timelines and reduces interface risk between designers and builders. The Board of Investment's smart city and logistics zone certifications favor this model for integrated technology deployment.
- General Contracting:Traditional construction-only services persist where owners retain design control, particularly in government agency projects with established architectural relationships and extended review timelines.
- Consulting:Environmental impact assessment and sustainability documentation specialists embed within project teams from conceptual phases, responding to Department of Public Works and Town & Country Planning enforcement tightening.
- Project Management:Oversight services concentrate among large integrated firms with building information modeling expertise, excluding smaller contractors from complex tender participation.
Design-Build captures margin concentration; General Contracting retains volume breadth.
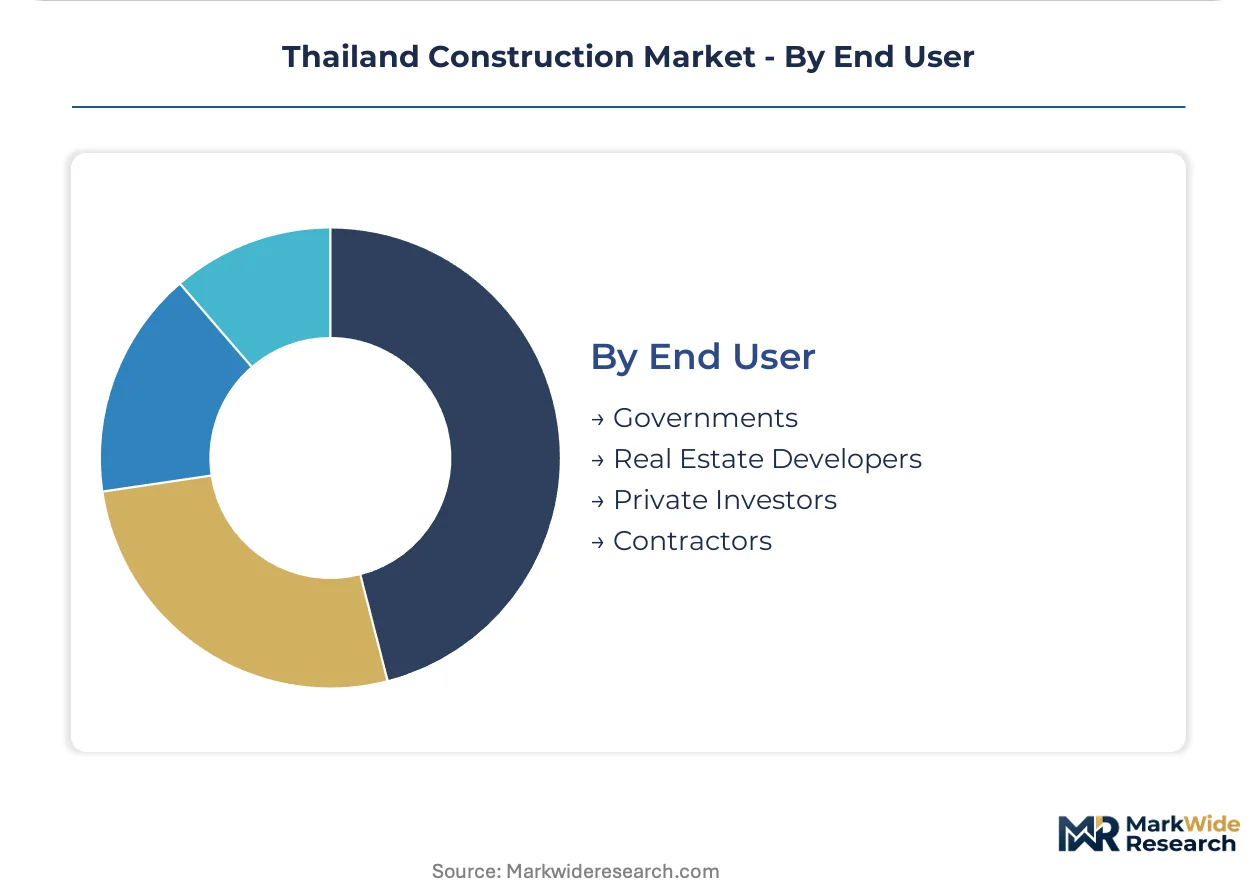
End User:
Buyer concentration patterns determine contract award fragmentation and vendor specialization requirements.
- Governments:Central budget allocations for rail, road, and water resource projects dominate awarded contract value. State enterprises and municipal authorities apply diverging technical specifications, splintering procurement across provincial channels.
- Real Estate Developers:Private capital flows toward Bangkok's metropolitan expansion and secondary city housing stock, with smart city tax privileges redirecting investment toward certified developments.
- Private Investors:Industrial estate and logistics zone development concentrates in Eastern Economic Corridor provinces, targeting export-oriented manufacturing tenants.
- Contractors:Subcontractor procurement channels persist for specialized trades—electrical, mechanical, finishing—where mid-tier firms lacking design capabilities compete on labor rates.
Governments anchor contract value; Real Estate Developers drive expansion velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Limestone deposits in Saraburi province anchor Thailand's cement production base, feeding infrastructure expansion across the Central Plains and Eastern seaboard. Domestic clinker capacity supports construction material supply chains radiating from Bangkok toward provincial growth corridors.
Bangkok Metropolitan Region
Mass transit rail extensions and peripheral residential zones in Pathum Thani and Nonthaburi absorb the majority of public infrastructure budgets. The Bangkok Metropolitan Administration applies specialized civil engineering specifications for elevated transport structures. Large integrated contractors concentrate design-build capabilities in this corridor to capture contiguous project clusters.
Eastern Economic Corridor
Chonburi, Rayong, and Chachoengsao provinces host state-directed logistics zones and industrial estates generating demand for contiguous construction execution. The Board of Investment administers tax privileges for smart city and logistics zone certifications that redirect private capital. Italian-Thai Development PCL leverages integrated EPC capabilities to anchor large-scale infrastructure bids in this zone.
Central Plains
Ayutthaya and Saraburi provinces concentrate cement manufacturing and steel fabrication facilities supplying downstream construction activity. The Department of Public Works and Town & Country Planning enforces seismic resistance specifications through Thai Industrial Standards Institute mandates. Water resource and flood management projects dominate public agency procurement in this basin.
Northern Region
Chiang Mai and Chiang Rai provinces experience accelerating residential construction responding to secondary city urbanization and tourism-related development. Provincial authorities apply divergent permitting timelines compared to metropolitan channels. Smaller contractors compete on labor rates for low-rise residential and resort construction lacking design-build complexity.
Southern Region
Songkhla and Phuket provinces concentrate port modernization and tourism infrastructure responding to maritime trade and hospitality demand. The Board of Investment's targeted incentives for logistics zone development reshape contractor procurement criteria in deepwater port zones. Seismic code compliance friction extends design review timelines for coastal structures facing tsunami resistance requirements.
Thailand Construction Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialized civil engineering niches and technology-integrated delivery models. The vendor base concentrates around integrated firms with in-house design capabilities and permitting expertise, while mid-tier contractors compete for subcontractor roles. Three archetypes dominate: EPC-integrated infrastructure specialists, residential-focused developers, and regional contractors serving provincial authorities. Competitive moves center on strategic partnerships for technology licensing and backward integration into prefabrication manufacturing to compress project timelines.
Within the integrated infrastructure tier, Italian-Thai Development PCL and CH. Karnchang PCL exemplify EPC-capable contractors positioned for large-scale public tenders. Sino-Thai Engineering and Construction PCL occupies a position among design-build competitors targeting industrial estate development. These firms represent varying degrees of vertical integration, from captive engineering resources to modular manufacturing capabilities, reflecting the sector's bifurcation between technology-enabled prime contractors and labor-dependent subcontractors.
| Leading Market Players |
|---|
| Unique Engineering and Construction PCL |
| Christiani And Nielsen (Thai) PCL |
| Italian-Thai Development PCL |
| Seafco PCL |
| Syntec Construction PCL |
| Sino-Thai Engineering and Construction PCL |
| TTCL Public Company Limited |
| Pre-Built Public Company Limited |
| CH. Karnchang PCL |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap contractors anchored in Bangkok and Chonburi provinces exercise pricing discipline through captive cement supply relationships and long-term steel offtake agreements with Saraburi-based mills. Their concentrated ownership structures enable rapid margin recapture when feedstock costs shift, while state enterprise procurement rules compress pricing flexibility on fixed-price infrastructure tenders.
Pricing Analysis
Volume concentrates in fixed-price public infrastructure contracts where cement and steel input volatility erodes contractor margins, while design-build premiums capture margin pools through timeline compression and risk transfer. Price differentiation hinges on seismic certification grade and in-house permitting capability, with BOI-certified smart city developments commanding financing advantages that offset higher upfront engineering costs. Cost compression in mid-tier general contracting intensifies as fixed-price public tenders absorb feedstock spikes without adjustment clauses. Government agencies exhibit lowest price sensitivity due to budgetary allocation cycles, while private residential developers in peripheral Bangkok zones negotiate aggressively on labor rates.
Supply Chain Analysis
Direct-to-state-enterprise channels handle hyperscale infrastructure demand through pre-qualified contractor rosters, while industrial estate developers source through integrated EPC firms with captive engineering resources. Geographic supply concentration centers on Thailand's Central Plains, with Saraburi limestone deposits feeding clinker production and Chonburi steel fabrication serving Eastern Economic Corridor projects. Raw material dependencies encompass natural gas for cement kilns, imported coking coal for steel production, and specialty admixtures for seismic-grade concrete formulations. Single-source vulnerability runs through concentrated steel mill capacity when export orders divert domestic supply. Distribution runs through project-specific logistics corridors radiating from Bangkok toward provincial growth zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's construction sector operates as a supply-constrained environment where skilled civil engineering technician shortages in secondary provinces prop pricing premiums for available labor pools. This bottleneck sustains margin capture for firms with established training pipelines and regional workforce deployment capabilities.
For Market Incumbents: Cement dominance in mass transit and water resource verticals by embedding sustainability documentation specialists within project teams from conceptual phases, countering Department of Public Works and Town & Country Planning review timeline extensions. Prioritize backward integration into prefabrication manufacturing to compress on-site assembly timelines and reduce labor dependency. Digital design competency gaps among mid-tier competitors create defensive moats for firms with building information modeling expertise.
For New Entrants and Emerging Players: The price-point gap between premium design-build integrators and economy-tier general contractors opens viable positioning for modular construction specialists targeting peripheral Bangkok residential zones in Pathum Thani and Nonthaburi. Building-integrated photovoltaics and net-zero certification capabilities represent the most penetrable service extension, qualifying projects for BOI preferential financing. Go-to-market execution should anchor on expedited permitting relationships with provincial authorities outside metropolitan channels.
For Investors and Strategic Acquirers: Eastern Economic Corridor logistics zone tender awards accelerating above historical baselines is the leading indicator that state-directed infrastructure primacy will sustain contract value concentration among integrated EPC firms. Long-term viability favors acquisition targets with captive civil engineering resources and established relationships with Bangkok Metropolitan Administration or provincial state enterprises. Monitor BOI smart city certification uptake rates as the inflection signal for technology-integrated construction specification shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Prefabrication Manufacturing | Captive modular component production compresses project timelines and reduces Bangkok-Chonburi labor market dependency. |
| Building Information Modeling Capability Investment | In-house digital design expertise qualifies firms for design-build tenders excluding traditional general contractors. |
| BOI Smart City Certification Pursuit | Tax privilege eligibility redirects private capital toward technology-integrated construction specifications. |
| Sustainability Documentation Specialist Embedding | Early-phase environmental impact assessment preparation mitigates Department of Public Works and Town & Country Planning review delays. |
| Peripheral Province Workforce Training Pipeline | Skilled technician cultivation in Pathum Thani and Nonthaburi addresses wage inflation and project delay risks in secondary locations. |
Study Parameters
Document review covered Board of Investment incentive filings, Department of Public Works and Town & Country Planning regulatory bulletins, and Thai Industrial Standards Institute seismic code updates, complemented by interviews with EPC contractor project directors, state enterprise procurement officers, cement plant operations managers, and industrial estate development executives. Secondary validation drew from customs trade data for construction material imports, Bank of Thailand infrastructure credit disbursement records, and municipal budget allocation disclosures. Bottom-up project pipeline enumeration triangulated against top-down national development plan expenditure frameworks.
Segment-level outputs across the projection horizon reflect modeled interactions between project type, service delivery model, and regional infrastructure investment intensity. Analytical frameworks incorporated material cost pass-through elasticity, labor supply concentration effects, and regulatory compliance timeline impacts. CAGRs derived from expenditure trajectory analysis against historical award pattern baselines. Forecast inputs encompassed natural gas price scenarios for cement production, steel mill capacity utilization rates, and BOI certification uptake velocity.
Inputs from state enterprise procurement databases and provincial planning authority filings were available through the study window; gaps in real-time subcontractor pricing data introduce uncertainty bands around residential construction cost projections. Forecasts reflect assumptions regarding sustained Eastern Economic Corridor infrastructure mandate execution and Bangkok Metropolitan Administration rail network extension commitments. Periodic stress-testing of base assumptions is recommended against energy price volatility scenarios and seismic code amendment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Japan Prefabricated Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
United States Commercial Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Kuwait Construction Market
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Construction Market
Building Construction
Egypt Construction Market