
 Japan Prefabricated Buildings Market | 2026-2036
Japan Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Prefabricated Buildings Market Insights
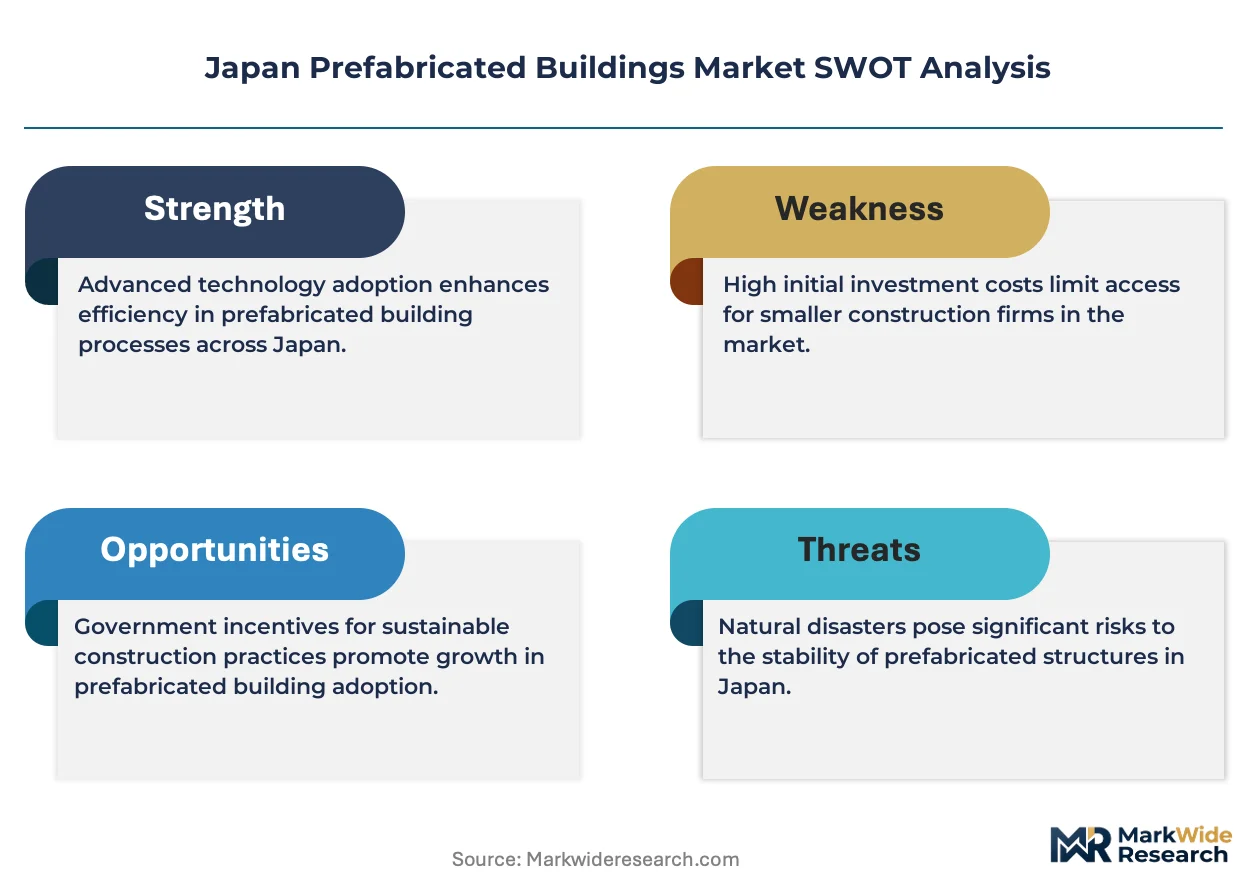
Seismic-grade specification upgrades is redrawing competitive boundaries across the Japan Prefabricated Buildings Market. Sekisui House leverages its integrated supply chain to control material quality from factory floor to final assembly. Daiwa House Group anchors its position through extensive R&D investment in earthquake-resistant joint systems. Panasonic Homes differentiates via smart-home technology embedded at the manufacturing stage rather than retrofitted on site.
Prefabricated buildings are factory-manufactured structural units assembled from standardized components such as steel frames, precast concrete panels, or engineered wood sections, then transported to sites for rapid installation. These systems achieve construction precision measured in millimeters while cutting on-site labor requirements by half versus conventional methods. Steel-framed residential units dominate current output volumes, reflecting Japan's stringent seismic performance codes and consumer preference for durability. Modular offices represent the fastest-expanding application segment, driven by corporate demand for relocatable workspace solutions in Tokyo and Osaka. Wood-based prefabricated housing maintains strong position in rural prefectures where traditional aesthetics align with modern engineered-laminate technologies.
METI enforces building energy efficiency standards that factory production satisfies more consistently than site-built alternatives, while JIS certification requirements for structural materials create compliance barriers for imported components. The country's national land regulator coordinates with prefectural governments to designate factory-built housing zones, streamlining permitting for modular developments. Stakeholders must track how evolving earthquake-resistance benchmarks and carbon-accounting rules for construction materials reshape procurement criteria for public and private projects alike.
Market Dynamics
Japan's prefabricated buildings sector is being fundamentally restructured by METI's carbon-neutral construction mandates, which favor factory-controlled production over conventional site-built methods for emissions compliance and quality standardization.
Growth Catalysts
- Greater Tokyo Area land scarcity:Extreme lot shortages in the capital region push developers toward vertical modular solutions that minimize on-site construction footprint and accelerate project timelines.
- METI building energy efficiency standards:Factory production achieves more consistent thermal performance and airtightness than site-built alternatives, creating regulatory alignment for modular procurement.
- Cross-laminated timber (CLT) engineering:Advanced wood panel systems satisfy rural prefecture aesthetic preferences while meeting seismic codes, expanding addressable housing stock.
Market Restraints
- JIS certification barriers:Stringent structural material standards create compliance friction for imported steel and engineered wood components, limiting supplier diversification.
- Specialized labor concentration:Factory production depends on skilled technicians concentrated in the Chubu and Kanto industrial corridors, creating geographic supply vulnerability.
- Site-built concrete substitution:Traditional cast-in-place methods retain cost advantages for large-scale commercial foundations, constraining modular penetration in certain building types.
Strategic Opportunities
- Disaster-preparedness public procurement:National land regulator coordination with prefectural governments designates factory-built housing zones for rapid emergency deployment.
- Smart-home manufacturing integration:Embedded IoT and energy management systems installed during factory assembly command premium positioning versus retrofitted alternatives.
- Osaka-Kobe corporate relocatable offices:Western Japan's commercial hub shows underpenetrated demand for modular workspace solutions serving project-based enterprise needs.
Industry Challenges
- Seismic-grade certification timelines:Updated earthquake-resistance benchmarks require extensive testing protocols that delay new product launches and factory retooling cycles.
- Legacy supply chain reconfiguration:Transition from site-centric to factory-centric logistics demands new transport infrastructure for oversized module delivery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Prefabricated Buildings Market |
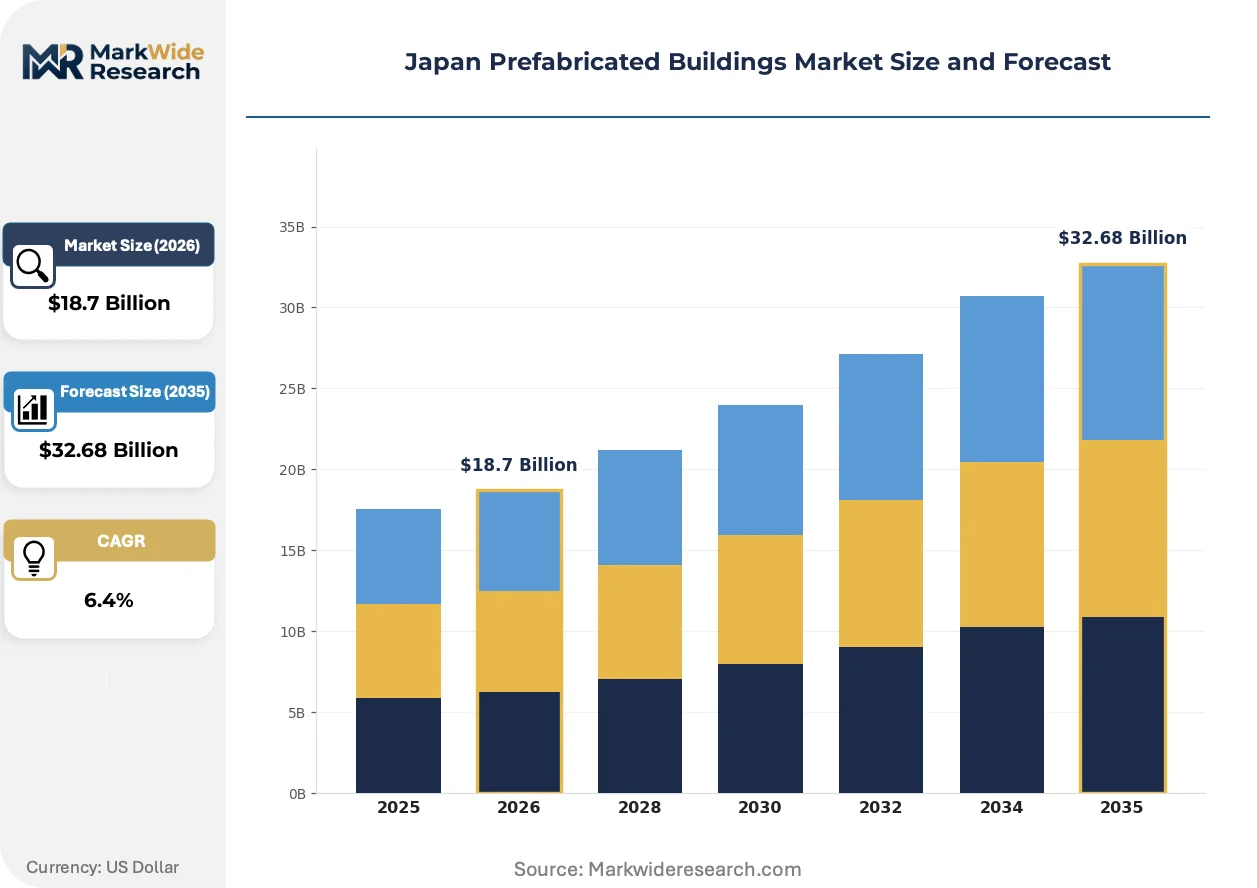
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Units, Commercial Spaces, Modular Offices, Industrial Structures Material: Steel, Concrete, Wood, Composite Application: Housing, Retail Outlets, Construction Sites, Disaster Relief Delivery Method: On-Site Assembly, Pre-Assembled Units, Custom Fabrication, Turnkey Solutions |
| Companies Covered | Sekisui House, Daiwa House Group, Panasonic Homes, Asahi Kasei Homes, Toyota Housing Corporation, Misawa Homes, Sumitomo Forestry, Sekisui Chemical, Shimizu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Prefabricated Buildings Market Trends and Innovations
Digital fabrication and policy-driven decarbonization are converging to transform how structural components are engineered, certified, and assembled across Japan's construction value chain.
Robotically welded steel frame systems with millimeter-level precision are displacing manual on-site fabrication for mid-rise residential structures. Major housing manufacturers deploy these automated production lines for standardized seismic joints. The technology compresses quality variation and labor dependency in ways conventional methods cannot replicate.
METI's push for carbon-neutral construction methods is accelerating factory-based building production through embodied carbon accounting rules. Factory environments enable precise material optimization and waste reduction versus site-built alternatives. Steel-framed residential units face the most immediate compliance pressure under these evolving benchmarks.
Corporate buyers in Tokyo and Osaka now specify relocatable modular offices with embedded decommissioning clauses. Leasing structures replace traditional capital expenditure models for temporary workspace needs. This pattern concentrates in technology and financial services sectors with project-based team scaling requirements.
Japan Prefabricated Buildings Market Segmentation
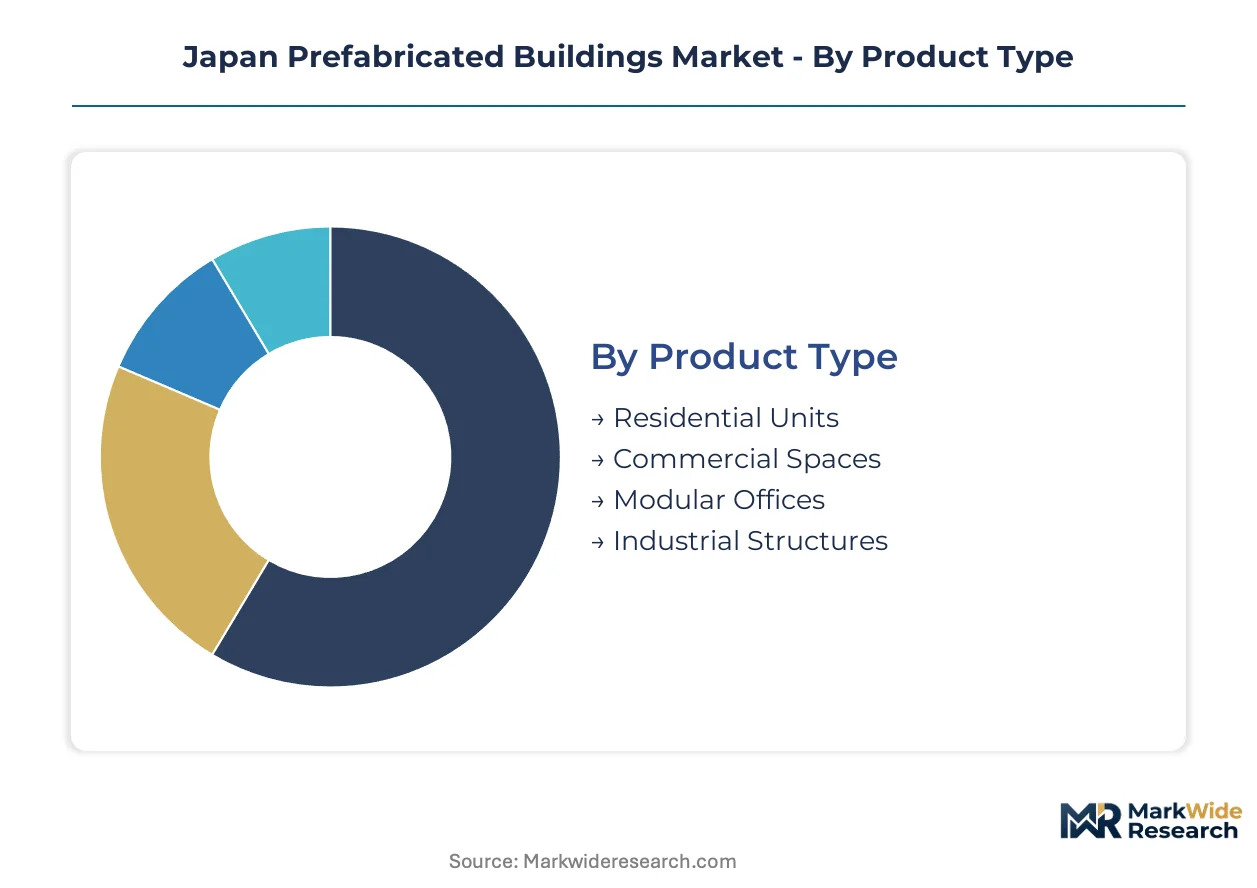
Segmentation reveals how factory-based construction methods map onto distinct procurement channels across Japan's built environment. Each dimension exposes different pressure points: material selection drives regulatory compliance, while delivery method determines project timeline compression.
Product Type:
Channel flow diverges sharply between permanent housing procurement through integrated manufacturers and temporary workspace solutions sourced via commercial leasing platforms.
- Residential Units:Steel-framed dwellings with millimeter-precision factory assembly dominate output volumes. Demand concentrates in Greater Tokyo Area infill developments where land scarcity accelerates vertical modular adoption.
- Commercial Spaces:Retail and hospitality modules deploy through corporate real estate channels with embedded decommissioning clauses. Osaka-Kobe corridor shows strongest uptake among project-based enterprises requiring relocatable footprint.
- Modular Offices:Technology and financial services sectors drive specification for IoT-ready units with factory-installed building management systems.
- Industrial Structures:Warehouse and logistics facilities utilize standardized steel framing for rapid deployment in designated factory-built housing zones.
By volume, Residential Units leads. By growth pace, Modular Offices is climbing the fastest.
Material:
Cost tier stratification separates premium seismic-grade steel from rural wood alternatives, with composite systems occupying emerging mid-market positioning.
- Steel:Hot-rolled and cold-formed structural sections achieve JIS certification for earthquake-resistant joint systems. METI carbon-accounting rules intensify embodied emissions scrutiny on steel production methods.
- Concrete:Precast panels retain foundation and core wall applications where cast-in-place methods face factory competition. Chubu industrial corridor hosts specialized precasting facilities serving commercial projects.
- Wood:Cross-laminated timber and engineered-laminate technologies satisfy rural prefecture aesthetic preferences while meeting updated seismic codes.
- Composite:Hybrid steel-timber and steel-concrete systems optimize strength-to-weight ratios for mid-rise applications in dense urban zones.
Steel commands the largest share of current procurement spend. Composite materials are gaining share fastest as manufacturers balance seismic performance against carbon intensity targets.
Application:
Customer type segmentation separates individual homebuyers accessing mortgage-linked manufacturer financing from institutional buyers with capital deployment flexibility.
- Housing:Owner-occupied and rental units flow through Sekisui House and Daiwa House Group direct sales networks with integrated land acquisition services.
- Retail Outlets:Convenience store chains and automotive showrooms specify standardized footprints with rapid installation protocols for franchise expansion.
- Construction Sites:Temporary site offices and worker dormitories deploy through equipment leasing channels with short-term rental structures.
- Disaster Relief:National land regulator coordinates public procurement of emergency housing stock pre-positioned in designated factory-built zones.
Housing absorbs the greatest absolute unit volume. Disaster Relief exhibits the steepest expansion trajectory as prefectural governments expand preparedness budgets.
Delivery Method:
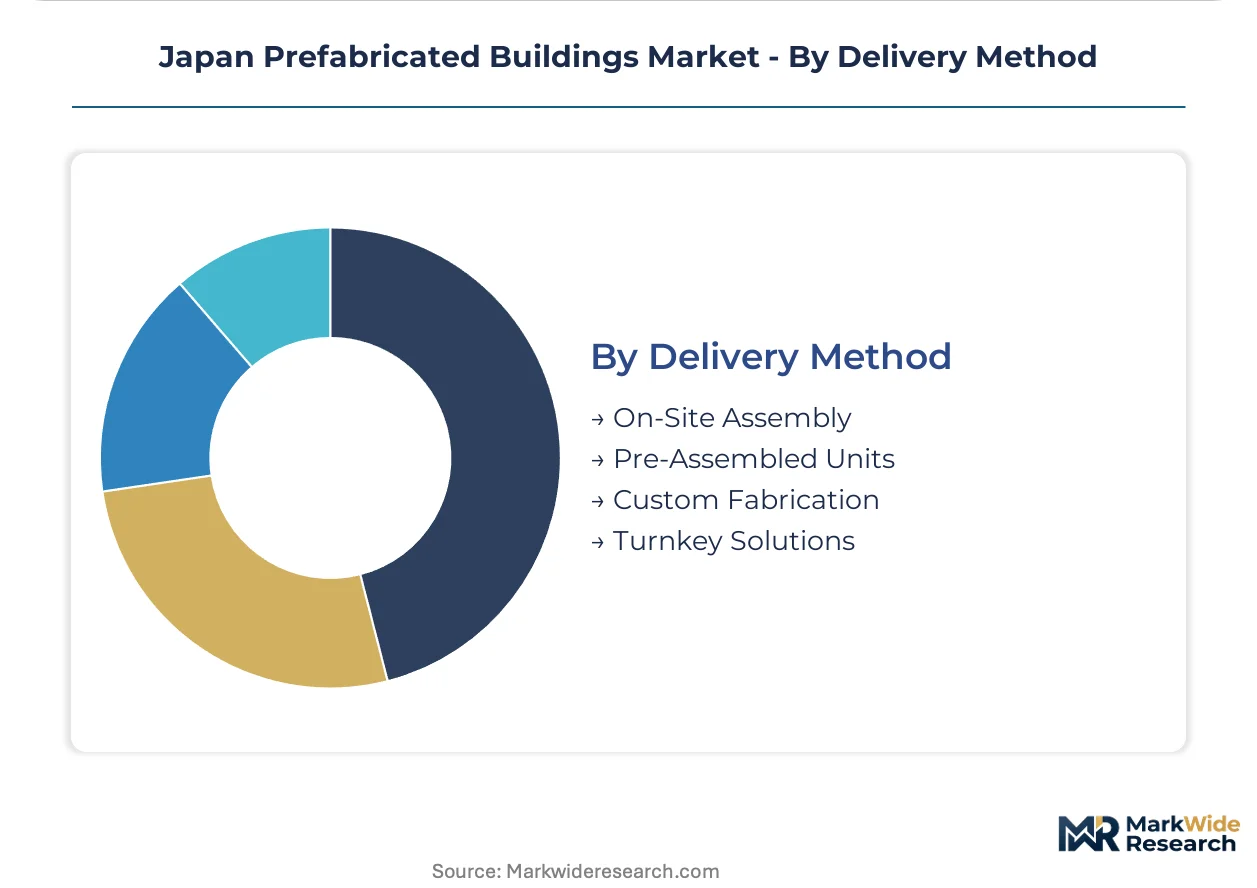
Supply concentration determines which delivery modes dominate: captive manufacturer fleets control pre-assembled transport, while specialized logistics providers serve fragmented on-site assembly demand.
- On-Site Assembly:Component kit delivery suits remote prefectures where module transport faces infrastructure constraints. Skilled technician deployment from Chubu and Kanto corridors creates geographic bottlenecks.
- Pre-Assembled Units:Volumetric modules complete with MEP rough-in demand heavy-lift transport infrastructure and route planning for oversized loads.
- Custom Fabrication:Architect-specified non-standard dimensions flow through design-build contracts with extended factory retooling cycles.
- Turnkey Solutions:Land acquisition through certificate of occupancy bundled offerings target individual buyers in Greater Tokyo Area with premium positioning.
Pre-Assembled Units represents the dominant delivery mode by project count. Turnkey Solutions is expanding most quickly as manufacturers capture margin from vertical integration into land development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese prefabricated building exports flow primarily to Southeast Asian markets, where Japanese construction standards command premium positioning in commercial and residential developments.
Kanto/Tokyo
Land scarcity and vertical development pressures concentrate prefabricated housing demand in the Greater Tokyo Area. METI designates factory-built housing zones across Saitama and Chiba prefectures to streamline permitting. Yokohama-Kawasaki industrial corridor hosts Sekisui House and Daiwa House Group production facilities serving the capital region.
Kansai/Osaka
Corporate relocatable office demand from technology and financial services sectors drives modular workspace procurement. Osaka prefecture coordinates with the national land regulator on designated factory-built zones for commercial development. Amagasaki and Sakai production clusters supply western Japan's commercial modular segment.
Chubu/Nagoya
Automotive industry supplier networks create adjacent demand for industrial prefabricated structures. Aichi prefecture maintains specialized technician training programs for factory production lines. Toyota Housing Corporation anchors manufacturing operations in this corridor with captive supply chain integration.
Kyushu
Disaster preparedness budgets from Fukuoka and Kumamoto prefectures expand emergency housing stock procurement. JIS certification requirements for seismic-grade materials shape local supplier relationships. Kitakyushu industrial zone hosts precast concrete panel facilities serving commercial foundation applications.
Tohoku
Post-disaster reconstruction programs sustain demand for rapid-deployment residential units. Miyagi and Fukushima prefectures coordinate with METI on carbon-neutral construction pilot projects. Sendai functions as distribution hub for modular components serving rural prefectures with infrastructure constraints.
Japan Prefabricated Buildings Market Competitive Landscape
Listed leaders compete with private specialists across integrated land development and factory production capabilities. The sector exhibits consolidated structure at the manufacturing tier with fragmented regional distribution. Three archetypes dominate: vertically integrated housing manufacturers, technology-embedded smart home specialists, and diversified construction conglomerates with modular divisions. Capacity expansion and strategic partnerships represent the primary competitive moves as firms secure JIS-certified material supply and designated zone development rights.
Among integrated housing manufacturers, Sekisui House, Daiwa House Group, and Panasonic Homes exemplify distinct strategic positioning within the market. Sekisui House occupies a position emphasizing supply chain control from factory floor through final assembly. Daiwa House Group represents the R&D-intensive archetype focused on structural system innovation. Panasonic Homes sits within the technology-embedded tier, differentiating through manufacturing-stage smart home integration rather than site-based retrofitting.
| Leading Market Players |
|---|
| Sekisui House |
| Daiwa House Group |
| Panasonic Homes |
| Asahi Kasei Homes |
| Toyota Housing Corporation |
| Misawa Homes |
| Sumitomo Forestry |
| Sekisui Chemical |
| Shimizu Corporation |
| Others |
Pricing and Supply Chain Analysis
Long-term capacity reservation contracts with JIS-certified steel mills lock in supply access and price visibility for Japanese prefabricated housing manufacturers. These arrangements insulate Sekisui House and Daiwa House Group from spot volatility in structural steel while embedding carbon-accounting compliance costs into fixed pricing schedules.
Pricing Analysis
Next-generation robotically welded frame systems command 15-20% premiums over manually fabricated equivalents, while legacy panelized construction faces margin compression. Three-tier pricing structure across premium seismic-grade, standard JIS-certified, and economy non-residential tiers reflects certification level and factory automation intensity. Pricing pressure stems from METI's embodied carbon accounting rules elevating low-emission steel procurement costs. Individual homebuyers in Greater Tokyo exhibit highest price sensitivity, while corporate relocatable office buyers prioritize speed-to-occupancy over unit economics.
Supply Chain Analysis
Inbound logistics costs from South Korean and Chinese steel suppliers through congested Yokohama and Kobe port facilities elevate landed material expenses for Chubu and Kanto production corridors. Geographic supply concentration centers on domestic steel from Chiba and Okayama mills, cross-laminated timber from Austrian and Canadian exporters, and engineered joint hardware from German specialists. Raw material dependencies include hot-rolled structural sections, seismic isolation bearings, and factory-applied fireproofing coatings. Single-source vulnerability permeates specialized welding robot maintenance networks. Distribution runs through captive manufacturer fleets for volumetric modules and specialized heavy-lift contractors for oversized loads.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's prefabricated buildings sector functions as a service-attach opportunity where factory-embedded smart home systems and post-occupancy energy management subscriptions expand faster than structural hardware sales. Recurring revenue from IoT platform fees and predictive maintenance contracts now exceeds margin contributions from initial module delivery for technology-integrated manufacturers.
For Market Incumbents: Consolidate control over JIS-certified material supply through backward integration into steel processing and captive CLT sourcing partnerships. Secure designated factory-built housing zone development rights ahead of prefectural allocation rounds. METI's escalating carbon-accounting requirements threaten margin structures for manufacturers lacking emissions-verified supply chains. For New Entrants and Emerging Players: JIS certification fast-track programs for cross-laminated timber and composite structural systems open entry pathways without competing directly on seismic steel expertise. White-space targets include disaster-relief emergency housing stockpiles in Kyushu and Tohoku, plus corporate relocatable offices in underpenetrated Osaka-Kobe technology corridors. Partner with regional equipment leasing platforms for temporary site office deployment rather than building direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward vertically integrated manufacturers with captive land development capabilities and established prefectural government relationships. Long-term viability hinges on positioning for carbon-neutral construction mandates tightening across the analysis window. Acquisition target archetype: mid-scale producers with JIS certification assets and underutilized factory capacity in Chubu or Kansai corridors. Monitor METI's evolving earthquake-resistance benchmark announcements as inflection indicators for factory retooling investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| JIS Certification Investment | Unlocks public procurement eligibility under METI's designated factory-built housing zone programs. |
| Smart Home Platform Integration | Captures recurring service revenue from energy management subscriptions attached to factory-installed IoT infrastructure. |
| CLT Supply Chain Partnership | Secures rural prefecture market access where engineered wood aesthetics align with seismic performance requirements. |
| Prefectural Zone Development Rights | Establishes permitting priority for modular projects in Saitama, Chiba, and Osaka coordinated land allocations. |
| Carbon Accounting System Deployment | Satisfies METI's embodied emissions disclosure mandates for steel-framed residential unit compliance. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with factory production managers, prefectural housing policy officers, corporate real estate procurement leads, and JIS certification auditors; alongside secondary validation through METI construction statistics, national land regulator zone designation records, and steel industry trade flow data. Bottom-up unit shipment estimates by product type and material category triangulated against top-down construction spend projections across the Greater Tokyo Area, Kansai corridor, and Tohoku reconstruction zones.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation dimensions spanning product type, material grade, application channel, and delivery method. CAGRs derived from historical shipment trajectories adjusted for METI policy implementation timelines and prefectural procurement budget cycles. Industry-specific forecast inputs incorporated seismic code revision schedules, CLT import tariff exposure, and factory automation penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained METI carbon-neutral enforcement, stable JIS certification timelines, and intact Chubu-Kanto technician labor pools would require recalibration. Forecasts reflect documented assumptions regarding prefectural disaster preparedness budget trajectories and corporate relocatable office adoption patterns. Practitioners should keep alternative scenarios live as earthquake-resistance benchmark evolution and steel supply chain reconfiguration dynamics unfold.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Saudi Arabia Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Construction Market
Building Construction
UAE Construction Market
Building Construction
Early Production Facility Market
Building Construction
Kuwait Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
El Salvador Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
Scandinavia Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
India Prefabricated Buildings Market