
 Indonesia Prefabricated Buildings Market | 2026-2036
Indonesia Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Prefabricated Buildings Market Foresight
Direct-to-contractor distribution is reshaping how prefabricated building components reach Indonesian construction sites. PT Wijaya Karya (WIKA) Building leverages its state-linked project pipeline to dominate public-sector prefab procurement. PT Hutama Karya anchors large-scale infrastructure deployments with captive manufacturing capacity. Kirby Building Systems competes through imported steel framing systems tailored to seismic specifications.
Prefabricated buildings encompass factory-produced structural modules assembled on location, typically employing steel frames, precast concrete panels, or engineered wood composites manufactured to tolerances of one to three millimeters. These systems serve Indonesia's need for rapid, standardized construction across flood-prone and earthquake-active zones. Modular Homes command the deepest residential margin pools as urban land scarcity intensifies in Jakarta and Surabaya. Steel-based Prefab Industrial units lead volume throughput due to warehouse and factory demand from Batang and Karawang industrial estates. Off-site Manufacturing deployment is gaining fastest traction as contractors seek to compress project schedules amid skilled-labor shortages.
BIS standards govern structural material certification, while Indonesia's national building codes enforced by the Ministry of Public Works and Housing mandate seismic resilience ratings for prefabricated assemblies. The country's PLI scheme for construction materials incentivizes domestic panel and frame production, reshaping supplier localization requirements. Stakeholders must track evolving local-content thresholds and seismic-code amendments to secure project approvals and maintain cost competitiveness against conventional build methods.
Market Dynamics
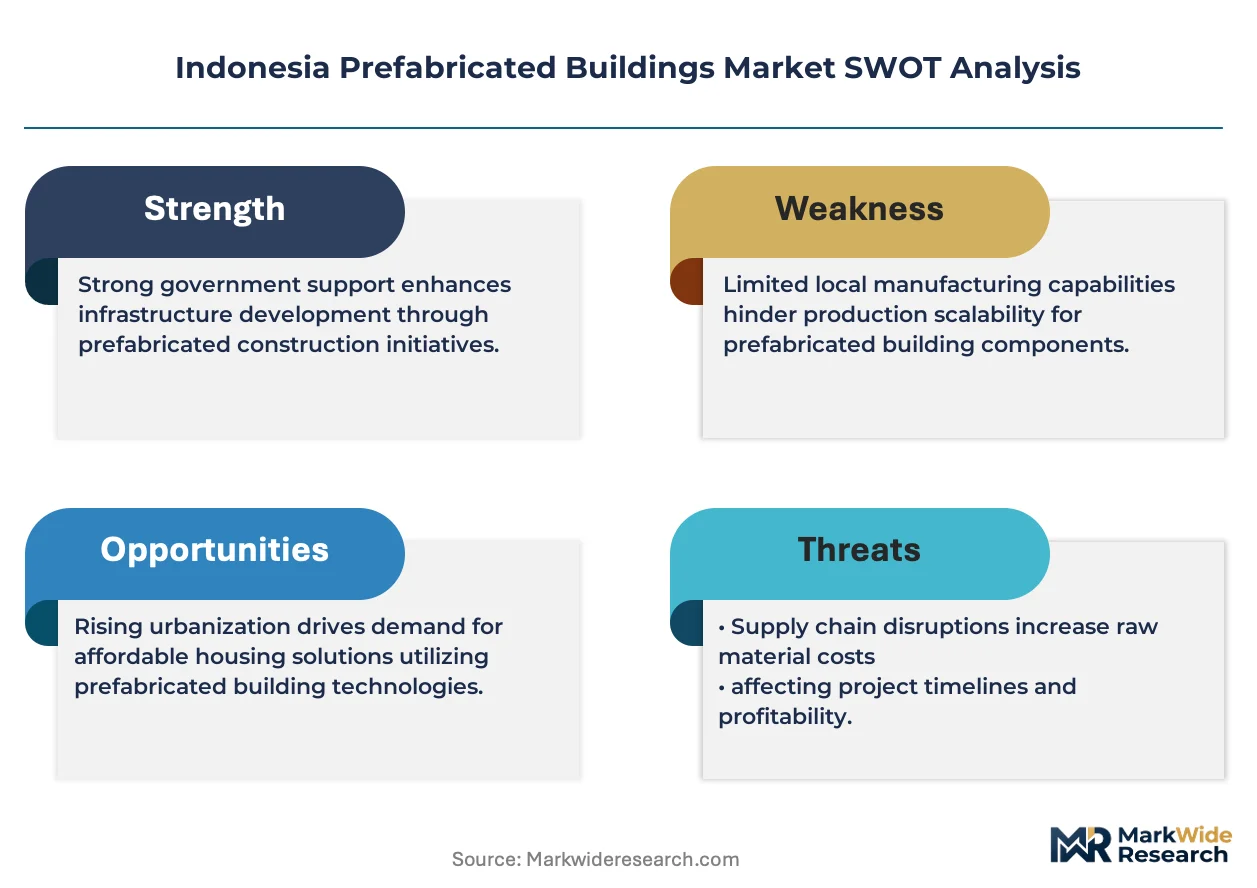
Indonesia's prefabricated buildings sector pivots on the collision between government-mandated seismic resilience standards and acute shortages of skilled site labor. The Ministry of Public Works and Housing is tightening enforcement of national building codes while contractors face compressed project timelines.
Growth Catalysts
- PLI Scheme for Construction Materials:Domestic production incentives for structural panels and steel frames are lowering import dependency among Batang and Karawang industrial estate developers.
- Java's Industrial Corridors:Warehouse and factory demand from automotive and electronics manufacturers is pulling steel-based prefab units into high-volume deployment.
- Seismic Code Alignment:BIS certification requirements for structural steel are standardizing quality benchmarks that prefabricated systems can reliably meet.
Market Restraints
- Hot-Rolled Steel Price Volatility:Input cost swings for structural steel frames compress margin predictability for fabricators serving Greater Jakarta residential zones.
- Import Dependency for Engineered Wood Composites:Concentrated supply from Southeast Asian processors creates vulnerability for modular home producers targeting Surabaya's urban infill projects.
- Site Assembly Skill Gaps:Limited availability of certified erection crews capable of achieving one-to-three-millimeter tolerances extends commissioning timelines.
Strategic Opportunities
- Eastern Indonesia Archipelago:Underpenetrated demand in Sulawesi and Papua for disaster-resistant housing creates first-mover positioning for seismic-rated panel systems.
- Off-Site Manufacturing Convergence:Integration of BIM workflows with factory automation is compressing design-to-delivery cycles for contractors facing labor scarcity.
- Direct-to-Contractor Channels:Bypassing traditional distributor markups through digital procurement platforms is capturing margin for component suppliers.
Industry Challenges
- BIS Certification Timelines:Extended approval cycles for imported steel framing systems delay project mobilization and strain contractor cash flow.
- Legacy Site-Built Integration:Mismatched tolerances between prefabricated modules and conventional concrete foundations generate field rework costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Prefabricated Buildings Market |
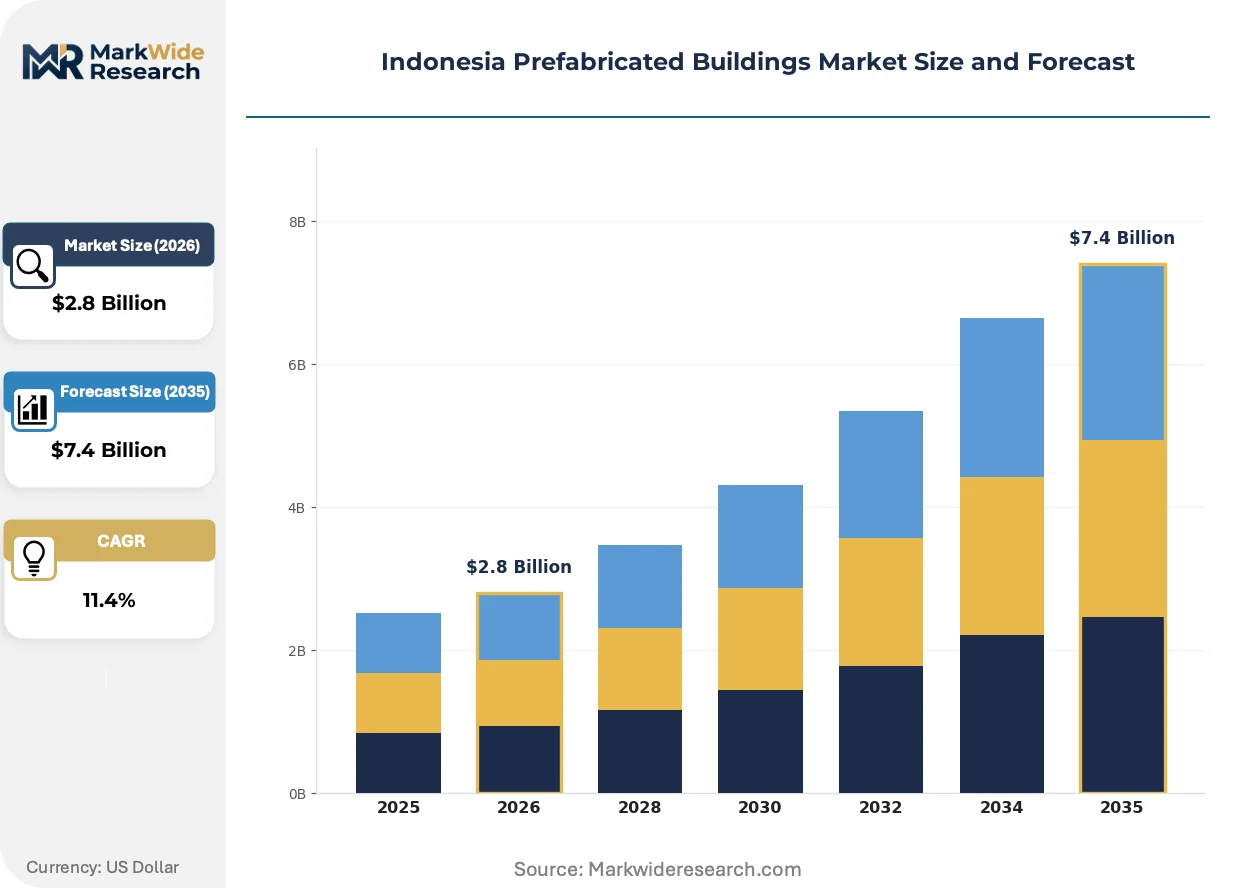
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefab Commercial, Prefab Industrial, Temporary Structures Material: Wood, Steel, Concrete, Composite End User: Residential Developers, Government Projects, Construction Firms, Commercial Developers Deployment: On-site Assembly, Off-site Manufacturing, Hybrid Solutions, Custom Projects |
| Companies Covered | PT Bukaka Teknik Utama Tbk, PT Hutama Karya, PT Wijaya Karya (WIKA) Building, PT Touchwood, DTH Prefab, Kirby Building Systems, PT Summarecon Prefab, Sanwa Prefab Technology, Bali Prefab, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Prefabricated Buildings Market Shifts & Advancements
Digital fabrication workflows and regulatory tightening are compressing traditional construction paradigms. Three convergent forces are redefining how structural modules reach Indonesian sites.
Building Information Modeling (BIM) is virtualizing design-to-fabrication handoffs by embedding seismic load calculations directly into factory cutting instructions. Major contractors in Greater Jakarta are adopting these workflows to eliminate dimensional errors before steel reaches site. The technology is virtualizing quality assurance steps that previously required multiple inspection rounds.
Indonesia's Ministry of Public Works and Housing is escalating enforcement of seismic resilience ratings for prefabricated assemblies. The policy is forcing fabricators to recertify legacy connection details and invest in higher-grade steel specifications. Modular residential projects in flood-prone zones face the steepest compliance ramps.
Contractor purchasing is fragmenting across project-specific procurement platforms that bypass established distributor networks. Component suppliers are establishing captive sales teams to capture margin previously lost to intermediaries. This channel shift is most visible among warehouse developers in Karawang industrial estates seeking direct pricing leverage.
Indonesia Prefabricated Buildings Market Segmentation
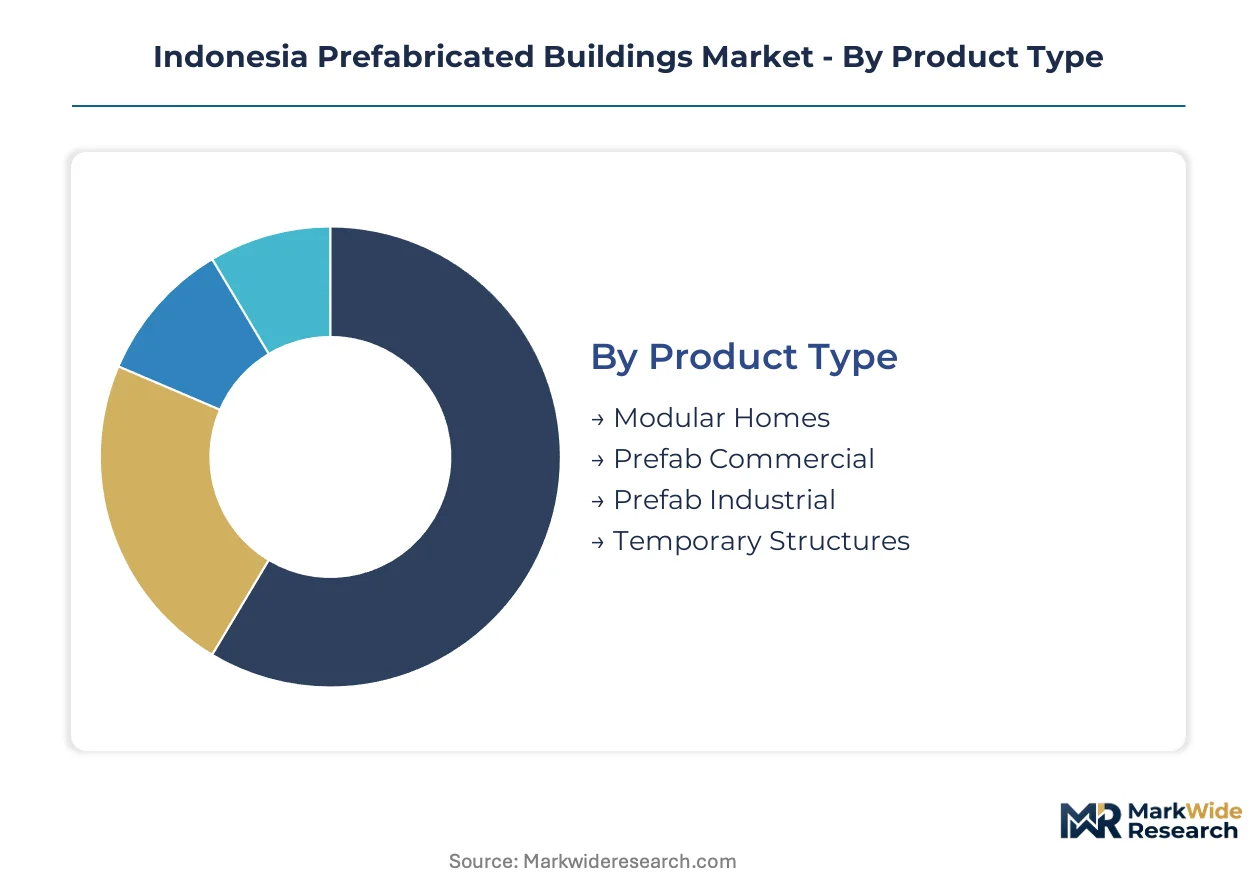
Segmentation reveals how Indonesia's prefabricated buildings market fragments across structural applications, material specifications, and procurement channels. Each dimension exposes distinct margin profiles and regulatory exposure that shape supplier positioning.
Product Type:
Application focus determines volume scale and margin depth across Indonesia's construction procurement landscape.
- Modular Homes:Factory-produced residential units employing engineered wood or steel framing achieve one-to-three-millimeter tolerances for rapid urban infill. Demand concentrates in Greater Jakarta and Surabaya where land scarcity intensifies developer interest in vertical density solutions.
- Prefab Industrial:Steel-framed warehouse and factory modules dominate throughput from Batang and Karawang industrial estates serving automotive and electronics manufacturers. The PLI scheme for construction materials is accelerating domestic panel production for these deployments.
- Prefab Commercial:Mid-rise office and retail structures balance speed-to-market with design flexibility for Jakarta's emerging business districts.
- Temporary Structures:Rapid-assembly pavilions and emergency housing serve disaster response and event infrastructure needs across Java's population centers.
Prefab Industrial commands the established base. The steepest expansion runs through Modular Homes.
Material:
Cost tier and seismic performance requirements segment supplier capabilities across Indonesia's regulatory environment.
- Steel:Hot-rolled and cold-formed structural sections achieve BIS certification for seismic resilience ratings mandated by the Ministry of Public Works and Housing. Price volatility in global steel markets compresses margin predictability for fabricators serving industrial estate developers.
- Concrete:Precast panels and tilt-up systems anchor permanent foundations in flood-prone zones where thermal mass and durability outweigh speed considerations. Demand clusters in government infrastructure programs with extended asset-life requirements.
- Wood:Engineered timber and cross-laminated panels offer carbon-conscious alternatives for low-rise residential and hospitality applications in Bali and Yogyakarta heritage districts.
- Composite:Fiber-reinforced polymer and hybrid material systems address specialized corrosion resistance for coastal and chemical-processing environments.
Steel maintains volume leadership. Composite materials are climbing the fastest as performance specifications tighten.
End User:
Customer type dictates procurement protocols, payment terms, and certification documentation burdens.
- Government Projects:State-linked infrastructure deployments through the Ministry of Public Works and Housing require extensive BIS documentation and local-content compliance. PT Wijaya Karya leverages its captive project pipeline to dominate this channel.
- Residential Developers:Private-sector housing builders in Greater Jakarta prioritize speed-to-market and design customization for luxury and mid-market segments.
- Construction Firms:General contractors integrating prefab modules into mixed-build projects face tolerance-matching challenges with legacy concrete foundations.
- Commercial Developers:Warehouse and logistics facility operators in Karawang industrial estates drive direct-to-contractor procurement for cost leverage.
Government Projects anchor procurement volume. Residential Developers are expanding most quickly as urban land constraints intensify.
Deployment:
Maturity of off-site integration separates efficiency leaders from conventional site-built competitors.
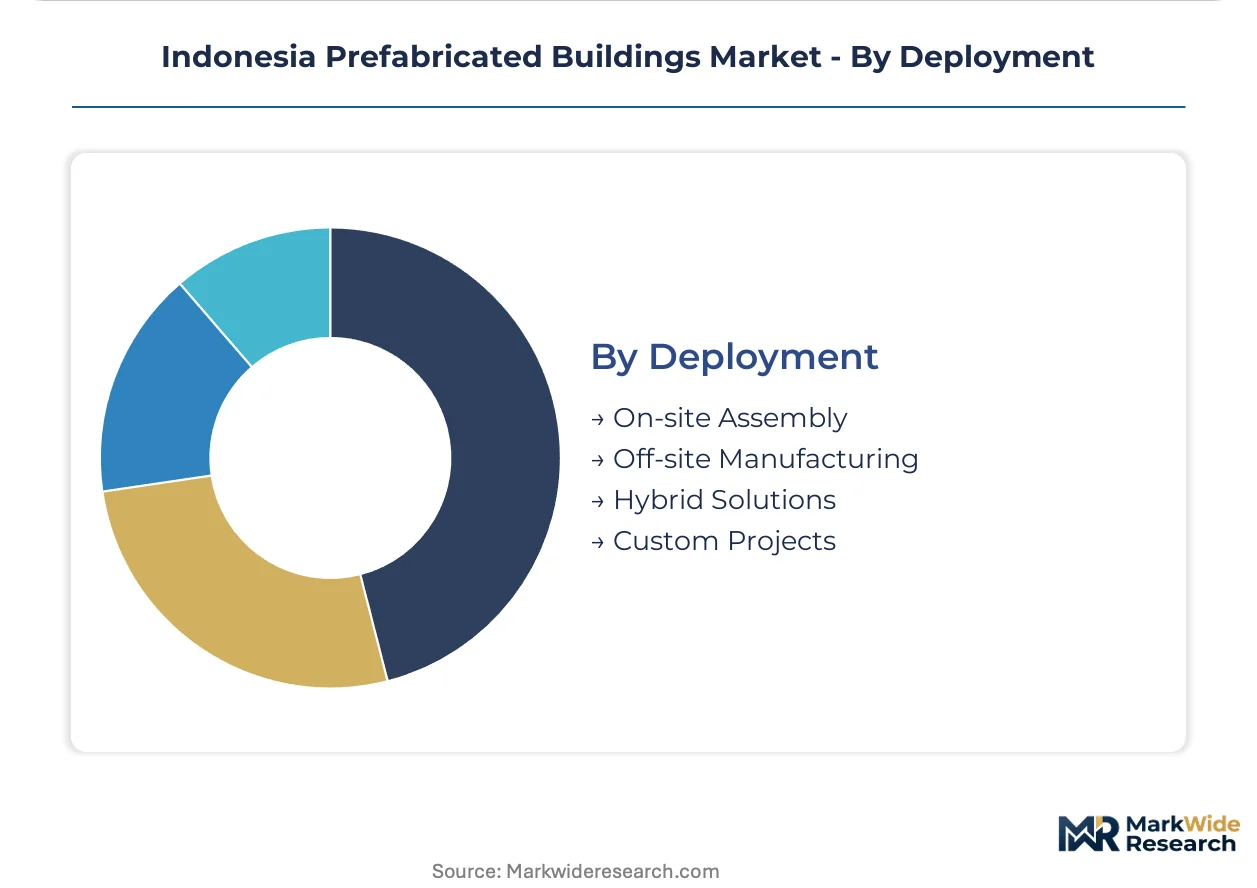
- Off-site Manufacturing:Factory-controlled production with BIM-integrated cutting instructions eliminates dimensional errors before modules reach Java's construction sites. Skilled-labor shortages are accelerating contractor adoption of these workflows.
- Hybrid Solutions:Partial prefabrication of structural frames combined with site-finished interiors balances speed with localized design adaptation for Indonesian architectural preferences.
- On-site Assembly:Traditional prefab panel erection persists in remote geographies where transportation infrastructure limits module delivery.
- Custom Projects:Bespoke modular designs for flagship commercial or institutional buildings command premium pricing but extend design-to-delivery cycles.
Hybrid Solutions retain the largest installed base. Off-site Manufacturing is gaining share fastest as digital fabrication workflows mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Public Works and Housing anchors regulatory oversight across Indonesia's prefabricated buildings sector, with demand clustering in Java's industrial corridors and residential zones. Regional deployment patterns reflect varying infrastructure maturity, seismic exposure, and industrial estate concentration.
Java
Greater Jakarta and Surabaya drive residential modular demand as urban land scarcity intensifies vertical density solutions. The Ministry's seismic resilience ratings mandate BIS-certified steel specifications for all prefabricated assemblies. Karawang and Batang industrial estates pull high-volume steel-based warehouse modules from captive manufacturing facilities.
Sumatra
Medan and Palembang anchor commercial prefab demand for logistics and retail infrastructure serving palm oil and mining supply chains. The PLI scheme for construction materials incentivizes domestic panel production, reducing import dependency for industrial estate developers. Batam's free trade zone attracts cross-border prefab component flows from Singapore-based suppliers.
Sulawesi
Makassar and Manado present underpenetrated demand for disaster-resistant housing in earthquake-active and flood-prone zones. Local-content thresholds under national building codes complicate project approvals for imported structural systems. The nickel processing corridor around Morowali is pulling temporary prefab worker accommodations from regional fabricators.
Kalimantan
Balikpapan and Samarinda concentrate demand for modular industrial facilities serving oil, gas, and coal operations. BIS certification timelines for imported steel framing strain contractor mobilization schedules. The new capital city development at Nusantara is generating procurement volume for standardized government building modules.
Bali and Nusa Tenggara
Denpasar and Lombok hospitality projects favor engineered timber and low-rise modular solutions for heritage-sensitive districts. Seismic code alignment requirements are accelerating adoption of factory-certified connection details. Tourism infrastructure recovery is pulling rapid-assembly pavilion systems for event and accommodation use.
Indonesia Prefabricated Buildings Market Competitive Landscape
State-linked contractors and independent fabricators split the market along procurement channel lines. PT Wijaya Karya leverages its captive public-sector pipeline to dominate government-linked deployments. Three strategic archetypes define competitive positioning: state-owned infrastructure specialists with integrated manufacturing, private industrial estate developers with direct-to-contractor channels, and imported-system distributors serving seismic-specification niches. Capacity expansion and BIS certification investments represent the dominant competitive moves as quality benchmarks tighten.
Among state-owned specialists, PT Wijaya Karya and PT Hutama Karya occupy positions anchored by public infrastructure pipelines. Kirby Building Systems represents the imported-technology archetype, with steel framing systems positioned for seismic-resilience applications. PT Bukaka Teknik Utama Tbk sits within the diversified engineering tier, exemplifying contractors with manufacturing backward integration into structural components.
| Leading Market Players |
|---|
| PT Bukaka Teknik Utama Tbk |
| PT Hutama Karya |
| PT Wijaya Karya (WIKA) Building |
| PT Touchwood |
| DTH Prefab |
| Kirby Building Systems |
| PT Summarecon Prefab |
| Sanwa Prefab Technology |
| Bali Prefab |
| Others |
Supply & Pricing Matrix
Karawang industrial estate's captive steel fabrication capacity shapes downstream pricing power for warehouse developers across Greater Jakarta. Batang's emerging panel production clusters under Indonesia's PLI scheme are compressing import-dependent pricing tiers for structural components.
Pricing Analysis
Greater Jakarta commands a 15-25% premium over Surabaya for BIS-certified steel modules due to logistics and land costs. Three-tier pricing structure across premium seismic-rated, standard industrial-grade, and economy temporary structures dominates procurement. Cost compression in economy tiers is intensifying because hot-rolled steel volatility feeds directly into fabricator margins. Residential developers in urban infill zones show highest price sensitivity, while government infrastructure programs prioritize certification compliance over unit cost.
Supply Chain Analysis
Hot-rolled steel feedstock draws from China, Japan, and South Korea, with BIS certification adding 6-8 week processing delays at Indonesian ports. Structural steel sections, engineered wood composites, and precast concrete additives constitute the critical input trinity. Single-source vulnerability concentrates in high-grade seismic connection hardware from Japanese specialty suppliers. Distribution runs through direct-to-contractor digital platforms bypassing traditional distributor markups, particularly among Karawang warehouse operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's prefabricated buildings sector functions as a service-attach opportunity where BIM-integrated project management and post-assembly maintenance contracts expand faster than component hardware sales. After-sales seismic recertification and module retrofit services are capturing recurring revenue streams from government infrastructure portfolios.
For Market Incumbents: Pre-empt margin erosion from direct-to-contractor platforms by consolidating captive fabrication capacity in Batang and Karawang industrial corridors. Lock in BIS certification pipelines before regulatory timelines extend further. Channel control through state-linked project pipelines remains the priority defensive lever against private-sector procurement digitization. For New Entrants and Emerging Players: Build out Eastern Indonesia distribution infrastructure targeting Sulawesi and Papua disaster-resistant housing demand where local-content thresholds have kept imported systems at bay. The nickel processing corridor around Morowali presents the most penetrable near-term anchor for temporary worker accommodation contracts. Lead with seismic-rated panel systems certified under Ministry of Public Works and Housing protocols to bypass incumbent state-owned relationships. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified engineering conglomerates with underutilized structural component manufacturing arms. Long-term viability hinges on regulatory compliance infrastructure rather than pure capacity scale. Watch for BIS certification backlog clearance rates as the inflection signal for fabrication margin recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Rolling | Captive hot-rolled capacity insulates PT Wijaya Karya from import price volatility and BIS delays. |
| BIM-Platform Acquisition | Digital fabrication workflows compress design-to-delivery cycles for contractors facing Java labor scarcity. |
| Eastern Indonesia Distribution Partnership | Local logistics alliances bypass Sulawesi and Papua infrastructure gaps that constrain module delivery. |
| Seismic Recertification Service Launch | Recurring compliance revenue attaches to government infrastructure portfolios with mandatory inspection cycles. |
| PLI Scheme Localization Investment | Domestic panel production qualifies Batang and Karawang facilities for construction material incentives. |
Research Methodology
The analysis maps modular residential, prefab industrial, and temporary structure sub-sectors, each validated through contractor procurement directors, Ministry of Public Works and Housing compliance officers, steel fabricator plant managers, and industrial estate development leads. Primary interview intelligence triangulates against BIS certification databases, Ministry infrastructure program disclosures, PLI scheme participant registries, and customs import records for structural steel and engineered wood composites. Bottom-up project pipeline aggregation and top-down construction sector output modeling cross-validate volume estimates.
Fixed assumptions across the modeling period include continued PLI scheme eligibility for domestic panel production, steady-state BIS certification processing capacity, and no seismic code downgrades. Segmentation dimensions encompass product type, material specification, end-user procurement channel, and deployment maturity tier. CAGRs derive from regression against historical construction sector capital formation and industrial estate absorption rates, with sensitivity testing around steel price volatility bands and skilled labor availability scenarios.
Practitioners should monitor BIS certification timeline extensions, PLI scheme local-content threshold adjustments, and hot-rolled steel import duty modifications for early signals of forecast deviation. Cross-checking against Ministry of Public Works and Housing infrastructure budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
North America Construction Market
Building Construction
GCC Advanced Buildings Materials Market
Building Construction
China Construction Market
Building Construction
El Salvador Construction Market
Building Construction
Global Dry Construction Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
Vietnam Prefabricated Buildings Market
Building Construction
Kuwait Construction Market
Building Construction
GCC Green Buildings Market
Building Construction
Sweden New Construction Market
Building Construction
Latin America Construction Market
Building Construction
US Modular Construction Market
Building Construction
Africa Construction Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
Bangladesh Construction Market
Building Construction
China Prefabricated Buildings Market