
 Middle East Data Center Construction Market | 2026-2036
Middle East Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Data Center Construction Market Insights
A shift from single-source EPC contracts toward multi-source procurement with specialized subcontractors is restructuring how mega-facilities get delivered across the GCC. Khazna Data Centers leverages its vertically integrated development model to compress delivery timelines for hyperscale clients. Gulf Data Hub anchors the UAE's wholesale colocation segment through its Dubai-centric campus strategy. ALEC Engineering & Contracting competes by combining civil works with MEP self-performance, reducing interface risk on complex builds.
Middle East data center construction encompasses the engineering, procurement, and construction of mission-critical facilities housing IT infrastructure, with specifications typically requiring tier III or tier IV redundancy, power densities exceeding 15 kW per rack, and precision cooling maintaining temperatures within ASHRAE guidelines. These facilities serve as the physical backbone for cloud computing, financial transaction processing, and sovereign data storage across the Arabian Peninsula. Hyperscale data centers capture the dominant share of capital deployment as global cloud operators expand regional footprints, while modular data centers are gaining traction among enterprises requiring rapid, phased capacity additions in secondary cities. Turnkey solutions command premium pricing relative to onsite construction due to the integration risk absorbed by single-point-responsibility contractors.
SFDA guidelines on pharmaceutical data integrity and MOHAP health information standards in the UAE are extending compliance requirements to data center operators hosting regulated workloads, tightening facility certification demands. Saudi Arabia's central bank and the UAE's telecommunications regulator enforce data residency rules that prohibit cross-border storage of citizen financial records, directly stimulating domestic construction. Stakeholders must weigh sovereign facility commitments against emerging edge computing architectures that could redistribute capacity requirements toward smaller, distributed nodes.
Market Dynamics
Data localization mandates from Saudi Arabia's communications regulator and the UAE's telecommunications authority are compelling hyperscale operators to build sovereign infrastructure rather than serve regional demand from European or Asian hubs. This regulatory pressure is restructuring procurement timelines and capital allocation across the Gulf construction sector.
Growth Catalysts
- Financial data residency rules:Saudi Arabia's central bank prohibits cross-border storage of citizen financial records, forcing banks and payment processors to commission domestic Tier IV facilities.
- Smart city infrastructure:Government-backed programs in Riyadh and Dubai are absorbing hyperscale capacity as municipal digitization accelerates demand for localized compute and storage.
- Pharmaceutical compliance:SFDA guidelines on data integrity and MOHAP health information standards extend certification requirements to data center operators hosting regulated workloads.
Market Restraints
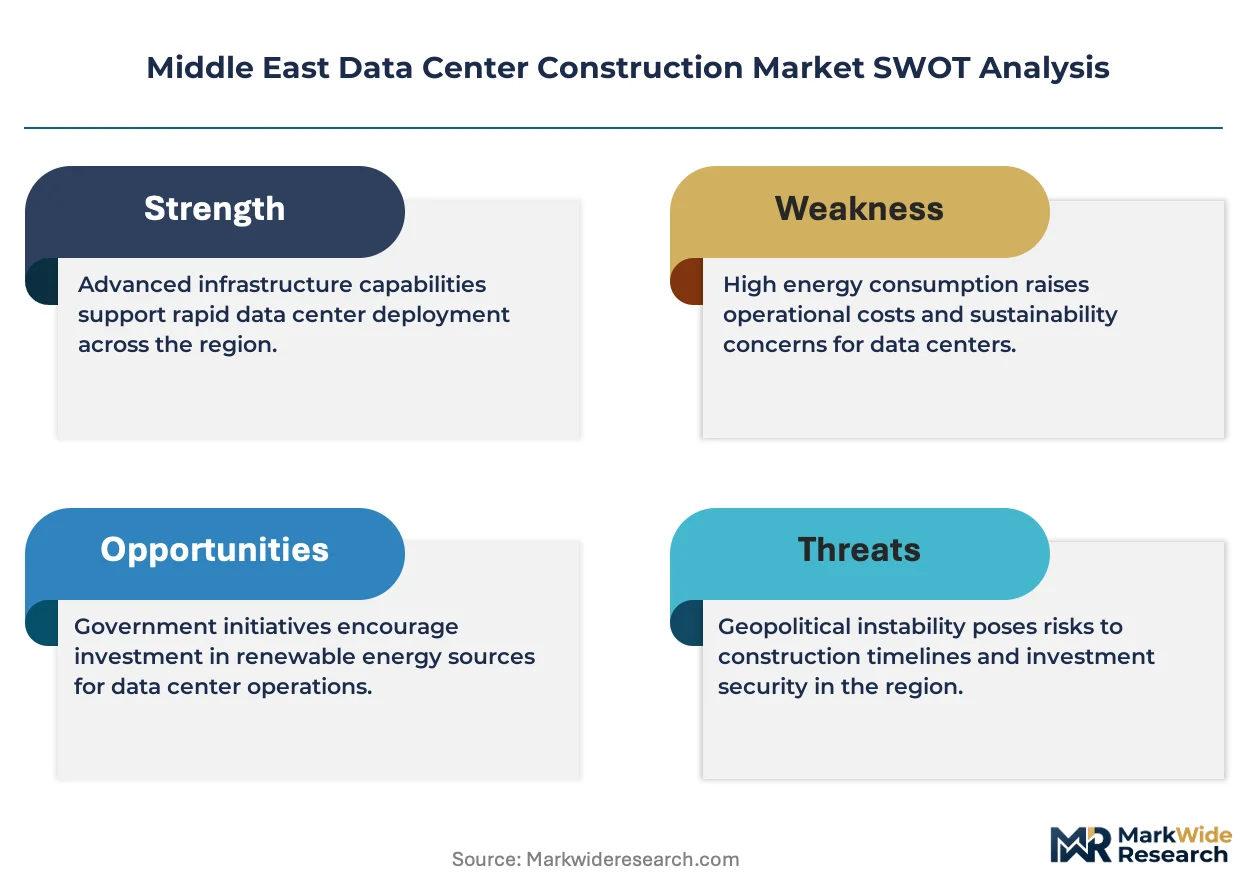
- Skilled MEP labor scarcity:Precision cooling and electrical specialists command premiums that inflate construction costs across the GCC, with talent concentrated in Dubai and Riyadh.
- Copper and aluminum price volatility:Busbar and cabling materials represent significant input cost exposure for electrical contractors on fixed-price EPC engagements.
- Grid interconnection delays:Utility approval timelines for multi-megawatt connections routinely extend project schedules beyond contractual delivery windows.
Strategic Opportunities
- Kuwait and Bahrain expansion:Secondary Gulf markets remain underserved by Tier III+ capacity, creating first-mover advantages for developers securing land and power allocations.
- Modular edge deployment:Prefabricated data hall units enable rapid capacity additions in secondary cities where traditional construction timelines conflict with enterprise demand urgency.
- Free zone incentives:Dubai's designated technology zones offer tax advantages and streamlined permitting that reduce total project cost structures for foreign operators.
Industry Challenges
- Tier IV certification timelines:Uptime Institute assessment procedures add months to project closeout, compressing revenue recognition and straining contractor cash flow.
- Legacy facility retrofit complexity:Older commercial buildings in established business districts require extensive structural reinforcement to support modern power densities exceeding 15 kW per rack.
- Cross-trade coordination:Interface management between civil, MEP, and IT infrastructure specialists generates rework and schedule slippage on fast-track hyperscale builds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Data Center Construction Market |
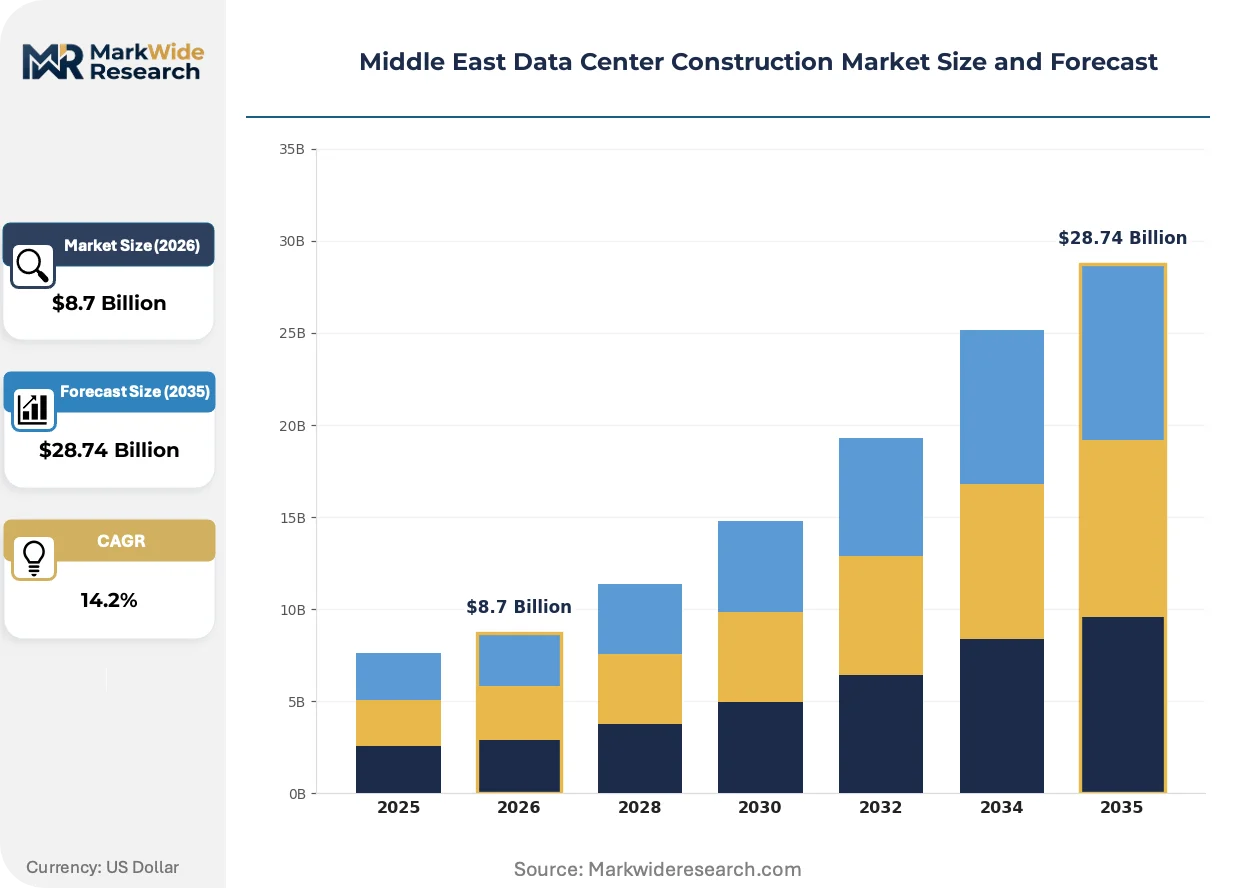
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Containerized Data Centers, Traditional Data Centers, Hyperscale Data Centers End User: Telecommunication, Educational Institutions, Government, Financial Services Technology: Cooling Systems, Power Management, Networking Equipment, Racking Solutions Installation: Onsite Construction, Prefabricated Solutions, Renovation Projects, Turnkey Solutions |
| Companies Covered | Khazna Data Centers, center3, Equinix, Gulf Data Hub, ALEC Engineering & Contracting, Laing O’Rourke, McLaren Construction Group, Nesma & Partners, Orascom Construction, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Data Center Construction Market Trends and Innovations
Liquid cooling architectures and AI-optimized facility designs are compressing traditional engineering assumptions about power density and thermal management. Construction methodologies are adapting to accommodate rack-level liquid distribution networks that were absent from standard specifications five years ago.
Direct-to-chip liquid cooling is electrifying how hyperscale operators approach thermal design in the Gulf's extreme ambient conditions. Colocation providers in Dubai are retrofitting existing halls with rear-door heat exchangers and in-row cooling manifolds to support GPU-intensive workloads. This technology is electrifying competitive positioning by enabling operators to offer guaranteed densities above 30 kW per rack where air-cooled competitors face physical constraints.
SFDA pharmaceutical data integrity guidelines and MOHAP health information standards are tightening facility certification requirements for operators hosting regulated workloads. Data center developers must now incorporate audit trails, access controls, and environmental monitoring systems that exceed base Tier III specifications. Healthcare and life sciences tenants in the UAE are prioritizing pre-certified facilities over speculative builds to accelerate compliance timelines.
Hyperscale operators are unbundling traditional EPC relationships in favor of multi-source procurement with specialized subcontractors. This disintermediation compresses single-source contractor margins while transferring interface risk to owner representatives. Saudi Arabia's sovereign wealth-backed developments are most aggressive in adopting this model, directly contracting MEP specialists and modular fabricators rather than routing through generalist construction managers.
Middle East Data Center Construction Market Segmentation
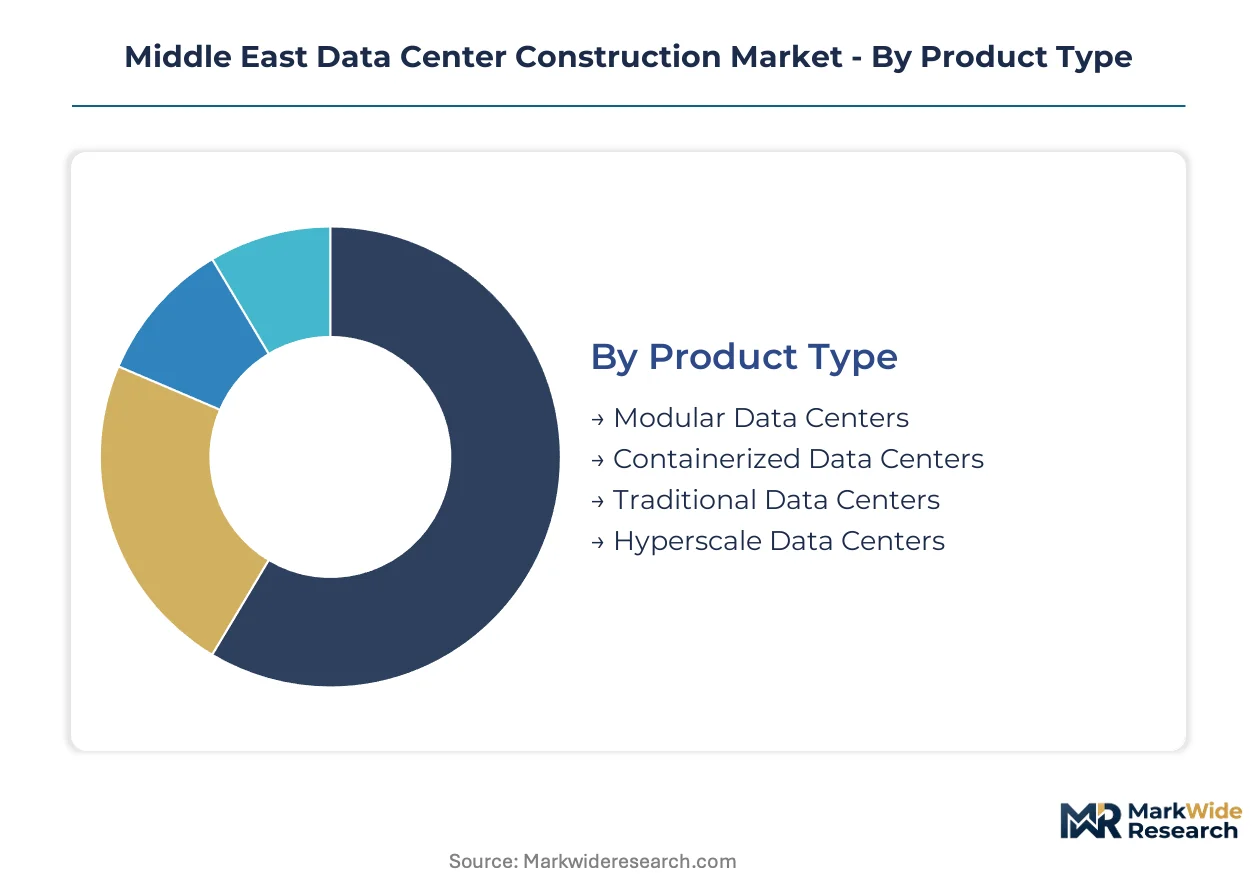
Construction methodologies and certification requirements diverge sharply across facility types in the Middle East. Product architecture determines whether projects pursue Uptime Institute Tier IV certification or modular compliance pathways, reshaping procurement timelines and vendor selection criteria.
Product Type:
Tier IV certification burdens concentrate on permanent structures requiring redundant electrical paths and fault-tolerant mechanical systems, while modular formats navigate faster factory-based compliance workflows.
- Hyperscale Data Centers:Purpose-built facilities exceeding 10 MW designed for single-tenant cloud operators with rack densities above 30 kW. Demand clusters in Riyadh and Dubai where Saudi Arabia's central bank and the UAE's telecommunications authority enforce data residency for financial workloads. These projects absorb the majority of Tier IV certification investment and specialized MEP labor.
- Modular Data Centers:Prefabricated data hall units enabling phased capacity deployment without full-scale civil construction. Secondary Gulf cities including Kuwait City and Manama are adopting this format to bypass grid interconnection delays and compressed municipal permitting timelines. Factory acceptance testing substitutes for extensive onsite commissioning.
- Traditional Data Centers:Conventional build-to-suit facilities with raised-floor environments and air-cooled architectures.
- Containerized Data Centers:Self-contained IT enclosures deployed as temporary or edge capacity supplements.
Leading the category by volume: Hyperscale Data Centers. Growing fastest: Modular Data Centers.
End User:
Regulated industries impose the steepest facility specifications, with financial and healthcare sectors driving premium construction margins.
- Financial Services:Banks, payment processors, and insurance carriers subject to Saudi Arabian Monetary Authority and UAE Central Bank data localization mandates. These operators commission domestic Tier IV facilities exclusively, rejecting colocation in European or Asian hubs. SFDA pharmaceutical guidelines and MOHAP health standards extend similar compliance rigor to healthcare-adjacent financial data.
- Government:Smart city programs in Riyadh and Dubai absorb hyperscale capacity for municipal digitization, sovereign cloud infrastructure, and national identity systems. Projects route through sovereign wealth vehicles with accelerated procurement authority and direct contracting flexibility.
- Telecommunication:Mobile network operators and fixed-line carriers building edge presence for 5G core infrastructure.
- Educational Institutions:Universities and research centers deploying high-performance computing clusters with moderate redundancy requirements.
Financial Services commands the highest construction premiums per square meter. Government contracts deliver the largest absolute contract values.
Technology:
Power densities above 15 kW per rack are forcing technology selection toward liquid-cooling-capable infrastructure.
- Cooling Systems:Precision air handlers, rear-door heat exchangers, and direct-to-chip liquid distribution networks. GPU-intensive AI workloads in Dubai colocation facilities are retrofitting with in-row cooling manifolds to guarantee densities above 30 kW per rack where air-cooled competitors face physical constraints.
- Power Management:Medium-voltage switchgear, UPS arrays, and busbar distribution engineered for fault-tolerant redundancy.
- Networking Equipment:Structured cabling and optical interconnects supporting spine-leaf architectures.
- Racking Solutions:Enclosed cabinets and open frames designed for liquid cooling integration.
Cooling Systems represents the fastest-growing technology investment category. Power Management retains the largest share of capital expenditure.
Installation:
Delivery models determine risk allocation between owners and contractors, with hyperscale operators unbundling traditional EPC relationships.
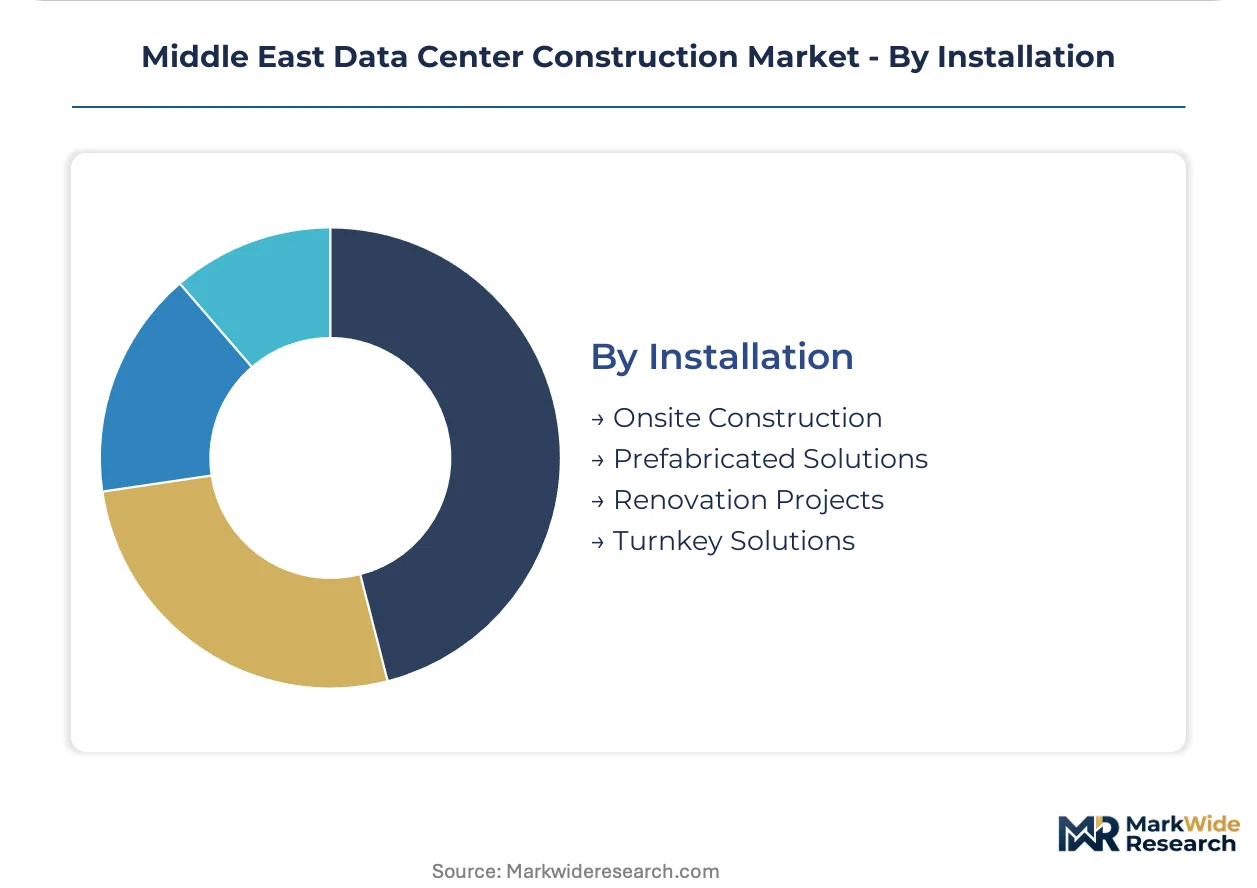
- Turnkey Solutions:Single-point-responsibility contracts where EPC contractors absorb integration risk between civil, MEP, and IT infrastructure workstreams. Premium pricing reflects this risk transfer. Saudi sovereign wealth-backed developments are most aggressive in abandoning this model for multi-source procurement.
- Onsite Construction:Traditional stick-built delivery with sequential trade mobilization and extended commissioning periods.
- Prefabricated Solutions:Factory-built mechanical and electrical modules shipped for rapid field assembly.
- Renovation Projects:Legacy facility retrofits requiring structural reinforcement to support modern power densities.
Turnkey Solutions still dominate contract value. Prefabricated Solutions are gaining share fastest among time-constrained enterprise deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the Gulf Cooperation Council states where sovereign wealth vehicles and hyperscale operators commission Tier IV facilities. Financial data residency rules from Saudi Arabia's central bank and the UAE's telecommunications authority redirect capital flows toward domestic construction. Secondary markets in Kuwait and Bahrain remain capacity-constrained, creating first-mover premiums for developers securing power allocations.
Saudi Arabia
Riyadh absorbs the majority of new hyperscale capacity through government-backed smart city programs and financial district expansions. The Saudi Arabian Monetary Authority enforces strict data localization for citizen financial records, compelling banks to commission domestic Tier IV facilities. NEOM's northwest development zone and the Eastern Province's industrial corridor are emerging as secondary clusters for modular edge deployments.
United Arab Emirates
Dubai anchors the region's wholesale colocation segment through campus strategies serving cloud operators and financial services tenants. MOHAP health information standards and the telecommunications regulator's data residency rules tighten certification requirements for regulated workloads. Abu Dhabi's designated technology zones offer tax advantages that reduce total project cost structures for foreign operators establishing sovereign infrastructure.
Qatar
Doha's financial services sector generates concentrated demand for Tier III+ capacity as the Qatar Central Bank implements data protection frameworks for banking records. The national communications regulator has issued draft localization guidelines that would prohibit cross-border storage of sensitive citizen data. Lusail's smart city infrastructure and the Qatar Science & Technology Park are absorbing initial hyperscale investments ahead of broader market development.
Kuwait
Kuwait City remains underserved by certified data center capacity despite enterprise demand from banking and oil sector digitization initiatives. The Central Bank of Kuwait has signaled forthcoming data residency requirements that would mirror Saudi and UAE precedents. The Shuwaikh industrial area and Sabah Al Ahmad Sea City are attracting preliminary land acquisitions from developers anticipating regulatory alignment with Gulf neighbors.
Bahrain
Manama's financial hub status generates specialized demand from Islamic banking institutions requiring compliant data infrastructure. The Central Bank of Bahrain's cloud computing guidelines encourage domestic facility deployment for regulated financial workloads. Bahrain Bay and the Diyar Al Muharraq development are emerging as preferred locations for modular deployments targeting latency-sensitive trading applications.
Middle East Data Center Construction Market Competitive Landscape
Capacity expansion dominates the current landscape as developers race to secure land and power allocations ahead of regulatory deadlines. The market structures around three distinct tiers: sovereign wealth-backed national champions, international hyperscale operators with captive construction programs, and specialized regional contractors. Vertically integrated development models compress delivery timelines, while multi-source procurement patterns transfer interface risk to owner representatives. Strategic partnerships with modular fabricators and MEP specialists are displacing traditional single-source EPC relationships.
Among UAE-based operators, Khazna Data Centers and Gulf Data Hub exemplify contrasting development archetypes. Khazna leverages vertically integrated construction capabilities to serve hyperscale clients with accelerated timelines. Gulf Data Hub anchors the wholesale colocation segment through its Dubai-centric campus expansion strategy. ALEC Engineering & Contracting represents the specialized contractor tier, combining civil works self-performance with MEP integration to reduce interface risk on complex Tier IV builds.
| Leading Market Players |
|---|
| Khazna Data Centers |
| center3 |
| Equinix |
| Gulf Data Hub |
| ALEC Engineering & Contracting |
| Laing O’Rourke |
| McLaren Construction Group |
| Nesma & Partners |
| Orascom Construction |
| Others |
Pricing and Supply Chain Analysis
Tier IV certification premiums against modular commodity offerings create a bifurcated market where pricing power concentrates with Uptime Institute-certified operators while supply chains fragment between specialized MEP fabricators and standardized prefabrication yards. This divergence forces procurement officers to navigate dual sourcing strategies that reconcile mission-critical redundancy requirements against compressed delivery timelines demanded by hyperscale cloud tenants.
Pricing Analysis
Volume concentration in hyperscale contracts compresses per-megawatt margins, while boutique Tier IV certifications sustain premium pricing through scarcity of qualified commissioning engineers. Price differentiation hinges on Uptime Institute certification tier and in-house MEP self-performance capability. Pricing pressure intensifies as Saudi sovereign wealth vehicles bypass traditional EPC markups through direct subcontractor engagement. Financial services tenants exhibit lowest price sensitivity due to regulatory non-negotiability, whereas secondary city enterprises drive modular procurement decisions primarily on total cost of ownership.
Supply Chain Analysis
Regional distribution centers in the UAE and Saudi Arabia anchor hub-and-spoke material flows for precision cooling equipment and medium-voltage switchgear. Manufacturing concentration rests on Germany, China, and the USA for critical power infrastructure, while copper busbar and aluminum cabling feed from GCC smelters and Asian refiners. Single-source vulnerability permeates liquid cooling component supply, with direct-to-chip cold plates and manifolds drawing from limited qualified fabricators. Distribution runs through Dubai's Jebel Ali Free Zone for tax-advantaged staging before final mile deployment to Riyadh and Doha construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation accelerates as multi-source procurement patterns erode single-source EPC margins and sovereign wealth-backed developers internalize construction capabilities. Skilled MEP labor scarcity functions as the primary pressure forcing weaker generalist contractors toward exit or acquisition.
For Market Incumbents: Deepen backward integration into precision cooling fabrication and electrical module pre-assembly to defend margin position against disintermediation by hyperscale owner-representatives. Capture captive supply of Tier IV commissioning engineers through apprenticeship pipelines anchored to Riyadh and Dubai technical institutes. Khazna's vertically integrated model demonstrates how in-house MEP capability compresses delivery timelines and locks out competitor access to hyperscale tender lists. For New Entrants and Emerging Players: Capture underserved modular deployment demand in Kuwait City and Manama where grid interconnection delays and compressed permitting timelines favor factory-built data hall units. Target Islamic banking institutions in Bahrain requiring compliant infrastructure with accelerated compliance pathways. Lead with pre-certified facility offerings that bypass speculative build risks and align with SFDA and MOHAP audit trail requirements for healthcare-adjacent financial data. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of specialized MEP subcontractors with Tier IV commissioning track records and established relationships with Saudi sovereign wealth vehicles. Long-term viability favors operators with demonstrated capability across liquid cooling integration and AI-optimized thermal design. Watch hyperscale direct contracting adoption rates as the inflection signal determining whether traditional EPC margins compress irreversibly or stabilize through hybrid procurement models.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration | Direct-to-chip architectures enable guaranteed densities above 30 kW per rack in Dubai's extreme ambient conditions. |
| Modular Fabrication Partnership | Factory-built data hall units bypass grid interconnection delays that routinely extend traditional project schedules. |
| Tier IV Certification Investment | Uptime Institute assessment differentiates operators serving Saudi Arabian Monetary Authority financial data mandates. |
| Sovereign Infrastructure Joint Venture | Partnerships with Saudi sovereign wealth vehicles secure accelerated procurement authority and land allocations. |
| MEP Specialist Acquisition | Precision cooling and electrical expertise scarcity commands premium valuations and locks out competitor access. |
Research Methodology
Independent corroboration across EPC contractor project managers, hyperscale cloud operator procurement officers, and MEP specialist engineering directors underwrites the qualitative findings in this study. Primary fieldwork encompassed structured interviews with data center facility directors, Uptime Institute commissioning engineers, and sovereign wealth vehicle infrastructure investment leads. Secondary validation drew from SEC filings of publicly traded contractors, UAE Telecommunications and Digital Government Regulatory Authority policy releases, and Saudi Arabian Monetary Authority circulars on data localization. Bottom-up project pipeline aggregation triangulates against top-down capital expenditure estimates from cloud operator disclosure patterns.
Comparable-period anchoring to historical construction completion rates and certification timelines established the forecast window boundaries. The analytical framework models segmentation across facility type, end-user vertical, cooling technology tier, and installation delivery model throughout the projection horizon. CAGRs derive from regression analysis of announced project capacities against regulatory deadline schedules. Forecast inputs incorporate hyperscale cloud operator regional expansion commitments and Saudi Vision 2030 smart city infrastructure disbursement trajectories.
The model holds under sustained regulatory enforcement of data residency rules; deviation in grid interconnection approval timelines or copper price volatility would shift capacity deployment schedules. Forecasts reflect base-case assumptions regarding MEP labor availability and Tier IV assessor capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Early Production Facility Market
Building Construction
Cold Storage Construction Market
Building Construction
Modular and Prefabricated Construction Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Europe Modular Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Oman Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
South Korea Data Center Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Japan Construction Market
Building Construction
Germany Prefabricated Buildings Market
Building Construction
Indonesia Infrastructure Market
Building Construction
US Prefabricated Buildings Market
Building Construction
Indonesia Commercial Construction Market