
 UAE Prefab Wood Buildings Market | 2026-2036
UAE Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Prefab Wood Buildings Market Insights
Finnish and Austrian engineered-wood capacity is reconfiguring supply routes into the Gulf, shortening lead times for cross-laminated timber and glulam shipments. Karmod Prefabricated Technologies leverages its Istanbul manufacturing base to dominate modular hospitality deliveries across the Emirates. Red Sea International anchors its position through panelized system fabrication in Jeddah, competing on proximity to UAE project sites. ArchiLine Wooden Houses specializes in laminated log residential units, sustaining premium positioning among luxury villa developers in Dubai Hills and Saadiyat Island.
Prefab wood buildings are factory-manufactured structural systems using engineered timber, laminated wood, or mass-timber components, typically assembled through panelized, modular, or timber-frame methods, with fire-retardant treatments and thermal insulation meeting Gulf-specific humidity and seismic codes. These structures serve permanent and semi-permanent functions across residential, commercial, and institutional applications where speed of erection and embodied-carbon reduction are prioritized. Residential Homes leads product-type revenue, while Modular Construction captures the fastest expansion as developers seek repeatable, scalable solutions for workforce and tourist accommodation. Panelized Systems occupy the mature margin pool, given established supplier networks and standardized engineering workflows.
MOHAP building-safety directives and Dubai Municipality's green building codes shape material certification pathways, requiring third-party structural validation and fire-performance documentation for all timber-based construction. The Emirates Authority for Standardization and Metrology enforces product conformity under UAE-specific technical regulations, filtering out uncertified European and Asian suppliers. Stakeholders must monitor evolving federal procurement preferences for low-carbon construction materials, as Abu Dhabi Department of Energy and Dubai Supreme Council of Energy integrate embodied-carbon metrics into public-project tender evaluation frameworks.
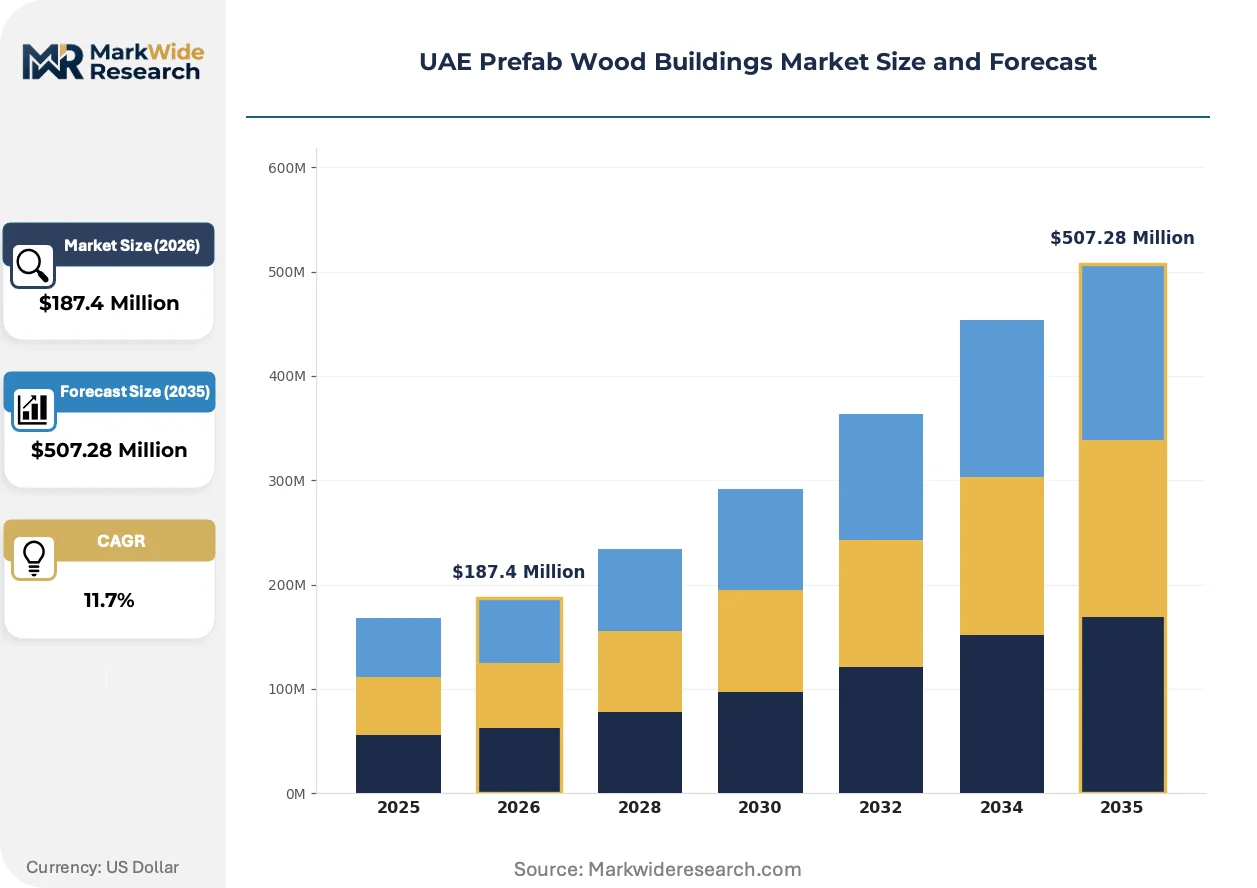
Market Dynamics
Dubai Municipality's Al Sa'fat green building rating system and Abu Dhabi's Pearl rating mandates are compressing project timelines and forcing developers toward factory-manufactured timber systems that satisfy embodied-carbon thresholds.
Growth Catalysts
- Al Sa'fat Rating System:Dubai Municipality's green building framework mandates energy-efficient materials, accelerating timber specification in hospitality and residential verticals.
- Cross-laminated timber:Finnish and Austrian engineered-wood suppliers are shortening Gulf supply routes, reducing lead times for mass-timber components.
- Eco-lodge developers:Red Sea and Al Ain tourism projects are specifying prefab wood structures for rapid assembly in remote locations.
Market Restraints
- Humidity degradation:Gulf coastal conditions require specialized fire-retardant and moisture-barrier treatments, adding 15-20% to material costs.
- European supply concentration:CLT and glulam capacity clusters in Austria, Finland and Germany, exposing projects to shipping bottlenecks and currency fluctuation.
- Concrete substitution threat:Local ready-mix concrete remains price-competitive for mid-rise commercial structures, limiting timber penetration in office and retail segments.
Strategic Opportunities
- Ras Al Khaimah tourism corridor:Underdeveloped emirate offers greenfield resort development with fewer legacy construction constraints than Dubai or Abu Dhabi.
- Workforce accommodation modularization:Expo 2020 legacy sites and industrial zones require scalable, repeatable housing units for labor populations.
- Federal procurement preference:Abu Dhabi Department of Energy's embodied-carbon metrics in public tenders create first-mover advantage for certified timber suppliers.
Industry Challenges
- Fire-performance certification timeline:Emirates Authority for Standardization and Metrology validation for novel timber treatments extends project pre-construction phases by 4-6 months.
- Mass-timber engineering skill scarcity:Local structural engineering firms lack specialized expertise in seismic and humidity-adapted timber design, forcing reliance on European consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Prefab Wood Buildings Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Homes, Commercial Buildings, Temporary Structures, Garden Sheds Construction Method: Panelized System, Modular Construction, Hybrid Construction, Timber Frame End User: Construction Firms, Real Estate Developers, Government Projects, Retail Chains Application: Office Spaces, Educational Facilities, Recreational Areas, Emergency Housing |
| Companies Covered | Karmod Prefabricated Technologies, Red Sea International, ArchiLine Wooden Houses, Wood Wooden Works, Newcastle Factory, Houses of Wood, Space Box, Al Bait Al Raqi, Tareeq Al Khaleej Prefab House, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Prefab Wood Buildings Market Trends and Innovations
Factory automation and digital fabrication are compressing design-to-assembly cycles for timber structures, while regulatory pressure on embodied carbon is repositioning mass-timber as a default structural option for mid-rise construction.
Cross-laminated timber is migrating from niche architectural showcase projects to standardized hospitality and residential developments. Dubai Hills and Saadiyat Island developers are specifying CLT for five-story hotel and villa structures. This migration is compressing the traditional concrete-steel procurement cycle and forcing general contractors to retool project management for just-in-time panel delivery.
MOHAP building-safety directives now require third-party structural validation and fire-performance documentation for all timber-based construction. The industrial consequence is a filtering of uncertified European and Asian suppliers from the vendor pool. Hospitality developers are most affected, responding by pre-qualifying only Emirates Authority for Standardization and Metrology-approved fabricators in early design phases.
Developer procurement teams are bundling design, fabrication and erection into single-source contracts with modular specialists. Traditional general contractors are losing timber project control to Istanbul-based and Jeddah-based integrated fabricators. This consolidation is most visible in Dubai's luxury villa segment, where developers prioritize speed-to-market over multi-vendor bidding.
UAE Prefab Wood Buildings Market Segmentation
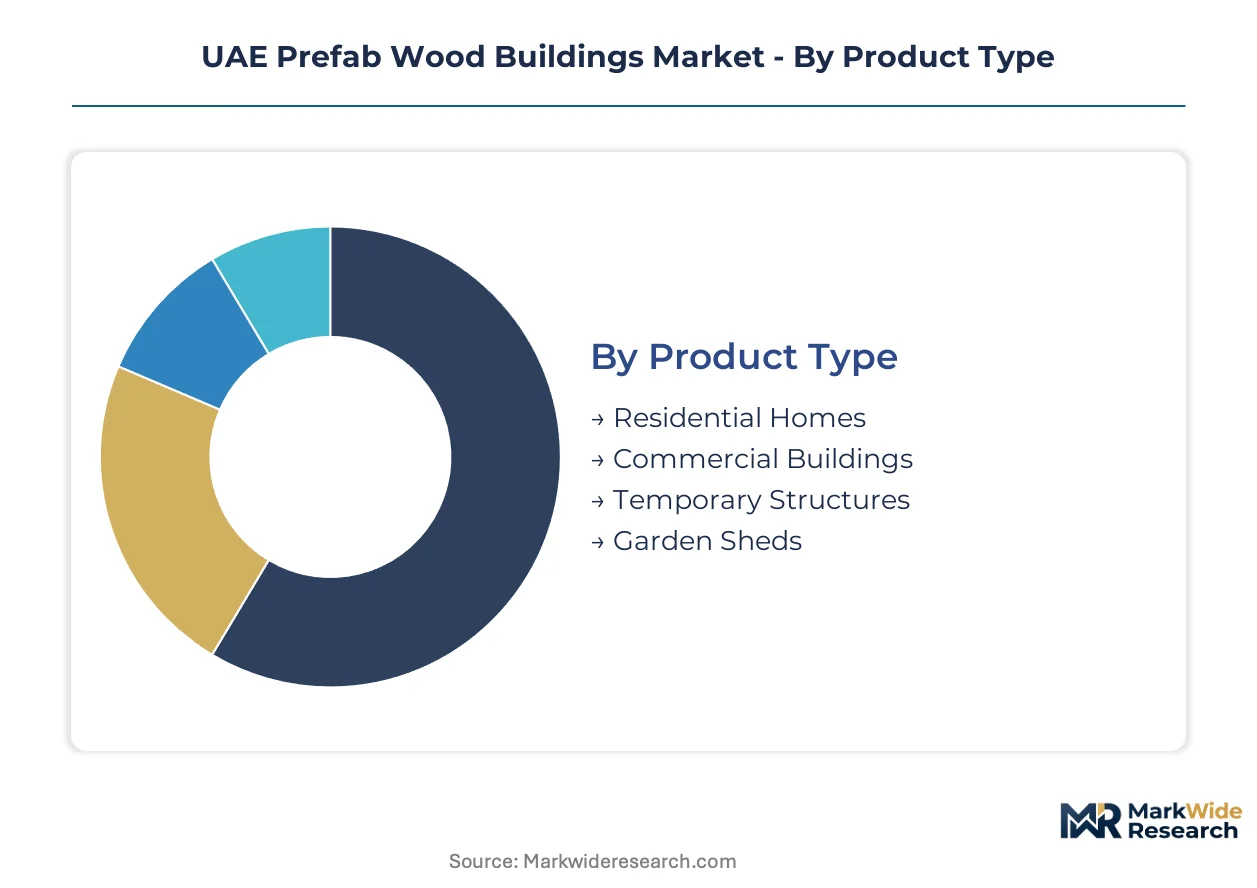
Prefab wood buildings in the Emirates fragment across construction methodology, end-user procurement patterns, and functional application. Each dimension reveals distinct margin structures and regulatory exposure that shape supplier positioning.
Product Type:
Cost tiers separate permanent structural investments from semi-permanent and accessory installations.
- Residential Homes:Engineered timber villas and townhouses using CLT and glulam systems dominate revenue concentration. Dubai Hills and Saadiyat Island developers specify these for five-story luxury structures where embodied-carbon credentials accelerate sales velocity.
- Commercial Buildings:Mid-rise offices and retail structures face concrete substitution pressure but gain traction in hospitality pods and boutique retail where speed-to-market outweighs material cost premiums.
- Temporary Structures:Semi-permanent workforce accommodation and event pavilions serve Expo 2020 legacy sites and industrial zones with rapid deployment requirements.
- Garden Sheds:Accessory storage units for villa compounds represent a fragmented, price-sensitive tier with limited regulatory scrutiny.
Residential Homes holds installed capacity. Temporary Structures is rotating up the share rankings.
Construction Method:
Application requirements dictate whether developers prioritize factory precision, on-site flexibility, or hybrid adaptability.
- Panelized System:Pre-cut wall and floor assemblies shipped flat-pack for on-site erection occupy mature margin pools. Established supplier networks and standardized engineering workflows reduce project risk for general contractors unfamiliar with timber.
- Modular Construction:Volumetric units factory-finished with MEP and interiors represent the steepest expansion trajectory. Istanbul-based and Jeddah-based integrated fabricators are consolidating single-source contracts for hospitality and workforce housing.
- Hybrid Construction:Timber-steel or timber-concrete composite systems address seismic and humidity adaptation where pure timber engineering expertise is scarce locally.
- Timber Frame:Traditional post-and-beam methods persist in low-rise luxury villa segments where architectural authenticity commands premium positioning.
Panelized System maintains the broadest contractor adoption. Modular Construction is climbing the fastest as procurement shifts toward design-fabrication-erection bundling.
End User:
Customer type determines certification burden, contract scale, and payment security.
- Construction Firms:General contractors acting as intermediaries face margin compression as developers bypass them for direct modular specialist relationships.
- Real Estate Developers:Master developers in Dubai and Abu Dhabi drive specification decisions, prioritizing Al Sa'fat and Pearl rating compliance over first-cost minimization.
- Government Projects:Federal and emirate-level procurement increasingly embeds embodied-carbon metrics from Abu Dhabi Department of Energy and Dubai Supreme Council of Energy.
- Retail Chains:Quick-service restaurant and convenience store rollouts demand repeatable kiosk and pavilion formats with minimal site disruption.
Real Estate Developers command specification authority. Government Projects is gaining share fastest as federal procurement preferences harden.
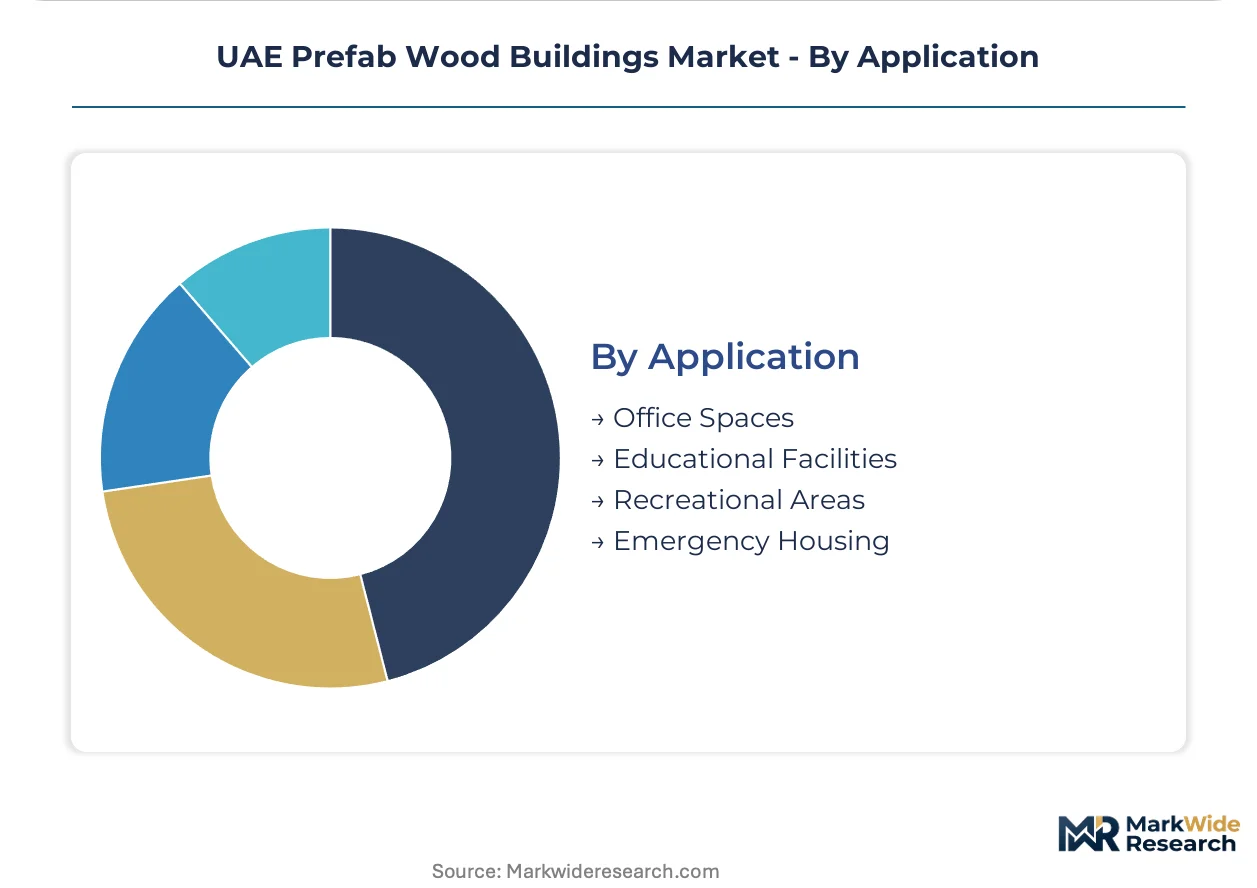
Application:
Volume concentration clusters where regulatory pressure and speed requirements intersect.
- Office Spaces:Mid-rise commercial structures face concrete competition but see timber penetration in creative industry clusters and co-working developments.
- Educational Facilities:Schools and training centers benefit from compressed construction schedules that minimize operational disruption.
- Recreational Areas:Eco-lodges and desert tourism infrastructure in Ras Al Khaimah and Al Ain exploit rapid assembly in remote locations with limited labor access.
- Emergency Housing:Disaster response and transitional accommodation represents a contingency-driven tier with irregular demand spikes.
Recreational Areas leads tourism-driven deployment. Educational Facilities is expanding most quickly as school operators prioritize schedule certainty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port's container throughput underwrites the Emirates' position as the Gulf's primary engineered-timber entry point, connecting Finnish and Austrian CLT suppliers to Dubai and Abu Dhabi construction corridors.
Dubai
Dubai Hills and Saadiyat Island master developers specify five-story CLT structures for luxury hospitality and residential verticals. Dubai Municipality's Al Sa'fat green building rating system mandates embodied-carbon thresholds that compress traditional concrete-steel procurement cycles. Jebel Ali Industrial Zone hosts prefabrication yards where Istanbul-based and Jeddah-based fabricators stage panelized systems for just-in-time delivery.
Abu Dhabi
Saadiyat Island cultural district and Yas Island entertainment zones drive demand for rapid-assembly timber structures in tourism and leisure applications. The Department of Energy embeds embodied-carbon metrics into public-project tender evaluations, filtering vendor pools to certified suppliers. Khalifa Industrial Zone anchors modular fabrication capacity serving federal procurement preferences for low-carbon construction materials.
Sharjah
Industrial zone expansion and workforce housing mandates create volume opportunities for repeatable modular units. The emirate's construction regulatory framework aligns with federal standardization requirements enforced by the Emirates Authority for Standardization and Metrology. Hamriyah Free Zone attracts secondary fabricators seeking lower operational costs than Dubai or Abu Dhabi core markets.
Ras Al Khaimah
Jebel Jais mountain tourism corridor and coastal resort development exploit greenfield sites with fewer legacy construction constraints. The emirate's tourism authority prioritizes eco-lodge formats that leverage rapid timber assembly in remote locations with limited labor access. Al Hamra Industrial Zone hosts emerging prefabrication capacity targeting hospitality-driven demand.
Northern Emirates
Fujairah and Umm Al Quwain industrial zones serve as overflow fabrication sites for Dubai and Abu Dhabi project backlogs. Federal infrastructure investment in east coast port expansion at Fujairah creates alternative timber import routes bypassing Jebel Ali congestion. Ajman's manufacturing free zones attract mid-scale panelized system producers serving cost-sensitive workforce accommodation segments.
UAE Prefab Wood Buildings Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying engineered timber and hardware. The vendor base stratifies between Istanbul-based and Jeddah-based integrated fabricators with single-source design-fabrication-erection capabilities, and European component suppliers shipping CLT and glulam through consolidated Gulf distribution channels. Three archetypes dominate: integrated modular specialists, European mass-timber exporters, and regional panelized system fabricators. Capacity expansion and strategic pre-qualification partnerships with master developers constitute the dominant competitive moves.
Among Turkey-based platform integrators, Karmod Prefabricated Technologies occupies a position exemplifying the design-fabrication-erection bundling model. Red Sea International anchors the proximity-competitive tier through its Jeddah manufacturing base serving UAE project sites. ArchiLine Wooden Houses represents the premium residential specialization archetype, with naming conventions suggesting laminated log and engineered-timber villa focus. These three entities illustrate the geographic and functional segmentation pressuring traditional general contractors out of timber project control.
| Leading Market Players |
|---|
| Karmod Prefabricated Technologies |
| Red Sea International |
| ArchiLine Wooden Houses |
| Wood Wooden Works |
| Newcastle Factory |
| Houses of Wood |
| Space Box |
| Al Bait Al Raqi |
| Tareeq Al Khaleej Prefab House |
| Others |
Pricing and Supply Chain Analysis
Finnish and Austrian engineered-wood capacity clusters anchor upstream supply, compressing margin pools toward Jeddah-based and Istanbul-based fabricators who bundle design-fabrication-erection into single-source contracts. This concentration forces European component suppliers to compete on certification speed rather than price alone.
Pricing Analysis
Dubai Municipality's Al Sa'fat rating system dictates the pricing tier structure across the Emirates, separating Emirates Authority for Standardization and Metrology-certified fabricators from uncertified competitors. Project-based contracting dominates, with price differentiation hinging on fire-performance certification tier and volume scale of CLT or glulam procurement. Cost compression in mid-rise commercial segments is intensifying because ready-mix concrete retains cost parity, while hospitality developers show least price sensitivity as they prioritize speed-to-market and embodied-carbon credentials.
Supply Chain Analysis
Cross-laminated timber feedstock draws from Austria, Finland, and Germany, with glulam beams and laminated logs sourced through consolidated Baltic and Nordic distribution channels. Raw material dependencies center on spruce and pine timber grades, fire-retardant chemical treatments, and humidity-barrier membrane systems. Single-source vulnerability runs through Jebel Ali Port container throughput, which anchors Gulf import routes. Distribution runs through Dubai-based staging yards where panelized systems await just-in-time delivery to Abu Dhabi and Ras Al Khaimah project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Emirates prefab wood market sits at a platform-economics inflection where design-fabrication-erection bundling by integrated fabricators is displacing traditional general contractor intermediation, much as cloud infrastructure displaced on-premise IT procurement.
For Market Incumbents: Insulate project control by securing pre-qualification partnerships with Saadiyat Island and Dubai Hills master developers before Istanbul-based competitors deepen their specification lock-in. Prioritize backward integration into fire-retardant treatment capacity to compress certification timelines that currently extend pre-construction phases, defending margin pools against Jeddah-based proximity competitors. For New Entrants and Emerging Players: Establish a beachhead in Ras Al Khaimah's Jebel Jais tourism corridor, where greenfield resort development lacks incumbent fabricator relationships and eco-lodge formats favor rapid timber assembly. Target workforce accommodation modularization at Expo 2020 legacy sites with repeatable unit designs, leveraging Hamriyah Free Zone cost advantages to undercut Dubai-based staging costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with European mass-timber exporters facing margin compression as Gulf fabricators consolidate single-source contracts. Five-to-ten year viability hinges on certification moats rather than manufacturing scale alone. Watch for Abu Dhabi Department of Energy tender evaluations embedding embodied-carbon metrics as the signal for when federal procurement preference hardens into mandatory thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Qualification Partnerships | Al Sa'fat compliance locks out uncertified European suppliers from Dubai hospitality pipelines. |
| Backward Integration into Treatment Capacity | In-house fire-retardant processing compresses Emirates Authority validation timelines by months. |
| Ras Al Khaimah Greenfield Positioning | Jebel Jais tourism corridor offers incumbent-free terrain for eco-lodge specification capture. |
| Workforce Accommodation Modularization | Expo 2020 legacy sites demand scalable repeatable units with federal procurement preference tailwinds. |
| European Component Supplier Consolidation | Finnish and Austrian CLT capacity faces margin pressure from Jeddah proximity competition. |
Research Methodology
Initial hypotheses were tested against primary input from master developer procurement directors, modular fabrication executives, structural engineering consultants, and Emirates Authority certification officers, then refined against Dubai Municipality regulatory filings, MOHAP building-safety directives, customs import records for engineered timber, and project development databases tracking hospitality and residential construction pipelines. Bottom-up project pipeline aggregation was cross-checked with top-down construction spending forecasts across the analysis window.
Demand-supply-balance framing anchored the analytical framework throughout the projection horizon, modeling construction method, end-user procurement pattern, functional application, and emirate-level regulatory intensity as core segmentation dimensions. CAGRs were derived from installation capacity trajectories and policy-driven specification shifts, with cross-laminated timber adoption curves and Al Sa'fat compliance deadlines serving as industry-specific forecast inputs.
Stress conditions across shipping route congestion, euro-dirham exchange volatility, and fire-performance certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and master developer procurement centralization. Cross-checking against Dubai Department of Economy and Tourism construction permit data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Construction Market
Building Construction
Honduras Construction Market
Building Construction
Guatemala Construction Market
Building Construction
India Commercial Construction Market
Building Construction
US Offsite Construction Market
Building Construction
Turkey Commercial Construction Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
Sweden New Construction Market
Building Construction
Cold Storage Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Egypt Residential Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
China Building Construction Market
Building Construction
Oman Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Early Production Facility Market