
 Europe 3D Printing Construction Market | 2026-2036
Europe 3D Printing Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Europe 3D Printing Construction Market Analytics
Public-sector infrastructure buyers are unwinding reliance on traditional concrete contractors across the Netherlands and Denmark. COBOD International dominates large-format gantry systems for multi-story housing, leveraging its Nordic project portfolio to sustain technical credibility. MX3D anchors the metals segment with wire-arc additive systems for bridge components, while PERI Group competes through rental-model access to its BOD2 printer fleet.
Europe 3D printing construction deploys layer-by-layer material deposition to fabricate structural and non-structural building elements, typically using cementitious mixes with layer heights of 10-50 mm and compressive strengths exceeding 30 MPa after post-processing. The primary purpose is to reduce formwork waste, labor hours, and embodied carbon in vertical construction. Concrete 3D printers capture the dominant share of installed equipment value, though hybrid systems that combine printing with robotic reinforcement placement are expanding fastest as margin pools shift toward integrated workflow solutions. Material extrusion leads technology adoption for on-site housing, while powder binder jetting occupies a narrower niche in prefabricated facade production.
The EU Green Deal and CE marking requirements under the Construction Products Regulation shape material qualification pathways, with ECHA REACH compliance governing chemical admixtures in printable mortars. Germany's DIBt approvals and France's CSTB evaluations serve as de facto gatekeepers for cross-border product acceptance. Stakeholders must monitor how the EU AI Act interfaces with autonomous print-path optimization software, as algorithmic compliance costs could reshape vendor economics.
Market Dynamics
The EU Green Deal's embodied-carbon thresholds are forcing housing developers across Northern Europe to abandon traditional formwork-intensive construction methods. This regulatory compression is redrawing procurement patterns and equipment deployment timelines.
Growth Catalysts
- CE marking pathways:Germany's DIBt approvals for load-bearing printed walls are creating cross-border product acceptance frameworks that lower market entry barriers for qualified systems.
- Public infrastructure procurement:Dutch and Danish transport authorities are specifying printed structural components in bridge and tunnel tenders, normalizing additive manufacturing in civil engineering specifications.
- Wire-arc additive manufacturing:Metals printing for bridge reinforcement is penetrating municipal infrastructure budgets previously reserved for cast-steel fabricators.
Market Restraints
- Portland cement price volatility:Input cost swings in cementitious mixes compress project margins before contracts close, deterring fixed-price tendering.
- ECHA REACH compliance costs:Chemical admixture qualification timelines extend material certification cycles by 18-24 months.
- Precast concrete substitution:Established prefabrication plants in Poland and Romania offer faster delivery certainty for standardized structural elements.
Strategic Opportunities
- France CSTB fast-track evaluations:Accelerated technical assessments for printable mortars are opening pathways for novel binder systems.
- Hybrid robotic reinforcement:Convergence of extrusion printing with automated rebar placement is creating integrated workflow premiums.
- Equipment-as-a-service models:Rental access to gantry systems is lowering capital barriers for mid-tier housing developers in Scandinavia.
Industry Challenges
- Print-path optimization expertise:Shortage of technicians capable of calibrating layer-height parameters for variable weather conditions delays site commissioning.
- Legacy BIM integration:Design software workflows require manual translation to printer-native formats, extending pre-construction phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe 3D Printing Construction Market |
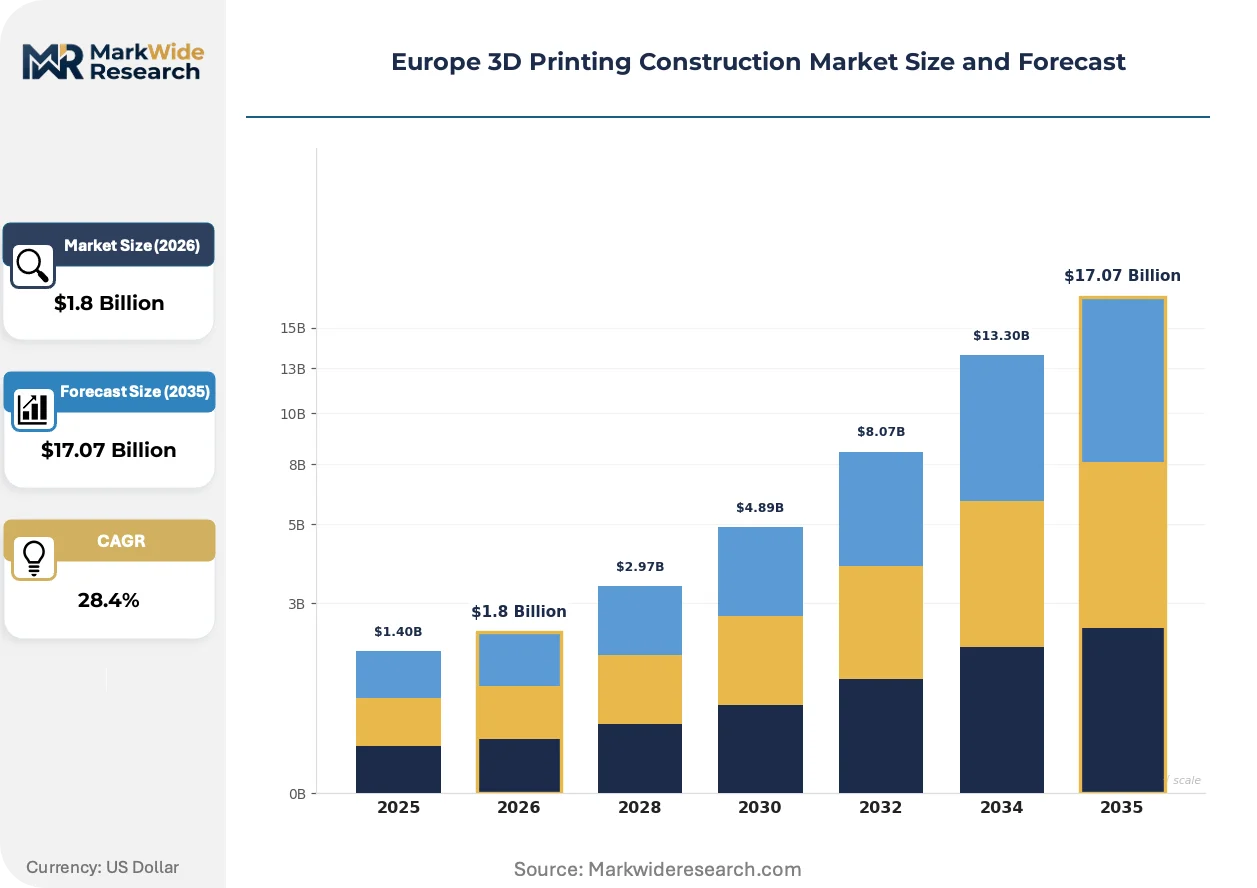
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete 3D Printers, Hybrid 3D Printers, Material Extrusion Printers, Powder Bed Fusion Printers Technology: Binder Jetting, Material Extrusion, Powder Binder Jetting, Direct Energy Deposition Application: Residential Buildings, Commercial Structures, Bridges, Infrastructure End User: Contractors, Architects, Developers, Public Sector |
| Companies Covered | COBOD International, MX3D, Sika AG, XtreeE, Constructions-3D, CyBe Construction, WASP, PERI Group, Skanska Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe 3D Printing Construction Market Evolving Landscape
Layer-height precision and post-processing automation are compressing the gap between printed and cast-in-place structural performance. Equipment vendors are racing to embed these capabilities into turnkey workflow offerings.
Multi-material extrusion heads capable of simultaneous cement deposition and fiber reinforcement are supplanting single-nozzle systems in German housing developments. Mid-rise residential contractors in Bavaria and North Rhine-Westphalia are adopting these configurations for perimeter wall assemblies. The technology is supplanting traditional formwork carpentry crews and compressing structural enclosure schedules from weeks to days.
The EU AI Act's risk-classification framework for autonomous construction algorithms is mandating documentation standards for print-path optimization software. Vendors must now maintain algorithmic audit trails to maintain CE marking eligibility. German and French equipment manufacturers are absorbing compliance costs into subscription pricing tiers to preserve margin structures.
Housing associations in the Netherlands are consolidating procurement through framework agreements that bundle design, printing, and finishing services. This bundled contracting displaces fragmented subcontractor relationships. Denmark's municipal housing corporations are piloting similar consolidated sourcing for social housing renewals.
Europe 3D Printing Construction Market Segmentation
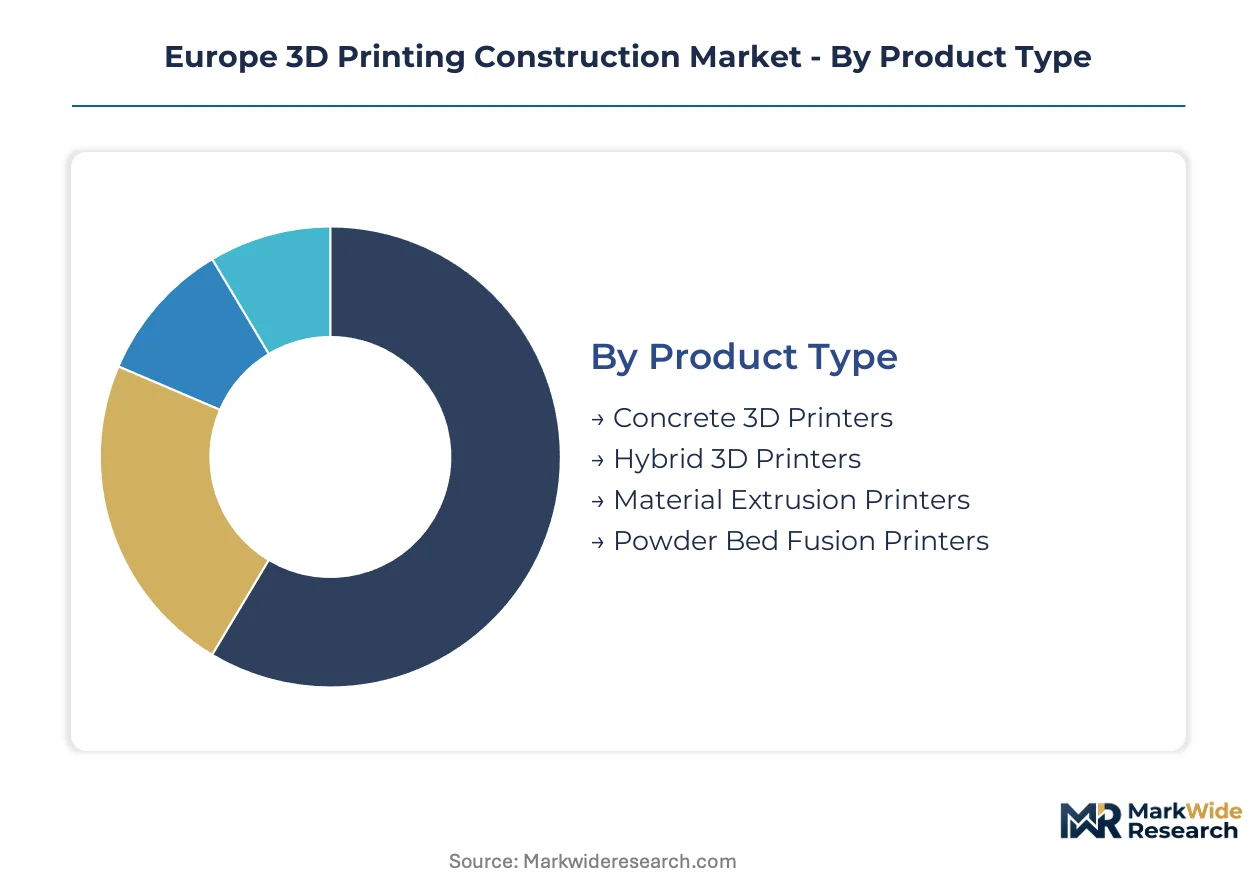
Equipment procurement patterns in Europe diverge sharply by product format, with gantry-based concrete systems flowing through capital-intensive channels while compact extrusion units reach mid-tier contractors via rental networks. Technology choices cascade through application requirements, determining which segments capture margin premiums versus volume scale.
Product Type:
Concrete 3D printers move through direct manufacturer sales to large housing developers, while hybrid and material extrusion systems increasingly route through equipment-as-a-service platforms serving Scandinavia's mid-market builders.
- Concrete 3D Printers:Gantry-mounted systems deposit cementitious mixes with layer heights of 10-50 mm and compressive strengths exceeding 30 MPa after post-processing. German housing developers in Bavaria and North Rhine-Westphalia are concentrating procurement here as DIBt approvals validate load-bearing wall applications under tightened EU Green Deal thresholds.
- Hybrid 3D Printers:These systems converge extrusion printing with robotic reinforcement placement, creating integrated workflow premiums. Demand is climbing fastest among Dutch and Danish contractors seeking to displace traditional formwork carpentry crews in multi-story residential enclosures.
- Material Extrusion Printers:Compact, mobile units serve on-site housing applications across Northern Europe.
- Powder Bed Fusion Printers:Industrial systems occupy prefabricated facade production niches with limited deployment.
Concrete 3D printers dominate installed base. Hybrid 3D printers are where expansion concentrates.
Technology:
Cost tier stratification separates mature extrusion methods from emerging deposition techniques, with binder systems commanding premium pricing for specialized infrastructure applications.
- Binder Jetting:Powder-based binding processes enable complex geometries in prefabricated structural components. French CSTB fast-track evaluations are accelerating adoption for novel binder systems in facade elements.
- Material Extrusion:Layer-by-layer cement deposition leads on-site housing adoption across Germany and the Netherlands. Municipal housing corporations in Denmark are specifying this technology for social housing renewals.
- Powder Binder Jetting:Narrow niche in precast facade manufacturing with limited geographic penetration.
- Direct Energy Deposition:Wire-arc additive systems for bridge reinforcement are penetrating municipal infrastructure budgets in the Netherlands.
Material extrusion commands volume leadership. Binder jetting captures the steepest expansion trajectory in specialized applications.
Application:
Customer type dictates channel access, with public infrastructure buyers consolidating procurement through framework agreements while private developers maintain fragmented subcontractor relationships.
- Residential Buildings:Mid-rise perimeter wall assemblies represent the core volume application. Housing associations in the Netherlands are bundling design, printing, and finishing services through consolidated contracts.
- Commercial Structures:Office and retail shells require higher precision tolerances and extended post-processing. German developers are absorbing these costs to meet accelerated enclosure schedules.
- Bridges:Wire-arc additive manufacturing for structural reinforcement is specified in Dutch and Danish transport authority tenders.
- Infrastructure:Tunnel linings and civil engineering components face precast concrete substitution pressure from Polish and Romanian fabrication plants.
Residential buildings anchor current deployment. Bridges represent the fastest-climbing application as public procurement normalizes additive specifications.
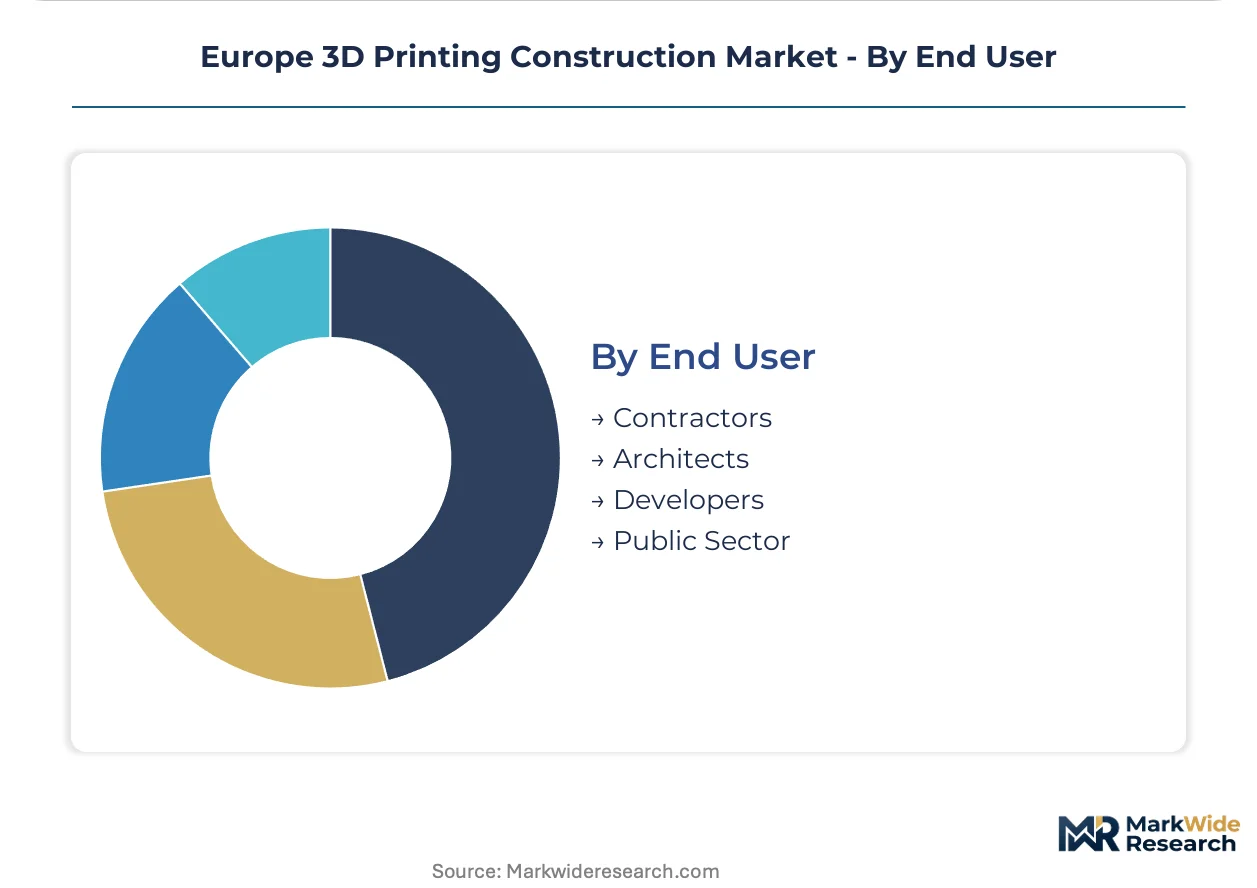
End User:
Volume concentration sits with generalist contractors, while margin pools shift toward architects and public buyers who control specification authority and bundled service procurement.
- Contractors:General construction firms execute the majority of printed wall installations. Equipment rental access through PERI Group's BOD2 fleet is lowering capital barriers for Scandinavian mid-tier builders.
- Architects:Design professionals increasingly specify printed elements in early project phases. COBOD International leverages its Nordic project portfolio to sustain technical credibility with this segment.
- Developers:Private housing developers in Germany drive demand for load-bearing printed walls.
- Public Sector:Dutch and Danish transport authorities are unwinding reliance on traditional concrete contractors through additive specifications.
Contractors capture execution volume. Public sector procurement is where specification authority is concentrating fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine corridor's freight rail density underwrites Germany's centrality in European construction equipment logistics, while North Sea port capacity anchors material flows into the Netherlands and Denmark.
Germany
Federal transport infrastructure renewal and municipal housing densification drive equipment deployment. DIBt approvals for load-bearing printed walls validate cross-border product acceptance under EU Green Deal thresholds. Bavaria and North Rhine-Westphalia concentrate gantry system procurement for mid-rise residential enclosures.
Netherlands
Delta region flood defense upgrades and port hinterland expansion create demand for rapid structural fabrication. Dutch transport authorities specify printed bridge components in public tenders, normalizing additive specifications in civil engineering. Randstad housing associations bundle design-to-finish procurement through consolidated framework agreements.
Denmark
Municipal social housing renewal programs and Copenhagen metro extensions accelerate printed element adoption. Danish building codes incorporate EU AI Act documentation standards for autonomous print-path software. Odense and Aarbourg municipal housing corporations pilot consolidated sourcing for multi-story residential renewals.
France
Grand Paris Express tunnel linings and Lyon conurbation housing targets stimulate material qualification activity. CSTB fast-track evaluations accelerate novel binder system approvals under Construction Products Regulation CE marking pathways. Île-de-France prefabrication clusters integrate powder binder jetting for complex facade geometries.
United Kingdom
Thames Tideway super-sewer ancillary structures and modular housing factory investments create specification pull. Building Safety Regulator oversight of construction product compliance shapes admixture disclosure requirements. Greater Manchester and West Midlands development corporations trial printed structural cores for mid-rise residential schemes.
Europe 3D Printing Construction Market Competitive Landscape
Listed leaders compete with private specialists across equipment financing and material qualification capabilities. The vendor base stratifies between gantry-system manufacturers capturing large-developer contracts and compact-printer specialists serving rental-network distribution. Three archetypes dominate: Nordic-origin gantry builders, German-Austrian equipment-as-a-service platforms, and French-Dutch materials-technology integrators. Competitive moves concentrate on CE marking pathway acceleration and equipment rental network densification.
Among Nordic-origin system builders, COBOD International and MX3D occupy positions anchoring technical credibility through accumulated project portfolios. PERI Group represents the equipment-as-a-service archetype, with its BOD2 fleet rental model lowering capital barriers for mid-tier Scandinavian contractors. Sika AG exemplifies materials-technology integration, bridging chemical admixture qualification with printer-native mortar development under ECHA REACH compliance frameworks.
| Leading Market Players |
|---|
| COBOD International |
| MX3D |
| Sika AG |
| XtreeE |
| Constructions-3D |
| CyBe Construction |
| WASP |
| PERI Group |
| Skanska Group |
| Others |
Value Network & Pricing Analysis
Portland cement substitution by novel geopolymer binders is redrawing raw-material sourcing maps while compressing formulation cost curves across German and Dutch project portfolios.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates equipment procurement, with CE-marked gantry systems commanding certification premiums over uncertified compact units. Price differentiation hinges on DIBt approval status and bundled after-sales calibration support. Cost compression in economy-tier rental access is intensifying because PERI Group's BOD2 fleet expansion floods Scandinavian mid-market channels. Municipal housing corporations exhibit lowest price sensitivity; fragmented general contractors face acute margin pressure.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port congestion ripple through cementitious admixture delivery schedules, extending lead times for REACH-qualified mortar formulations. Supply concentrates in Germany, the Netherlands, and Denmark for gantry system assembly, while specialty chemical inputs draw from Belgium and France. Raw material dependencies span Portland cement clinker, polycarboxylate superplasticizers, and steel reinforcement fiber. Single-source vulnerability sits with ECHA REACH-compliant admixture suppliers. Distribution runs through manufacturer-direct sales for large developers and equipment-as-a-service platforms for mid-tier contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
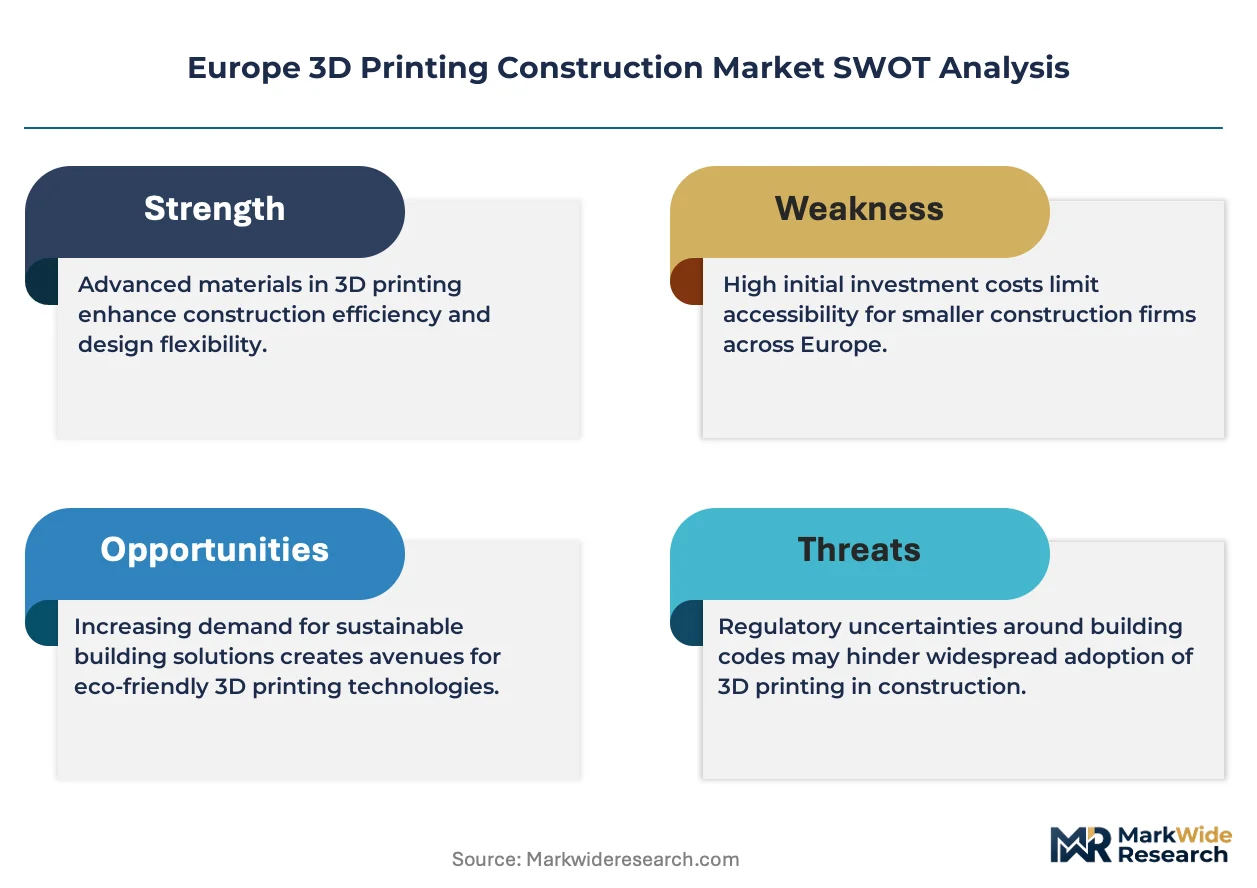
Incumbents must navigate substitution defense against precast concrete plants in Poland and Romania that offer faster delivery certainty for standardized structural elements.
For Market Incumbents: Shield DIBt-approved product positioning through accelerated CSTB parallel qualifications in France, absorbing EU AI Act compliance costs into subscription pricing to preserve margin structures against emerging hybrid-system specialists.
For New Entrants and Emerging Players: Lead with wire-arc additive manufacturing capabilities for bridge reinforcement tenders in Dutch and Danish transport authority procurement, leveraging equipment-as-a-service rental models to bypass capital barriers that constrain Scandinavian mid-tier builder adoption.
For Investors and Strategic Acquirers: The market sits at a standardization phase that favors materials-technology integrators with ECHA REACH-compliant admixture portfolios; watch for DIBt approval expansion into novel binder systems as the inflection signal for re-rating vendor economics.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | DIBt and CSTB parallel approvals unlock cross-border product acceptance under EU Green Deal thresholds. |
| Equipment-as-a-Service Expansion | Rental network densification lowers capital barriers for Scandinavian mid-tier housing developers. |
| Hybrid System Integration | Convergence of extrusion printing with robotic reinforcement displaces traditional formwork carpentry crews. |
| Novel Binder System Development | Geopolymer formulations reduce Portland cement dependency while satisfying REACH compliance timelines. |
| AI Act Compliance Infrastructure | Algorithmic audit trail capabilities preserve CE marking eligibility for autonomous print-path software. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with equipment procurement managers at German housing developers, gantry system operators in Denmark, Dutch transport authority specification engineers, and ECHA REACH compliance officers at admixture suppliers. Secondary validation drew from DIBt approval registries, CSTB technical evaluation databases, EU Construction Products Regulation guidance documents, and Nordic municipal housing corporation tender archives. Bottom-up equipment deployment counts were triangulated against top-down construction spend forecasts.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product type, technology modality, application vertical, and end-user archetype. CAGRs were derived from regression analysis of historical equipment procurement patterns against EU Green Deal regulatory milestone timelines. Industry-specific inputs incorporated DIBt approval velocity, REACH certification cycle durations, and public infrastructure tender specification trends.
Forecasts assume regulatory continuity in EU Green Deal embodied-carbon thresholds and ECHA REACH admixture governance; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Germany Prefab Wood Buildings Market
Building Construction
Oman Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Tanzania Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Energy-Efficient Building Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Qatar Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
France Prefab Wood Building Market
Building Construction
Turkey Commercial Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market