
 Construction Market | 2026-2036
Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Market Analysis
Saudi Arabia is rewriting the competitive map of the Construction Market through its giga-project pipeline, which is pulling engineering capacity from Europe and Asia. China State Construction Engineering Corporation leverages its domestic manufacturing scale to bid aggressively on these mega developments. Vinci anchors European presence through specialized transport and energy infrastructure expertise. Skanska differentiates via its green building certification depth and digital delivery platforms.
Construction encompasses the assembly of physical structures using cement, bricks, steel, and wood, combined with engineered systems for load-bearing, weather protection, and operational functionality. The sector serves residential shelter, commercial activity, industrial production, and public infrastructure. Residential application commands the largest volume base, though infrastructure is recording the fastest project pipeline growth as governments prioritize transport and energy networks. Mega projects concentrate the highest contract values and longest delivery cycles, while design-build contracting is displacing traditional fixed-price arrangements to accelerate delivery and transfer risk.
OSHA mandates govern site safety standards across the United States, while the EU Green Deal and CE marking frameworks shape material sourcing and carbon disclosure obligations in Europe. BIS certification requirements in India enforce structural quality thresholds for imported steel and cement. Stakeholders must track how regulatory divergence on embodied carbon accounting is fragmenting supply chain compliance costs across jurisdictions.
Market Dynamics
The Construction Market is being fundamentally restructured by embodied carbon accounting mandates that are fragmenting material specifications across regulatory jurisdictions. These disclosure requirements are forcing simultaneous redesign of procurement protocols, supplier qualification criteria, and project financing structures.
Growth Catalysts
- EU Green Deal embodied carbon limits:The tightening thresholds for building material carbon intensity are accelerating demand for low-carbon cement and mass timber structural systems across European public procurement.
- Data center construction surge:Hyperscale cloud infrastructure expansion is pulling prefabricated structural system volumes at scale previously reserved for residential tract development.
- India urban infrastructure budgets:Metropolitan rail, water, and power network investments are concentrating the fastest project pipeline growth in Mumbai, Delhi, and Bangalore corridors.
Market Restraints
- Steel and cement input cost volatility:Energy price swings and carbon border adjustment exposure are compressing fixed-price contract viability for mid-tier contractors.
- Chinese prefabrication supply concentration:Overreliance on integrated manufacturing-export clusters creates vulnerability to shipping rate spikes and trade policy friction.
- Technical limitation of cross-laminated timber spans:Current engineering constraints restrict mass timber to mid-rise commercial and residential, excluding high-rise structural applications.
Strategic Opportunities
- Underpenetrated Saudi giga-project pipeline:Neom, Red Sea Project, and Qiddiya developments represent concentrated demand for design-build contractors with modular delivery capability.
- Battery manufacturing facility construction:Gigafactory builds for electric vehicle supply chains are emerging as a discrete vertical with specialized cleanroom and power infrastructure requirements.
- Convergence of digital twin platforms and 5D BIM:Real-time cost-schedule-geometry integration is opening premium pricing for contractors with proprietary workflow integration.
Industry Challenges
- Structural engineer talent scarcity:Specialized expertise in seismic design and complex geometry modeling is concentrating among a shrinking pool of senior practitioners.
- Multi-jurisdiction certification timeline compression:LEED, BREEAM, and WELL simultaneous pursuit is extending pre-construction phases and freezing capital commitment windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Market |
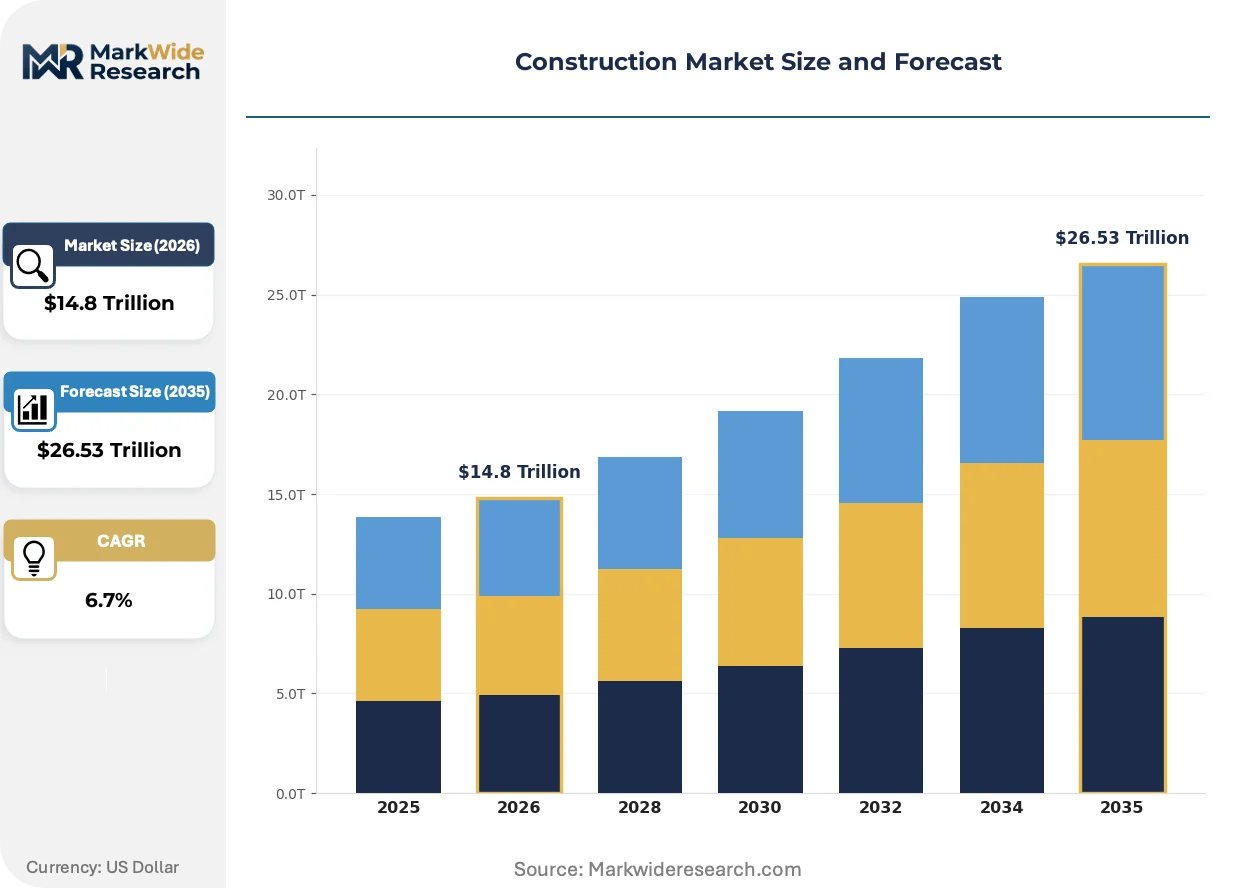
| Market Size in 2026 | $14.8 Trillion |
| Market Size in 2035 | $26.53 Trillion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Bricks, Steel, Wood Application: Residential, Commercial, Industrial, Infrastructure Project Size: Small Scale, Medium Scale, Large Scale, Mega Projects Contract Type: Fixed Price, Cost Plus, Time and Materials, Design-Build |
| Companies Covered | Vinci, ACS Group, Bechtel, China State Construction Engineering Corporation, Skanska, Turner Construction Co., Kiewit Corp., Fluor, AECOM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Market Emerging Trajectories
Construction delivery models are compressing project timelines through prefabrication depth and digital workflow integration. Material science advances and regulatory disclosure mandates are simultaneously reshaping specification authority and supplier relationships.
Mass timber structural systems are hybridizing traditional steel and concrete roles in mid-rise commercial and institutional buildings. Developers in Scandinavia and the Pacific Northwest are specifying cross-laminated timber for its carbon sequestration credentials and accelerated erection schedules. The technology is hybridizing procurement patterns by merging structural supplier selection with embodied carbon accounting compliance.
REACH and the EU Green Deal are mandating Environmental Product Declarations for imported construction materials entering European projects. Manufacturers must now document cradle-to-gate carbon intensity across cement, steel, and aluminum supply chains. Contractors serving EU public works are responding by qualifying alternative suppliers from Turkey, North Africa, and domestic sources with verified lower-carbon production.
Design-build contracting is displacing traditional design-bid-build arrangements for complex infrastructure and industrial projects. Owner organizations are transferring design risk to contractors with integrated engineering capability, particularly in data center and healthcare verticals. This pattern is most visible in the United States and Australia, where public agencies have relaxed procurement statutes to accelerate delivery timelines.
Construction Market Segmentation
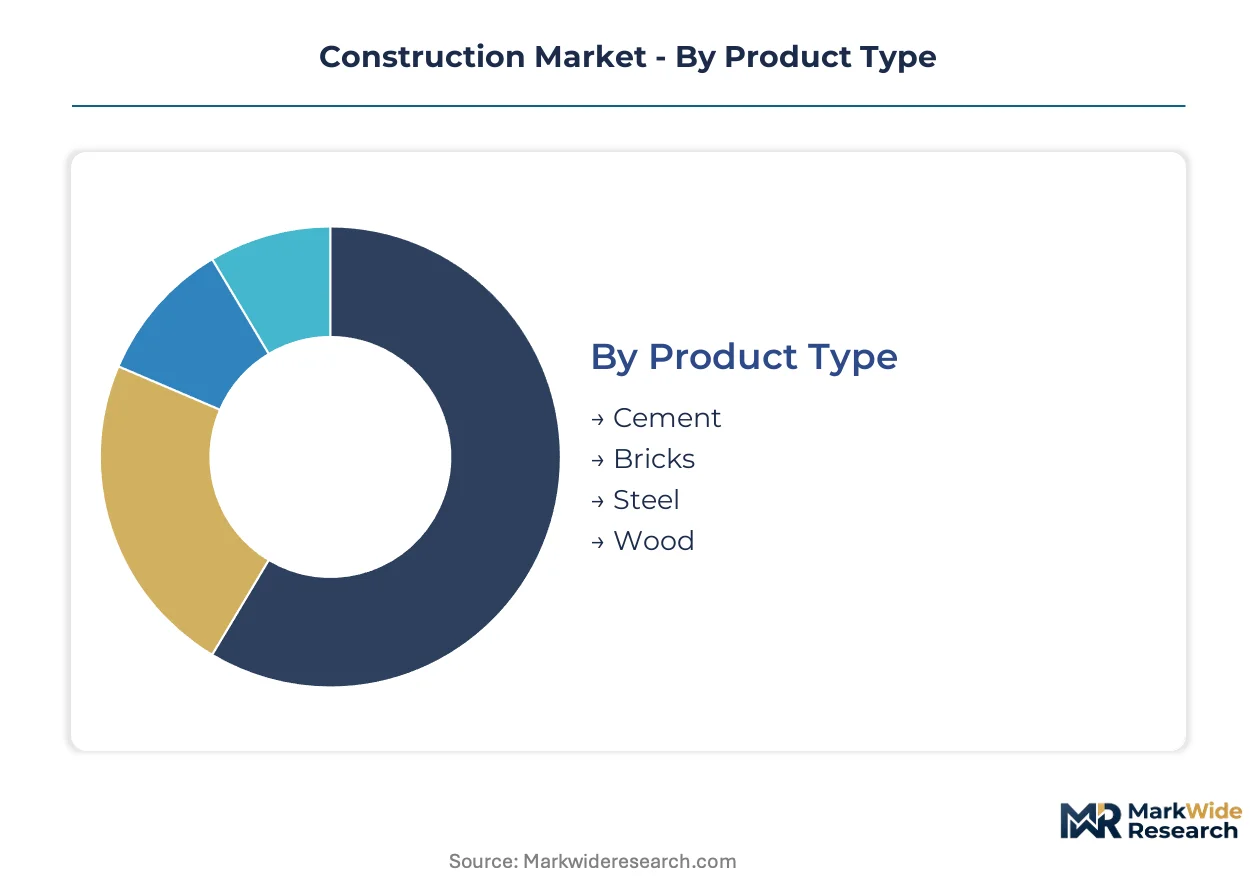
Construction market segmentation reveals how material specifications, project scale, and contracting structures fragment procurement authority across buyer types. Each dimension carries distinct margin profiles and regulatory exposure that reshape competitive positioning.
Product Type:
Material selection spans structural load-bearing requirements through finishing aesthetics, with embodied carbon thresholds now qualifying supplier pools.
- Cement:Portland and blended formulations dominate foundation and structural concrete applications. Demand concentrates in India and Saudi Arabia giga-project corridors where massive pour schedules favor bulk supply contracts with integrated producers.
- Steel:Rebar, structural sections, and sheet metal serve framing and envelope systems. European public procurement under EU Green Deal mandates is accelerating low-carbon electric arc furnace sourcing from Turkey and North African suppliers with verified Environmental Product Declarations.
- Bricks:Fired clay and concrete masonry units partition walls and clad low-rise structures. Regional quarry proximity governs specification in residential tract development across India and the United States.
- Wood:Dimensional lumber and engineered products frame residential and light commercial buildings. Cross-laminated timber is displacing steel in mid-rise Scandinavian and Pacific Northwest institutional projects seeking carbon sequestration credentials.
The dominant share belongs to cement, while steel is closing the gap fastest as infrastructure metal intensity rises.
Application:
End-use segments diverge sharply in project velocity, financing structures, and regulatory oversight density.
- Residential:Single-family and multifamily housing commands the largest volume base globally. Indian urban infrastructure budgets are channeling affordable housing density in Mumbai, Delhi, and Bangalore corridors where vertical construction accelerates.
- Commercial:Office, retail, and hospitality buildings prioritize speed-to-market and tenant customization. Data center construction is pulling prefabricated structural system volumes at scale previously reserved for residential tract development.
- Industrial:Manufacturing plants, warehouses, and processing facilities demand heavy foundations and specialized utility infrastructure. Battery gigafactory builds for electric vehicle supply chains are emerging as a discrete vertical with cleanroom and power infrastructure requirements.
- Infrastructure:Transport, energy, and water networks record the steepest expansion trajectory as governments prioritize deferred maintenance and capacity expansion. Saudi Arabia's giga-project pipeline concentrates the highest contract values and longest delivery cycles.
Residential maintains volume leadership, though infrastructure gains share fastest on public budget expansion.
Project Size:
Scale tiers determine contractor qualification thresholds, risk allocation mechanisms, and financing complexity.
- Small Scale:Single trades and minor renovations under local contractor capacity. Residential repair and improvement dominates volume across fragmented local markets.
- Medium Scale:Multi-trade commercial and institutional buildings requiring project management coordination. Design-build contracting is displacing traditional fixed-price arrangements to accelerate delivery and transfer risk.
- Large Scale:Complex buildings and civil works with extended schedules and staged payments. European transport and energy infrastructure anchors this tier through Vinci's specialized expertise.
- Mega Projects:Multi-billion developments with decade-long timelines and sovereign backing. Neom, Red Sea Project, and Qiddiya developments represent concentrated demand for contractors with modular delivery capability.
Medium scale captures the broadest contractor participation, while mega projects concentrate margin and reputation risk.
Contract Type:
Commercial structures allocate design risk, cost volatility exposure, and schedule accountability between owners and contractors.
- Fixed Price:Lump-sum bidding with contractor absorbing cost escalation risk. Steel and cement input cost volatility is compressing viability for mid-tier contractors under this structure.
- Cost Plus:Reimbursement of actual costs with fee for overhead and profit. Specialized industrial and healthcare projects deploy this mechanism where scope uncertainty prevails.
- Time and Materials:Unit pricing for labor and materials with markup. Emergency repair and maintenance work favors this flexibility.
- Design-Build:Single-point responsibility integrating engineering and construction. Owner organizations are transferring design risk to contractors with integrated capability, particularly in data center and healthcare verticals.
Fixed price retains share in standardized residential and commercial work, while design-build expands fastest in complex infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated manufacturing clusters in China anchor prefabrication capacity for global export, while sovereign wealth-funded developments in Saudi Arabia concentrate the highest-value project pipelines. Construction demand fragments across regulatory jurisdictions with diverging embodied carbon accounting standards.
United States
Data center construction from hyperscale cloud providers and IRA-funded clean energy infrastructure dominate project pipelines. OSHA mandates govern site safety standards while EPA disclosure requirements expand for federal construction contracts. The Texas Triangle and Northern Virginia data center clusters absorb prefabricated structural systems at unprecedented scale.
China
Urban renewal in tier-one cities and state-backed manufacturing facility construction sustain cement and steel consumption. MIIT dual carbon goals and GB standards enforce building energy efficiency thresholds in new construction. The Yangtze River Delta manufacturing-export corridor supplies integrated prefabrication systems for Middle Eastern giga-projects.
India
Metropolitan rail networks, affordable housing density targets, and semiconductor fab construction concentrate infrastructure budgets. BIS certification requirements enforce structural quality thresholds for imported steel and cement. The Mumbai-Delhi-Bangalore corridor channels the fastest urban infrastructure expansion.
Saudi Arabia
Neom, Red Sea Project, and Qiddiya developments represent multi-decade sovereign-backed construction demand. SFDA and local building codes govern material import and safety compliance for mega-project delivery. The northwest NEOM zone attracts design-build contractors with modular capability from European and Asian markets.
Germany
Transport infrastructure maintenance cycles and industrial facility modernization sustain civil engineering demand. REACH and EU Green Deal mandates accelerate low-carbon steel and cement sourcing through verified Environmental Product Declarations. The Rhine-Ruhr industrial corridor concentrates specialized energy infrastructure expertise.
Construction Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The market structures around three tiers: sovereign-backed mega-project contractors, regional infrastructure specialists, and trade-specific subcontractors. Two archetypes dominate—integrated engineering-construction firms with design-build capability and manufacturing-anchored players with captive prefabrication capacity. Competitive moves concentrate on strategic partnerships for technology access and geographic expansion into underpenetrated giga-project corridors.
Among European-based integrated contractors, Vinci and Skanska occupy positions reflecting divergent specialization vectors—transport-energy infrastructure versus green building certification depth. China State Construction Engineering Corporation anchors the manufacturing-export archetype with domestic prefabrication scale enabling aggressive bidding on Saudi mega-developments. These three exemplify how competitive positioning fragments across regulatory compliance capability, modular delivery technology, and sovereign relationship depth.
| Leading Market Players |
|---|
| Vinci |
| ACS Group |
| Bechtel |
| China State Construction Engineering Corporation |
| Skanska |
| Turner Construction Co. |
| Kiewit Corp. |
| Fluor |
| AECOM |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta manufacturing corridor anchors global prefabrication capacity, with its integrated steel-cement-wood processing clusters translating scale economics into pricing leverage over Middle Eastern and European project developers. Contracting structures now embed carbon border adjustment exposure as a discrete cost line item, compressing fixed-price viability for mid-tier contractors while amplifying premium capture for verified low-carbon suppliers.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European public procurement, separating verified Environmental Product Declaration holders from conventional suppliers. Three-tier pricing stratifies across premium low-carbon cement, standard blended formulations, and economy-grade bulk supply. Steel and cement input cost volatility is intensifying margin compression for fixed-price contractors, while sovereign-backed mega-project developers in Saudi Arabia exhibit the lowest price sensitivity due to decade-long capital commitment horizons.
Supply Chain Analysis
Upstream limestone deposits, iron ore reserves, and engineered wood feedstocks draw from China, India, and the Nordic region respectively. Cement production rests on domestic clinker capacity; steel sourcing hinges on Turkish and North African electric arc furnace output for EU compliance; mass timber feeds from Scandinavian and Pacific Northwest forestry operations. Single-source vulnerability concentrates in Chinese prefabrication-export clusters. Distribution runs through integrated manufacturing-anchored players with captive modular production capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among sovereign wealth funds and hyperscale cloud operators, fragmenting procurement authority away from traditional commercial developers. This concentration shifts margin capture upstream to contractors with modular delivery capability and carbon compliance certification depth.
For Market Incumbents: Entrench design-build capability through proprietary digital twin platform integration, defending against emerging manufacturing-anchored entrants from China. Prioritize certification investment in BREEAM and LEED concurrent pursuit to compress pre-construction timelines. Backward integration into low-carbon cement sourcing secures margin position under tightening EU Green Deal thresholds.
For New Entrants and Emerging Players: Establish a beachhead in battery gigafactory construction, the most penetrable vertical given specialized cleanroom and power infrastructure requirements that favor niche technical depth over scale. Target the Saudi giga-project pipeline through modular delivery partnerships with European engineering firms. Lead with embodied carbon accounting compliance as the go-to-market differentiator.
For Investors and Strategic Acquirers: Carve-out targets emerge from mid-tier contractors with stranded fixed-price contract exposure and undeveloped design-build capability. Long-term viability favors integrated engineering-construction firms with sovereign relationship depth in Middle Eastern corridors. Watch for steel and cement input cost volatility as the inflection signal for distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Cement | Secures supply position under tightening EU Green Deal embodied carbon limits. |
| Design-Build Capability Acquisition | Captures premium pricing from data center and healthcare verticals transferring design risk. |
| Digital Twin Platform Development | Enables real-time 5D BIM integration for contractors seeking workflow differentiation. |
| Modular Delivery Partnership Formation | Opens access to Saudi giga-project pipeline requiring accelerated erection schedules. |
| Environmental Product Declaration Certification | Qualifies suppliers for European public procurement under REACH and EU Green Deal mandates. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with project developers at sovereign wealth funds, procurement directors at hyperscale cloud operators, engineering executives at integrated contractors, and sustainability officers at material suppliers. Secondary validation drew from EPA construction contract disclosures, EIA energy infrastructure databases, EU Green Deal regulatory filings, and BIS certification records. Bottom-up project pipeline aggregation was triangulated against top-down macroeconomic construction spend estimates.
Calibration against historical cement and steel consumption patterns informed volume projections across the analysis window. Segmentation dimensions modeled include material type, application vertical, project scale tier, and contracting structure. CAGRs were derived from regression analysis of public budget trajectories and private capital deployment trends, with cross-checking against data center capex cycles and giga-project announcement pipelines.
Stress conditions across energy price volatility, carbon border adjustment implementation timing, and trade policy friction were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and sovereign funding continuity. Cross-checking against IEA infrastructure investment benchmarks and World Bank construction sector indicators is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Oman Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Early Production Facility Market
Building Construction
US Offsite Construction Market
Building Construction
China Building Construction Market
Building Construction
France Prefab Homes Market
Building Construction
Indonesia Infrastructure Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Tunnels Design and Construction Market
Building Construction
Europe 3D Printing Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Spain Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Sweden New Construction Market
Building Construction
France Prefab Wood Building Market