
 Spain Prefab Wood Buildings Market | 2026-2036
Spain Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Prefab Wood Buildings Market Analytics
Green mortgage securitization and build-to-rent leasing vehicles is tilting capital toward developers with standardized product platforms. Balat leverages its Andalusian manufacturing footprint to control panelized system costs. Viprehome sustains competitive positioning through architect-direct channel relationships across Catalonia. Madergia anchors its model on R&D intensity in cross-laminated timber engineering.
Spain prefab wood buildings are structural envelope systems manufactured off-site using engineered wood products such as CLT, glulam, and SIPs, then assembled on location to achieve precision tolerances of two millimeters. These systems serve residential and commercial clients seeking accelerated construction timelines and reduced on-site labor exposure. Panelized systems dominate current output volume due to transport flexibility and crane-access constraints on narrow Spanish urban plots. Modular construction represents the fastest-growing construction method as hospitality and multi-family developers pursue repeatable room-unit economics. Residential homes command the deepest margin pool among building types, driven by premium pricing for energy-certified single-family units in coastal municipalities.
Spain's Ministry of Transport and Urban Agenda enforces CTE compliance for structural fire safety and acoustic separation in timber buildings, while BREEAM ES certification shapes developer bidding criteria for public land concessions. The EU Green Deal's embodied carbon reporting requirements will tighten material sourcing disclosures for imported engineered wood. Stakeholders must monitor whether domestic CLT capacity expansion keeps pace with project pipeline growth or triggers supply bottlenecks for certified structural grades.
Market Dynamics
Spain's prefab wood building sector is compressing construction timelines through panelized system standardization while Madrid and Barcelona municipal authorities accelerate modular housing procurement. The collision of updated Código Técnico de la Edificación energy thresholds with constrained urban crane access is forcing design-tradeoff decisions that favor off-site fabrication.
Growth Catalysts
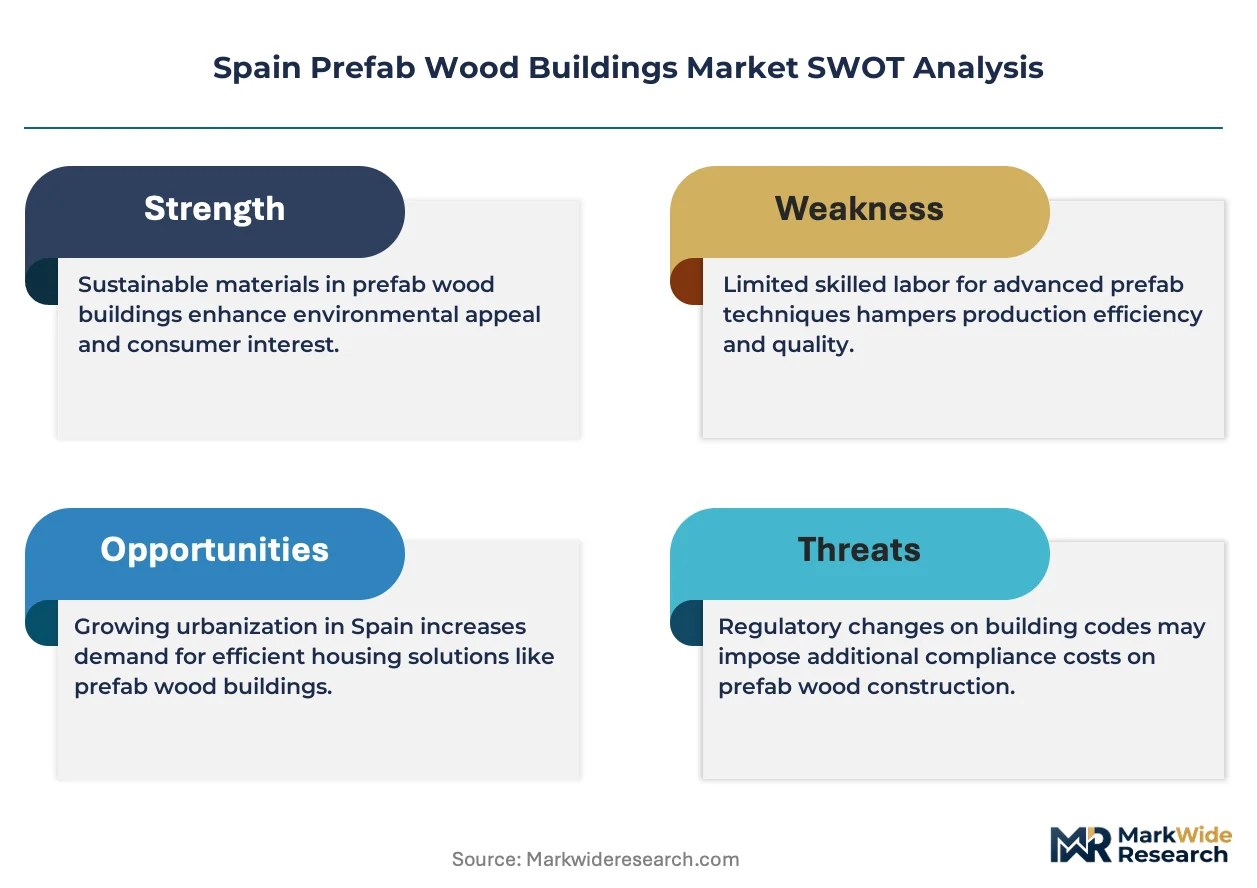
- CTE Energy Performance Mandates:Spain's tightened thermal envelope requirements for timber structures create compliance-driven demand for factory-precision panel joints that on-site carpentry cannot replicate.
- Andalusian Vacation Home Corridor:Costa del Sol developers are specifying CLT-based vacation units to compress permitting-to-occupancy cycles for seasonal rental income capture.
- Cross-Laminated Timber Engineering:Advances in Spanish CLT fire-rating certification are unlocking mid-rise residential applications previously reserved for concrete frames.
Market Restraints
- Certified Structural Timber Supply:Domestic CLT capacity expansion lags project pipeline growth, creating import dependency for PEFC-certified structural grades from Austrian and German suppliers.
- Urban Plot Crane Constraints:Narrow Barcelona and Madrid infill sites limit modular unit dimensions, forcing panelized fallback and erasing modular labor savings.
- Fire Safety Compliance Friction:CTE acoustic separation and structural fire safety testing timelines extend project pre-construction phases by four to six months versus conventional steel.
Strategic Opportunities
- Balearic and Canary Island Resorts:Insular logistics costs for conventional materials create premium capture potential for locally prefabricated timber hospitality units.
- EU Green Deal Embodied Carbon Reporting:Mandatory material sourcing disclosures will advantage domestic Spanish CLT producers with short-haul supply chains over Nordic competitors.
- Architect-Direct Channel Expansion:Bypassing traditional general contractor markups through design-build timber specialists is penetrating Catalonia's high-end single-family segment.
Industry Challenges
- Digital Fabrication Talent Scarcity:CNC programming and BIM-to-factory workflow expertise remains concentrated among Basque Country technical institutes, constraining Andalusian plant scaling.
- BREEAM ES Certification Timeline:Public land concession bidding criteria requiring BREEAM ES ratings demand six-month pre-qualification periods that strain developer working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Prefab Wood Buildings Market |
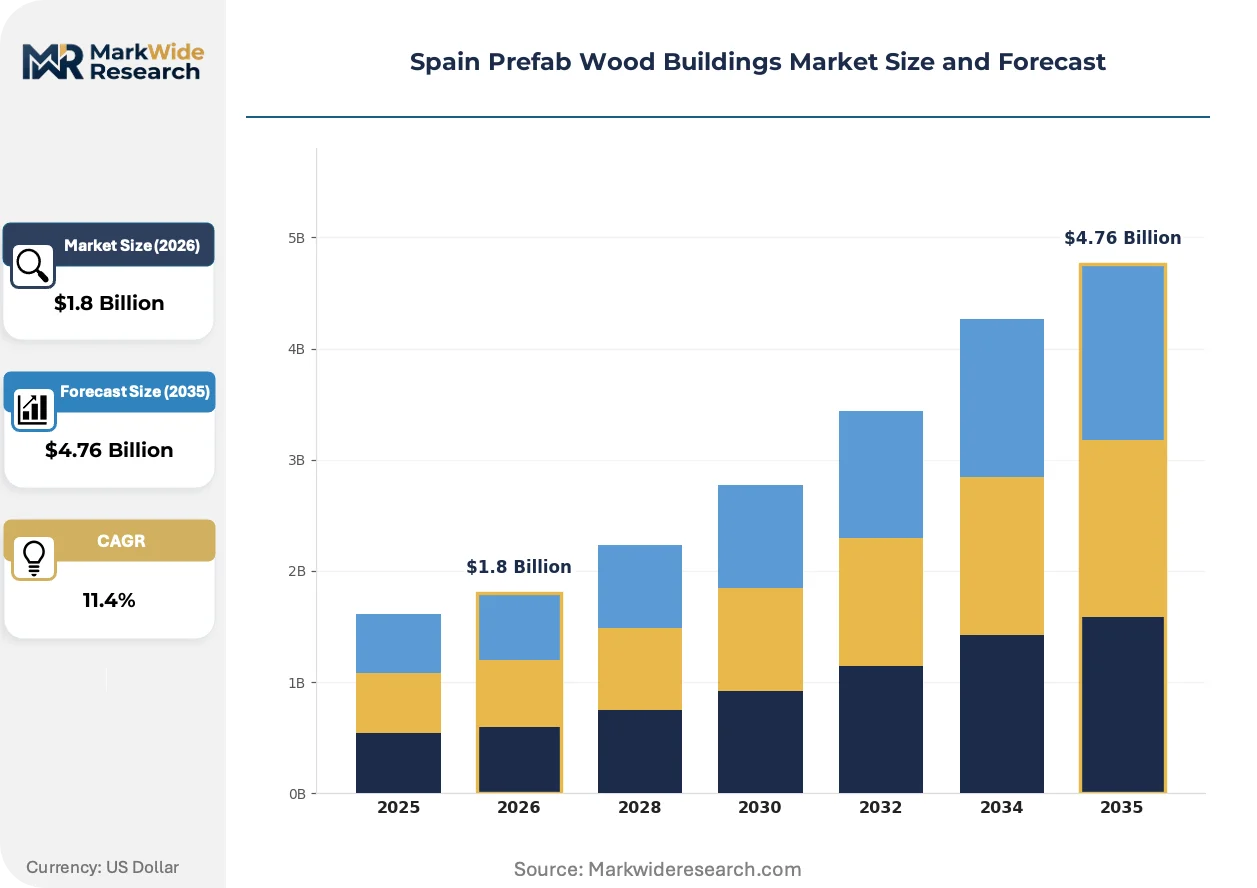
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Residential Homes, Commercial Buildings, Recreational Structures, Multi-Family Units Construction Method: Panelized Systems, Modular Construction, Stackable Units, Hybrid Systems End User: Homeowners, Property Developers, Contractors, Architects Application: Eco-Friendly Housing, Vacation Homes, Urban Development, Disaster Relief |
| Companies Covered | Tokamadera Estructuras Modulares S.L, Cabisuar SA, Viprehome, Balat, Canval Empresa Constructora S.L, Casas De Madera Caminas, Sismoha, Casas Tecnohome, Madergia, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Prefab Wood Buildings Market Evolving Landscape
Digital fabrication workflows and material certification protocols are compressing design-to-assembly cycles while reshaping competitive advantage around factory precision rather than on-site craft skill.
Cross-laminated timber is collapsing the traditional height limitations for wood construction in Spanish urban infill. Hospitality developers in Barcelona are specifying five-story CLT frames for boutique hotels. Factory-controlled char-layer engineering is collapsing the perceived fire-safety gap with concrete, enabling insurance parity that unlocks institutional financing.
Spain's updated Código Técnico de la Edificación is tightening embodied carbon disclosure requirements for public housing tenders. Developers must now document cradle-to-gate emissions for engineered wood products. The regulation is accelerating domestic CLT certification investments as imported Nordic timber faces scrutiny under new procurement criteria.
Build-to-rent institutional investors are consolidating procurement around standardized room-unit platforms. Traditional architect-custom builder relationships are fragmenting as Blackstone and local SOCIMIs issue master specifications that pre-qualify only panelized system vendors. The shift is most visible in Madrid's Ensanche and Barcelona's 22@ districts where repeatability commands rent premiums.
Spain Prefab Wood Buildings Market Segmentation
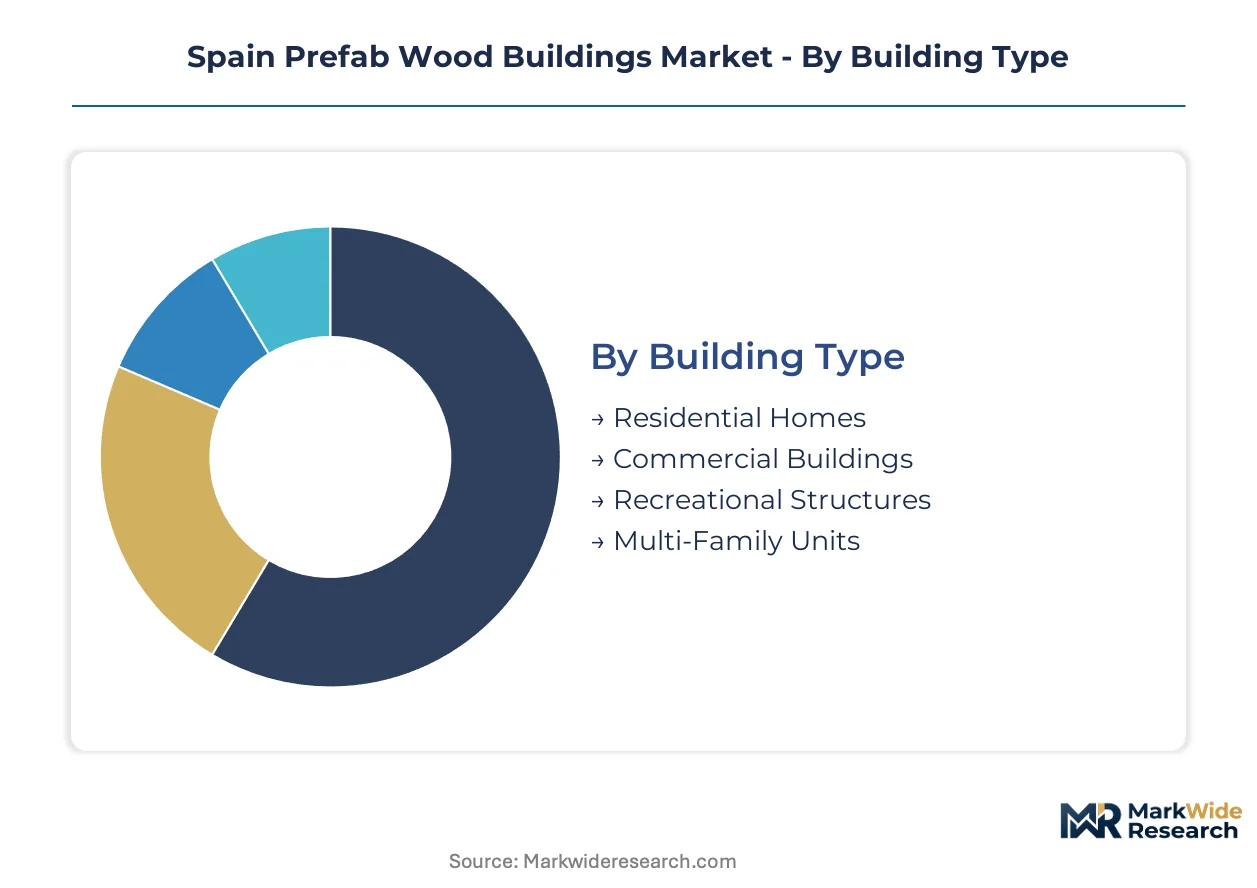
Segmentation reveals how prefab wood building demand fragments across distinct technical specifications, procurement channels, and use-case economics. Each dimension carries unique margin profiles and after-sales service intensity that shape vendor positioning strategies.
Building Type:
After-sales service intensity varies sharply across building types, with multi-year warranty obligations and energy performance monitoring driving recurring revenue potential for residential-focused vendors.
- Residential Homes:Single-family detached and semi-detached structures utilizing CLT wall panels and glulam beam systems. Costa del Sol municipalities command premium pricing for energy-certified units where seasonal rental income justifies accelerated construction timelines.
- Multi-Family Units:Mid-rise apartment buildings and townhome complexes employing platform-frame or mass timber structural systems. Barcelona and Madrid municipal housing authorities are scaling procurement of these units to address affordability mandates.
- Commercial Buildings:Office, retail, and mixed-use timber structures requiring enhanced fire-rating certification and acoustic separation engineering.
- Recreational Structures:Pavilions, glamping pods, and temporary hospitality installations emphasizing rapid deployment and minimal foundation requirements.
By volume, Residential Homes leads. By growth pace, Multi-Family Units is ahead.
Construction Method:
Cost tier differentiation separates premium factory-controlled precision from economy on-site assembly alternatives, with crane access constraints and transport logistics dictating method selection.
- Panelized Systems:Factory-manufactured wall, floor, and roof components shipped flat-packed for on-site crane erection. Narrow urban plots in Barcelona's Eixample and Madrid's Centro districts favor this method due to dimensional flexibility and reduced street closure permits.
- Modular Construction:Fully volumetric room units produced with interior finishes complete, then stacked and connected on-site. Hospitality developers along Andalusia's Costa del Sol specify these for repeatable room-unit economics and compressed permitting-to-occupancy cycles.
- Hybrid Systems:Combined panelized and modular approaches optimizing structural performance with design flexibility.
- Stackable Units:Interlocking container-adapted timber modules designed for temporary or relocatable deployment scenarios.
Panelized Systems dominates current output volume. Modular Construction is expanding most quickly as institutional investors consolidate procurement around standardized platforms.
End User:
Customer type determines procurement channel structure, with direct architect relationships commanding margin premiums versus contractor-mediated distribution.
- Property Developers:Build-to-rent SOCIMIs and hospitality investors issuing master specifications that pre-qualify panelized system vendors. These stakeholders prioritize repeatability and rent premium capture in Madrid's Ensanche and Barcelona's 22@ districts.
- Architects:Design-direct channel relationships penetrating Catalonia's high-end single-family segment, bypassing traditional general contractor markups through design-build timber specialists.
- Homeowners:Individual purchasers of single-family vacation homes and primary residences, concentrated in coastal Andalusian municipalities.
- Contractors:General construction firms integrating prefab wood systems as subcontractors within conventional project delivery models.
Property Developers lead by project value concentration. Architects are gaining share fastest through design-direct channel expansion.
Application:
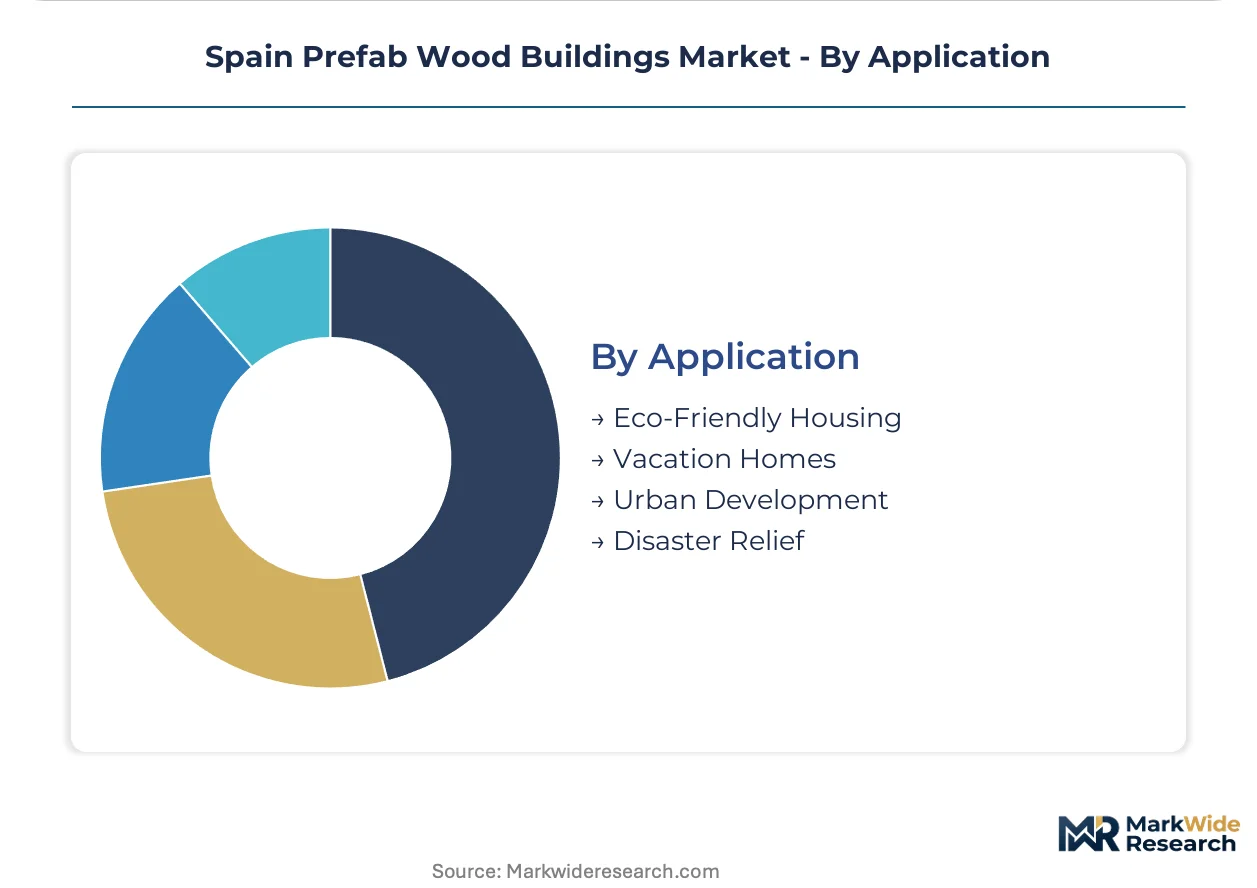
Application focus shapes regulatory compliance burden and certification timeline, with public housing tenders imposing stricter embodied carbon disclosure requirements than private vacation home development.
- Vacation Homes:Seasonal and second-residence units prioritizing rapid construction and energy performance certification for rental income optimization. Costa del Sol corridor developers specify CLT-based systems to compress permitting cycles.
- Eco-Friendly Housing:Net-zero and passive house-standard residences requiring BREEAM ES certification and cradle-to-gate emissions documentation under Spain's updated Código Técnico de la Edificación.
- Urban Development:Infill and densification projects on constrained Madrid and Barcelona sites where off-site fabrication resolves crane access limitations.
- Disaster Relief:Rapid-deployment temporary housing and community infrastructure for emergency response scenarios.
Vacation Homes leads by current project pipeline volume. Eco-Friendly Housing is climbing the fastest as EU Green Deal embodied carbon reporting tightens procurement criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's updated Código Técnico de la Edificación is channeling public procurement toward modular timber solutions while regional housing authorities compete for factory investment. Municipal land concessions in Madrid and Barcelona now embed energy performance thresholds that favor off-site fabrication precision.
Madrid
The capital's municipal housing authority is scaling procurement of modular multi-family units to meet affordability mandates. CTE compliance for structural fire safety shapes developer bidding criteria for public land concessions. The Ensanche district concentrates build-to-rent institutional investment where repeatability commands rent premiums.
Catalonia
Barcelona's 22@ district and Eixample infill sites drive architect-direct channel penetration for high-end single-family timber construction. BREEAM ES certification requirements for public tenders impose six-month pre-qualification timelines. Narrow urban plots favor panelized systems over volumetric modular due to crane access constraints.
Andalusia
Costa del Sol vacation home developers specify CLT-based units to compress permitting-to-occupancy cycles for seasonal rental capture. The EU Green Deal's embodied carbon reporting advantages domestic CLT producers with short-haul supply chains. Málaga and Marbella municipalities command premium pricing for energy-certified structures.
Basque Country
Digital fabrication talent concentrates here, with CNC programming and BIM-to-factory workflow expertise anchored in regional technical institutes. CTE acoustic separation testing extends pre-construction phases for timber projects versus conventional steel. San Sebastián and Bilbao host R&D-intensive engineering clusters for cross-laminated timber fire-rating certification.
Valencia
The region's logistics infrastructure supports panelized system distribution to Mediterranean coastal developments. Updated CTE thermal envelope requirements create compliance-driven demand for factory-precision panel joints. Alicante and Valencia cities are emerging as secondary hubs for vacation home prefabrication serving northern European buyers.
Spain Prefab Wood Buildings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement pathways that diverge between municipal housing tenders and architect-direct relationships. The vendor base organizes around three strategic archetypes: Andalusian manufacturing footprint controllers, Catalonia-based design-build specialists, and R&D-intensive engineering houses. Capacity expansion and certification investments represent the dominant competitive moves as domestic CLT production races to match pipeline growth.
Among Spanish fabricators, Balat exemplifies the manufacturing-footprint archetype through its Andalusian base, while Viprehome occupies a position within the architect-direct channel tier, and Madergia anchors the R&D-intensive engineering cluster focused on cross-laminated timber systems. These three represent distinct positioning vectors that map onto the market's geographic and procurement segmentation.
| Leading Market Players |
|---|
| Tokamadera Estructuras Modulares S.L |
| Cabisuar SA |
| Viprehome |
| Balat |
| Canval Empresa Constructora S.L |
| Casas De Madera Caminas |
| Sismoha |
| Casas Tecnohome |
| Madergia |
| Others |
Value Network & Pricing Analysis
Barcelona-Valencia maritime freight corridors carry Austrian and German CLT imports at rates that compress margins for domestic fabricators while amplifying price spreads between PEFC-certified premium grades and standard structural timber. This logistics cost dynamic concentrates supply power among Basque Country engineering houses with captive CNC capacity, forcing Andalusian vacation-home specialists to absorb transport premiums or downgrade certification tiers.
Pricing Analysis
Certification level creates the primary spread between BREEAM ES-compliant CLT systems and conventional glulam alternatives, with factory-controlled fire-rating testing adding fifteen to twenty percent premiums over on-site carpentry. Project-based contracting dominates, though build-to-rent SOCIMIs are consolidating procurement around standardized panel specifications that erode customization premiums. Cost compression in mid-rise multi-family segments intensifies as Madrid municipal housing tenders prioritize lowest compliant bid over performance differentiation. Property developers exhibit highest price sensitivity due to compressed yield thresholds on affordable housing mandates, while architect-direct channels in Catalonia sustain margin tolerance for design flexibility.
Supply Chain Analysis
EU timber import restrictions under the EU Green Deal's embodied carbon reporting regime constrain Nordic supply flows, accelerating Spanish domestic CLT capacity investments. Manufacturing concentrates in Austria, Germany, and emerging Spanish Basque Country facilities, with engineered wood products drawing from spruce and pine feedstocks certified under PEFC chain-of-custody protocols. Single-source vulnerability runs through Austrian structural-grade CLT suppliers whose fire-rating certifications anchor mid-rise project financing. Distribution runs through design-build timber specialists bypassing traditional general contractor markups, particularly in Catalonia's high-end residential corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's prefab wood building sector rewards early movers who embed regulatory entrenchment through CTE certification timelines that lock out later entrants. The six-month BREEAM ES pre-qualification period functions as a structural moat.
For Market Incumbents: Build certification moats by accelerating domestic CLT fire-rating investments ahead of EU Green Deal sourcing disclosure mandates. Anchor capacity expansion in Basque Country technical institutes to capture scarce CNC programming talent before Andalusian competitors scale. Vertical integration into glulam beam production mitigates Austrian import dependency as project pipelines outstrip certified structural timber supply. For New Entrants and Emerging Players: Build out Balearic and Canary Island resort fabrication footprints where insular logistics costs for conventional materials create localized pricing power. Target hospitality developers seeking rapid permitting-to-occupancy cycles with stackable timber modules designed for seasonal rental optimization. Architect-direct channel partnerships in Valencia's emerging vacation home corridor bypass entrenched Madrid-Barcelona procurement networks. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Andalusian panel manufacturers lacking succession planning and digital fabrication capability. Long-term viability hinges on whether domestic CLT capacity expansion matches pipeline growth or triggers import dependency spirals. Monitor CTE acoustic separation testing timeline extensions as inflection indicator for working capital stress among pre-qualified vendors.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic CLT Capacity Expansion | Reduces PEFC-certified import dependency from Austrian suppliers under EU Green Deal sourcing rules. |
| BREEAM ES Certification Acceleration | Shortens six-month pre-qualification timelines that strain developer working capital on public tenders. |
| Architect-Direct Channel Control | Bypasses general contractor markups in Catalonia's high-end single-family segment. |
| Digital Fabrication Talent Capture | Secures scarce CNC programming expertise concentrated in Basque Country technical institutes. |
| Insular Resort Manufacturing Footprint | Exploits Balearic and Canary Island logistics premiums to capture hospitality repeat-unit economics. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with timber engineering directors, municipal housing procurement officers, hospitality development executives, and CLT plant operations managers; and secondary validation against CTE regulatory filings, BREEAM ES certification databases, EU timber trade statistics, and Basque Country technical institute R&D disclosures. Bottom-up project pipeline enumeration across Madrid, Barcelona, and Costa del Sol municipalities was triangulated against top-down engineered wood product consumption estimates from Spanish construction material flow accounts.
Forecast inputs span building type, construction method, end-user procurement channel, and application focus across the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macro construction output assumptions. CLT fire-rating certification velocity and municipal affordable housing tender issuance frequency served as industry-specific demand drivers in the analytical framework.
Stress conditions across Austrian CLT import cost volatility, CTE acoustic separation testing timeline variability, and Basque Country digital fabrication talent migration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EU Green Deal implementation pacing and domestic manufacturing capacity commissioning schedules. Material shifts in PEFC certification acceptance criteria or CTE structural fire safety thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Oman Construction Market
Building Construction
Egypt Construction Market
Building Construction
United Kingdom Data Center Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Scandinavia Construction Market
Building Construction
Italy Construction Market
Building Construction
France Prefab Wood Building Market
Building Construction
India Prefabricated Buildings Market
Building Construction
GCC Construction Market
Building Construction
Saudi Arabia Transportation Infrastructure Construction Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
UAE Facade Market
Building Construction
Turkey Construction Market
Building Construction
United Arab Emirates Infrastructure Market
Building Construction
Saudi Arabia Construction Market
Building Construction
Honduras Construction Market