
 Thailand Construction Equipment Market | 2026-2036
Thailand Construction Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Construction Equipment Market Insights
Equipment-as-a-service subscription models is decoupling ownership from utilization across Thailand's construction sector. Komatsu leverages its KOMTRAX telematics platform to anchor long-term fleet management contracts with major contractors. SANY competes on manufacturing scale from its Rayong assembly complex, while Volvo Construction Equipment differentiates through connected uptime guarantees and regional parts distribution.
Construction equipment encompasses heavy machinery engineered for earthmoving, material handling, and vertical lifting operations, with hydraulic systems typically rated between 20 and 400 horsepower depending on application class. These machines serve as productive capital assets across civil engineering, building construction, and resource extraction workflows. Excavators command the largest installed base among equipment types, reflecting sustained trenching and foundation work across Thailand's infrastructure pipeline. Telematics-enabled fleets represent the fastest-expanding technology category, as contractors prioritize fuel monitoring and predictive maintenance over conventional diesel-only specifications.
Thailand's Department of Industrial Works enforces emissions compliance through factory inspection protocols, while the Board of Investment conditions tax incentives on local content thresholds for machinery assembly. The Industrial Estate Authority of Thailand coordinates zoning permits that concentrate heavy equipment depots near eastern seaboard logistics corridors. Stakeholders must weigh telematics integration costs against evolving carbon monitoring requirements that will reshape fleet replacement cycles and financing structures.
Market Dynamics
Equipment-as-a-service models are decoupling ownership from utilization across Thailand's construction sector, compressing capital deployment cycles and rewiring contractor-vendor relationships around uptime metrics rather than asset transfer.
Growth Catalysts
- Eastern Economic Corridor infrastructure pipeline:Megaprojects spanning Chonburi, Rayong, and Chachoengsao provinces sustain trenching and foundation work demand. Public contractors anchor fleet replacement schedules.
- Board of Investment machinery incentives:Tax holidays and import duty exemptions for local assembly operations reshape supply chain geography. Foreign OEMs establish captive production to qualify.
- Telematics penetration:Fuel monitoring and predictive maintenance capabilities convert specification decisions from diesel-only to connected-first. Contractors prioritize total cost of ownership visibility.
Market Restraints
- Steel input volatility:Hydraulic cylinder and chassis fabrication costs fluctuate with regional commodity pricing. Manufacturers lack long-term hedge coverage.
- Emissions compliance friction:Thailand's Department of Industrial Works factory inspection protocols create certification bottlenecks. Retrofit timelines extend equipment procurement cycles.
- Used equipment import competition:Lower-hour Japanese and Korean excavators displace new domestic sales. Price-sensitive contractors arbitrage depreciation curves.
Strategic Opportunities
- Rayong manufacturing cluster expansion:Industrial Estate Authority of Thailand zoning permits concentrate heavy equipment depots near eastern seaboard logistics corridors. Assembly-to-port distance advantages compound.
- Carbon monitoring integration:Evolving fleet replacement criteria create openings for OEMs bundling telematics with emissions tracking. Financing structures adapt to carbon-linked residual values.
- Rental fleet digitization:Contractor demand for short-cycle equipment access without capital commitment expands addressable market for subscription-based fleet management.
Industry Challenges
- Telematics technician scarcity:Diagnostic and firmware update capabilities outpace vocational training pipeline. Service networks struggle to staff connected equipment support.
- Legacy fleet integration complexity:Mixed-age equipment pools complicate unified fleet management platform deployment. Data standardization gaps fragment operational visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Construction Equipment Market |
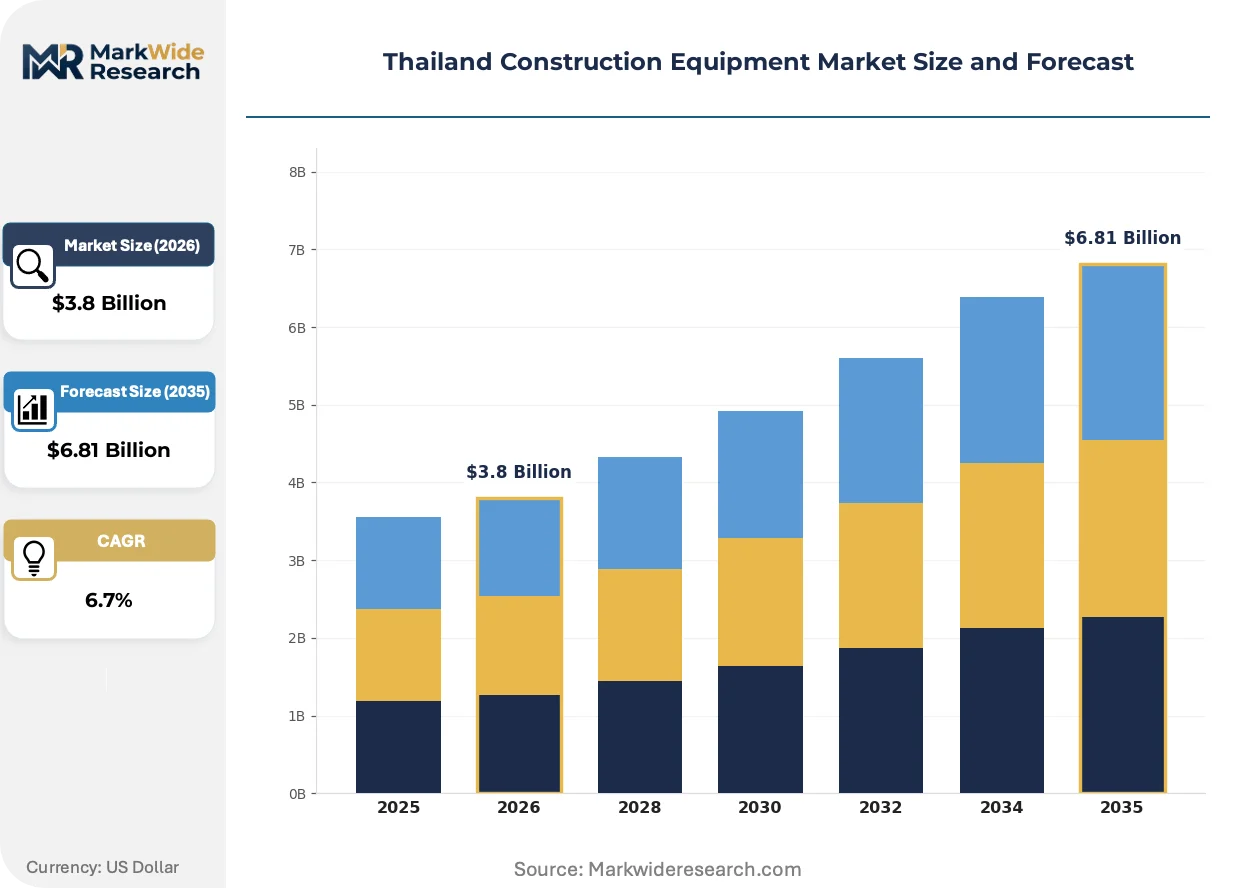
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Excavators, Bulldozers, Cranes, Loaders Application: Infrastructure Development, Residential Construction, Commercial Projects, Road Construction End User: Contractors, Builders, Government, Private Developers Technology: Telematics, Automation, Electric, Diesel |
| Companies Covered | Caterpillar, Komatsu, Volvo Construction Equipment, Hitachi Construction Machinery, SANY, Kobelco, XCMG, JCB, Liebherr, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Construction Equipment Market Trends and Innovations
Telematics-enabled fleet management is compressing specification criteria and rewiring competitive advantage around data services rather than mechanical performance alone.
Integrated telematics platforms are unifying equipment monitoring, maintenance scheduling, and fuel optimization into single-dashboard operations. Large contractors across Thailand's Eastern Economic Corridor are mandating connected specifications for new fleet additions. This convergence is compressing vendor selection criteria toward data interoperability and API accessibility.
Thailand's Board of Investment conditions tax incentives on local content thresholds for machinery assembly, forcing OEMs to reconfigure component sourcing. Foreign manufacturers are qualifying domestic suppliers for hydraulic systems and cab assemblies to maintain incentive eligibility. The policy most acutely affects excavator and wheel loader categories where import substitution carries the highest duty savings.
Contractor buying committees now weight total cost of ownership metrics above upfront capital expenditure in equipment selection. Equipment financiers and rental providers capture margin by underwriting utilization risk that contractors formerly self-insured through ownership. This behavioral shift concentrates most visibly among public infrastructure contractors managing multi-year project portfolios with variable equipment intensity.
Thailand Construction Equipment Market Segmentation
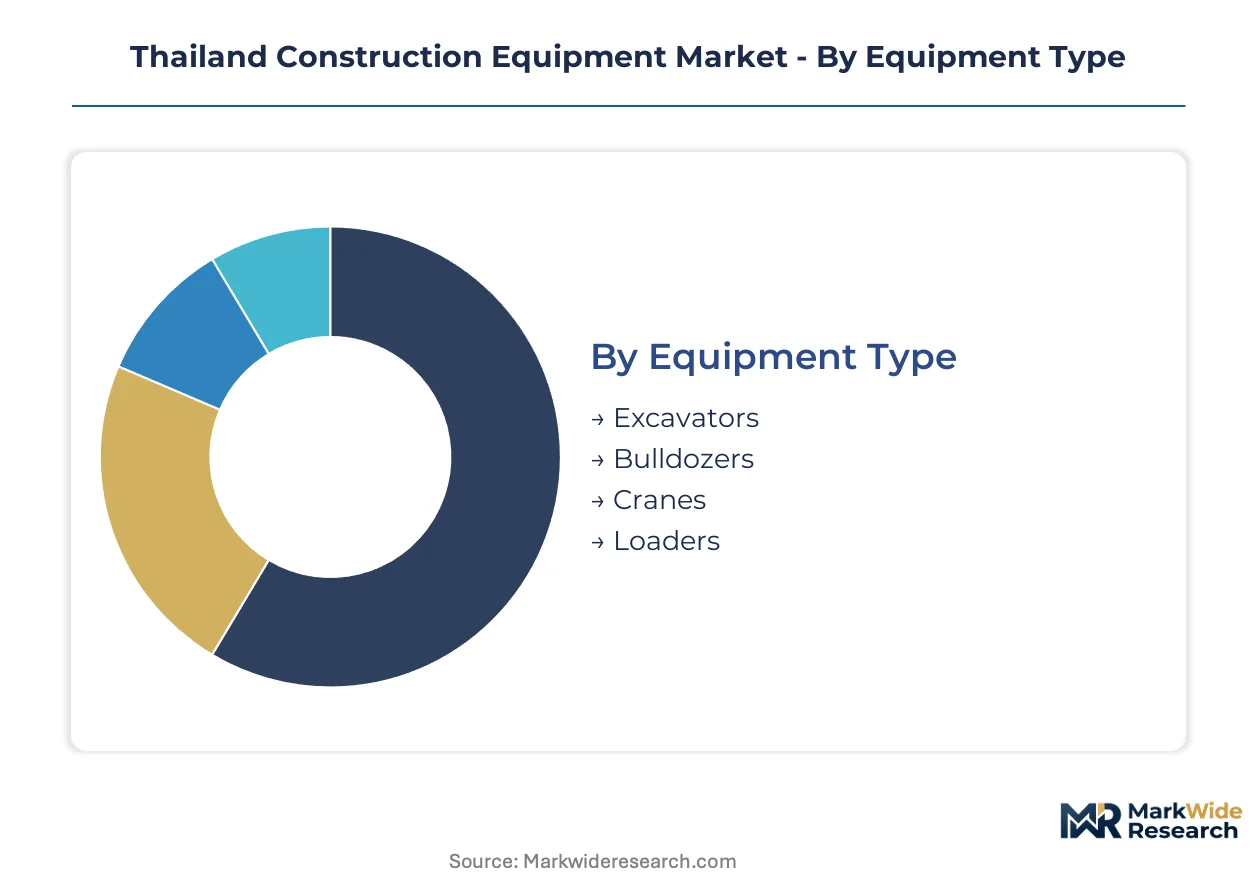
Equipment specification decisions in Thailand's construction sector revolve around emissions compliance thresholds and telematics certification requirements. Segmentation reveals how regulatory layering from the Department of Industrial Works and Board of Investment incentives reshape procurement patterns across contractor tiers.
Equipment Type:
Factory inspection protocols from Thailand's Department of Industrial Works impose tiered emissions certification burdens, with hydraulic excavators facing the most stringent retrofit timelines for Tier 4 equivalent standards.
- Excavators:Hydraulic systems rated 20-400 horsepower dominate trenching and foundation workflows across the Eastern Economic Corridor. Demand concentrates with public infrastructure contractors managing multi-year megaprojects in Chonburi and Rayong provinces, where extended equipment utilization justifies connected-fleet specifications.
- Loaders:Wheel loaders serve material handling operations at port terminals and industrial estate developments. Procurement from the Industrial Estate Authority of Thailand concentrates around Rayong's eastern seaboard logistics corridors, with local content thresholds driving assembly qualification strategies.
- Bulldozers:Tracked dozers handle bulk earthmoving for road construction and site preparation.
- Cranes:Mobile and tower cranes support vertical lifting for commercial high-rise development.
Excavators sit at the top of the volume ranking, with loaders climbing the fastest as industrial estate expansion accelerates material handling requirements.
Application:
Project scale and financing structure determine equipment access models, with public infrastructure commanding fleet ownership while private development shifts toward rental subscriptions.
- Infrastructure Development:Government-backed megaprojects spanning highways, rail corridors, and port expansions sustain the largest equipment deployment volumes. Contractors anchor replacement cycles around Board of Investment incentive timelines, optimizing local content qualification for tax holiday eligibility.
- Residential Construction:Smaller-scale housing developments favor short-cycle equipment rental over capital commitment. Subscription-based fleet management expands addressable market for mid-size excavators and compact loaders serving variable project intensity.
- Commercial Projects:High-rise and mixed-use development drives crane specifications and large-capacity material handling equipment.
- Road Construction:Highway and arterial road programs concentrate demand in bulldozers and motor graders for grading operations.
Infrastructure development commands the largest equipment deployment base, though residential construction is gaining share fastest as rental digitization penetrates smaller contractor tiers.
End User:
Capital deployment capacity separates ownership models, with government-linked contractors maintaining captive fleets while private developers externalize utilization risk.
- Contractors:Public infrastructure specialists manage multi-year project portfolios requiring predictable equipment availability. These firms prioritize telematics-enabled specifications for fuel monitoring and predictive maintenance, converting specification decisions from diesel-only to connected-first.
- Government:State agencies and public works departments procure through centralized tender processes with stringent local content requirements. Board of Investment incentive compliance shapes vendor selection toward OEMs with qualified domestic assembly operations.
- Builders:Private construction firms serving residential and commercial segments.
- Private Developers:Real estate and industrial estate developers with variable equipment intensity.
Contractors represent the dominant procurement volume, with government entities expanding fastest as public infrastructure pipelines deepen.
Technology:
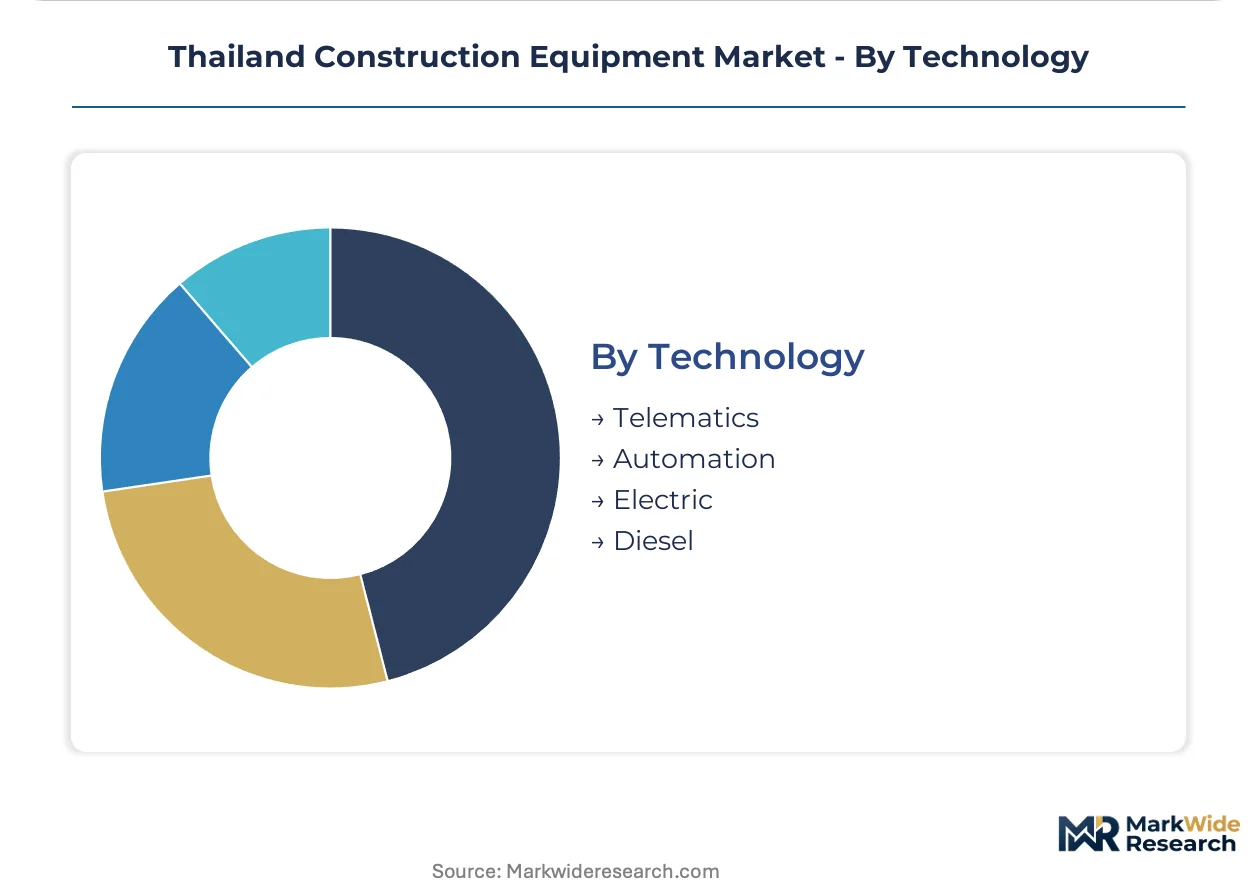
Specification criteria are compressing around data interoperability, with connectivity mandates from large contractors reshaping competitive advantage toward platform accessibility.
- Telematics:Integrated platforms unify equipment monitoring, maintenance scheduling, and fuel optimization into single-dashboard operations. Large contractors across the Eastern Economic Corridor mandate connected specifications, prioritizing API accessibility and total cost of ownership visibility over mechanical performance metrics alone.
- Electric:Battery-electric excavators and loaders emerge at pilot scale for indoor and urban construction applications. Emissions monitoring requirements from the Department of Industrial Works create openings for OEMs bundling zero-emission equipment with carbon tracking capabilities.
- Automation:Semi-autonomous grading and excavation systems for precision earthmoving.
- Diesel:Conventional internal combustion equipment facing retrofit pressure from evolving emissions protocols.
Telematics holds the dominant installed base position, with electric equipment posting the steepest expansion trajectory as carbon-linked financing structures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production arbitrage across Southeast Asia is accelerating as manufacturers chase Board of Investment tax holidays and emissions compliance cost differentials. Equipment assembly migrates toward jurisdictions with consolidated incentive regimes and streamlined factory inspection protocols.
Chonburi Province
Laem Chabang Deep Sea Port expansion and high-speed rail terminus construction sustain excavator deployment at scale. Thailand's Board of Investment grants eight-year tax holidays for machinery manufacturing operations meeting local content thresholds. Amata City and WHA industrial estates concentrate assembly plants serving Eastern Economic Corridor logistics corridors.
Rayong Province
Petrochemical complex upgrades and Map Ta Phut port modernization drive material handling equipment procurement cycles. The Industrial Estate Authority of Thailand coordinates zoning permits that cluster heavy equipment depots near eastern seaboard shipping lanes. SANY operates its captive assembly complex here, qualifying for import duty exemptions on component kits.
Chachoengsao Province
High-speed rail corridor construction and logistics park development anchor bulldozer and motor grader demand. Department of Industrial Works emissions certification timelines compress equipment replacement schedules for public contractors. Gateway City industrial zone attracts depot operators seeking assembly-to-port distance advantages.
Bangkok Metropolitan Region
Mass transit extensions and commercial high-rise development sustain crane specifications and vertical lifting equipment demand. Centralized government tender processes enforce stringent local content requirements that reshape vendor selection. Rangsit and Bang Na districts concentrate rental fleet operators serving variable project intensity.
Thailand Construction Equipment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-line OEMs anchoring public infrastructure procurement while rental specialists capture residential construction variability. Market structure tilts toward consolidated leadership in excavators and fragmented competition in compact equipment. Three archetypes dominate: telematics-integrated fleet managers, scale-driven assembly operators, and regional parts distributors. Competitive moves concentrate on capacity expansion in eastern seaboard industrial zones and strategic partnerships bundling equipment with financing structures.
Among telematics-integrated fleet managers, Komatsu occupies a position exemplifying connected-first specification strategies through its long-term service contract anchoring. SANY represents the scale-driven assembly archetype from its Rayong manufacturing base. Volvo Construction Equipment sits within the uptime-guarantee tier, differentiating through regional distribution density. These three patterns illustrate how competitive positioning decouples from pure manufacturing scale toward service-layer integration.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Construction Equipment |
| Hitachi Construction Machinery |
| SANY |
| Kobelco |
| XCMG |
| JCB |
| Liebherr |
| Others |
Pricing and Supply Chain Analysis
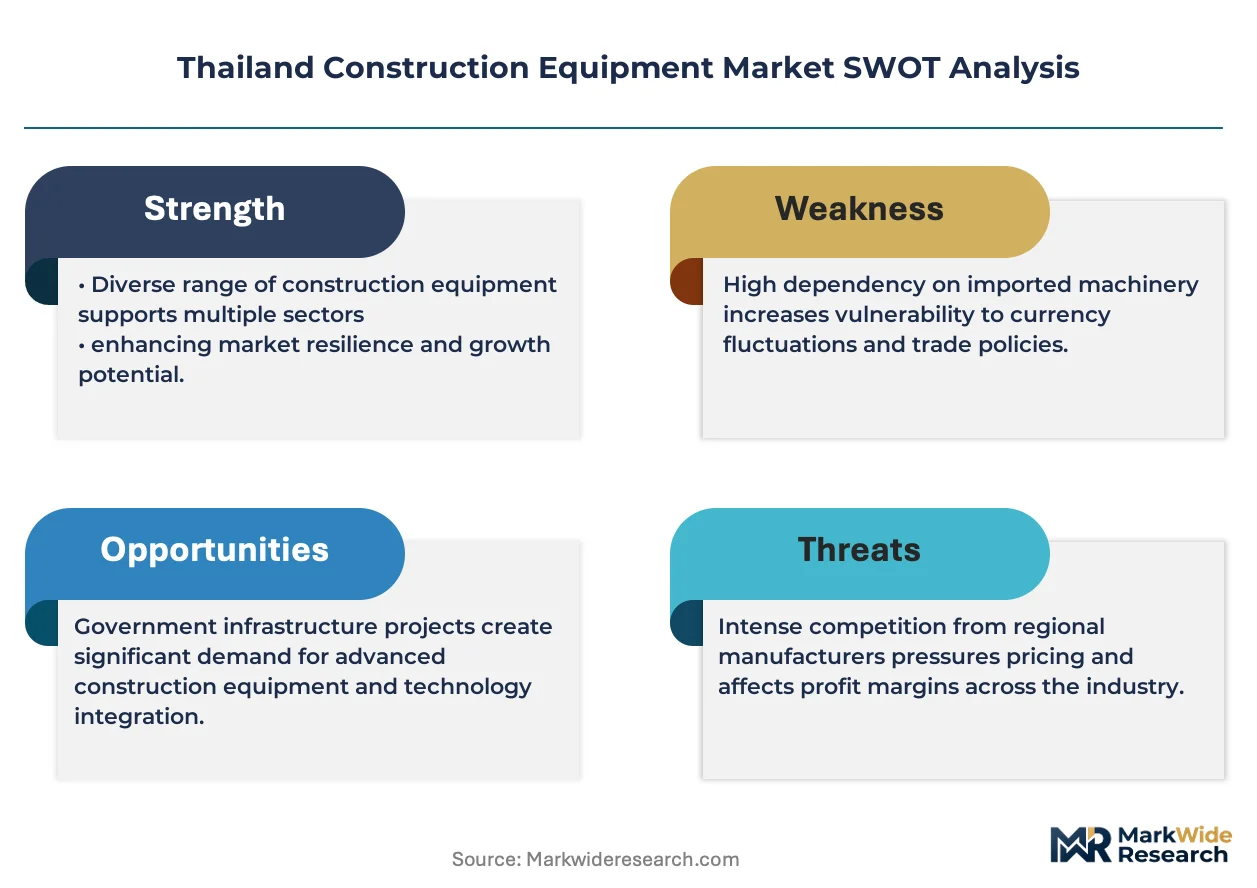
Steel price indices on the Shanghai Futures Exchange cascade through hydraulic cylinder and chassis fabrication costs, compressing margins for Thai equipment assemblers and forcing three-tier pricing stratification across premium telematics-integrated, standard connected, and economy diesel-only specifications.
Pricing Analysis
Distributor markups of 12-18 percent on imported component kits anchor landed cost structures for foreign OEMs operating Thai assembly plants. Price differentiation hinges on telematics certification grade and local content qualification for Board of Investment tax holiday eligibility. Cost compression in the economy tier intensifies as used Japanese and Korean excavators arbitrage depreciation curves. Public infrastructure contractors show lowest price sensitivity due to multi-year project financing, while residential builders prioritize upfront capital expenditure minimization.
Supply Chain Analysis
Workforce availability constraints in Chonburi and Rayong industrial estates complicate skilled technician recruitment for telematics-integrated equipment servicing. Geographic supply concentration centers on China for hydraulic systems, Japan for precision engine components, and South Korea for electronic control modules. Raw material dependencies span high-strength steel plate, specialized hydraulic seals, and semiconductor chips for fleet management controllers. Single-source vulnerability in hydraulic pump supply chains from Japanese tier-one suppliers creates procurement risk. Distribution runs through regional parts depots clustered near Laem Chabang and Map Ta Phut ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's construction equipment market functions as a stable compounder anchored by decade-long Eastern Economic Corridor infrastructure pipelines that sustain predictable replacement demand regardless of cyclical construction volatility.
For Market Incumbents: Extend telematics platform penetration through long-term fleet management contracts that lock in contractor relationships beyond equipment transfer. Deepen backward integration into hydraulic system assembly within Rayong industrial zones to satisfy Board of Investment local content thresholds. Defend against used equipment import competition by bundling residual value guarantees with subscription-based uptime commitments.
For New Entrants and Emerging Players: Digital rental marketplaces offer the most penetrable route for bypassing incumbent distribution control and capturing residential construction variability. Target short-cycle equipment access demand among mid-tier contractors lacking capital deployment capacity for fleet ownership. Deploy asset-light fleet aggregation models that pool underutilized contractor equipment into shared utilization networks.
For Investors and Strategic Acquirers: Asymmetric upside sits with telematics-enabled rental fleet operators positioned to capture subscription revenue expansion as contractor ownership models erode. Five-to-ten year viability hinges on carbon-linked financing structure maturation and emissions compliance cost pass-through capability. Monitor Board of Investment incentive renewal timelines as the critical inflection signal for domestic assembly profitability thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | Komatsu's KOMTRAX system anchors long-term service contracts with Eastern Economic Corridor contractors. |
| Rayong Manufacturing Expansion | SANY's captive assembly complex qualifies for import duty exemptions on component kits from China. |
| Carbon Monitoring Bundling | Volvo Construction Equipment differentiates through connected uptime guarantees tied to emissions tracking. |
| Rental Fleet Digitization | Subscription-based fleet management expands addressable market among price-sensitive residential builders. |
| Local Content Qualification | Foreign OEMs reconfigure hydraulic system sourcing to satisfy Board of Investment tax holiday thresholds. |
Research Methodology
Multiple input streams — equipment procurement directors at public infrastructure contractors, aftermarket service managers at Thai distributor networks, and Board of Investment incentive compliance officers — were reconciled against customs import data, Industrial Estate Authority of Thailand zoning permits, and Department of Industrial Works emissions certification records. Secondary validation drew from SEC filings of listed construction equipment manufacturers, Eastern Economic Corridor development authority project announcements, and regional steel price benchmarks. Bottom-up equipment deployment estimates from contractor fleet inventories were triangulated with top-down market sizing derived from import duty exemption records.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning equipment type, application category, end-user capital deployment capacity, and technology specification tier. CAGRs were derived from equipment replacement cycle analysis weighted against public infrastructure pipeline visibility. Forecast inputs incorporated telematics penetration trajectories, local content qualification timelines, and carbon-linked financing structure evolution.
The model assumes a particular technology adoption path; alternative pathways for battery-electric equipment would alter the outlook if charging infrastructure deployment accelerates beyond baseline assumptions. Forecasts reflect assumptions around Board of Investment incentive continuity and emissions protocol enforcement intensity. Material deviation in Eastern Economic Corridor project approval timelines or steel input cost volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Hoist and Winches Market
Construction Equipment
Rail Welding Equipment Market
Construction Equipment
Truck Mounted Concrete Mixer Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Static Crane Market
Construction Equipment
Global Mobile Concrete Mixer Market
Construction Equipment
Cold Forming Equipment Market
Construction Equipment
Grader Blades Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Global CNC Tool and Cutter Grinding Machine Market
Construction Equipment
Autonomous Heavy Equipment Market
Construction Equipment
Jib Crane Market
Construction Equipment
Asia-Pacific Mobile Light Tower Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
ASEAN Construction Equipment Rental Market
Construction Equipment
Global Welding Market