
 Germany Prefabricated Buildings Market | 2026-2036
Germany Prefabricated Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Prefabricated Buildings Market Foresight
Market Context with Strategic Players
Modularization of building systems into standardized volumetric units is broadening buyer choice across residential and commercial segments in Germany. SchwörerHaus KG leverages its timber engineering heritage to dominate premium single-family modular homes in southern Germany. Goldbeck GmbH anchors large-scale commercial and industrial prefabrication through controlled steel-frame production. DFH Deutsche Fertigbau Holding AG competes across multiple price tiers through its portfolio of regional brands.
Technical Definition and Structural Segments
Prefabricated buildings in Germany are structures manufactured off-site in factory conditions using precision-cut timber, steel, or concrete assemblies, then transported and erected on foundations, with thermal performance typically engineered to meet or exceed EnEV/GEG U-value requirements of 0.24 W/(m²K) for exterior walls. The primary industrial purpose is to compress construction schedules, reduce on-site labor dependency, and standardize quality in a market facing acute skilled-trade shortages. Timber and insulated panels lead material demand due to Germany's forestry supply chain and energy-efficiency mandates, while modular homes capture the fastest growth trajectory among building types as municipalities relax zoning for denser urban housing. Commercial workspaces sustain mature volume through Goldbeck's dominance in logistics and office shells, where margin pools concentrate in turnkey fit-out bundles rather than shell-only delivery.
Regulatory Frame and Forward-Looking Close
Germany's Building Energy Act (GEG), the federal KfW subsidy framework for efficient construction, and DIN 18015 electrical installation standards collectively shape product specifications, financing access, and approval timelines for prefabricated systems. KBA and state-level building authorities enforce type approval for transportable modules on public roads, creating compliance barriers that favor established manufacturers with dedicated logistics engineering. Stakeholders must monitor whether the EU Green Deal's embodied-carbon reporting requirements will force material disclosure that advantages timber-intensive suppliers over concrete-dependent competitors.
Market Dynamics
The Building Energy Act (GEG) is compressing approval timelines for factory-built assemblies while simultaneously elevating thermal performance thresholds that favor off-site manufacturing precision over traditional site-built methods.
Growth Catalysts
- Timber-frame engineering:Bavarian and Baden-Württemberg developers are specifying cross-laminated timber modules to satisfy GEG U-value mandates of 0.24 W/(m²K) for exterior wall assemblies.
- KfW subsidy framework:Federal efficiency financing is steering capital toward panelized construction that meets DIN 18015 electrical standards and EnEV thermal benchmarks.
- Urban infill zoning:Berlin, Hamburg, and Munich municipalities are relaxing density restrictions for modular multi-family housing on constrained central sites.
Market Restraints
- Transport module limits:KBA type-approval requirements for road-legal dimensions restrict volumetric unit sizing and create logistics engineering costs that favor established manufacturers.
- Skilled-trade dependency:On-site foundation and utility connection work still requires scarce German masonry and electrical trades, limiting full schedule compression.
- Concrete supply concentration:Heavy prefabrication remains tied to regional ready-mix concrete networks that face carbon-cost exposure under EU Green Deal embodied-carbon reporting rules.
Strategic Opportunities
- Carbon disclosure advantage:EU Green Deal material reporting requirements will force lifecycle transparency that advantages timber-intensive Bavarian suppliers over concrete-dependent competitors.
- Commercial fit-out bundling:Logistics and office shell buyers are migrating from shell-only procurement to turnkey interior packages, expanding margin pools for integrated providers.
- Panel-to-volumetric upgrade:Residential developers in North Rhine-Westphalia are shifting from flat-panel systems to three-dimensional modular units for mid-rise urban projects.
Industry Challenges
- State-level approval fragmentation:German building authorities in 16 Länder apply divergent interpretation of DIN standards for modular electrical and plumbing systems, stretching certification timelines.
- Foundation-interface complexity:Precision tolerances between factory-built superstructures and site-poured foundations demand specialized surveying skills that remain scarce in eastern German construction labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Prefabricated Buildings Market |
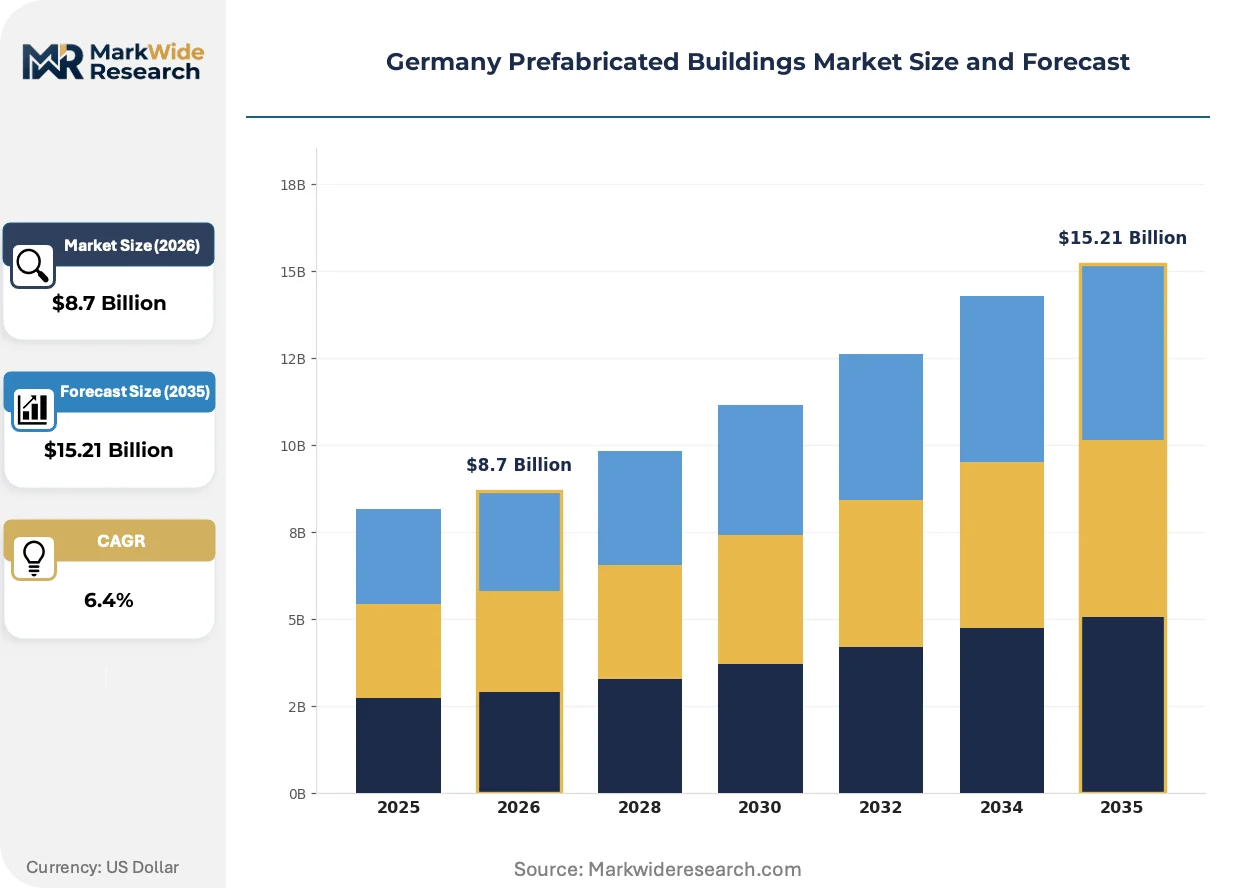
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Building Type: Modular Homes, Portable Offices, Commercial Complexes, Educational Facilities, Healthcare Units Material: Steel, Timber, Concrete, Composite Panels, Insulated Panels Application: Residential Projects, Commercial Workspaces, Institutional Buildings, Healthcare Infrastructure, Recreational Centers Customer Type: Construction Companies, Real Estate Developers, Government Agencies, Educational Institutions, Healthcare Providers |
| Companies Covered | SchwörerHaus KG, Goldbeck GmbH, DFH Deutsche Fertighaus Holding AG, Kleusberg GmbH & Co. KG, ALHO Systembau GmbH, Bien-Zenker GmbH, Haas Fertigbau GmbH, Cadolto Modulbau GmbH, WeberHaus GmbH & Co. KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Prefabricated Buildings Market Shifts & Advancements
Digital fabrication and material science advances are compressing the gap between architectural customization and factory standardization, enabling mass-customized prefabrication at price points competitive with conventional construction.
Cross-laminated timber (CLT) is converging with automated CNC cutting systems to produce structural panels with millimeter precision for complex geometries. Southern German housing cooperatives are specifying CLT-steel hybrid frames for six-story residential blocks. This convergence is collapsing the traditional trade-off between design flexibility and factory throughput speed.
The EU Green Deal's embodied-carbon reporting requirements are mandating Environmental Product Declarations (EPDs) for all structural materials in publicly funded buildings. German manufacturers must now document cradle-to-gate carbon intensity for timber, steel, and concrete assemblies. Timber-dependent suppliers in Bavaria are accelerating EPD certification to capture public-sector procurement preference.
Municipal housing authorities are unbundling design, fabrication, and site-assembly contracts that were historically awarded to single general contractors. Berlin and Hamburg developers are now procuring volumetric modules through framework agreements with multiple factory operators while retaining separate foundation contractors. This procurement fragmentation is most visible in urban infill projects where speed-to-occupancy drives contract structure innovation.
Germany Prefabricated Buildings Market Segmentation
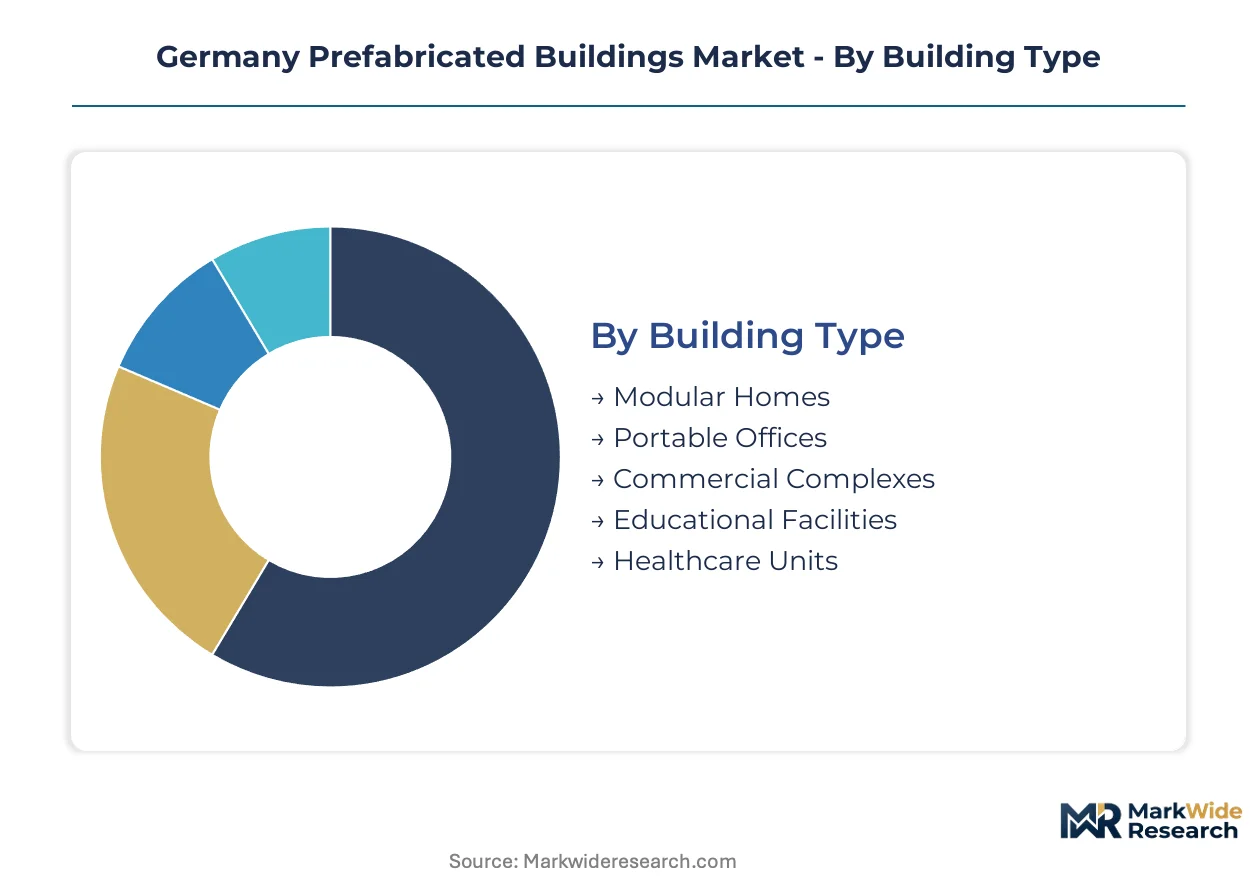
Prefabricated building demand in Germany fragments across structural systems, material specifications, and procurement channels. Each segmentation axis reveals distinct margin pools and regulatory exposure that shape supplier positioning.
Building Type:
Customization intensity varies sharply across this category, from standardized volumetric units to architecturally specified complex assemblies.
- Modular Homes:Factory-built residential units using timber-frame or steel chassis construction, engineered for KfW efficiency subsidies. Bavarian and Baden-Württemberg developers are specifying these for urban infill sites in Munich and Stuttgart where labor scarcity compresses schedules. GEG thermal mandates favor the precision of off-site wall assembly.
- Portable Offices:Relocatable single-story workspace modules, typically steel-framed with standardized MEP interfaces. Logistics operators in Hamburg and Berlin industrial zones deploy these for rapid capacity expansion without foundation permits. Demand concentrates in temporary-to-permanent conversion contracts.
- Commercial Complexes:Multi-bay industrial and retail shells delivered through panelized or hybrid systems.
- Educational Facilities:Classroom and administrative buildings with enhanced acoustic and ventilation specifications.
- Healthcare Units:Clinic modules with infection-control finishes and medical gas infrastructure.
Most installed capacity flows through Modular Homes. Expansion is steepest in Commercial Complexes.
Material:
Cost tier stratification separates premium engineered timber from commodity concrete systems, with carbon exposure now reshaping procurement preferences.
- Timber:Cross-laminated timber and glulam assemblies, predominantly spruce and pine from domestic forestry supply chains. Southern German manufacturers leverage this for GEG-compliant U-values and EU Green Deal EPD advantages. CLT-steel hybrid frames are penetrating six-story residential blocks in Bavarian housing cooperatives.
- Steel:Cold-formed and hot-rolled structural sections for commercial shells and modular chassis. Goldbeck GmbH anchors volume through controlled production of galvanized framing for logistics facilities. DIN 18800 structural design standards govern weld quality and corrosion protection.
- Concrete:Precast wall and floor elements tied to regional ready-mix networks.
- Composite Panels:Metal-faced insulated sandwich systems for rapid-enclosure applications.
- Insulated Panels:High-performance envelope assemblies with polyurethane or mineral wool cores.
Timber commands premium pricing in residential applications. Steel dominates commercial volume.
Application:
End-use maturity ranges from established residential workflows to emerging healthcare infrastructure retrofit demand.
- Residential Projects:Single-family and multi-family housing delivered through modular or panelized methods. North Rhine-Westphalia developers are shifting from flat panels to volumetric units for mid-rise urban density. KfW subsidy access requires EnEV/GEG thermal compliance that factory assembly guarantees.
- Commercial Workspaces:Office shells, logistics centers, and light manufacturing facilities. Turnkey fit-out bundling is displacing shell-only procurement as buyers seek integrated delivery. Margin pools concentrate in interior completion packages rather than structural shells.
- Institutional Buildings:Government and administrative facilities with extended durability specifications.
- Healthcare Infrastructure:Hospital extensions and diagnostic centers with specialized mechanical systems.
- Recreational Centers:Sports and community facilities with large-span structural requirements.
Residential Projects absorb the highest unit volume. Healthcare Infrastructure is gaining share fastest.
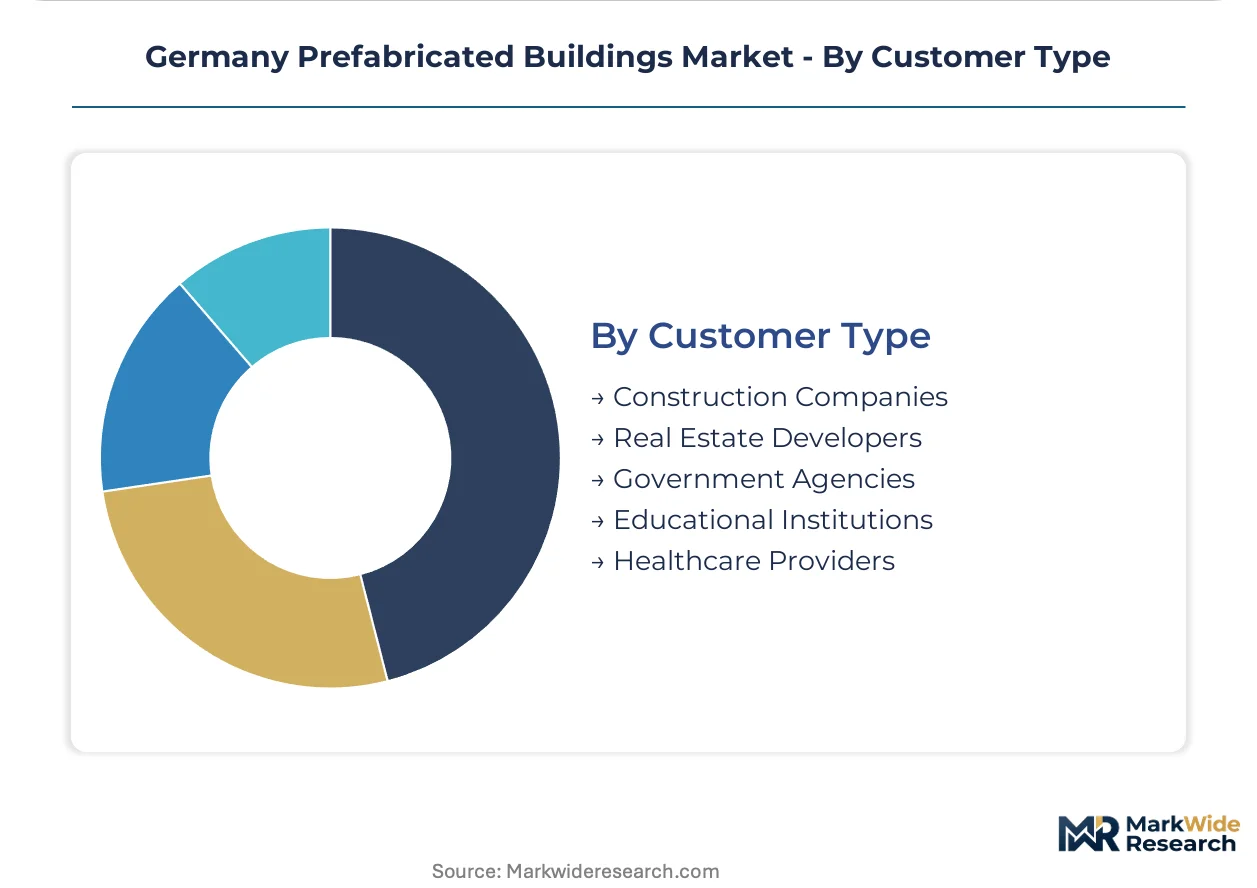
Customer Type:
Procurement sophistication varies from standardized framework agreements to complex multi-contractor project structures.
- Construction Companies:General contractors and specialist prefabrication installers purchasing structural systems for project integration. These buyers prioritize schedule certainty and labor substitution in eastern German markets where masonry and electrical trades remain scarce.
- Real Estate Developers:Asset owners and project sponsors specifying building systems for rental and sale portfolios. Berlin and Hamburg developers are unbundling design, fabrication, and assembly contracts that historically went to single general contractors.
- Government Agencies:Federal, state, and municipal procurement bodies with public-sector EPD requirements.
- Educational Institutions:University and school district capital programs with lifecycle cost evaluation criteria.
- Healthcare Providers:Hospital networks and clinic operators with stringent infection-control specifications.
Construction Companies represent the largest procurement volume. Real Estate Developers are driving contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's prefabricated building industry traces its industrial lineage to post-war reconstruction programs that established factory-based timber housing in Bavaria and Baden-Württemberg. This heritage continues to shape regional specialization patterns across German states.
Bavaria
Timber-frame modular housing dominates residential development in Munich and surrounding districts, driven by strict GEG thermal performance mandates. State-level building authorities enforce DIN standards for factory-controlled panel assembly. Housing cooperatives in the Munich metropolitan area specify cross-laminated timber modules for six-story urban infill projects.
Baden-Württemberg
Cross-laminated timber engineering concentrates around Stuttgart and the Black Forest region, leveraging domestic spruce supply chains. The state's forestry heritage supports precision manufacturing for GEG-compliant U-value specifications. Stuttgart developers deploy CLT-steel hybrid frames for mid-rise residential density in constrained central sites.
North Rhine-Westphalia
Developers in Cologne and Düsseldorf are shifting from flat-panel systems to three-dimensional volumetric units for urban housing projects. KfW subsidy access drives capital toward factory-built assemblies meeting EnEV thermal benchmarks. The Ruhr industrial corridor hosts panel-to-volumetric upgrade activity for former industrial site redevelopment.
Berlin-Brandenburg
Municipal housing authorities unbundle design, fabrication, and assembly contracts for speed-to-occupancy in dense urban infill zones. Berlin's relaxed density restrictions favor modular multi-family construction on constrained central sites. Brandenburg's logistics corridors support module transport to capital region construction sites.
Hamburg
Port logistics operators deploy portable office modules for rapid capacity expansion in industrial zones without foundation permits. KBA type-approval requirements for road-legal dimensions shape module sizing decisions. Hamburg developers procure volumetric modules through framework agreements with multiple factory operators.
Germany Prefabricated Buildings Market Competitive Landscape
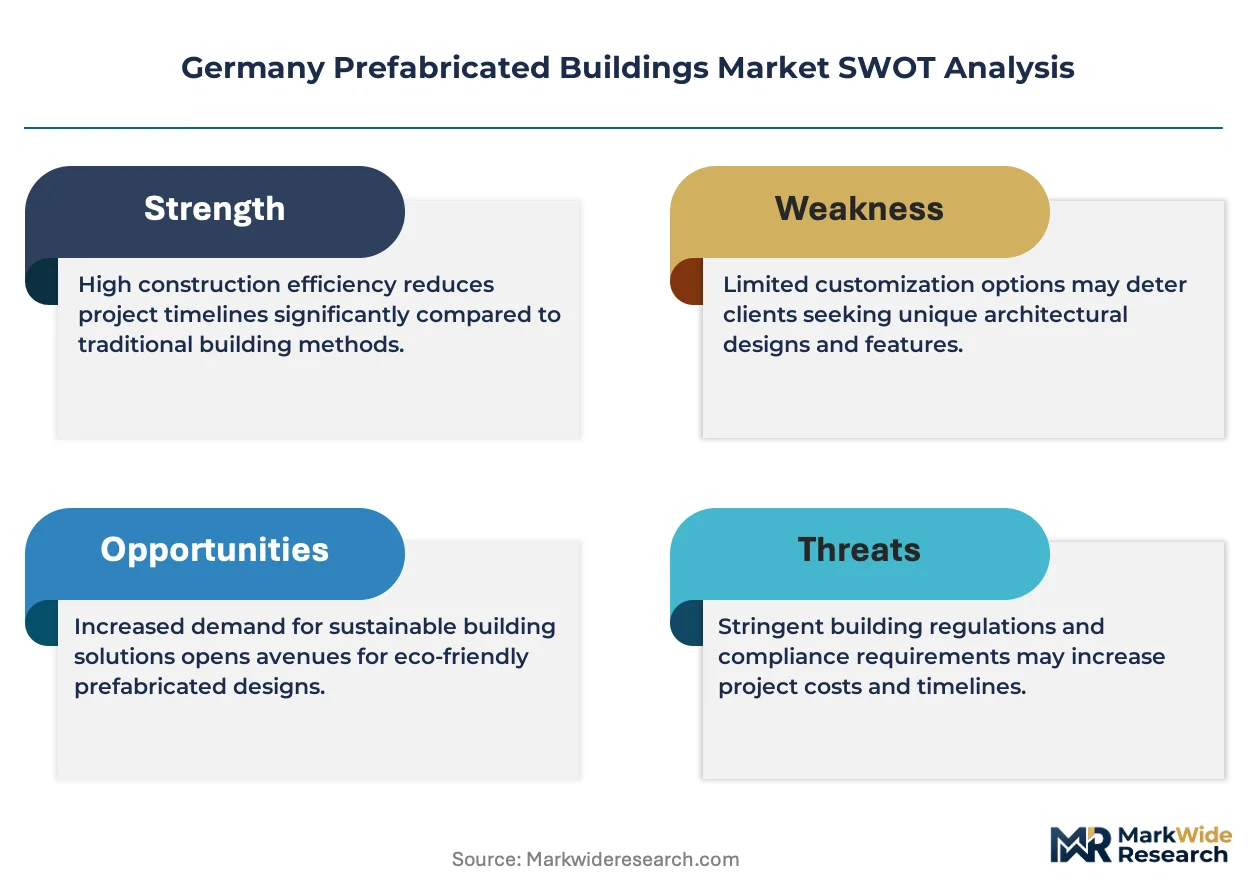
The competitive structure tilts toward regional specialists with deep timber engineering heritage and national-scale commercial fabricators with controlled steel production. Bavarian and Baden-Württemberg manufacturers dominate premium residential modular systems, while northern German players anchor large-scale commercial and industrial prefabrication. Two strategic archetypes define positioning: timber-intensive regional specialists leveraging GEG thermal compliance, and steel-frame national operators capturing logistics and office shell volume. Competitive moves concentrate on turnkey fit-out bundling and panel-to-volumetric portfolio upgrades.
Among Germany-based fabricators, SchwörerHaus KG and Goldbeck GmbH occupy distinct archetype positions, while DFH Deutsche Fertighaus Holding AG represents multi-brand portfolio diversification. SchwörerHaus KG exemplifies the timber-engineering specialist model rooted in southern German manufacturing heritage. Goldbeck GmbH anchors the steel-frame commercial segment through controlled production systems. DFH Deutsche Fertigbau Holding AG sits within the holding-company tier, competing across price tiers through regional brand aggregation.
| Leading Market Players |
|---|
| SchwörerHaus KG |
| Goldbeck GmbH |
| DFH Deutsche Fertighaus Holding AG |
| Kleusberg GmbH & Co. KG |
| ALHO Systembau GmbH |
| Bien-Zenker GmbH |
| Haas Fertigbau GmbH |
| Cadolto Modulbau GmbH |
| WeberHaus GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Timber-frame engineering clusters in Bavaria and Baden-Württemberg compress labor-cost differentials into pricing-tier spreads across premium CLT modules, standard panelized systems, and economy steel-frame units. KfW subsidy eligibility and GEG thermal compliance separate these tiers, with factory-controlled precision commanding measurable premiums over site-built alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement decisions, with certification grade under KfW efficiency standards and geographic delivery cost to eastern German markets driving differentiation. Cost compression in economy steel-frame tiers is intensifying because concrete supply networks face carbon-cost exposure under EU Green Deal rules. Municipal housing authorities in Berlin show highest price sensitivity, while healthcare providers specify infection-control finishes with minimal cost elasticity.
Supply Chain Analysis
Certification gating through KBA type-approval for road-legal module dimensions restricts supplier pools to established manufacturers with dedicated logistics engineering. Domestic spruce and pine forestry in southern Germany, cross-laminated timber processing in Bavaria, and galvanized steel production in northern industrial corridors anchor material flows. Single-source vulnerability concentrates in regional ready-mix concrete networks for heavy prefabrication. Distribution runs through framework agreements with multiple factory operators retained by real estate developers for urban infill projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Germany Prefabricated Buildings Market reads as a late-cycle quality story, with municipal procurement shifting toward GEG-compliant thermal specifications that reward factory precision over conventional construction.
For Market Incumbents: Anchor timber-engineering heritage through captive CLT production capacity in Bavarian forestry corridors, defending against steel-frame modular entrants from northern commercial specialists. Backward integration into cross-laminated timber processing secures margin pools as EU Green Deal EPD requirements harden material disclosure standards. Certification investment in DIN 18015 electrical compliance creates switching costs for developers dependent on KfW subsidy access. For New Entrants and Emerging Players: The gap between premium CLT modules and economy steel-frame units opens white-space in mid-tier panelized systems for North Rhine-Westphalia urban housing cooperatives. Eastern German markets show penetrable demand where masonry trade scarcity compresses schedules for foundation-interface specialists. A go-to-market angle through turnkey fit-out bundling captures margin expansion as logistics buyers migrate from shell-only procurement. For Investors and Strategic Acquirers: Timber-intensive regional specialists with GEG-compliant product portfolios are the most active acquirer targets for national commercial fabricators seeking residential market entry. Long-term viability hinges on embodied-carbon disclosure capabilities that advantage Bavarian suppliers over concrete-dependent competitors. The signal to watch is KfW subsidy recalibration that would accelerate panel-to-volumetric upgrade cycles.| Strategic Initiative | Industry Significance |
|---|---|
| CLT Production Capacity Expansion | Captures GEG thermal compliance premiums in Bavarian housing cooperatives. |
| KfW Certification Investment | Locks in subsidy-dependent developer procurement through DIN 18015 compliance. |
| Turnkey Fit-Out Bundling | Migrates logistics buyers from shell-only contracts to integrated interior packages. |
| Panel-to-Volumetric Upgrade | Addresses mid-rise urban density demand in North Rhine-Westphalia infill zones. |
| EPD Certification Acceleration | Secures public-sector procurement preference under EU Green Deal reporting rules. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with prefabrication plant managers, real estate development executives, municipal housing procurement officers, and KfW program administrators with secondary validation. Regulatory filings from KBA and state-level building authorities, DIN standards documentation, EU Green Deal implementation guidance, and forestry supply chain databases anchored the data foundation. Bottom-up module shipment tracking and top-down construction spend analysis enabled cross-verification.
Segment-weighting across building type, material specification, application, and customer type dimensions shaped volume and value outputs across the projection horizon. CAGRs derived from historical trajectory analysis and policy-impact scenario modeling incorporated GEG amendment implementation timelines and KfW subsidy framework adjustments as structural inputs.
Caveats apply where KfW subsidy recalibration, EU Green Deal embodied-carbon enforcement intensity, or state-level DIN standard interpretation divergence could materially shift the outlook. A model refresh is warranted upon material change in federal efficiency financing parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Europe Modular Construction Market
Building Construction
Thailand Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Egypt Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Qatar Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
GCC Cement Market
Building Construction
Vietnam Construction Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
North America Prefabricated Buildings Market
Building Construction
China Building Construction Market
Building Construction
Tunnels Design and Construction Market
Building Construction
Kuwait Construction Market
Building Construction
UK Construction Market
Building Construction
Scandinavia Construction Market