
 Scandinavia Construction Market | 2026-2036
Scandinavia Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Scandinavia Construction Market Analytics
Multi-source procurement for structural materials is shifting toward consolidated supplier frameworks across Scandinavian project portfolios. Skanska AB leverages its integrated design-build capability to control project timelines from concept to handover. Veidekke ASA anchors its position through strong regional contractor networks in Norway and Denmark. Peab AB specializes in residential volume production, sustaining margin discipline through repeatable building system platforms.
Scandinavia construction encompasses the planning, engineering, and assembly of buildings and civil infrastructure across Denmark, Norway, and Sweden, where timber-frame systems and cross-laminated wood panels account for a substantial share of structural assemblies in low-rise and mid-rise applications. The sector serves housing provision, commercial facility expansion, transport connectivity, and industrial facility modernization across Nordic urban and rural territories. Residential application leads absolute value contribution, supported by persistent housing deficits in Stockholm and Oslo metropolitan zones. Infrastructure exhibits the fastest trajectory, driven by rail electrification, tunneling, and coastal protection investments. Sustainable Materials technology commands premium positioning as Boverket, the Danish Building Regulations, and Norwegian TEK17 standards tighten lifecycle carbon thresholds.
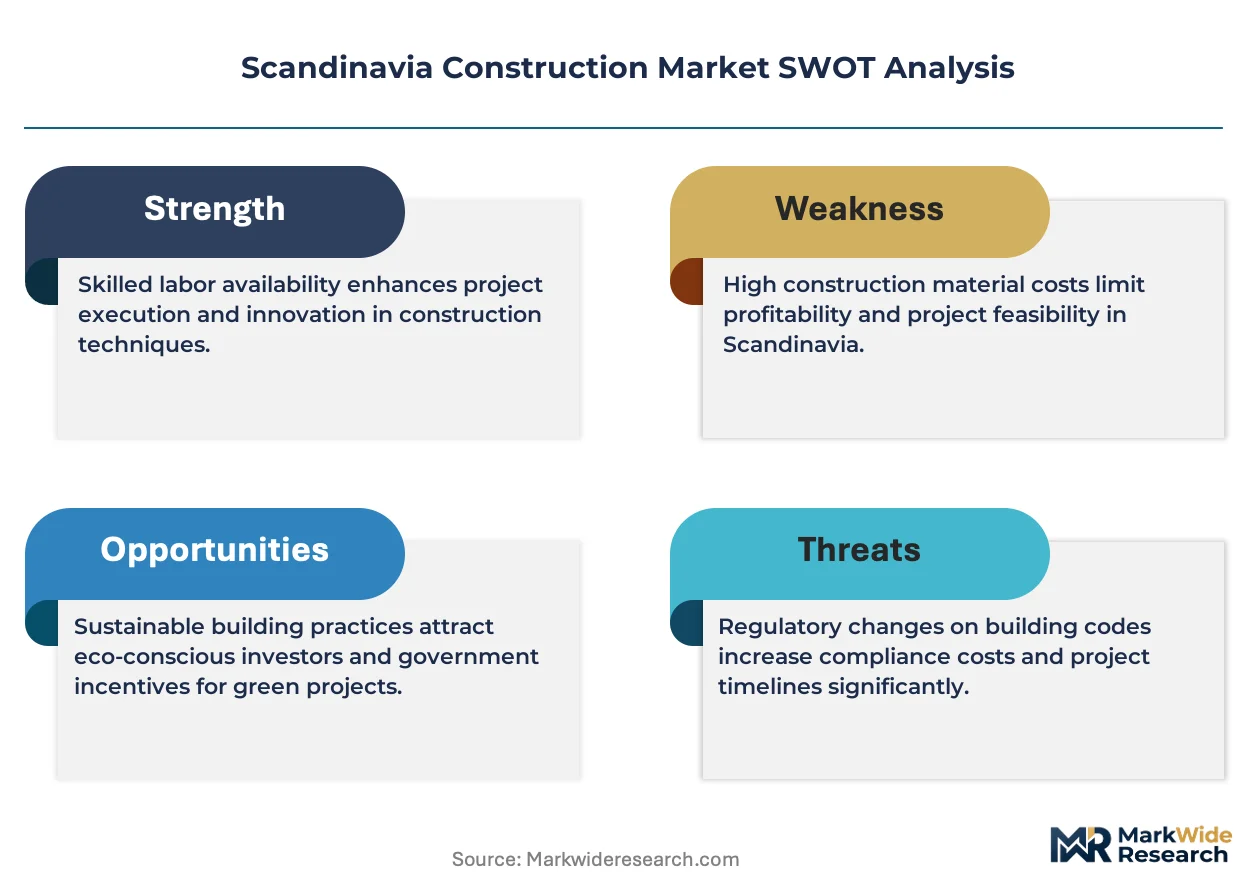
Sweden's Boverket enforces progressively stricter energy performance certificates, while Norway's TEK17 technical standards mandate near-zero emission thresholds for new public buildings. Denmark's Building Regulations align with EU Green Deal carbon-border mechanisms, reshaping material specification toward certified low-carbon cement and recycled steel. Finland's Ministry of the Environment coordinates Nordic harmonization of climate declarations for construction products. Stakeholders must monitor regulatory divergence between national building codes and emerging EU-wide embodied-carbon labeling requirements.
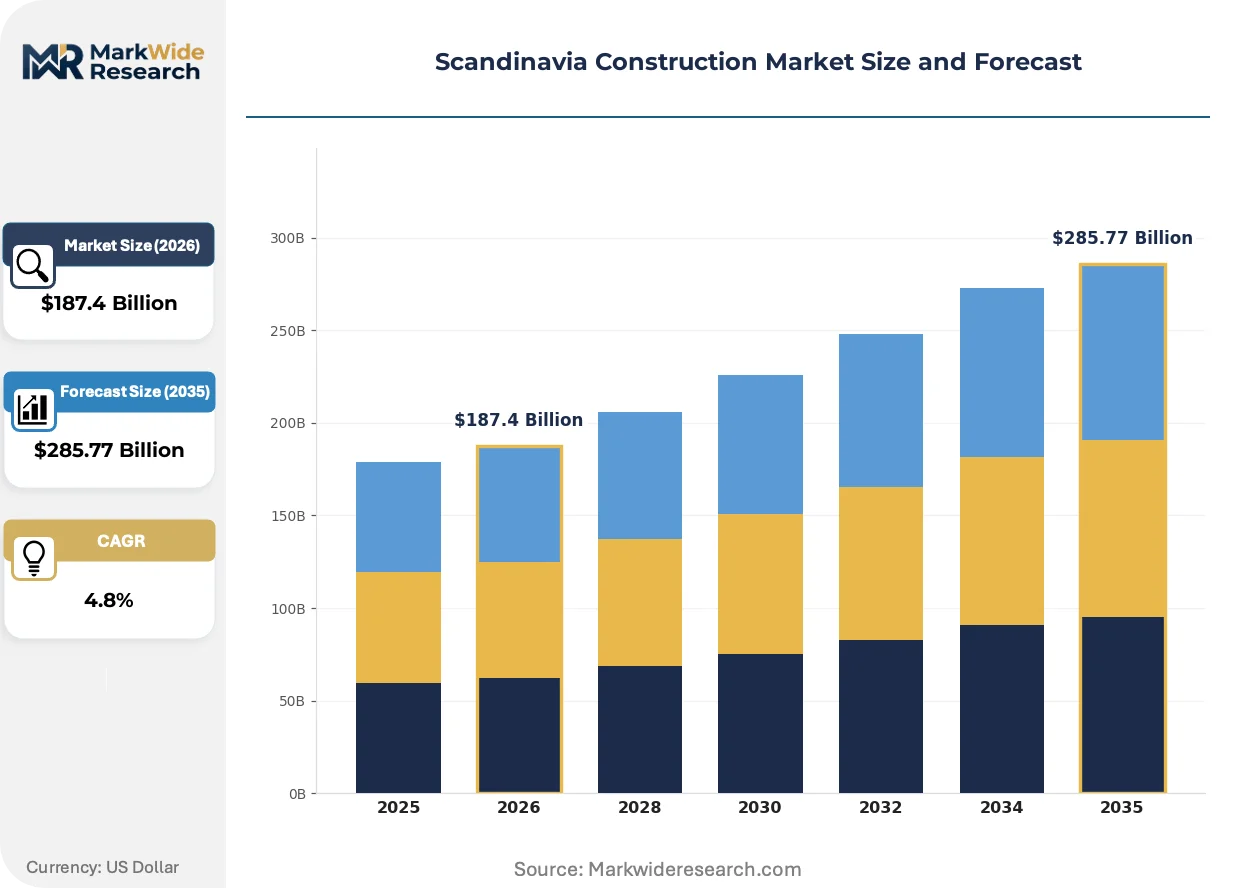
Market Dynamics
Prefabricated timber systems are compressing construction timelines across Scandinavian residential portfolios while Boverket's embodied-carbon thresholds force material specification changes at the project level.
Growth Catalysts
- EU Green Deal carbon-border mechanisms:Denmark's Building Regulations now require certified low-carbon cement and recycled steel in public projects, redirecting specification decisions toward verified supply chains.
- Rail electrification corridors:Norway's urban corridor from Oslo to Bergen is absorbing tunneling and coastal protection investments that converge with energy-efficient housing demand.
- Cross-laminated timber platforms:Sweden's Boverket building codes favor structural assemblies using engineered wood products in mid-rise residential applications.
Market Restraints
- Certified low-carbon cement scarcity:Domestic production capacity for compliant binders lags behind specification requirements in Danish public tenders.
- Nordic steel supply concentration:Recycled structural steel sourcing depends on a limited number of blast furnace operators with EU ETS compliance documentation.
- TEK17 near-zero emission thresholds:Norwegian technical standards for new public buildings impose cost premiums that compress contractor margins on fixed-price contracts.
Strategic Opportunities
- Finnish climate declaration harmonization:Finland's Ministry of the Environment is coordinating Nordic alignment of construction product carbon labeling, creating first-mover advantage for certified suppliers.
- Energy performance certificate arbitrage:Stockholm and Oslo metropolitan housing deficits reward developers delivering above-code efficiency ratings.
- Integrated design-build consolidation:Single-source accountability from concept to handover is displacing fragmented procurement in Danish commercial portfolios.
Industry Challenges
- Embodied-carbon auditing competency:Lifecycle assessment expertise remains concentrated among specialized consultants, creating bottlenecks in project documentation.
- Prefabrication-to-site integration:Timber module tolerances clash with legacy concrete foundation practices, requiring retraining of site supervision teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scandinavia Construction Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Concrete, Steel, Bricks Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Developers, Government, Homeowners Technology: Prefabrication, 3D Printing, Sustainable Materials, Smart Solutions |
| Companies Covered | Peab AB, Ramboll Group A/S, Skanska AB, AF Gruppen ASA, MT Højgaard Holding A/S, Veidekke ASA, JM AB, YIT Oyj, NCC AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scandinavia Construction Market Evolving Landscape
Digital fabrication and regulatory carbon accounting are converging to reshape how Scandinavian projects specify, procure, and assemble structural systems across residential and infrastructure segments.
Cross-laminated timber (CLT) and glulam systems are consolidating market share in mid-rise Scandinavian housing as engineered wood products demonstrate fire-rated performance equivalent to concrete and steel. Danish and Swedish developers specify these materials for projects between four and twelve stories, compressing foundation loads and enabling faster envelope closure. The technology is consolidating supplier relationships around integrated mill-to-site logistics platforms that control moisture content and dimensional tolerance through final installation.
Sweden's Boverket progressively tightens energy performance certificate requirements for new construction and major renovations, forcing retrofit planning into earlier project phases. The regulation compresses design timelines as architects must model operational carbon alongside embodied emissions before planning approval. Norwegian TEK17 and Danish Building Regulations are following similar trajectories, creating a unified Nordic compliance burden that favors contractors with in-house energy modeling capability.
Consolidated supplier frameworks are displacing multi-source structural material procurement across Scandinavian project portfolios. Developers in Norway and Denmark now award multi-year timber and steel packages to single qualified vendors, trading price competition for schedule certainty and carbon traceability. This concentration is most visible in Stockholm's residential volume production, where repeatable building systems depend on captive material supply chains.
Scandinavia Construction Market Segmentation
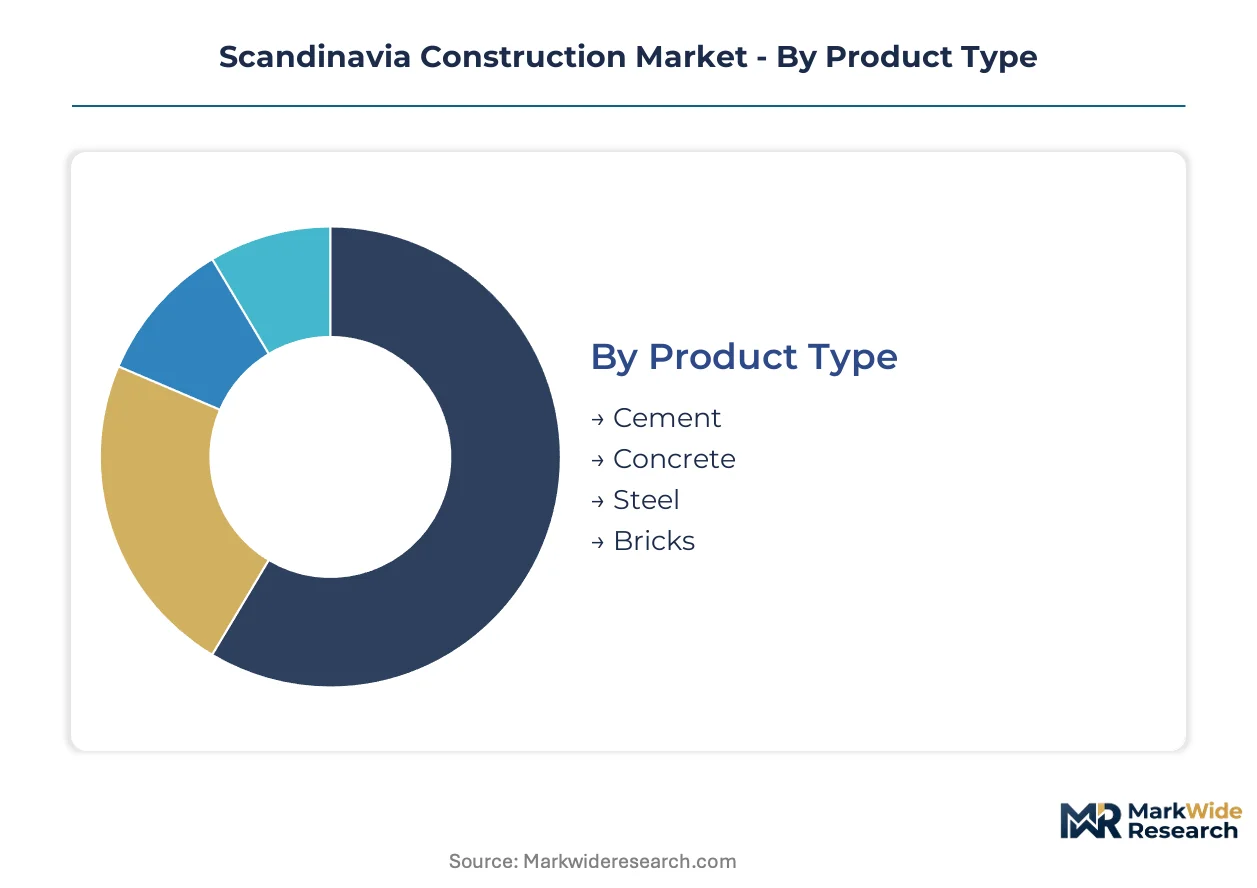
Scandinavian construction procurement increasingly demands segment-specific compliance documentation. Material suppliers and contractors must align product portfolios with divergent national building codes across Denmark, Norway, and Sweden.
Product Type:
Supply concentration for certified structural materials is tightening procurement options across Nordic project portfolios.
- Steel:Recycled structural steel with EU ETS compliance documentation dominates mid-rise commercial frames in Oslo and Stockholm. Norwegian TEK17 near-zero emission thresholds and Danish public tender requirements restrict sourcing to blast furnace operators with verified carbon declarations.
- Cement:Low-carbon binders incorporating calcined clay and supplementary cementitious materials serve foundation and infrastructure applications. Domestic production capacity lags behind specification requirements in Danish public projects, forcing reliance on imported certified supply.
- Concrete:Ready-mix formulations with embodied-carbon declarations support residential volume production and transport infrastructure across Sweden's urban corridors.
- Bricks:Fired clay masonry retains niche positioning in heritage-sensitive renovations and acoustic partitions within Copenhagen's historic districts.
Today's leader: Steel. Tomorrow's challenger: Cement.
Application:
Cost tier stratification separates premium efficiency-rated projects from baseline compliance builds across Nordic metropolitan zones.
- Residential:Volume production of energy-efficient housing absorbs prefabricated timber systems at scale. Stockholm and Oslo metropolitan deficits reward developers delivering above-code Boverket energy performance certificates.
- Infrastructure:Rail electrification, tunneling, and coastal protection investments are expanding most quickly across Norway's urban corridor from Oslo to Bergen.
- Commercial:Integrated design-build frameworks consolidate procurement for office and retail facilities in Danish urban centers.
- Industrial:Facility modernization projects specify certified low-carbon materials for manufacturing plant expansions in Sweden's peripheral regions.
Residential commands absolute value contribution; infrastructure climbs the fastest.
End User:
Customer type determines contract structure risk allocation and carbon accountability requirements.
- Government:Public tenders in Denmark and Norway mandate certified low-carbon cement and recycled steel, redirecting specification toward verified supply chains with full lifecycle documentation.
- Developers:Private residential volume producers in Stockholm sustain margin discipline through repeatable building system platforms and captive material supply chains.
- Contractors:Integrated design-build specialists control timelines from concept to handover across Scandinavian commercial portfolios.
- Homeowners:Individual renovations navigate Boverket energy performance certificate requirements for major retrofit planning approvals.
Government sets compliance benchmarks; developers scale efficient delivery.
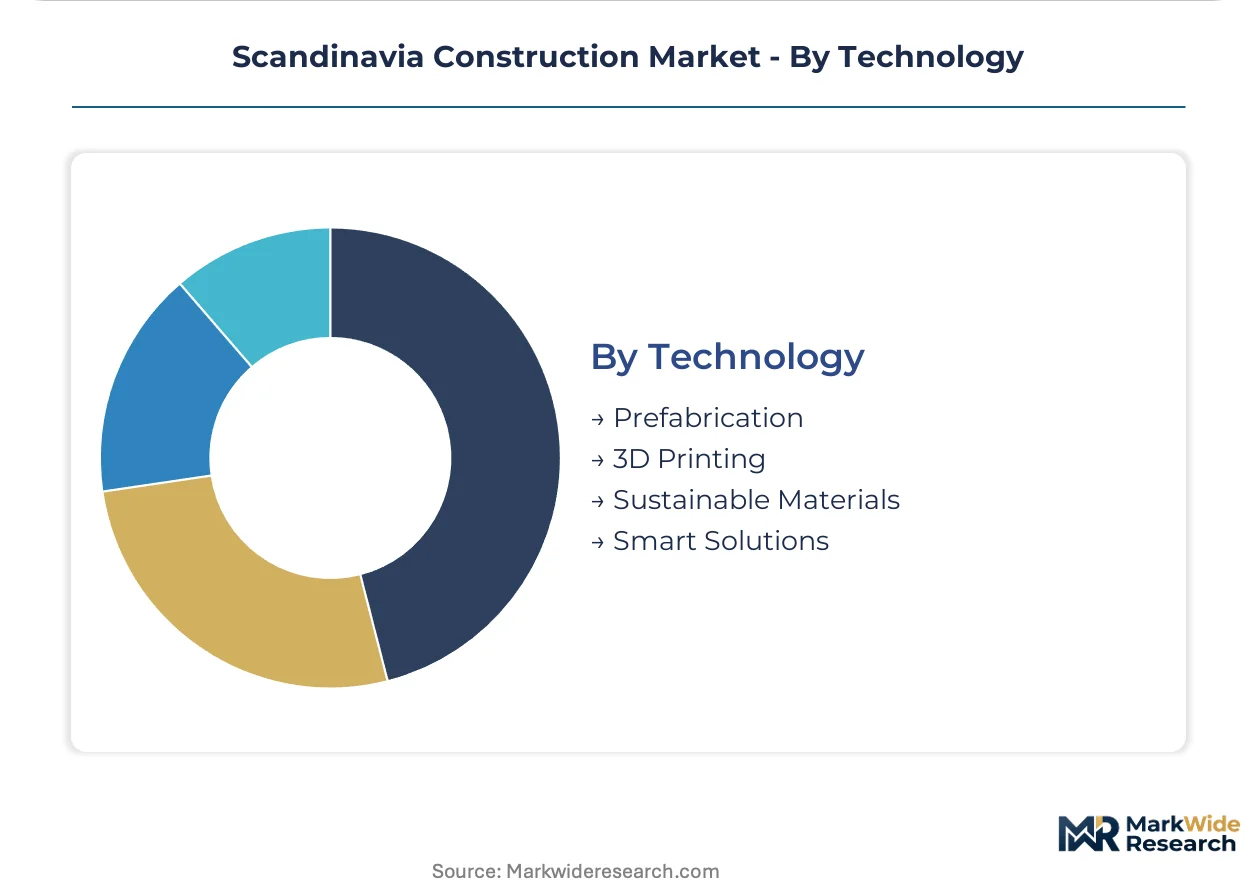
Technology:
Maturity curves separate proven prefabrication platforms from emerging digital fabrication methods.
- Prefabrication:Cross-laminated timber and glulam systems compress construction timelines for mid-rise housing between four and twelve stories. Mill-to-site logistics platforms control moisture content through final installation.
- Sustainable Materials:Engineered wood products demonstrate fire-rated performance equivalent to concrete and steel, consolidating supplier relationships around integrated carbon traceability systems.
- Smart Solutions:Digital building management integration supports operational efficiency monitoring in Norwegian near-zero emission public buildings.
- 3D Printing:Layered concrete deposition remains experimental for structural applications, constrained by Nordic building code acceptance timelines and material certification requirements.
Prefabrication anchors current volume; sustainable materials gain regulatory tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stockholm's metropolitan corridor anchors Scandinavian construction demand through 2035, absorbing prefabricated timber systems and energy-efficient housing at scale across Denmark, Norway, and Sweden.
Sweden
Residential volume production concentrates in Stockholm, Gothenburg, and Malmö metropolitan zones where housing deficits persist. Boverket progressively tightens energy performance certificate requirements for new construction and major renovations. The Stockholm urban corridor absorbs cross-laminated timber platforms for mid-rise developments between four and twelve stories.
Norway
Rail electrification, tunneling, and coastal protection investments expand across the Oslo to Bergen urban corridor. TEK17 technical standards mandate near-zero emission thresholds for new public buildings. Oslo's metropolitan zone converges infrastructure renewal with energy-efficient housing demand.
Denmark
Integrated design-build frameworks consolidate procurement for commercial facilities in Copenhagen and Aarhus urban centers. Danish Building Regulations align with EU Green Deal carbon-border mechanisms requiring certified low-carbon cement and recycled steel. Copenhagen's historic districts retain fired clay masonry for heritage-sensitive renovations.
Finland
Climate declaration harmonization efforts position Finnish suppliers for Nordic carbon labeling alignment. The Ministry of the Environment coordinates regional standards for construction product lifecycle documentation. Helsinki-Tampere corridor developments test prefabrication-to-site integration for timber module tolerances.
Scandinavia Construction Market Competitive Landscape
Global majors compete with regional champions across integrated design-build capability and prefabricated system platforms. The vendor base clusters around three tiers: multinational contractors with captive supply chains, mid-sized national specialists with regional contractor networks, and volume residential producers with repeatable building systems. Strategic moves concentrate on consolidated supplier frameworks and multi-year material packages trading price competition for schedule certainty.
Within the integrated design-build tier, Skanska AB and Veidekke ASA exemplify single-source accountability models spanning concept to handover. Peab AB anchors the volume residential segment through repeatable building system platforms. Ramboll Group A/S occupies a position among engineering specialists providing technical advisory for carbon-accounting compliance.
| Leading Market Players |
|---|
| Peab AB |
| Ramboll Group A/S |
| Skanska AB |
| AF Gruppen ASA |
| MT Højgaard Holding A/S |
| Veidekke ASA |
| JM AB |
| YIT Oyj |
| NCC AB |
| Others |
Value Network & Pricing Analysis
Nordic timber futures and engineered wood commodity benchmarks cascade through Scandinavian construction supply chains, compressing margins for contractors locked into fixed-price agreements while rewarding developers with captive mill relationships. Boverket's embodied-carbon thresholds and TEK17 near-zero emission mandates stratify procurement costs across certified and uncertified material tiers.
Pricing Analysis
Input-cost pass-through from certified low-carbon cement and recycled structural steel runs unevenly through project pricing tiers. Three-tier pricing structure across premium certified, standard compliant, and economy baseline levels separates government tenders with full lifecycle documentation from private residential volume production. Price differentiation hinges on EU ETS compliance grade and Boverket energy performance certificate rating. Cost compression in standard-tier residential builds is intensifying because domestic cement production capacity lags specification requirements. Government procurement officers demonstrate lowest price sensitivity, while individual homeowners navigating retrofit approvals show highest elasticity.
Supply Chain Analysis
Direct-to-contractor mill channels handle cross-laminated timber and glulam demand from Stockholm and Oslo metropolitan developers, bypassing traditional distribution layers. Supply concentration rests on Sweden, Norway, and Finland for engineered wood production, with Denmark drawing from German and Polish steel processors for TEK17-compliant recycled structural sections. Raw material feeds from Nordic spruce forests, blast furnace slag for low-carbon binders, and calcined clay deposits shape regional sourcing patterns. Single-source vulnerability in EU ETS-certified steel documentation creates procurement bottlenecks for Danish public tenders. Distribution runs through integrated design-build frameworks that consolidate multi-year material packages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scandinavia construction functions as a regulatory compounder where EU Green Deal carbon-border mechanisms and national building code convergence accelerate demand for certified material supply chains and energy modeling capabilities.
For Market Incumbents: Extend captive timber supply agreements through 2035 to lock in mill capacity before Finnish climate declaration harmonization triggers Nordic-wide certification competition. Consolidate in-house lifecycle assessment expertise to eliminate embodied-carbon auditing bottlenecks that delay project approvals. Defend margin position against emerging modular housing specialists by anchoring integrated design-build accountability from concept to handover.
For New Entrants and Emerging Players: Begin with Copenhagen and Aarhus commercial retrofit segments where fragmented procurement creates white-space for consolidated supplier frameworks. Target Danish government tenders with certified low-carbon cement import partnerships that bypass domestic production constraints. Pursue mill-to-site logistics platform partnerships as the primary go-to-market angle for timber module tolerance integration.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized embodied-carbon auditing consultancies and engineered wood product suppliers with verified Boverket compliance documentation. Long-term viability favors acquisition targets with Nordic-spanning regulatory relationships and captive access to EU ETS-certified steel supply. Watch for Finnish Ministry of the Environment announcement timing on climate declaration harmonization as the inflection signal for first-mover certification advantage.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive mill relationships secure Boverket-compliant CLT capacity for Stockholm residential volume production. |
| Lifecycle Assessment Capability Buildout | In-house embodied-carbon modeling eliminates documentation bottlenecks under tightening Nordic building codes. |
| Multi-Year Material Package Contracts | Consolidated supplier frameworks trade price competition for schedule certainty across Norwegian infrastructure corridors. |
| Cross-Border Certification Pre-Positioning | Finnish climate declaration alignment creates first-mover advantage for EU-wide embodied-carbon labeling requirements. |
| Integrated Design-Build Platform Expansion | Single-source accountability from concept to handover displaces fragmented procurement in Danish commercial portfolios. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with construction procurement directors, Boverket compliance officers, timber mill operations managers, and integrated design-build project executives with secondary validation. Regulatory filings from Sweden's Boverket, Norway's Direktoratet for byggkvalitet, and Denmark's Bygningsreglementet anchored policy trajectory assessment. Nordic trade association construction output data, EU ETS emissions registry records, and national building permit databases supported volume estimation. Bottom-up project pipeline analysis and top-down macroeconomic scenario weighting produced convergent market size estimates.
Segment-weighting approaches distributed value across product type, application, end user, and technology dimensions, with additional modeling for regulatory compliance tier and carbon certification grade. CAGRs derived from regression analysis of historical permit issuance, material price indices, and policy implementation timelines. Cross-laminated timber adoption curves, rail electrification investment schedules, and embodied-carbon threshold phase-in schedules informed trajectory assumptions across the projection horizon.
Several conditions sit outside the modeled scope, including geopolitical disruption to EU ETS carbon credit markets, abrupt Boverket regulatory reversals, and breakthrough 3D printing code acceptance that could accelerate material substitution. Forecasts reflect assumptions about steady Nordic economic growth and continued EU Green Deal implementation. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Guatemala Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
India Pre-Engineered Buildings Market
Building Construction
India Prefabricated Buildings Market
Building Construction
China Modular Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Oman Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Indonesia Infrastructure Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Australia Construction Market
Building Construction
Tunnels Design and Construction Market
Building Construction
GCC Cement Market
Building Construction
North America Construction Market
Building Construction
Singapore Data Center Construction Market
Building Construction
United Kingdom Data Center Construction Market