
 Modular and Prefabricated Construction Market | 2026-2036
Modular and Prefabricated Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Modular and Prefabricated Construction Market Analysis
The gap between premium architect-designed volumetric units and commodity panelized housing is consolidating around certification depth and supply chain control. Skanska AB leverages its integrated design-build capability to capture complex commercial and healthcare contracts. Clayton Homes anchors the mass-market residential segment through factory scale and retail channel density across North America.
Modular and prefabricated construction encompasses factory-manufactured building components or fully volumetric units produced under controlled conditions, then transported and assembled on-site, with structural performance typically validated to ISO 9001 quality management and local seismic or wind-load codes. Its primary purpose is compressing construction schedules, reducing material waste, and stabilizing labor inputs against on-site variability. Residential application leads volume absorption, though healthcare application generates superior margin pools due to stringent infection-control and MEP integration requirements. Off-site fabrication technology dominates current throughput, while 3D printing technology occupies an emerging niche for geometrically complex architectural elements.
The EPA administers stormwater and air-quality permits that factory operations must satisfy to maintain production continuity, while OSHA sets workplace safety benchmarks that influence automation investment levels in fabrication plants. ISO standards for quality management and structural performance create baseline market-access requirements that differentiate certified producers from regional competitors. Stakeholders must weigh capital allocation between expanding factory automation and securing long-term steel and cross-laminated timber supply agreements.
Market Dynamics
Factory automation investments are compressing production cycles for volumetric modules while labor scarcity in traditional construction accelerates procurement shifts toward off-site fabrication systems.
Growth Catalysts
- EU Green Deal embodied carbon rules:Procurement mandates for low-carbon assemblies redirect public and private contracts toward factory-controlled production environments with verified material traceability.
- German housing shortages:Municipal zoning reforms and federal construction targets favor volumetric methods to overcome skilled labor deficits and accelerate unit delivery timelines.
- Healthcare infection-control standards:Off-site fabrication with integrated MEP systems meets stringent clean-room specifications that on-site construction struggles to replicate consistently.
Market Restraints
- Cross-laminated timber supply concentration:European and North American mill capacity constraints create input bottlenecks for low-carbon modular projects seeking mass timber structural systems.
- Transportation infrastructure limitations:Highway load restrictions and bridge clearances in older urban cores limit module dimensions and increase last-mile logistics costs.
- Building code fragmentation:Jurisdiction-specific approval processes for factory-built components create regulatory friction that erodes schedule advantages in multi-state or multi-national deployments.
Strategic Opportunities
- India affordable housing shortfall:Central government PMAY-Urban targets and state-level slum redevelopment programs present volume absorption potential for standardized panelized systems.
- Data center rapid deployment:Hyperscale cloud operators require compressed construction timelines for power and cooling infrastructure that modular electrical and mechanical skids can satisfy.
- 3D printing-concrete hybrid methods:Convergence of robotic extrusion for complex architectural forms with conventional panelized systems enables geometric differentiation without sacrificing factory throughput.
Industry Challenges
- Digital fabrication technician scarcity:CNC programming and robotic assembly operations require specialized skills that vocational training pipelines have not yet scaled to meet.
- Multi-jurisdictional certification timelines:ISO 9001 quality management validation alongside local seismic and wind-load approvals extends pre-production approval cycles.
- Legacy site integration complexity:Foundation tolerances and utility connection standards vary across markets, forcing module producers to maintain excessive design variant inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modular and Prefabricated Construction Market |
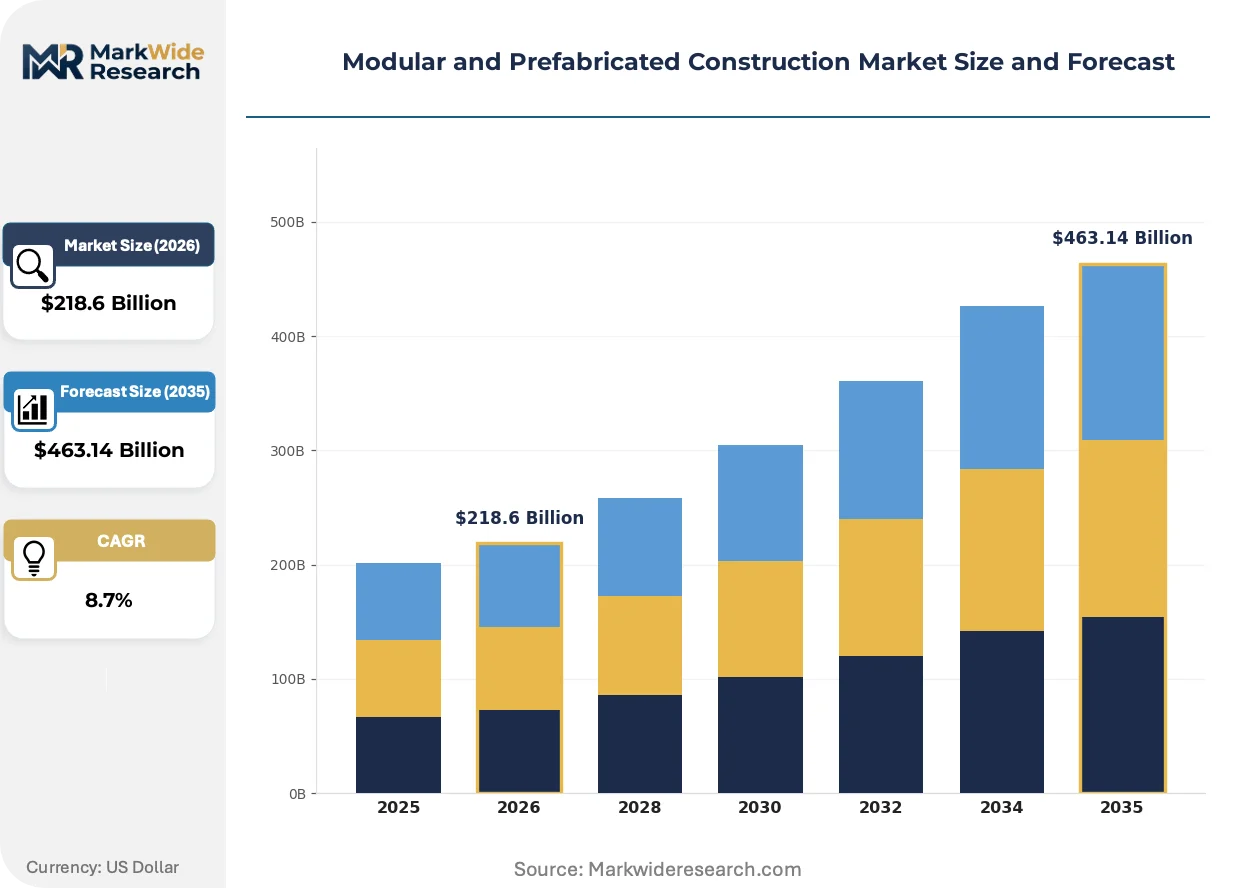
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $463.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
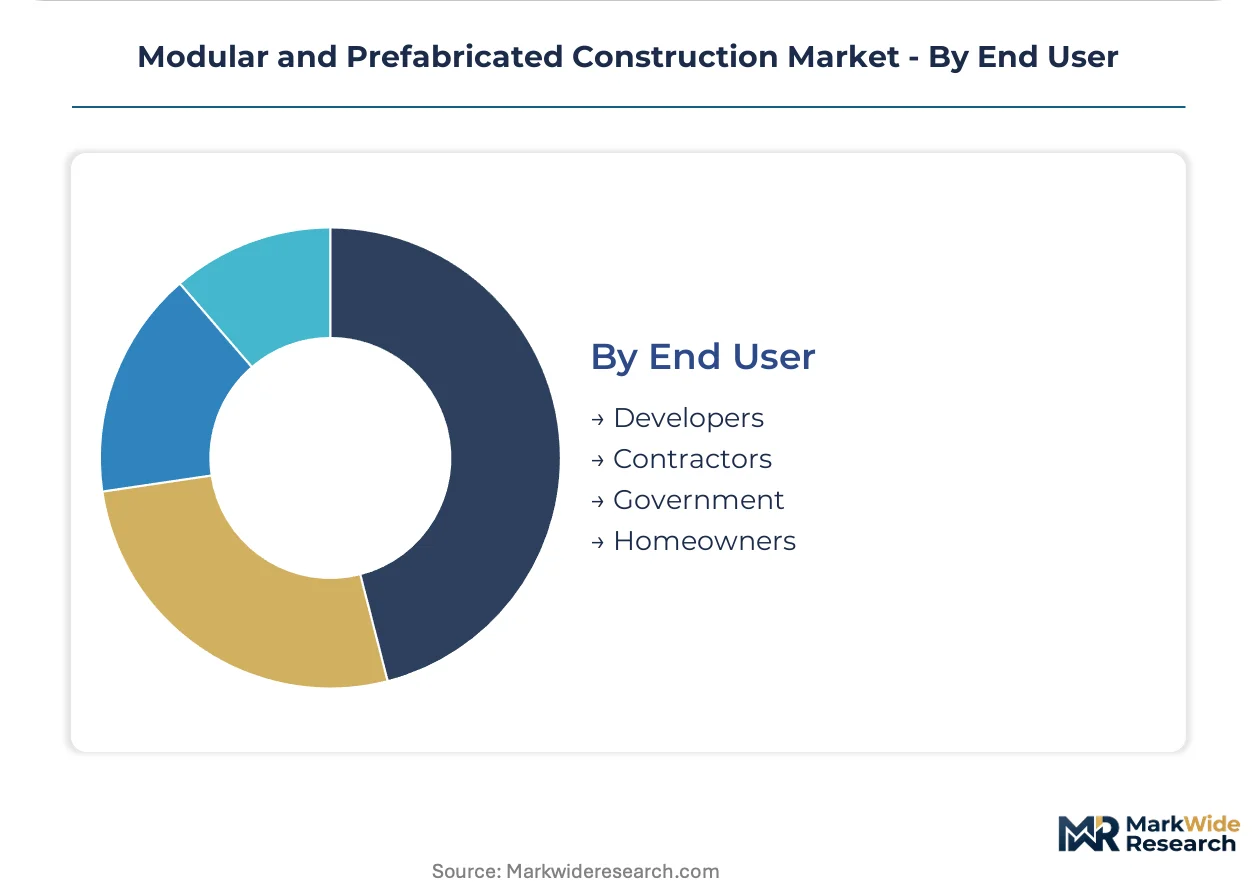
| Segmentation | Product Type: Modular Homes, Prefabricated Offices, Container Homes, Modular Schools Technology: 3D Printing, BIM, Off-site Fabrication, Smart Construction Application: Residential, Commercial, Educational, Healthcare End User: Developers, Contractors, Government, Homeowners |
| Companies Covered | Skanska AB, Bouygues Construction, Lendlease Group, Clayton Homes, Daiwa House Industry Co., ATCO Ltd., Kiewit Corporation, Laing O’Rourke, Red Sea International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modular and Prefabricated Construction Market Emerging Trajectories
Digital twin workflows and automated quality inspection systems are reshaping how factory environments validate structural performance before modules leave controlled production conditions.
Cross-laminated timber and mass timber hybrid systems are consolidating market position as primary structural materials for mid-rise residential and commercial volumetric construction. German and Austrian developers have accelerated adoption to satisfy EU Green Deal carbon accounting requirements. The technology is consolidating supply chain control among engineered wood producers with captive forestry operations and certified fabrication facilities.
REACH chemical registration requirements and the EU Construction Products Regulation are tightening material disclosure obligations for factory-produced building components. Manufacturers must now document substance content across adhesives, coatings, and insulation materials to maintain CE marking validity. Healthcare and educational facility developers in France and the Netherlands are prioritizing suppliers with complete environmental product declarations to preempt future compliance exposure.
Developer procurement teams are compressing vendor qualification cycles and demanding outcome guarantees on energy performance and construction schedule adherence. Traditional design-bid-build sequencing is yielding to design-build and integrated project delivery contracts that transfer risk to modular fabricators. This pattern is most visible in US metropolitan markets where labor cost volatility and interest rate exposure have made fixed-price, accelerated delivery terms attractive to institutional real estate investors.
Modular and Prefabricated Construction Market Segmentation
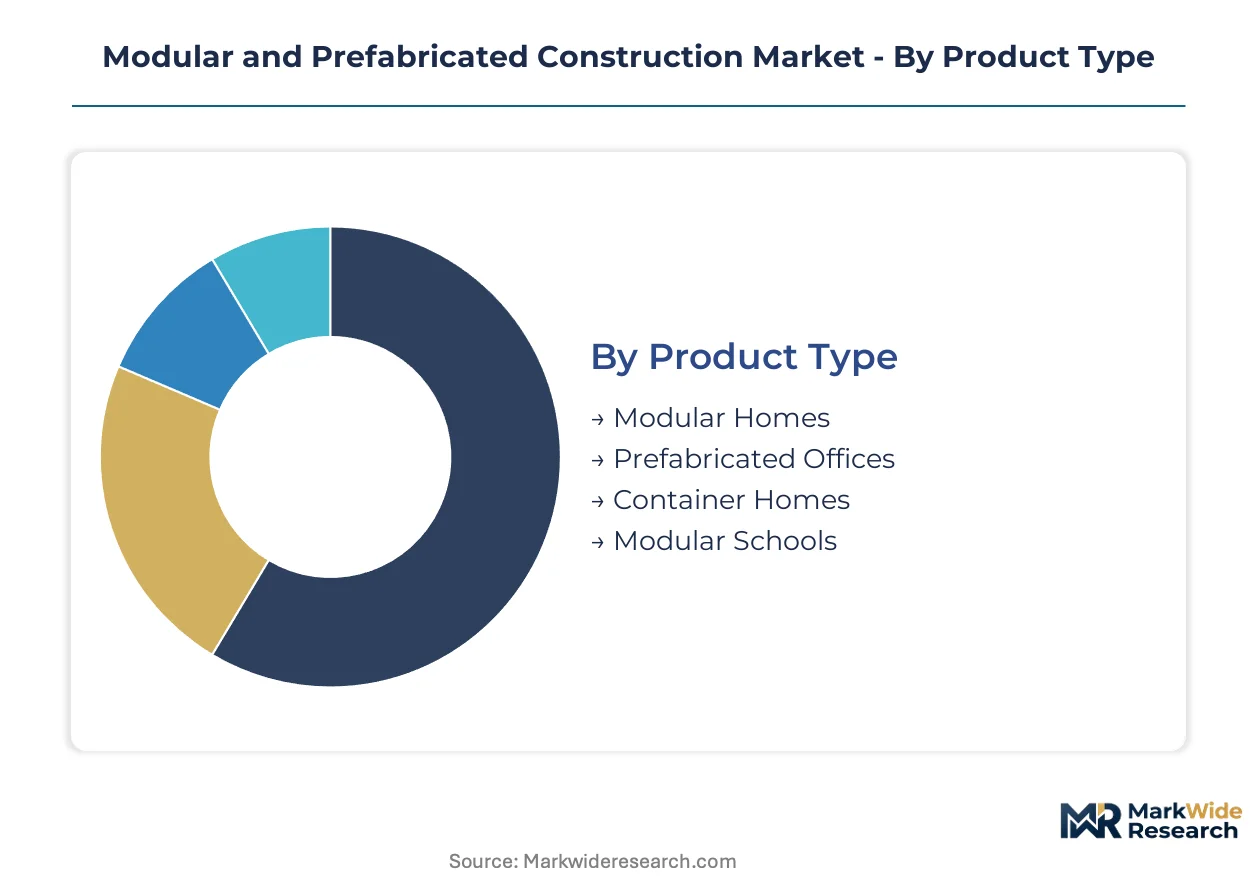
Segmentation in modular construction reveals how capital allocation, technology maturity, and procurement authority fragment across distinct buyer profiles. Factory automation requirements and certification depth create divergent margin structures that reward specialization over breadth.
Product Type:
Capital intensity varies sharply across product categories, with volumetric modules demanding the heaviest upfront investment in factory infrastructure and quality systems.
- Modular Homes:Fully volumetric residential units manufactured under ISO 9001 protocols with integrated MEP systems. German municipal housing programs and federal construction targets in Germany concentrate procurement volume as labor scarcity accelerates adoption of factory-built dwellings.
- Prefabricated Offices:Panelized and volumetric commercial workspace assemblies designed for rapid deployment. Hyperscale cloud operators in the United States and data center developers in India drive demand for compressed construction timelines on power and cooling infrastructure.
- Container Homes:Repurposed shipping containers converted to habitable space with structural modifications. Standardized dimensions reduce design variant inventories for producers serving affordable housing programs.
- Modular Schools:Volumetric educational facilities with specialized acoustic and ventilation specifications. State-level procurement in France and the Netherlands prioritizes suppliers with complete environmental product declarations under EU Construction Products Regulation.
Modular Homes absorb the bulk of installed capacity; Prefabricated Offices are expanding most quickly.
Technology:
Technology selection maps directly to production throughput capabilities and the skill intensity of workforce requirements.
- Off-site Fabrication:Controlled factory production of building components or complete modules under environmental conditions that stabilize material performance. This technology dominates current throughput across residential and healthcare applications in Germany and the United States.
- BIM:Building Information Modeling systems that coordinate design, fabrication, and site integration through digital twin workflows. Healthcare facility developers in France leverage BIM to meet stringent infection-control specifications that on-site construction struggles to replicate.
- 3D Printing:Robotic extrusion of concrete or polymer materials for geometrically complex architectural elements. Emerging niche status limits deployment to demonstration projects and custom facade components.
- Smart Construction:Sensor-integrated modules with embedded IoT infrastructure for performance monitoring. Early-stage adoption concentrates in commercial office deployments seeking operational efficiency guarantees.
Off-site Fabrication commands the largest share of production volume; BIM is climbing the fastest as procurement teams demand outcome guarantees on schedule adherence.
Application:
Application segments separate by margin structure, with specialized facility types commanding premium pricing for certification depth and MEP integration.
- Residential:Single-family and multi-family housing delivered through volumetric or panelized systems. Housing shortages in Germany and affordable housing shortfalls in India direct procurement toward standardized panelized systems with accelerated delivery timelines.
- Healthcare:Hospitals, clinics, and clean-room facilities requiring stringent infection-control and integrated mechanical-electrical-plumbing systems. Superior margin pools attract producers with ISO 9001 validation and verified material traceability under EU Green Deal embodied carbon rules.
- Commercial:Office buildings, retail spaces, and hospitality structures. Procurement in United States metropolitan markets shifts toward design-build contracts that transfer risk to modular fabricators.
- Educational:Schools and university facilities with specialized acoustic and ventilation requirements. French and Dutch developers prioritize environmental product declarations to preempt future compliance exposure under REACH chemical registration.
Residential absorbs the bulk of installed capacity; Healthcare is gaining share fastest on margin differentiation.
End User:
End user categories reflect divergent procurement authority, with institutional buyers demanding outcome guarantees that reshape contract structures.
- Developers:Institutional real estate investors and project sponsors controlling capital allocation across multi-unit residential and commercial portfolios. United States metropolitan developers compress vendor qualification cycles and demand fixed-price, accelerated delivery terms.
- Government:Federal, state, and municipal agencies administering housing programs and public infrastructure. German federal construction targets and India's PMAY-Urban scheme direct volume toward standardized systems.
- Contractors:Construction firms integrating modular components into broader project delivery. Design-build contract proliferation transfers risk to fabricators with integrated design capabilities.
- Homeowners:Individual purchasers of single-family modular dwellings. Retail channel density in North America anchors mass-market penetration for factory-scale producers.
Developers absorb the bulk of installed capacity; Government procurement is climbing the fastest on infrastructure program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European modular fabrication capacity, with factory clusters in Dortmund and Essen supplying volumetric units across federal housing programs. German municipal zoning reforms accelerate procurement timelines for standardized residential modules.
United States
Data center construction in Northern Virginia and Phoenix drives demand for rapid-deployment electrical and mechanical skids. OSHA workplace safety benchmarks influence automation investment levels in fabrication plants across the Southeast manufacturing belt. Clayton Homes anchors mass-market residential penetration through factory scale and retail channel density.
Germany
Federal construction targets and housing shortages in Berlin, Munich, and Hamburg favor volumetric methods to overcome skilled labor deficits. EU Green Deal embodied carbon rules redirect procurement toward factory-built low-carbon assemblies with verified material traceability. Cross-laminated timber supply from Austrian and Bavarian mills feeds mid-rise residential projects.
India
Central government PMAY-Urban targets and Maharashtra state slum redevelopment programs present volume absorption potential for standardized panelized systems. BIS certification requirements for factory-built components create regulatory friction that domestic fabricators navigate through state-level partnerships. Ahmedabad and Pune industrial corridors concentrate production capacity for affordable housing modules.
Japan
Daiwa House Industry exemplifies integrated design-build capability capturing multi-family residential contracts in Tokyo and Osaka metro areas. METI building energy codes drive demand for high-performance envelope systems that off-site fabrication delivers consistently. Prefabrication rates in residential construction exceed global averages due to seismic performance requirements.
United Arab Emirates
Red Sea International occupies a position serving hospitality and worker accommodation projects across Dubai and Abu Dhabi. MOHAP healthcare facility standards accelerate adoption of infection-control modules for hospital expansion. Jebel Ali industrial zone hosts fabrication yards supplying modular units for Saudi giga-projects.
Modular and Prefabricated Construction Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification depth and supply chain control dimensions. The vendor base stratifies into three tiers: integrated design-build operators capturing complex commercial contracts, factory-scale residential specialists, and regional panelized system fabricators. Competitive positioning depends on securing long-term engineered wood supply agreements and expanding factory automation. Consolidation pressure favors players with captive design capabilities and multi-jurisdictional approval experience.
Within the integrated construction tier, Skanska AB represents European design-build capability, while Bouygues Construction exemplifies French engineering conglomerate positioning. Lendlease Group anchors Australian-origin international project delivery. Among factory-scale residential specialists, Clayton Homes occupies the North American mass-market vector. These players illustrate how geographic origin and corporate structure map to strategic archetype selection in fragmented procurement environments.
| Leading Market Players |
|---|
| Skanska AB |
| Bouygues Construction |
| Lendlease Group |
| Clayton Homes |
| Daiwa House Industry Co. |
| ATCO Ltd. |
| Kiewit Corporation |
| Laing O'Rourke |
| Red Sea International |
| Others |
Supply Flow & Price Mechanics
Captive forestry operations among engineered wood producers anchor supply positions and pricing power for mass timber modular systems in Germany and Austria. This backward integration into timber sourcing insulates margin structures against raw material volatility while enabling premium positioning under EU Green Deal carbon accounting requirements.
Pricing Analysis
Outcome-based pricing tied to guaranteed construction schedule adherence anchors contract structures for healthcare and data center applications. Three-tier pricing structure across premium architect-designed volumetric units, standard certified modules, and economy panelized systems separates buyers by certification depth and MEP integration complexity. Pricing pressure stems from steel and cross-laminated timber input bottlenecks squeezing mid-tier producers. Government procurement programs in India exhibit highest price sensitivity; institutional healthcare developers in France and the Netherlands demonstrate lowest sensitivity due to infection-control compliance premiums.
Supply Chain Analysis
Regional distribution centers in Dortmund, Essen, and Jebel Ali coordinate hub-and-spoke delivery patterns for volumetric modules facing highway load restrictions and bridge clearance constraints. Manufacturing concentrates in Germany, the United States, and India, with cross-laminated timber sourcing from Austrian and Bavarian mills. Supply chains rest on steel coil, engineered wood adhesives, and IoT sensor components. Single-source vulnerability in European mass timber milling creates structural risk. Distribution runs through factory-direct channels for large developers and retail networks for residential homeowners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over engineered wood supply and factory automation scale determines competitive survival. Players are pursuing captive forestry operations as the decisive upstream lever.
For Market Incumbents: Deploy design-build contract capabilities to capture complex healthcare and commercial projects before panelized competitors achieve ISO 9001 certification depth. Consolidate position through multi-jurisdictional approval experience that accelerates pre-production cycles. Counter emerging 3D printing-concrete hybrid entrants by expanding factory automation in the Southeast United States manufacturing belt. For New Entrants and Emerging Players: The price-point gap between premium volumetric healthcare modules and economy panelized residential units offers white-space entry. Target India's PMAY-Urban affordable housing shortfall with standardized panelized systems certified under BIS requirements. Pursue state-level partnerships in Maharashtra and Gujarat to navigate regulatory friction. Go-to-market through contractor channel partnerships rather than direct developer sales. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated construction conglomerates seeking factory-scale fabrication capabilities. Long-term viability favors producers with captive timber supply and multi-jurisdictional ISO validation. Target acquisition archetype: mid-scale German or Austrian modular specialists with EU Green Deal compliance infrastructure. Watch cross-laminated timber mill capacity expansion as the inflection signal for input cost relief.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Timber Supply | Captive forestry operations insulate margin structures against European mill capacity constraints. |
| Factory Automation Scale-Up | Robotic assembly investments compress production cycles for volumetric modules in German Ruhr corridor. |
| Multi-Jurisdictional Certification Investment | ISO 9001 validation alongside local seismic codes accelerates procurement in fragmented regulatory environments. |
| Design-Build Capability Acquisition | Integrated project delivery contracts transfer risk from institutional real estate investors to fabricators. |
| Regional Distribution Hub Expansion | Dortmund and Jebel Ali hub-and-spoke networks overcome last-mile logistics bottlenecks for oversized modules. |
Methodological Framework
Multi-period observation of factory automation investment flows, EU Green Deal procurement mandates, and cross-laminated timber mill capacity anchored the trend analysis, supplemented by interviews with modular construction plant managers, healthcare facility development executives, municipal housing procurement officers, and engineered wood supply specialists. Secondary validation drew from EPA permitting databases, OSHA workplace safety filings, EU Construction Products Regulation disclosure records, and BIS certification registries. Bottom-up project pipeline tracking and top-down construction spending analysis enabled triangulation across volume and value estimates.
Input-output matrices modeled demand across product type, technology maturity, application margin structure, and end-user procurement authority segments throughout the forecast period. CAGRs were derived from regression analysis against construction labor cost indices, interest rate exposure patterns, and federal housing program allocation trajectories. Industry-specific forecast inputs included German municipal zoning reform timelines and hyperscale data center deployment schedules in Northern Virginia and Phoenix.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time factory utilization rates and proprietary contract pricing introduce uncertainty bands around volume projections. Forecasts reflect documented assumptions regarding EU embodied carbon rule enforcement intensity and Indian state-level slum redevelopment pacing. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
North America Construction Market
Building Construction
Australia Construction Market
Building Construction
South Korea 3D Printing Construction Market
Building Construction
Pre-Engineered Building Market
Building Construction
Middle East Data Center Construction Market
Building Construction
US Modular Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
Russia Prefabricated Buildings Market
Building Construction
Africa Construction Market
Building Construction
Malaysia Construction Market
Building Construction
GCC Prefabricated Housing Market
Building Construction
Saudi Arabia Prefab Wood Buildings Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
China Building Construction Market
Building Construction
Precast Construction Market