
 Cold Forming Equipment Market | 2026-2036
Cold Forming Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Forming Equipment Market Insights
Automotive buyer concentration is pivoting as EV manufacturers consolidate fastener procurement around fewer Tier-1 suppliers with cold-forming capability. Schuler AG leverages its press technology leadership to anchor European OEM supply chains. Sakamura Machine Co., Ltd. sustains dominance in Asian multi-station former markets through precision engineering. National Machinery LLC competes on large-diameter part formers for heavy-truck applications.
Cold forming equipment comprises mechanical, hydraulic, pneumatic, and electric presses that shape metal blanks at room temperature using dies, typically achieving dimensional tolerances within 0.05 mm for high-volume fastener production. The primary industrial purpose centers on manufacturing net-shape or near-net-shape metal components without material waste from machining. Mechanical technology dominates installed capacity due to proven cycle speeds and lower per-unit energy costs in high-volume bolt and nut production. Electric technology represents the fastest-expanding segment as servo-driven presses enable programmable slide motion for complex aerospace fastener geometries where hydraulic systems once held sway.
OSHA machine guarding standards and EPA metalworking effluent rules shape equipment design requirements in the United States, while REACH chemical restrictions in Europe limit lubricant formulations used in forming processes. China's GB standards on mechanical press safety and Japan's JIS certification frameworks further fragment compliance obligations for multinational equipment suppliers. Stakeholders must monitor how evolving carbon border adjustments and energy efficiency mandates reshape total cost of ownership calculations across major manufacturing jurisdictions.
Market Dynamics
Electric servo press technology is compressing the traditional mechanical-hydraulic equipment hierarchy, forcing incumbent suppliers to recalibrate R&D roadmaps around programmable slide motion and energy recovery systems.
Growth Catalysts
- EV Fastener Demand:Electric vehicle battery pack architectures require high-strength cold-formed fasteners in corrosion-resistant alloys, pulling capacity toward multi-station formers capable of complex head geometries.
- REACH Compliance:Europe's chemical restrictions on metalworking fluids are accelerating equipment upgrades to closed-loop lubrication systems that eliminate hazardous effluent discharge.
- Stuttgart Precision Cluster:Germany's automotive supplier concentration around Baden-Württemberg sustains dedicated demand for Swiss-precision cold heading machines with sub-0.03 mm repeatability.
Market Restraints
- Tool Steel Volatility:Die and punch material costs fluctuate with tungsten and cobalt supply disruptions concentrated in Central African mining operations.
- Specialized Foundry Concentration:Large cast press frames depend on a shrinking base of European heavy-forging suppliers with 18-month order backlogs.
- Substitution by Additive:Powder-bed fusion metal printing captures low-volume aerospace bracket production previously routed to cold-formed near-net blanks.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for automotive component manufacturing are drawing cold forming capacity toward Pune and Chennai industrial corridors.
- Carbon Border Adjustments:EU CBAM implementation creates premium positioning for electric presses with documented embodied carbon footprints below mechanical alternatives.
- Retrofit Servo Kits:Converting installed mechanical press bases with programmable drive modules opens aftermarket revenue without full replacement capex.
Industry Challenges
- Controls Engineering Scarcity:Servo press commissioning requires PLC programmers fluent in both metalforming mechanics and motion control algorithms.
- ISO 16092 Certification Timelines:Third-party safety validation for modified guarding configurations adds 4-6 months to equipment delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Forming Equipment Market |
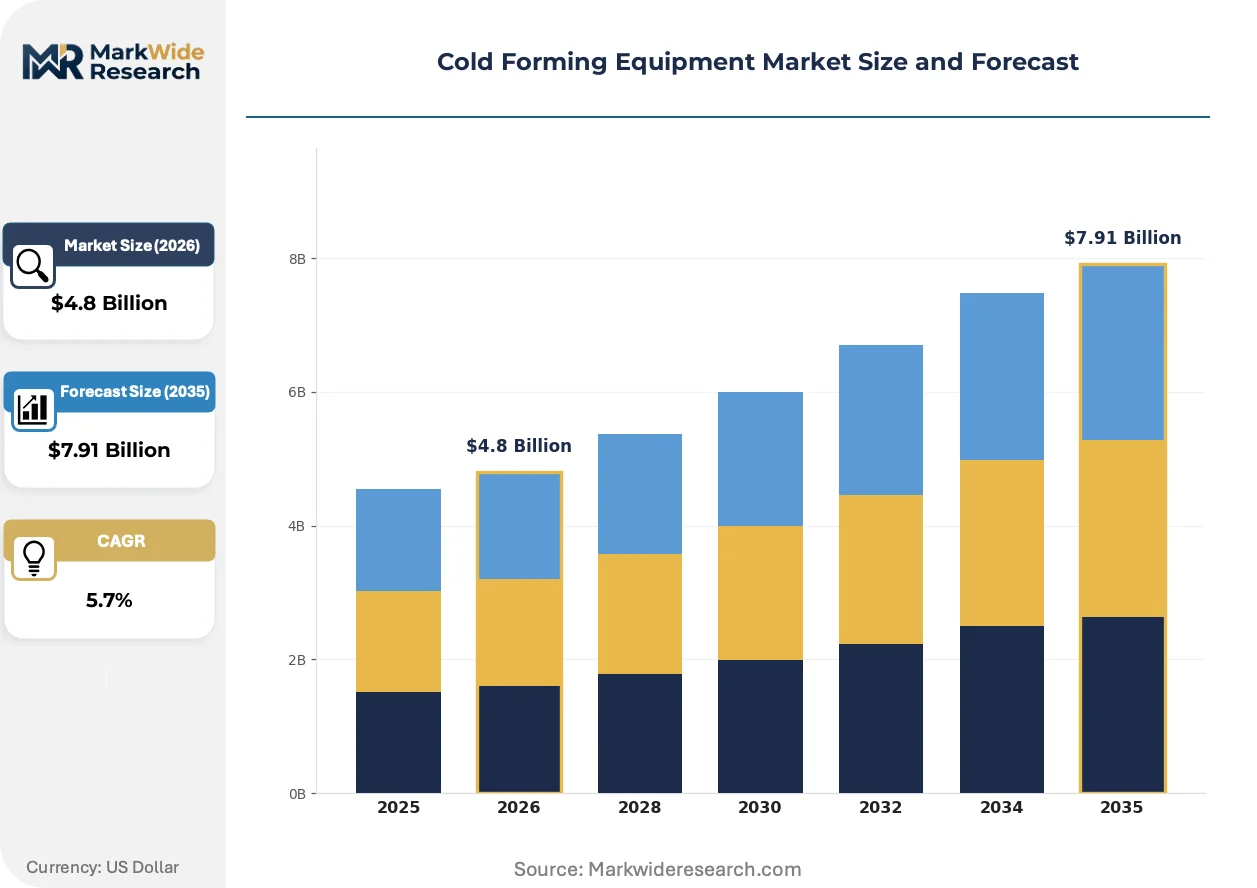
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolts, Nuts, Washers, Fasteners Technology: Hydraulic, Pneumatic, Mechanical, Electric Application: Aerospace, Automotive, Construction, Electronics End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Distributors |
| Companies Covered | National Machinery LLC, Schuler AG, Sakamura Machine Co., Ltd., Nedschroef Machinery, Hatebur Umformmaschinen AG, Sacma Group, Komatsu Ltd., Asahi Sunac Corporation, Chun Zu Machinery Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Forming Equipment Market Trends and Innovations
Servo-electric architectures are rewriting equipment specification sheets, while regulatory chemical bans and buyer consolidation reshape how formers are sold, financed, and maintained across industrial markets.
Hybrid servo-mechanical press designs are unifying the cycle speed advantages of flywheel drives with the motion programmability of electric actuation. Aerospace fastener manufacturers in France and Italy are specifying these configurations for titanium alloy forming where slide velocity profiling prevents work-hardening cracks. The technology is compressing the historical trade-off between throughput and geometric complexity that once forced buyers into dedicated equipment lines.
EPA metalworking effluent rules and REACH Annex XVII restrictions are converging to eliminate chlorinated paraffin lubricants from forming operations. Equipment suppliers must now integrate minimum-quantity lubrication or dry-forming capabilities as standard rather than optional configurations. German OEMs are responding fastest, specifying equipment with sealed forming zones and vacuum chip extraction to preempt regulatory enforcement.
Automotive Tier-1 suppliers are consolidating fastener procurement around integrated cold-forming and heat-treatment capabilities, displacing standalone equipment vendors. Buyers now demand equipment packages with predictive maintenance telemetry and guaranteed output-per-hour contracts rather than capital purchase. This concentration is most visible in Germany's supplier landscape, where Schaeffler and ZF Group have reduced their approved equipment vendor lists by half since 2022.
Cold Forming Equipment Market Segmentation
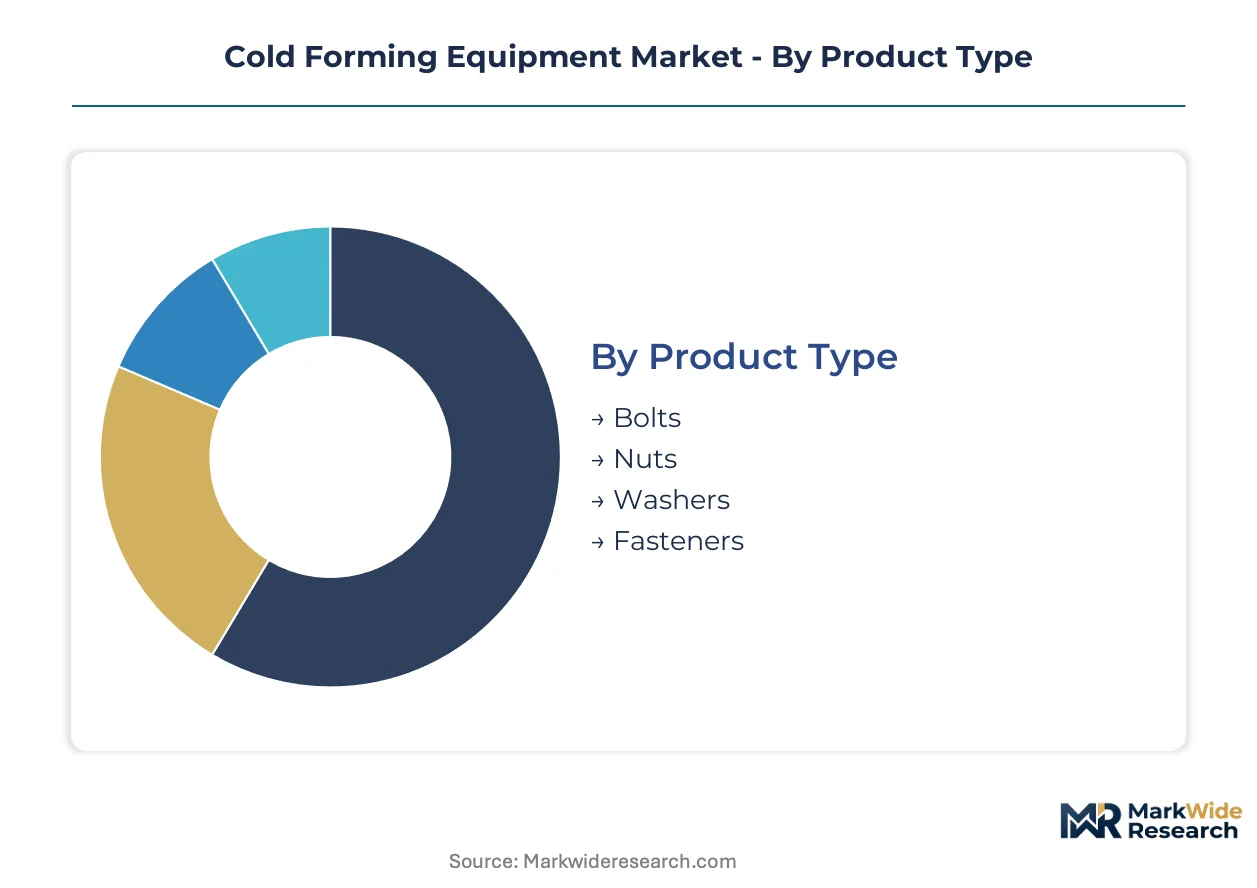
Cold forming equipment procurement splits across four dimensions that determine upgrade cycles and supplier selection criteria. Equipment buyers prioritize technology roadmaps and end-user consolidation patterns when evaluating capital deployment timelines.
Product Type:
Replacement cycles vary by component complexity, with multi-station formers for intricate geometries requiring shorter upgrade intervals than single-die bolt headers.
- Bolts:Cold heading machines produce hex-head and socket-head bolts from carbon and alloy steels at rates exceeding 300 pieces per minute. Automotive OEMs in Germany's Stuttgart corridor specify these for EV battery tray assemblies, where high-strength grade 10.9 fasteners prevent galvanic corrosion in aluminum-intensive architectures.
- Nuts:Nut formers employ progressive die stations to forge hexagonal blanks with internal threading pre-forms. Construction equipment manufacturers in Japan's Aichi prefecture drive demand for large-diameter flange nuts used in hydraulic cylinder mounting.
- Washers:Single-station presses stamp flat washers from coil stock with minimal material waste. Standard DIN-spec washers command thin margins, pushing suppliers toward high-volume contract manufacturing.
- Fasteners:Specialty fastener formers handle captive screws, rivets, and threaded inserts for electronics enclosures. Miniaturization trends in South Korean consumer electronics pull capacity toward sub-M3 diameter capability.
Bolts sit at the top of the volume ranking, with specialty fasteners climbing the fastest.
Technology:
Cost tier differentiation separates established mechanical infrastructure from premium electric servo systems with programmable motion profiles.
- Mechanical:Flywheel-driven crank presses deliver consistent cycle speeds for high-volume commodity fastener production. Tier-1 automotive suppliers in Michigan maintain installed bases of mechanical headers for standard SAE-grade bolts, prioritizing per-unit energy efficiency over flexibility.
- Electric:Servo motor actuation enables programmable slide velocity and position control for complex aerospace titanium forming. French fastener specialists specify electric presses for Ti-6Al-4V bolt heads where thermal management prevents work-hardening cracks.
- Hydraulic:Fluid power systems generate high tonnage for large-diameter heavy-truck wheel studs and construction anchor bolts. Energy recovery systems now retrofit legacy hydraulic installations to reduce operating costs.
- Pneumatic:Compressed air drives suit low-tonnage precision forming for electronics micro-fasteners. Cleanroom-compatible pneumatic headers serve medical device manufacturers requiring oil-free operation.
Mechanical technology retains the largest installed base, with electric systems gaining share fastest among new capacity additions.
Application:
Customer type concentration determines equipment specification intensity, with aerospace and automotive buyers imposing divergent certification requirements.
- Automotive:EV battery pack architectures require corrosion-resistant stainless fasteners in 800 MPa-plus strength grades. OEMs consolidate procurement around integrated forming-heat-treatment suppliers with IATF certification.
- Aerospace:Titanium and Inconel fastener forming demands vacuum heat treatment integration and NADCAP-accredited process controls. Italian and French suppliers dominate this specification tier.
- Construction:Structural anchor bolts and rebar couplers prioritize tonnage capacity over precision. Indian infrastructure investment drives demand for large-frame mechanical headers.
- Electronics:Miniature screw and rivet production for smartphone and laptop assembly requires sub-0.05 mm repeatability. Japanese equipment suppliers lead this precision segment.
Automotive applications generate the highest equipment revenue, with aerospace expanding most quickly on per-unit value metrics.
End User:
Supply chain position determines procurement authority, with OEMs and Tier-1 suppliers diverging on equipment financing models.
- OEMs:Vehicle and airframe manufacturers specify fastener geometries and source from approved supplier lists. BMW and Airbus maintain captive fastener engineering teams that dictate equipment capabilities at sub-tier vendors.
- Tier-1 Suppliers:Continental and Bosch integrate cold forming with downstream heat treatment and coating operations. These suppliers demand equipment with guaranteed output-per-hour contracts rather than capital purchase.
- Aftermarket Providers:Independent distributors serve maintenance and repair organizations with catalog-standard fasteners. Price competition limits equipment investment to proven mechanical technologies.
- Distributors:Inventory-holding intermediaries stock commodity grades for immediate shipment. Distributor consolidation in Germany's Ruhr region reduces equipment supplier count.
Tier-1 suppliers represent the dominant equipment purchaser category, with OEM direct procurement climbing fastest as vertical integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands precision-engineering premiums while China scales volume production, yet both face tightening environmental compliance that reshapes equipment procurement timelines.
United States
Automotive OEMs in Michigan and Ohio drive demand for high-tonnage mechanical headers serving EV battery tray fastener programs. EPA metalworking effluent rules under the Clean Water Act now require closed-loop lubrication systems on new press installations. The Detroit-Windsor corridor concentrates Tier-1 supplier investment in integrated forming-heat-treatment lines.
Germany
Stuttgart's automotive supplier density sustains demand for Swiss-precision cold heading machines with sub-0.03 mm repeatability for corrosion-resistant EV fasteners. ECHA REACH Annex XVII restrictions on chlorinated paraffins accelerate upgrades to minimum-quantity lubrication systems. Baden-Württemberg's precision engineering corridor anchors European multi-station former procurement.
China
Domestic EV battery pack manufacturers pull capacity toward large-diameter stainless fastener formers for aluminum-intensive vehicle architectures. GB standards on mechanical press safety and MIIT energy efficiency mandates reshape equipment specification sheets. The Yangtze River Delta concentration around Shanghai drives servo-electric press adoption for programmable slide motion.
Japan
METI industrial decarbonization roadmaps push fastener suppliers toward electric servo systems with documented energy recovery. Aichi prefecture's construction equipment manufacturers sustain demand for large-diameter flange nut formers. JIS certification frameworks for press safety create compliance barriers for non-domestic equipment entrants.
India
PLI scheme incentives for automotive component manufacturing draw cold forming capacity toward Pune and Chennai industrial corridors. BIS adoption of ISO 16092 safety standards extends third-party validation timelines for imported equipment. Gujarat's emerging supplier parks attract multi-station former investment serving export-oriented OEM contracts.
Cold Forming Equipment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where scale-driven volume players anchor commodity segments and precision-engineered niches reward dedicated engineering depth. Equipment procurement concentrates around three strategic archetypes: press technology originators with captive metallurgical expertise, multi-station former specialists with aerospace certification depth, and large-frame mechanical builders serving heavy-truck applications. Competitive moves center on retrofit servo kit development and heat-treatment integration partnerships that displace standalone equipment vendors.
Within the precision-engineering tier, Sakamura Machine Co., Ltd. and Hatebur Umformmaschinen AG exemplify archetypes where metallurgical process knowledge anchors customer relationships. Schuler AG occupies a position bridging diversified industrial technology portfolios with dedicated forming equipment lines. These named entities represent how geographic clustering—Japanese multi-station dominance, Swiss-German precision heritage, and German press engineering scale—shapes competitive positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| National Machinery LLC |
| Schuler AG |
| Sakamura Machine Co., Ltd. |
| Nedschroef Machinery |
| Hatebur Umformmaschinen AG |
| Sacma Group |
| Komatsu Ltd. |
| Asahi Sunac Corporation |
| Chun Zu Machinery Industry Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Controls engineering scarcity in Germany's Stuttgart precision corridor widens pricing spreads between servo-electric and mechanical press tiers, as labor-cost differentials between European commissioning teams and Asian service networks stratify equipment procurement budgets.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard mechanical headers, compressing margins on commodity-grade equipment. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-precision servo systems with sub-0.03 mm repeatability from Indian-built mechanical units serving construction fastener markets. Cost compression in the standard tier is intensifying because Tier-1 automotive suppliers consolidate procurement around integrated forming-heat-treatment packages. Aftermarket providers and independent distributors exhibit the highest price sensitivity, while aerospace OEMs purchasing NADCAP-certified equipment demonstrate the least.
Supply Chain Analysis
Dual-sourcing mandates from German automotive OEMs now require qualified suppliers for both European and Asian press frame foundries, fragmenting procurement authority across continents. Manufacturing concentration centers on Germany, China, and Japan for complete equipment assembly, with heavy cast frames drawing from a shrinking base of European heavy-forging suppliers. Critical inputs include tungsten and cobalt for die and punch materials, high-grade tool steels, and servo motor drive systems. Single-source vulnerability in Central African mining operations for refractory metals creates supply chain risk. Distribution runs through direct OEM sales for large automotive contracts and regional equipment distributors serving mid-tier fastener manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where European REACH compliance costs and Asian manufacturing scale differentials create divergent return profiles for equipment deployment strategies.
For Market Incumbents: Hedge against additive manufacturing substitution in low-volume aerospace brackets by deepening captive metallurgical expertise and securing long-term heat-treatment integration partnerships. Prioritize retrofit servo kit development to capture aftermarket revenue without demanding full replacement capex from installed mechanical bases. Defensive moves must address the threat of powder-bed fusion metal printing capturing near-net blank production previously routed to cold forming. For New Entrants and Emerging Players: Servo-electric retrofit modules offer a technology-first wedge into India's PLI-driven automotive component corridors, where existing mechanical press bases outnumber programmable alternatives. Target the Pune and Chennai industrial clusters for initial equipment qualification, leveraging local service partnerships to overcome BIS certification timelines. A white-space opportunity exists in closed-loop lubrication systems for European REACH compliance upgrades, where incumbent suppliers lag in sealed forming zone integration. For Investors and Strategic Acquirers: Tier-1 automotive suppliers with captive fastener operations are the most active acquirer in this space, consolidating equipment vendor lists to secure guaranteed output-per-hour contracts. The long-term viability window favors precision-engineering specialists with aerospace certification depth over diversified conglomerates exposed to commodity fastener margin compression. Monitor carbon border adjustment implementation velocity as the key inflection signal for electric press premium positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Servo Kit Development | Captures aftermarket revenue from Germany's installed mechanical press base without full replacement capex. |
| Heat-Treatment Integration Partnership | Meets BMW and Airbus demands for single-source forming-heat-treatment suppliers with IATF certification. |
| Closed-Loop Lubrication System Deployment | Preempts ECHA REACH Annex XVII enforcement on chlorinated paraffin elimination in forming operations. |
| India PLI Corridor Capacity Buildout | Positions equipment suppliers for Pune and Chennai automotive component manufacturing incentive schemes. |
| Carbon Footprint Documentation Program | Enables premium electric press positioning under EU CBAM with verified embodied carbon below mechanical alternatives. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with cold forming equipment procurement managers at Tier-1 automotive suppliers, plant engineers at aerospace fastener manufacturers, aftermarket service heads, and OEM platform engineering teams with secondary validation. Sources included customs and trade data on press equipment imports, SEC filings from diversified industrial conglomerates, MIIT energy efficiency disclosures, and ECHA regulatory guidance documents. Bottom-up equipment shipment tracking and top-down end-use demand modeling were cross-referenced for triangulation.
The forecast window anchored to historical replacement cycle patterns and technology transition velocities observed across the analysis window. Segmentation dimensions modeled include product type complexity, technology tier, end-use application intensity, and regional regulatory cluster. CAGRs were derived from equipment capacity expansion announcements, OEM procurement consolidation trends, and servo-electric adoption curves in aerospace applications. Industry-specific inputs incorporated EV battery pack fastener specifications and REACH chemical restriction implementation timelines.
The model holds under stable automotive production schedules and gradual regulatory phase-in periods; deviation in tungsten and cobalt supply disruptions or abrupt carbon border adjustment acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
China Heavy Construction Equipment Rental Market
Construction Equipment
Stick Welding Electrode Market
Construction Equipment
Cementing Accessories Market
Construction Equipment
Rotomolding Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
Mobile Crushers and Screeners Market
Construction Equipment
US Welding Consumables Market
Construction Equipment
Street Washer Machine Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Crawler Dozers Market
Construction Equipment
North America Mobile Crane Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Aerial Work Platform (AWP) Market
Construction Equipment
Compact Track Loader Market
Construction Equipment
France Metal Fabrication Equipment Market