
 Hoist and Winches Market | 2026-2036
Hoist and Winches Market Size, Share, and Industry Trends Forecast 2026-2036
Hoist and Winches Market Outlook
Project finance for port modernization and offshore wind vessel fleets is tilting competitive access toward capital-rich equipment suppliers. Konecranes leverages its integrated service network to anchor long-term contracts at container terminals worldwide. Columbus McKinnon Corporation specializes in precision lifting systems for entertainment and industrial staging applications. Ingersoll Rand competes through channel control in energy and mining verticals where pneumatic and electric hoists face extreme duty cycles.
Hoists and winches are mechanical or electro-mechanical lifting and pulling devices rated by load capacity, line speed, and duty cycle classification, designed to raise, lower, or horizontally move materials across industrial, marine, and construction environments. Electric hoists dominate installed base volumes due to their compatibility with automated material handling systems and variable-frequency drive controls. Heavy-duty and ultra-heavy-duty capacity segments command the strongest margin pools, particularly in offshore energy and shipyard applications where failure tolerance approaches zero. The marine end-user segment shows the fastest structural expansion, driven by vessel fleet renewal and subsea installation activity.
FAA crane safety protocols, OSHA hoist inspection mandates, and EU Machinery Directive compliance requirements collectively elevate product certification costs and extend vendor qualification timelines for North American and European market access. China's SAMR enforces GB standards that foreign manufacturers must meet for domestic project participation, creating parallel certification tracks. Stakeholders must monitor how carbon-border adjustments and embodied-emissions tracking reshape sourcing decisions for steel-intensive lifting equipment.
Market Dynamics
Offshore wind turbine scaling is forcing marine winch manufacturers to reengineer load-bearing architectures as single-unit nacelle weights exceed 500 metric tons, compressing supplier qualification cycles and concentrating procurement among certified heavy-lift specialists.
Growth Catalysts
- EU Machinery Directive 2006/42/EC amendments:Mandatory functional safety upgrades for lifting equipment are accelerating replacement cycles in German automotive assembly plants and Dutch shipyards.
- Subsea cable installation:Burgeoning interconnector projects across the North Sea are pulling specialized tension-controlled winch systems into fleet expansion budgets.
- Carbon steel supply concentration:Proximity to integrated mills in China's Hebei province is lowering fabrication costs for export-oriented hoist manufacturers serving Southeast Asian infrastructure markets.
Market Restraints
- High-strength alloy price volatility:Nickel and molybdenum input swings are compressing margin predictability for ultra-heavy-duty capacity segment producers.
- Single-source bearing supply:Precision slew bearings for offshore cranes concentrate among three European specialty manufacturers, creating vulnerability in vessel delivery timelines.
- Electrification substitution:Hydraulic winch architectures face displacement risk in port applications where shore-power compatibility mandates favor all-electric drive trains.
Strategic Opportunities
- India's port privatization wave:Jawaharlal Nehru Port Trust modernization and Adani Group terminal expansions are opening specification windows for automated container handling systems.
- Condition monitoring convergence:IoT sensor fusion with predictive maintenance algorithms is enabling servitization models that capture lifetime value from offshore vessel operators.
- US Inflation Reduction Act offshore wind credits:Domestic content bonuses are incentivizing local assembly of marine winch systems for Jones Act-compliant installation vessels.
Industry Challenges
- Weld procedure qualification bottlenecks:Offshore certification societies demand traceable welder continuity records that extend fabrication timelines for heavy-lift components.
- Legacy crane control integration:Retrofitting variable-frequency drives into 1980s-era hoist installations requires custom engineering that fragments vendor standardization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hoist and Winches Market |
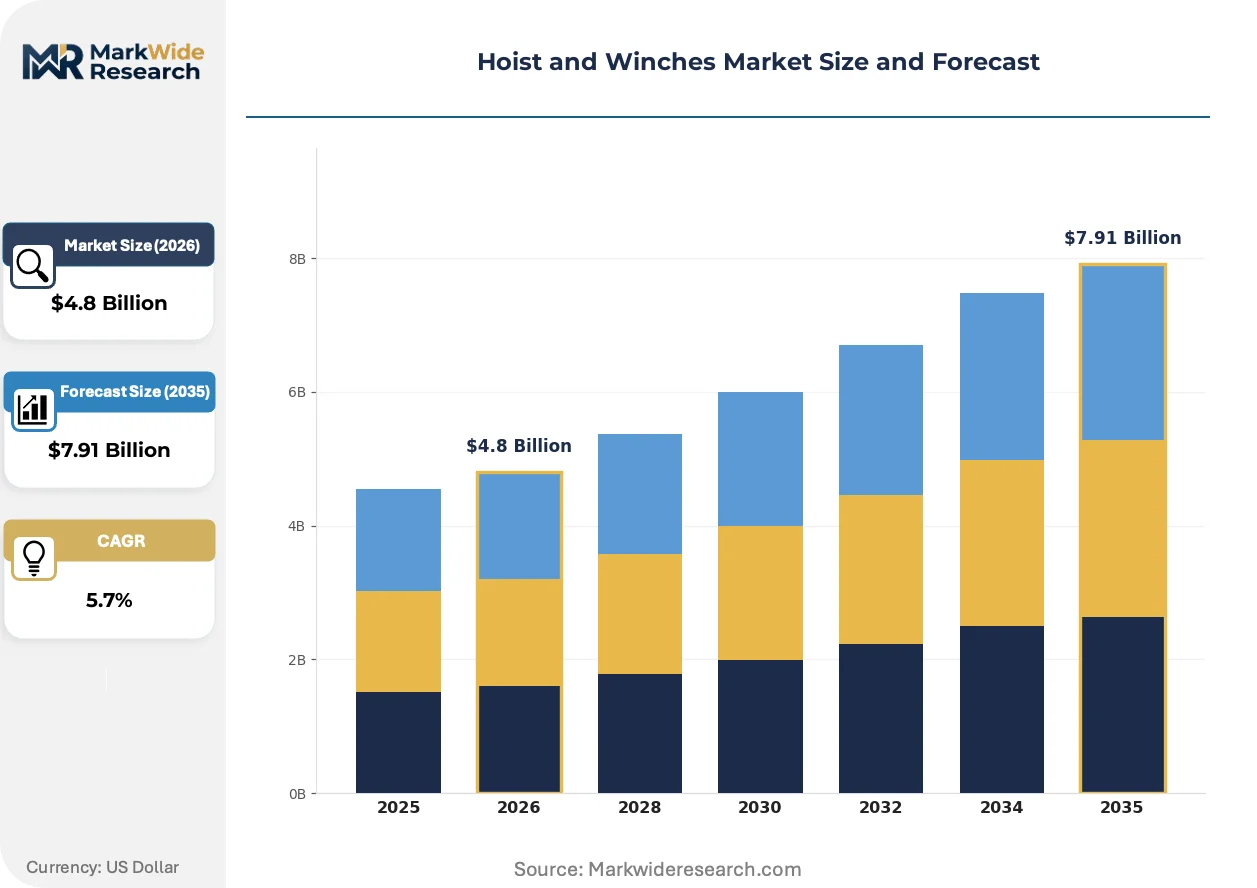
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Hoists, Manual Hoists, Air Hoists, Winches End User: Construction, Marine, Manufacturing, Entertainment Technology: Electric, Hydraulic, Pneumatic, Mechanical Capacity: Light Duty, Medium Duty, Heavy Duty, Ultra Heavy Duty |
| Companies Covered | Konecranes, Columbus McKinnon Corporation, Terex Corporation, Ingersoll Rand, Mitsubishi Electric, Hitachi, Demag Cranes & Components, ABUS Kransysteme GmbH, Donati Sollevamenti Srl, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hoist and Winches Market Strategic Shifts
Digital thread integration across design, manufacturing, and field service is collapsing information latency in heavy-lift equipment supply chains, enabling real-time load monitoring that shifts competitive advantage toward data-fluent suppliers.
Variable-frequency drive technology paired with permanent magnet motors is digitizing torque control precision in electric hoists. Container terminal operators in Singapore and Rotterdam are specifying these systems for automated stacking cranes. The technology is digitizing maintenance scheduling by embedding motor health telemetry directly into port operating systems.
China's SAMR enforcement of updated GB/T 30024 standards for crane safety is mandating redundant braking systems and load moment limiters on all new installations. Domestic manufacturers in Jiangsu and Zhejiang provinces are absorbing certification costs to maintain project eligibility. Foreign suppliers face parallel testing tracks that extend market entry timelines by eight to fourteen months.
Buyers are unbundling aftermarket service contracts from initial equipment procurement in offshore energy applications. Norwegian and UK North Sea operators now separate maintenance provision from capital expenditure, creating standalone service competitions that favor regional technical centers over manufacturer-tied arrangements. This pattern is most pronounced in floating wind pre-installation campaigns where vessel downtime costs exceed equipment capital by an order of magnitude.
Hoist and Winches Market Segmentation
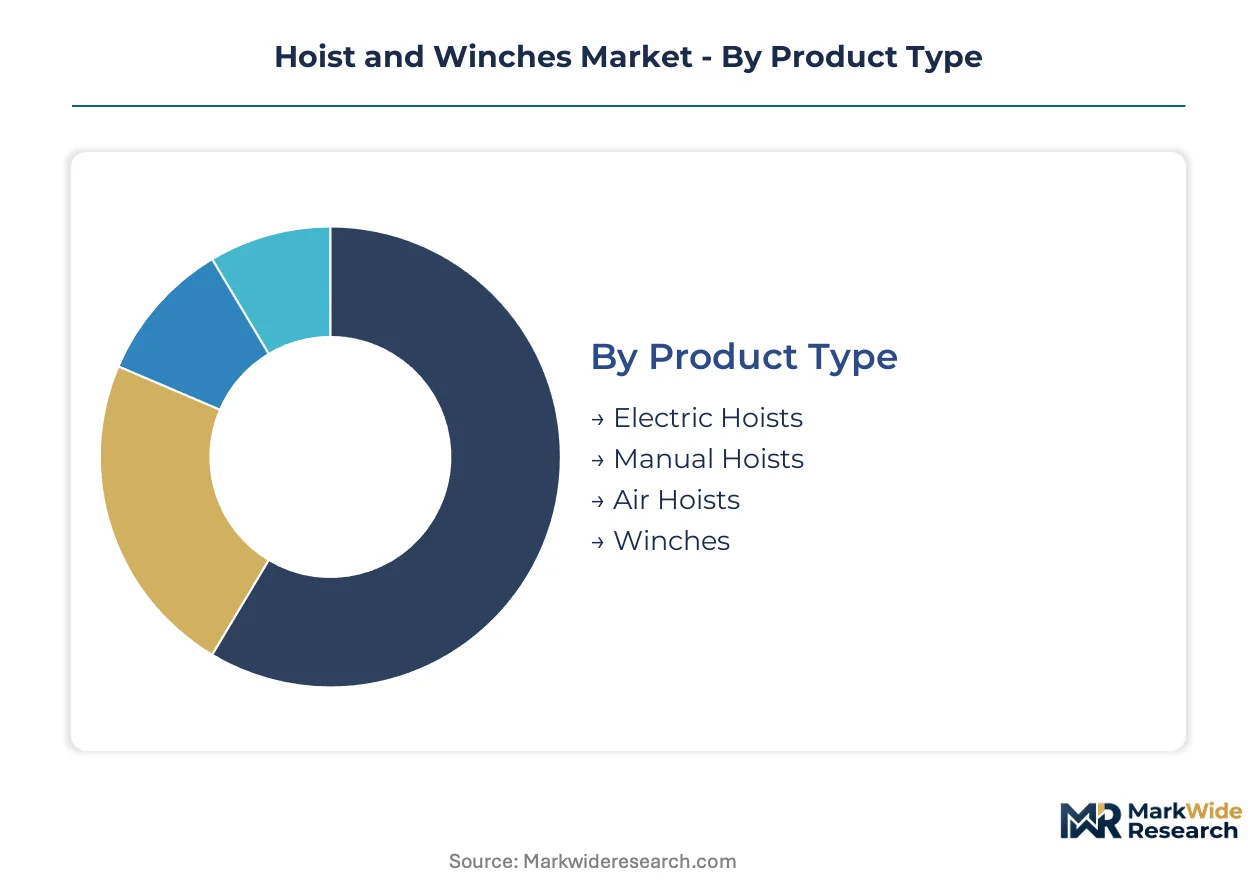
Segmentation in the hoist and winches market reveals divergent margin structures across power transmission architectures and duty cycle classifications. Procurement patterns cluster around specific end-use certification requirements that reshape vendor qualification pathways.
Product Type:
Mature electric architectures dominate installed volumes while pneumatic and manual systems occupy specialized niches with distinct total-cost profiles.
- Electric Hoists:Variable-frequency drive compatibility positions these systems at the core of automated material handling integration. German automotive assembly plants and Dutch port terminals specify these for synchronized crane operations where precision positioning reduces cycle times.
- Manual Hoists:Ratchet and lever mechanisms serve maintenance bays and confined-space construction where power infrastructure is absent. Demand concentrates in India's infrastructure corridor where electrification gaps persist at remote bridge and dam sites.
- Air Hoists:Spark-resistant operation suits explosive atmosphere applications in petrochemical maintenance.
- Winches:Drum-based pulling systems anchor marine and subsea deployment with tension-controlled line management.
Electric Hoists retain volume leadership; Winches hold the steepest expansion curve.
End User:
Application intensity varies dramatically across sectors, with offshore energy and container logistics driving specification upgrades while entertainment staging creates bespoke engineering demands.
- Marine:Heavy-lift winch systems for offshore wind turbine installation command premium positioning as nacelle weights exceed 500 metric tons. Norwegian and UK North Sea operators require redundant braking architectures certified by DNV for floating foundation deployment.
- Construction:Tower crane hoists and material hoists face cyclical replacement tied to building permit volumes. China's urban renewal programs in Jiangsu province sustain demand for medium-duty electric units on high-rise residential projects.
- Manufacturing:Overhead crane systems in Germany's industrial corridor serve automotive and heavy machinery production with synchronized multi-crane operations.
- Entertainment:Precision lifting for concert staging and theatrical rigging demands silent operation and millimeter-accurate positioning control.
Marine applications capture the fastest margin expansion; Construction maintains the broadest installed base.
Technology:
Power transmission selection hinges on duty cycle severity, environmental exposure, and shore-power compatibility mandates reshaping port equipment specifications.
- Electric:Permanent magnet motor architectures digitize torque control for automated stacking cranes in Singapore and Rotterdam terminals. Motor health telemetry embeds directly into port operating systems, collapsing maintenance scheduling latency.
- Hydraulic:High-force density suits extreme duty cycles in mining and offshore pipelaying where mechanical advantage outweighs efficiency losses. Shore-power compatibility mandates in EU ports are displacing these architectures in new container handling procurements.
- Pneumatic:Compressed air systems persist in explosive atmosphere applications and mining verticals where electrical ignition risks dominate safety protocols.
- Mechanical:Gear and brake assemblies serve manual override functions and legacy crane retrofits where control system integration costs prohibit full electrification.
Electric systems anchor new procurement volumes; Hydraulic faces selective displacement in coastal applications.
Capacity:
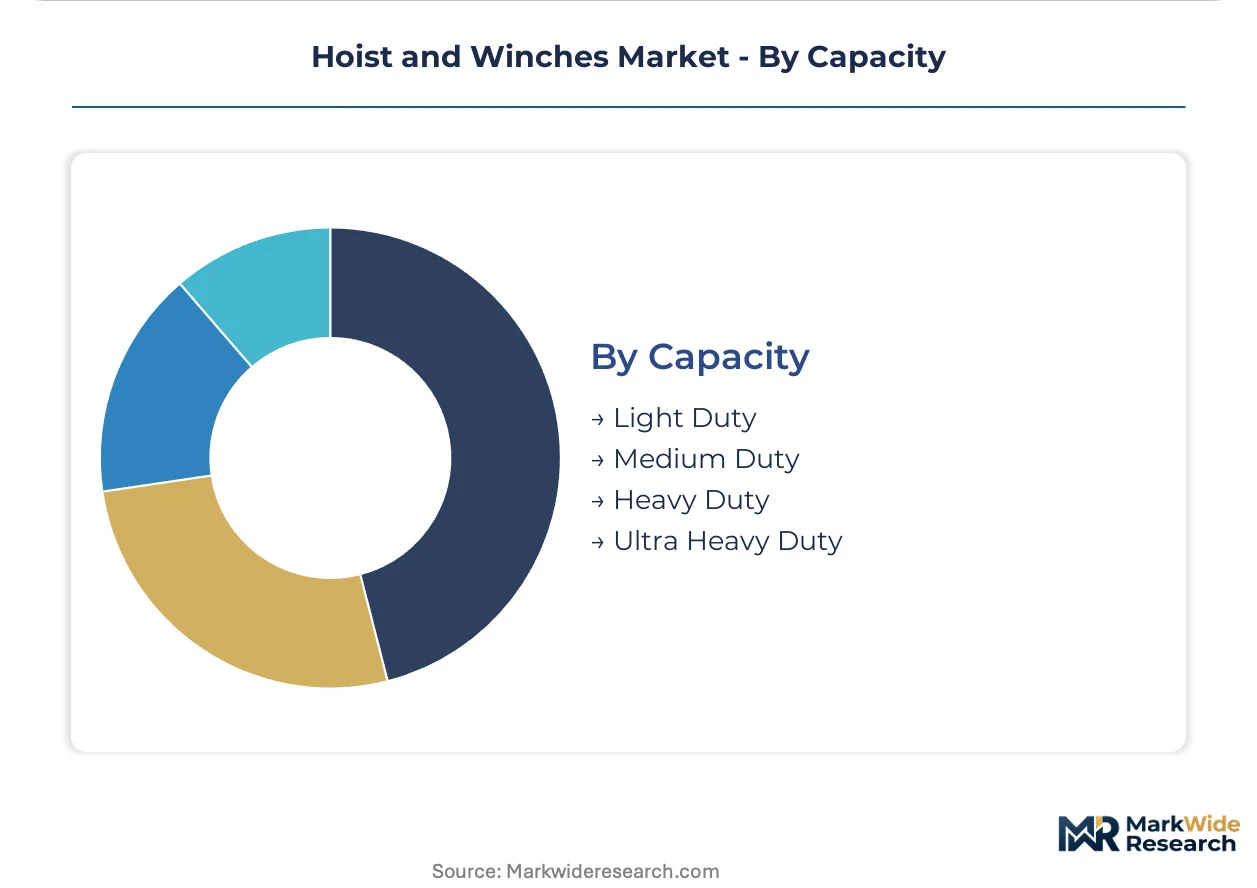
Load rating stratification concentrates margin pools at the extreme duty end where failure tolerance approaches zero and certification burdens filter supplier participation.
- Heavy Duty:50-500 metric ton capacity segments serve shipyard gantry cranes and offshore construction vessels. German and South Korean yards specify these for liquefied natural gas carrier module assembly where weld traceability extends fabrication timelines.
- Ultra Heavy Duty:Above-500-ton systems for floating wind turbine installation command the strongest margin pools. Single-source bearing supply from European specialty manufacturers creates procurement bottlenecks in vessel delivery schedules.
- Medium Duty:10-50 ton ratings dominate general manufacturing and warehouse applications with standardized maintenance protocols.
- Light Duty:Below-10-ton units serve workshops, maintenance bays, and small-scale construction with minimal regulatory burden.
Heavy Duty retains procurement value concentration; Ultra Heavy Duty exhibits the most acute supply-side scarcity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Port operators and offshore wind developers concentrate procurement in industrial corridors with dense crane installations and marine fabrication capacity. Regional demand patterns track vessel fleet renewal cycles, port privatization waves, and domestic content requirements for renewable energy infrastructure.
Germany
Automotive assembly plants in Stuttgart and Wolfsburg sustain dense overhead crane networks requiring synchronized multi-hoist operations. OSHA-aligned EU Machinery Directive amendments mandate functional safety upgrades, accelerating replacement cycles at BMW and Mercedes-Benz facilities. The industrial corridor between Cologne and Dortmund anchors heavy machinery production with integrated service contracts.
China
Urban renewal programs in Jiangsu province drive demand for medium-duty electric hoists on high-rise residential construction. SAMR enforcement of updated GB/T 30024 standards requires redundant braking systems, extending certification timelines for foreign suppliers. Hebei province's integrated steel mills supply fabrication inputs for export-oriented hoist manufacturers serving Southeast Asian infrastructure markets.
United States
Jones Act-compliant offshore wind installation vessels trigger domestic assembly requirements for marine winch systems under Inflation Reduction Act credits. FAA crane safety protocols and OSHA hoist inspection mandates elevate certification costs for port equipment modernization. Gulf Coast shipyards and East Coast container terminals concentrate procurement for heavy-lift capacity expansion.
India
Jawaharlal Nehru Port Trust modernization and Adani Group terminal expansions open specification windows for automated container handling systems. BIS certification requirements filter vendor participation in public infrastructure tenders. Maharashtra and Gujarat industrial zones sustain workshop-grade manual hoist demand where electrification gaps persist at remote construction sites.
Norway
Floating wind pre-installation campaigns in the North Sea generate demand for DNV-certified redundant braking architectures on heavy-lift winches. Norwegian operators unbundle aftermarket service contracts from capital expenditure, favoring regional technical centers over manufacturer-tied arrangements. Subsea cable interconnector projects pull specialized tension-controlled systems into fleet expansion budgets.
Hoist and Winches Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market positions. Consolidation concentrates among capital-rich suppliers capable of financing port modernization and offshore wind vessel fleets under long-term service contracts. Three archetypes dominate: integrated port terminal solution providers, precision lifting specialists for entertainment and staging applications, and energy-vertical channel controllers. Competitive moves center on geographic expansion through regional technical centers and portfolio diversification into predictive maintenance servitization models.
Within the integrated service tier, Konecranes anchors long-term container terminal contracts through its worldwide maintenance network. Columbus McKinnon Corporation exemplifies the precision-specialist archetype for industrial staging and entertainment rigging applications. Ingersoll Rand occupies the energy-vertical channel control position, competing through distribution strength in mining and extreme duty cycle environments.
| Leading Market Players |
|---|
| Konecranes |
| Columbus McKinnon Corporation |
| Terex Corporation |
| Ingersoll Rand |
| Mitsubishi Electric |
| Hitachi |
| Demag Cranes & Components |
| ABUS Kransysteme GmbH |
| Donati Sollevamenti Srl |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Rotterdam maritime corridor's freight cost volatility feeds directly into supply concentration among Hebei province steel mills and downstream price differentiation between certified heavy-lift specialists and commodity hoist suppliers. Buyers absorb carbon steel input swings through cost-plus contracts indexed to London Metal Exchange nickel and molybdenum benchmarks, while procurement officers at German automotive plants and Norwegian offshore vessel operators negotiate fixed-price multi-year service bundles that decouple hardware margins from raw material cycles.
Pricing Analysis
Cost-plus contracts with LME-indexed alloy surcharges dominate ultra-heavy-duty marine winch procurement, separating DNV-certified suppliers from uncertified competitors through weld traceability premiums and redundant braking architecture markups. Price differentiation rests on certification tier and after-sales service bundling, with Norwegian floating wind operators paying service-attach premiums exceeding hardware base costs. Cost compression in medium-duty electric hoists intensifies as Jiangsu province manufacturers absorb GB/T 30024 certification expenses to maintain domestic eligibility. Workshop-grade manual hoist buyers in India's Maharashtra industrial zones exhibit highest price sensitivity, while North Sea offshore vessel operators demonstrate lowest sensitivity due to vessel downtime costs dwarfing equipment capital.
Supply Chain Analysis
Tariff exposure between China and Southeast Asian infrastructure markets dominates procurement risk calculus for export-oriented hoist manufacturers dependent on Hebei province integrated mills. Supply concentrates in China, Germany, and South Korea, drawing from high-strength alloy steel, precision slew bearings, and permanent magnet motor windings. Single-source vulnerability in European specialty bearing manufacturers creates vessel delivery timeline fragility for ultra-heavy-duty capacity segments. Distribution runs through OEM-direct contracts for port terminal operators and regional technical service centers for offshore energy applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market structures around predictive maintenance servitization expanding faster than hardware replacement cycles, with Norwegian and UK North Sea operators unbundling aftermarket contracts from capital expenditure and creating standalone service competitions. Condition monitoring convergence enables lifetime value capture that shifts competitive advantage toward data-fluent suppliers.
For Market Incumbents: Harden certification investment in EU Machinery Directive functional safety upgrades and DNV redundant braking architectures to filter commodity competition from ultra-heavy-duty marine winch procurement. Deepen backward integration into precision slew bearing supply relationships or captive weld procedure qualification capacity to compress fabrication timelines threatened by single-source European bearing manufacturers. Anchor long-term port terminal contracts through integrated service networks that embed IoT sensor fusion and collapse maintenance scheduling latency. For New Entrants and Emerging Players: Pursue India's Jawaharlal Nehru Port Trust modernization and Adani Group terminal expansions as the most penetrable specification windows for automated container handling systems. Target workshop-grade manual hoist demand in Maharashtra and Gujarat industrial zones where electrification gaps persist and BIS certification burdens filter established foreign competitors. Enter through regional technical center partnerships that unbundle service provision from manufacturer-tied arrangements, mirroring Norwegian floating wind procurement patterns. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with undermonetized aftermarket service networks and stranded precision lifting capabilities in entertainment staging applications. Long-term viability over the next decade hinges on servitization model execution and carbon-border adjustment compliance for steel-intensive fabrication. Watch Jones Act domestic content bonus utilization rates as the inflection signal for US offshore wind marine winch assembly economics.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Servitization | IoT sensor fusion enables lifetime value capture from Norwegian floating wind vessel operators. |
| Backward Integration into Bearing Supply | Captive precision slew bearing sourcing compresses fabrication timelines for ultra-heavy-duty marine winches. |
| Regional Technical Center Expansion | Unbundled service contracts favor regional technical centers over manufacturer-tied arrangements in North Sea markets. |
| GB/T 30024 Certification Investment | Redundant braking system compliance maintains project eligibility in China's urban renewal programs. |
| Jones Act Domestic Assembly | Inflation Reduction Act credits incentivize local marine winch assembly for US offshore wind vessels. |
Study Parameters
Desk research of customs/trade data, SEC filings from listed equipment manufacturers, and DNV certification registries preceded structured interviews with maintenance directors at German automotive plants, offshore vessel fleet managers in Norway, port terminal procurement officers in Singapore and Rotterdam, and aftermarket service heads at integrated crane solution providers. Primary fieldwork combined with secondary validation against EU Machinery Directive amendment filings and SAMR GB standards enforcement records. Bottom-up equipment shipment analysis triangulated against top-down port modernization budget disclosures and offshore wind vessel fleet expansion plans.
Forecast assumptions held fixed the EU Machinery Directive compliance timeline and China's dual carbon goals enforcement intensity while varying offshore wind turbine scaling trajectories and nickel-molybdenum alloy price corridors across the projection horizon. The analytical framework modeled segmentation across power transmission architecture, duty cycle classification, end-use certification requirements, and regional port privatization waves. CAGRs derived from equipment replacement cycle analysis, vessel fleet renewal schedules, and infrastructure investment pipeline tracking. Industry-specific inputs included DNV certification queue lengths and Jones Act vessel construction timelines.
Sensitivities concentrate around carbon-border adjustment implementation scope for steel-intensive fabrication and floating wind turbine nacelle weight trajectories exceeding current winch load-bearing architectures. Forecasts reflect documented assumptions regarding EU Machinery Directive amendment adoption rates and SAMR enforcement consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Grader Blades Market
Construction Equipment
Europe Crane Market
Construction Equipment
Electrofusion Welding Machines Market
Construction Equipment
Middle East and Africa Rough Terrain Cranes Market
Construction Equipment
Tunneling Equipment Market
Construction Equipment
Construction Camera [Time Lapse Camera] Market
Construction Equipment
Construction Pump Market
Construction Equipment
Construction Site Preparation Equipment Market
Construction Equipment
Wheeled Excavators Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Commercial Sanitizing Equipment Market
Construction Equipment
Latin America Heavy Construction Equipment Market
Construction Equipment
Overhead Cranes Market
Construction Equipment
Rotary Blasthole Drilling Rig Market
Construction Equipment
Global Scaffolding Market
Construction Equipment
Laser Welding Equipment Market