
 Global CNC Tool and Cutter Grinding Machine Market | 2026-2036
Global CNC Tool and Cutter Grinding Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Global CNC Tool and Cutter Grinding Machine Market Analysis
Polycrystalline diamond is decoupling tool life economics from traditional carbide benchmarks in aerospace finishing applications. Walter Maschinenbau leverages its Swabian manufacturing base to dominate multi-axis universal grinder supply for European automotive transmission producers. ANCA specializes in software-driven tool geometry correction systems that sustain premium positioning across medical and defense contractor accounts. Junker Group anchors high-volume production grinding through rotary transfer integration with German OEM camshaft lines.
CNC tool and cutter grinding machines are precision metalworking equipment utilizing computer-numerical control to execute complex tool geometry corrections on cutting inserts, drills, end mills, and reamers with sub-micron positional accuracy. These systems employ direct-drive torque motor rotary tables and hydrostatic bearing spindles to maintain thermal stability during extended ceramic and superabrasive wheel operations. CNC tool grinders capture the dominant margin pool as aerospace and medical buyers prioritize unmanned lights-out capability over manual or semi-automated alternatives. Robotic grinding is accelerating within large-scale production environments where automotive powertrain plants integrate tool grinding cells directly into central tool management systems.
ISO 230 machine tool test codes, EPA metalworking effluent limitations under the Clean Water Act, and EU machinery directives with CE marking requirements collectively elevate capital equipment compliance costs while filtering out lower-tier suppliers. Germany's KBA and Japan's METI both enforce energy efficiency benchmarks that reshape grinder spindle motor and coolant system specifications for export eligibility. Stakeholders must monitor how dual carbon goals in China and evolving EU F-Gas Regulation restrictions on fluorinated coolant gases redirect R&D investment toward minimum-quantity lubrication and dry grinding architectures.
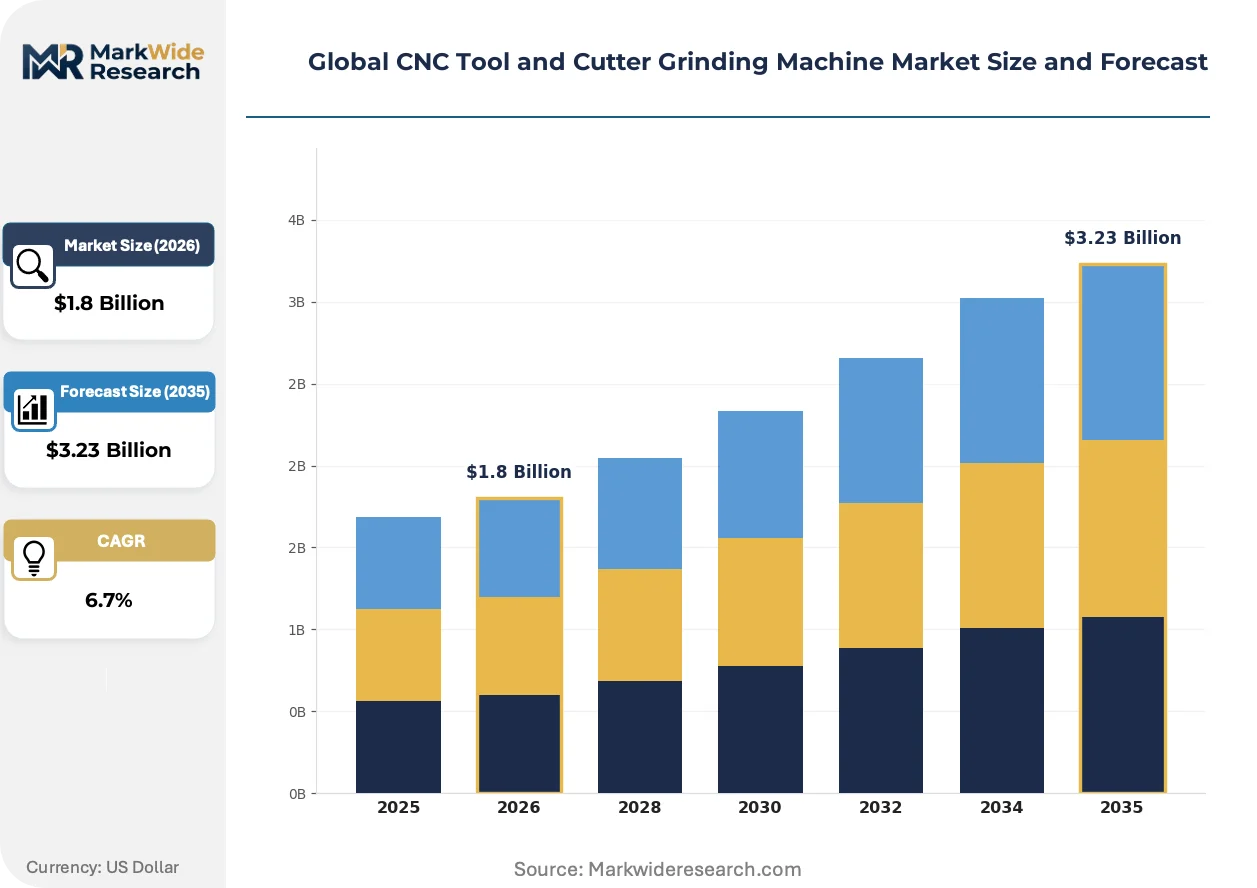
Market Dynamics
Polycrystalline diamond tooling economics are compressing traditional carbide replacement cycles across aerospace finishing operations, forcing grinder manufacturers to reconfigure wheel dressing systems and thermal management architectures for superabrasive processing.
Growth Catalysts
- Aerospace titanium machining:German, Japanese, and US airframe producers are expanding precision grinding capacity for heat-resistant superalloy tooling. This generates demand for multi-axis universal grinders with direct-drive torque motor tables.
- ISO 230 machine tool test codes:International standardization of volumetric positioning accuracy is elevating equipment specifications. Buyers now specify sub-micron repeatability as a baseline procurement criterion.
- Baden-Württemberg machining cluster concentration:Germany's automotive transmission corridor anchors high-volume tool grinding cell deployment. Local OEMs integrate grinding operations directly into central tool management systems.
Market Restraints
- Fluorinated coolant gas restrictions:EU F-Gas Regulation is phasing down hydrofluorocarbon-based metalworking fluids. This forces capital expenditure on minimum-quantity lubrication retrofits or dry grinding architectures.
- Superabrasive wheel supply concentration:Synthetic diamond and cubic boron nitride wheel production concentrates among Japanese and US suppliers. Geopolitical friction exposes European grinder OEMs to input cost volatility and delivery uncertainty.
- Energy efficiency benchmarking:Germany's KBA and Japan's METI enforce export eligibility standards for spindle motor power density. Compliance redesign consumes engineering resources without immediate revenue recovery.
Strategic Opportunities
- Medical device tooling corridors:Swiss and German orthopedic implant manufacturers require certified grinding processes for cobalt-chrome and ceramic cutting instruments. Regulatory tailwinds from EU MDR create captive demand for validated equipment.
- Robotic grinding cell integration:Automotive powertrain plants in the US Great Lakes manufacturing belt are deploying unmanned lights-out grinding cells. This converges CNC tool grinders with collaborative robot loading systems.
- Dual carbon goals in China:Beijing's emissions intensity targets are accelerating domestic demand for energy-efficient grinding spindles. Local machine tool builders seek European and Japanese technology licensing to meet new MEE efficiency mandates.
Industry Challenges
- Mechatronics technician scarcity:Hydrostatic bearing spindle maintenance and direct-drive rotary table calibration require specialized skills. German and Japanese grinder manufacturers report extended commissioning timelines due to qualified field service engineer shortages.
- CE marking documentation burden:EU machinery directives demand extensive technical file preparation for multi-axis safety systems. Smaller grinder builders face compliance timeline compression that delays market entry.
- Legacy CAM software integration:Tool geometry correction algorithms must interface with existing shop floor programming environments. Aerospace contractors resist grinding cell purchases that require parallel CAM system investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CNC Tool and Cutter Grinding Machine Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Universal Tool Grinders, CNC Tool Grinders, Angle Grinders, Sharpening Machines Technology: Automated Grinding, Manual Grinding, Robotic Grinding, High-Speed Grinding End User: Aerospace, Automotive, Industrial Manufacturing, Metalworking Size: Small-Scale, Medium-Scale, Large-Scale, High-Production |
| Companies Covered | Walter Maschinenbau, Junker Group, ANCA, Gleason, Vollmer, Makino, Rollomatic, Star Cutter, Okuma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CNC Tool and Cutter Grinding Machine Market Emerging Trajectories
Software-defined tool geometry correction is displacing mechanical compensation methods, while regulatory pressure on metalworking effluents accelerates dry grinding and minimum-quantity lubrication architectures across precision machining corridors.
Adaptive grinding wheel dressing systems are integrating real-time acoustic emission monitoring to optimize superabrasive layer exposure. Aerospace finishing shops in Germany and Japan are deploying these systems to extend polycrystalline diamond wheel life beyond traditional fixed-interval dressing protocols. The technology is integrating unmanned lights-out operation by eliminating operator judgment from wheel conditioning cycles.
EPA metalworking effluent limitations under the Clean Water Act are tightening discharge standards for grinding swarf and coolant mixtures. US-based automotive powertrain plants must now install advanced filtration and coolant recycling systems to maintain operating permits. The regulation most affects high-volume production grinding operations in Michigan and Ohio, where facilities are retrofitting central coolant management infrastructure.
Tool-as-a-service procurement models are emerging among medical device manufacturers seeking to unbundle capital expenditure from consumable tooling programs. Swiss orthopedic implant producers now contract grinding capacity per finished tool rather than purchasing equipment outright. This shift concentrates most visibly in the Jura Arc watchmaking and medical corridor, where specialized grinding houses absorb equipment ownership risk.
Global CNC Tool and Cutter Grinding Machine Market Segmentation
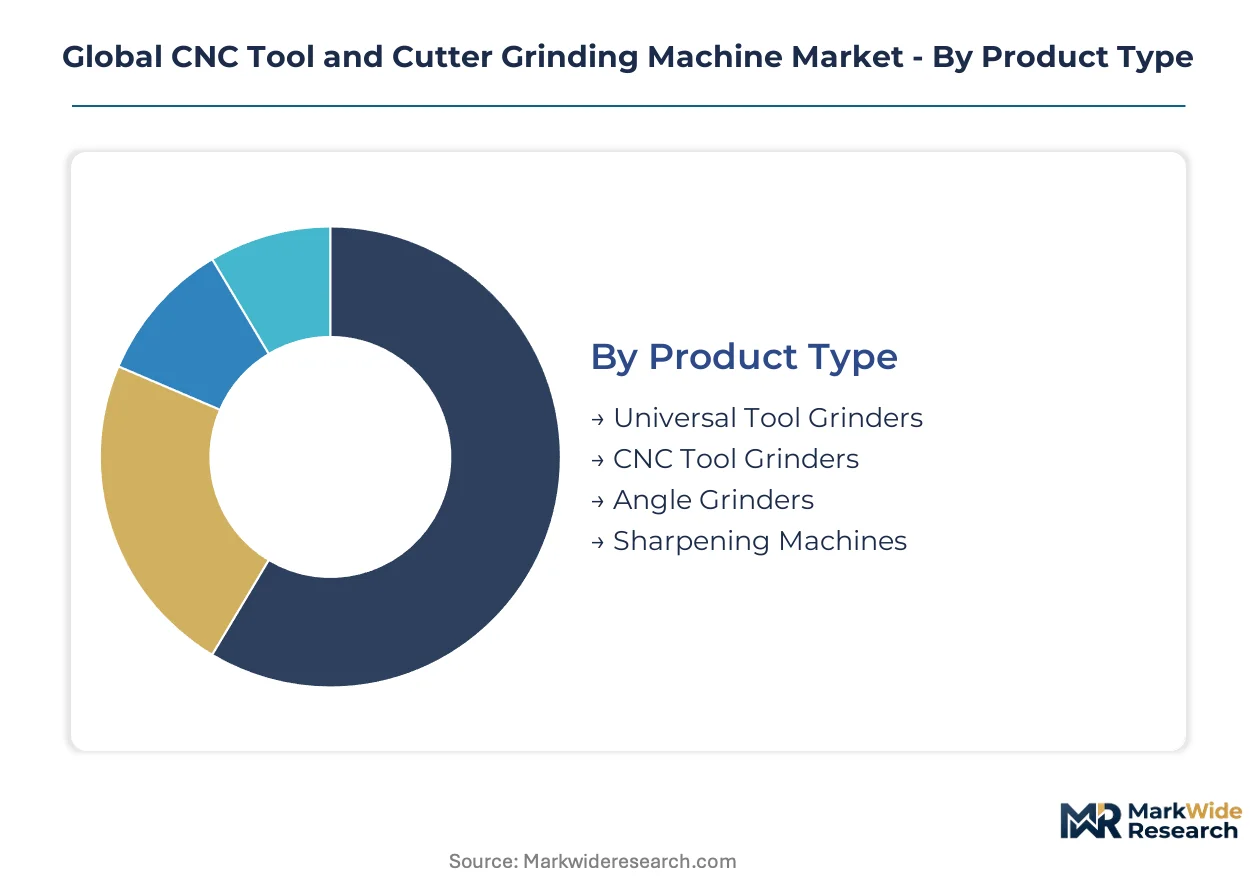
Segmentation in the CNC tool and cutter grinding machine market reveals how equipment specifications diverge across integration architectures. Standalone systems dominate high-mix aerospace tooling, while embedded grinding cells anchor automotive powertrain operations.
Product Type:
Integration depth separates standalone universal platforms from embedded production-line systems, with software sophistication determining placement in centralized tool management architectures.
- Universal Tool Grinders:Multi-axis platforms with direct-drive torque motor rotary tables execute complex geometry corrections on drills, end mills, and reamers. German automotive transmission producers in Baden-Württemberg deploy these as standalone cells integrated into central tool management systems.
- CNC Tool Grinders:Computer-numerical control systems with hydrostatic bearing spindles maintain sub-micron positional accuracy during extended ceramic wheel operations. Aerospace manufacturers in Japan's Aichi Prefecture specify these for unmanned lights-out processing of titanium and superalloy tooling.
- Angle Grinders:Compact units for edge preparation and secondary finishing operations in metalworking shops.
- Sharpening Machines:Entry-level equipment for tool room maintenance and small-batch reconditioning.
Volume placements concentrate in CNC Tool Grinders; the faster expansion belongs to Universal Tool Grinders.
Technology:
Cost tier stratification places robotic and automated systems in premium capital expenditure brackets, while manual grinding persists in cost-sensitive maintenance applications.
- Automated Grinding:Software-driven wheel dressing and thermal compensation architectures process superabrasive materials with minimal operator intervention. US Great Lakes automotive powertrain plants specify these for high-volume production environments with integrated coolant recycling systems.
- Robotic Grinding:Collaborative robot loading systems converge with CNC platforms to enable continuous unmanned operation. Swiss orthopedic implant manufacturers in the Jura Arc corridor deploy these for certified cobalt-chrome and ceramic instrument processing under EU MDR requirements.
- Manual Grinding:Operator-dependent systems retained for specialized prototype work and custom tool geometries.
- High-Speed Grinding:Spindle architectures optimized for reduced cycle times in large-batch manufacturing.
Capital deployment concentrates in Automated Grinding; the steepest expansion trajectory belongs to Robotic Grinding.
End User:
Application-specific requirements drive specification divergence, with aerospace and medical sectors imposing certification burdens that filter supplier participation.
- Aerospace:Heat-resistant superalloy and titanium tooling demands multi-axis platforms with superabrasive wheel compatibility. German, Japanese, and US airframe producers expand precision grinding capacity to support ceramic matrix composite machining programs.
- Automotive:High-volume transmission component production requires rotary transfer integration with OEM camshaft lines. Junker Group anchors this segment through embedded grinding cell deployment in European powertrain plants.
- Industrial Manufacturing:General metalworking operations spanning mold and die production with mixed batch requirements.
- Metalworking:Job shops and contract manufacturers serving diverse end-market tooling needs.
Equipment shipments concentrate in Automotive; the fastest share gain belongs to Aerospace.
Size:
Customer type and facility scale determine equipment footprint, with high-production architectures dominating OEM captive operations and small-scale units serving independent grinding houses.
- Large-Scale:Integrated grinding centers with central coolant management and robotic material handling support continuous production. EPA metalworking effluent limitations under the Clean Water Act drive filtration infrastructure investment in Michigan and Ohio facilities.
- High-Production:Dedicated lines with rotary transfer integration match German OEM specifications for camshaft and crankshaft tool grinding. METI energy efficiency benchmarks reshape spindle motor specifications for Japanese export eligibility.
- Medium-Scale:Flexible cells accommodating batch size variation in industrial manufacturing environments.
- Small-Scale:Compact units for independent tool grinding houses and medical device subcontracting operations.
Installed base concentrates in Large-Scale systems; the quickest climb belongs to High-Production configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision grinding demand concentrates in three industrial corridors: Germany's automotive transmission belt, Japan's aerospace tooling corridor, and the US Great Lakes manufacturing cluster. Equipment specifications diverge sharply across these geographies as national regulators impose distinct energy efficiency and effluent standards.
United States
EPA metalworking effluent limitations under the Clean Water Act are forcing coolant recycling infrastructure investment across Michigan and Ohio automotive powertrain plants. Aerospace contractors in the Pacific Northwest and Southeast are expanding titanium tooling capacity for commercial airframe programs. The Great Lakes manufacturing belt anchors high-volume grinding cell deployment with integrated robotic loading systems.
Germany
Baden-Württemberg's automotive transmission corridor generates sustained demand for multi-axis universal grinders with direct-drive torque motor tables. KBA energy efficiency benchmarks reshape spindle motor specifications for export eligibility. Walter Maschinenbau leverages its Swabian manufacturing base to supply European OEM camshaft grinding lines.
Japan
METI enforces power density standards that filter grinder spindle designs for domestic and export markets. Aichi Prefecture's aerospace tooling corridor concentrates demand for unmanned lights-out processing of heat-resistant superalloy tooling. Synthetic diamond wheel supply relationships with domestic abrasives producers expose grinder OEMs to input cost volatility.
China
MEE efficiency mandates under Beijing's dual carbon goals are accelerating domestic demand for energy-efficient grinding spindles. Local machine tool builders seek European and Japanese technology licensing to meet new emissions intensity targets. Yangtze River Delta manufacturing clusters are retrofitting central coolant management infrastructure.
Switzerland
Swissmedic certification requirements and EU MDR regulatory tailwinds create captive demand for validated grinding processes in the Jura Arc medical corridor. Orthopedic implant manufacturers in the watchmaking belt are adopting tool-as-a-service procurement models. Cobalt-chrome and ceramic cutting instrument production requires certified equipment with documented process validation.
Global CNC Tool and Cutter Grinding Machine Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with premium-tier suppliers capturing margin pools in aerospace and medical applications while volume-oriented fabricators serve automotive powertrain operations. The vendor base organizes around three archetypes: Swabian precision engineering houses, Japanese mechatronics integrators, and software-defined geometry correction specialists. Competitive dynamics center on strategic technology licensing arrangements and embedded grinding cell integration with OEM production lines.
Within the precision engineering tier, Walter Maschinenbau GmbH and Junker Group GmbH exemplify German manufacturing depth. ANCA Pty Ltd represents software-driven tool geometry correction capabilities. Makino Milling Machine Co., Ltd. and Okuma Corporation anchor Japanese spindle and control system integration. Gleason Corporation and Vollmer Werke Maschinenfabrik GmbH occupy positions in gear and circular tool grinding specializations.
| Leading Market Players |
|---|
| Walter Maschinenbau |
| Junker Group |
| ANCA |
| Gleason |
| Vollmer |
| Makino |
| Rollomatic |
| Star Cutter |
| Okuma |
| Others |
Supply Flow & Price Mechanics
Automotive powertrain OEMs in Germany's Baden-Württemberg corridor anchor volume procurement, locking in contract-based long-term offtake agreements that compress margins for standard-configuration grinders while preserving premium pricing for ISO 230-certified systems with documented sub-micron repeatability.
Pricing Analysis
Volume placements concentrate in mid-tier automated grinding platforms serving automotive transmission producers, while margin pools accrue to robotic grinding cells with integrated collaborative loading systems for aerospace and medical applications. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked multi-axis systems with full technical documentation from stripped configurations for emerging market buyers. Cost compression in standard-tier equipment is intensifying because Chinese machine tool builders are licensing European spindle technology to meet MEE efficiency mandates. Job shops and independent grinding houses exhibit highest price sensitivity; aerospace contractors with captive tool management systems show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and US suppliers of synthetic diamond and cubic boron nitride grinding wheels, exposing European grinder OEMs to input cost volatility when geopolitical friction disrupts abrasives trade flows. Superabrasive wheel production concentrates in Japan and the United States, while hydrostatic bearing spindle assemblies draw from German and Swiss precision engineering clusters. Supply chain risk centers on regulatory restriction as EU F-Gas Regulation phases down hydrofluorocarbon-based metalworking fluids, forcing coolant system redesigns. Distribution runs through OEM-integrated grinding cell deployment for automotive powertrain plants and specialized machine tool distributors serving aerospace and medical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EU machinery directives with CE marking requirements and EPA metalworking effluent limitations create barrier-to-entry moats that filter out undercapitalized competitors and consolidate share among documentation-capable incumbents.
For Market Incumbents: Anticipate margin pressure from Chinese machine tool builders acquiring European spindle technology through licensing agreements rather than direct competition. Prioritize backward integration into superabrasive wheel supply relationships to reduce exposure to Japanese and US abrasives concentration. Invest in minimum-quantity lubrication and dry grinding architectures ahead of tightening EU F-Gas Regulation enforcement. For New Entrants and Emerging Players: Enter via software-defined tool geometry correction capabilities that interface with existing aerospace CAM environments, avoiding the capital intensity of mechanical platform manufacturing. Target medical device tooling corridors in Switzerland and Germany where EU MDR regulatory tailwinds create captive demand for validated equipment with documented process verification. Pursue tool-as-a-service procurement models to unbundle capital expenditure for orthopedic implant manufacturers. For Investors and Strategic Acquirers: The window for entry favors precision engineering specialists with embedded grinding cell integration capabilities and established OEM relationships in automotive powertrain. Long-term viability hinges on regulatory compliance infrastructure rather than pure manufacturing scale. Monitor METI and KBA energy efficiency benchmark evolution as inflection indicator for spindle technology obsolescence risk.| Strategic Initiative | Industry Significance |
|---|---|
| Minimum-Quantity Lubrication Retrofit | EU F-Gas Regulation compliance protects market access for European grinder OEMs. |
| Software-Defined Geometry Correction | ANCA-type algorithmic positioning sustains premium pricing in medical and defense accounts. |
| Robotic Grinding Cell Integration | US Great Lakes automotive plants demand unmanned lights-out processing capability. |
| Superabrasive Wheel Supply Agreement | Japanese abrasives concentration creates vulnerability for European grinder manufacturers. |
| Dual Carbon Spindle Development | MEE efficiency mandates in China open technology licensing revenue streams. |
Methodological Framework
Document review covered SEC filings from precision machine tool manufacturers, METI energy efficiency benchmark disclosures, and EU machinery directive technical documentation, complemented by interviews with plant engineers at German automotive transmission producers, aerospace tooling procurement managers in Japan's Aichi Prefecture, and aftermarket service heads at Swiss orthopedic implant manufacturers. Secondary validation drew from ISO 230 machine tool test code publications, EPA Clean Water Act effluent limitation records, and customs trade data for grinding machine imports. Bottom-up equipment shipment analysis triangulated against top-down market sizing from OEM production capacity announcements.
Segment-level outputs across the analysis window reflect modeled projections for universal tool grinders, CNC tool grinders, and robotic grinding platforms by technology tier, end-use vertical, and geographic production cluster. CAGRs were derived from regression analysis of historical shipment data against aerospace titanium machining program announcements and automotive powertrain capital expenditure cycles. Industry-specific forecast inputs included KBA and METI energy efficiency compliance timelines and EU MDR medical device certification requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated EU F-Gas Regulation enforcement or disruption to Japanese superabrasive wheel supply chains. Aerospace program delays or automotive powertrain electrification shifts could revise equipment demand assumptions materially. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Global Welding Market
Construction Equipment
Field Marking Equipment Market
Construction Equipment
Earthmoving Equipment Market
Construction Equipment
Cable Winches Market
Construction Equipment
CNC Machine Market
Construction Equipment
Thermal Spray Equipment Market
Construction Equipment
Screw Compressor Rental Market
Construction Equipment
Hoist and Winches Market
Construction Equipment
Electric and Hybrid Construction Equipment Market
Construction Equipment
Cement Consistometer Market
Construction Equipment
Pipe Manufacturing Machines Market
Construction Equipment
Radial Drilling Machine Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
India Crane Market
Construction Equipment
Asia Pacific Construction Equipment Market
Construction Equipment
Hand Push Trencher Market