
 Global IoT in Construction Market | 2026-2036
Global IoT in Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Global IoT in Construction Market Intelligence
The shift from centralized, proprietary hardware to open, software-defined sensor networks is fragmenting the traditional value chain for construction site monitoring. Siemens Smart Infrastructure leverages its deep building automation expertise to offer integrated platforms for large commercial projects. In contrast, specialists like Pulse IoT Technologies and InstaDigin compete by offering modular, use-case-specific solutions for equipment tracking and safety monitoring. Honeywell extends its industrial control systems legacy into connected construction applications.
Internet of Things (IoT) in construction involves deploying a network of interconnected sensors, trackers, and wearable devices on job sites. These devices often utilize low-power wide-area network (LPWAN) protocols to transmit data on equipment status, environmental conditions, and worker location. The primary purpose is to collect real-time data for improved safety, efficiency, and project management. Within the use cases, equipment management and safety monitoring constitute the most mature applications. Solutions for predictive maintenance represent the fastest-growing segment, driven by contractor focus on minimizing asset downtime.
Data governance frameworks like Europe's GDPR impose strict requirements on handling worker location and biometric data collected by wearables. In the United States, OSHA guidelines influence the adoption of safety monitoring technologies to prevent workplace accidents. Concurrently, ISO standards for asset management provide a framework for integrating IoT data into operational workflows. The critical decision for contractors is how to integrate disparate data streams from multiple IoT solutions into a single, actionable project dashboard.
Market Dynamics
The central dynamic shaping the market is the technical and commercial friction involved in integrating siloed data streams. While individual IoT solutions for tracking or safety are mature, the primary challenge for contractors is aggregating this disparate information from multiple vendors into a unified, actionable project management dashboard.
Growth Catalysts
- Widespread 5G Deployment:The expansion of 5G networks provides the high-bandwidth, low-latency connectivity required to support real-time data transmission from thousands of sensors, wearables, and drones on large-scale construction sites.
- Safety Regulation Enforcement:Mandates from bodies like the U.S. Occupational Safety and Health Administration (OSHA) create direct demand for IoT-based safety monitoring systems, including geofencing and worker alert wearables, to reduce accidents.
- Infrastructure Project Scale:Developers of large civil and commercial projects are adopting IoT to gain visibility over complex logistics, monitor high-value asset utilization, and control costs, which are difficult to manage with manual methods.
Market Restraints
- High Initial Investment:The significant upfront capital expenditure for purchasing sensors, gateways, networking hardware, and sophisticated software platforms presents a major barrier for small to medium-sized construction firms.
- Lack of Interoperability:Proprietary protocols and data formats from different IoT vendors result in data silos, preventing seamless integration and creating a fragmented view of site operations for project managers.
- Data Privacy Regulations:Strict data governance frameworks, notably Europe's GDPR, impose limitations on the collection and processing of personal data, such as worker location and biometric information from wearables.
Strategic Opportunities
- Predictive Maintenance Services:A significant opportunity exists in developing advanced analytics platforms that use sensor data to predict equipment failure, allowing contractors to shift from reactive repairs to proactive maintenance schedules.
- Integration with BIM:Converging real-time IoT data with Building Information Modeling (BIM) enables the creation of dynamic digital twins, offering sophisticated simulation and progress-tracking capabilities throughout a project's lifecycle.
- Emerging Market Infrastructure:Underdeveloped markets in Southeast Asia and Latin America with major public infrastructure investment plans represent a substantial new growth frontier for IoT in construction solution providers.
Industry Challenges
- Data Integration Complexity:The primary operational challenge for contractors is the technical difficulty and cost associated with integrating diverse IoT data sources into a single, coherent dashboard for project oversight and decision-making.
- Skilled Labor Scarcity:A shortage of personnel with expertise in data science, network management, and IoT system implementation hampers the ability of construction companies to effectively deploy and leverage these technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global IoT in Construction Market |
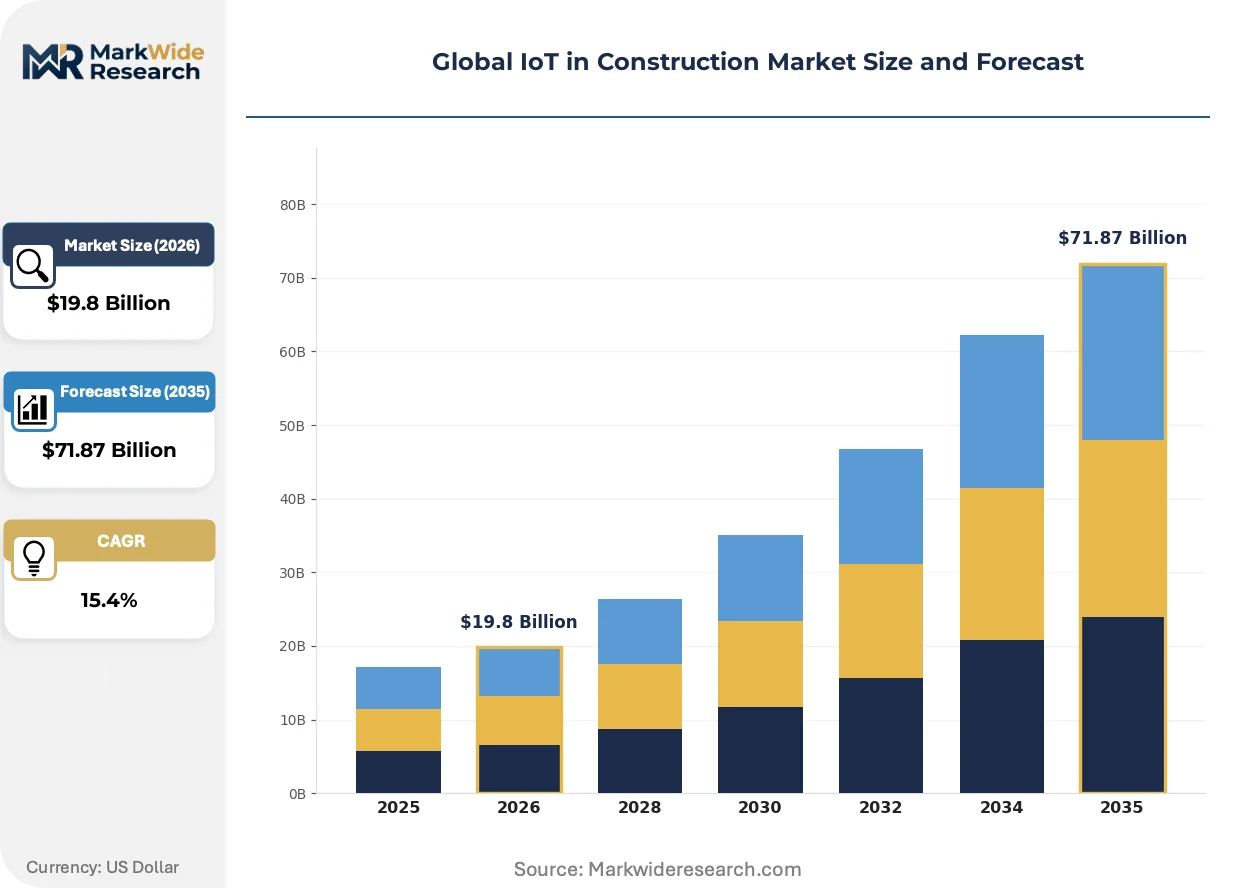
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $71.87 Billion |
| CAGR (2026 – 2036) | 15.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sensors, Asset Trackers, Wearable Devices, Environmental Monitors, Connectivity Modules Technology: LPWAN, 5G, Bluetooth Mesh, Zigbee, RFID Use Case: Equipment Management, Safety Monitoring, Predictive Maintenance, Resource Optimization, Quality Assurance End User Industry: General Contracting, Specialized Trade Contractors, Infrastructure Developers, Real Estate Developers, Facility Management |
| Companies Covered | WatchBuilt, Protechtio, Johnson Controls, Normal Software, InstaDigin, Siemens Smart Infrastructure, Pulse IoT Technologies, Checkton, Honeywell, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global IoT in Construction Market Strategic Shifts & Innovations
The market's evolution is defined by a move from basic data collection toward intelligent systems that provide predictive insights. This maturation reflects a shift from simply connecting assets to creating integrated digital ecosystems that model and manage the entire construction environment.
Digital twin technology, which creates a virtual replica of a physical asset or site, is a pivotal innovation. Large-scale commercial and infrastructure developers are the earliest adopters, using it to visualize project progress. This convergence of IoT sensor data with 3D models is digitizing traditional project management, replacing manual inspections with automated monitoring and analysis.
The ISO 55000 family of standards for asset management provides a globally recognized framework that is influencing IoT adoption. This standard promotes a structured, lifecycle approach to managing physical assets, encouraging the use of sensor data for maintenance and utilization tracking. Contractors pursuing certification are aligning their IoT strategies to meet these international benchmarks for operational efficiency.
A transition from outright hardware acquisition to subscription-based "Sensing-as-a-Service" models is becoming more common. This opex-based approach lowers the entry barrier for small and mid-sized contractors by reducing initial capital investment for sensor deployment. The model is most visible in North America for use cases like equipment fleet tracking and site environmental monitoring.
Global IoT in Construction Market Segmentation
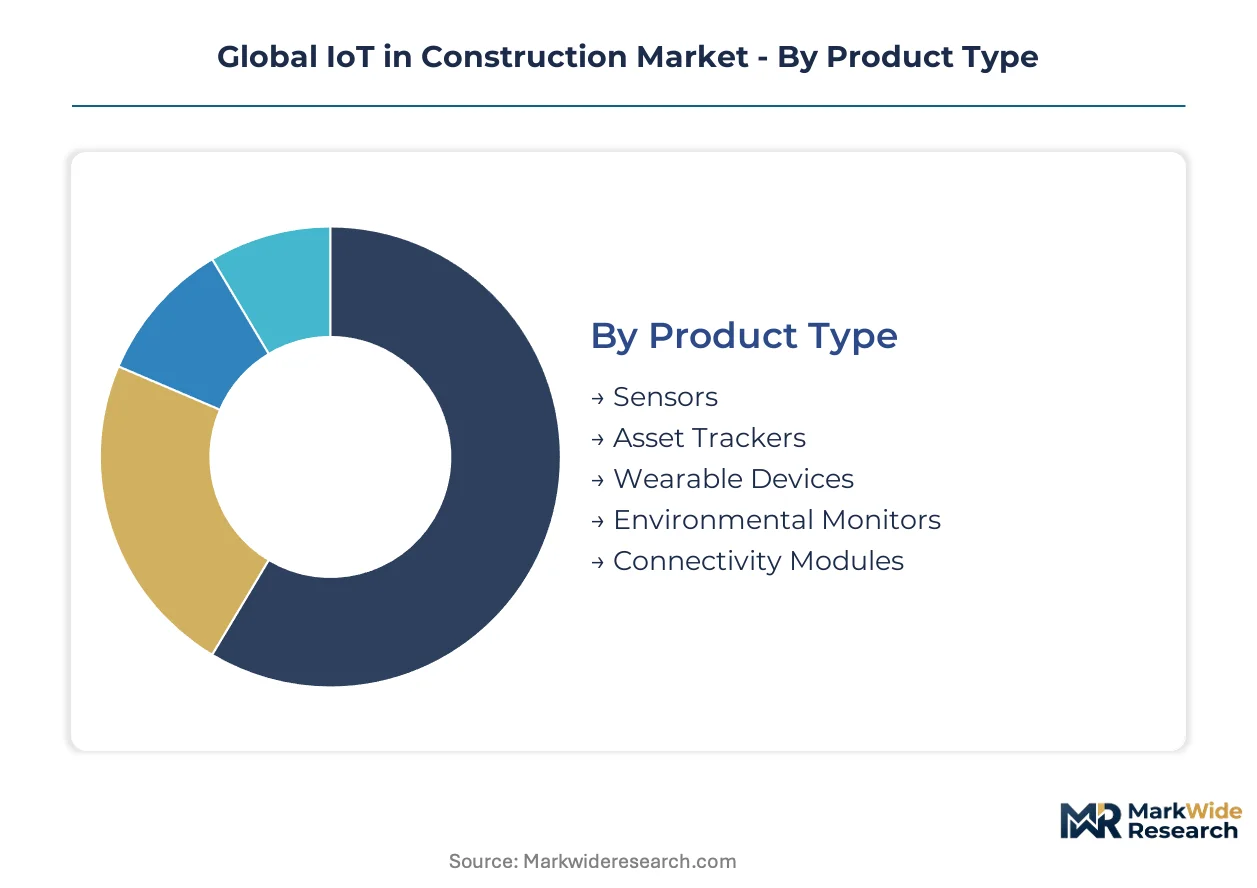
The IoT in construction market segments across various dimensions, reflecting the specialized nature of technologies and applications deployed on job sites. Understanding these distinct segments is crucial for solution providers to tailor offerings and for contractors to identify the most impactful deployments for their operational needs.
Product Type:
The product type segmentation addresses the diverse range of hardware solutions deployed across construction sites, each serving specific operational needs.
- Asset Trackers:These compact GPS or RFID-enabled devices are affixed to equipment, tools, and materials for real-time location and status monitoring. Demand concentrates among infrastructure developers seeking to optimize utilization and prevent loss of expensive machinery on large-scale projects.
- Sensors:Sensors encompass a broad category of devices measuring physical parameters like temperature, humidity, vibration, and structural integrity. Their application is critical in quality assurance and predictive maintenance, particularly within commercial building construction to ensure structural stability and material performance.
- Wearable Devices:These include smart helmets and vests monitoring worker biometrics and location for enhanced safety on hazardous sites.
- Environmental Monitors:Devices measure air quality, noise levels, and weather conditions, ensuring compliance with site regulations in urban developments.
- Connectivity Modules:These integrated components facilitate data transmission from IoT devices to central platforms, supporting seamless network operations.
The dominant share belongs to Asset Trackers, while Sensors are closing the gap fastest.
Technology:
Different technologies underpin IoT connectivity, each optimized for specific data transmission requirements and site conditions.
- 5G:5G technology provides ultra-high bandwidth and extremely low latency connectivity, supporting real-time video feeds and complex data analytics. Its deployment is crucial for large infrastructure projects in the United States, enabling drone-based inspections and real-time digital twin updates.
- LPWAN:Low-Power Wide-Area Network (LPWAN) protocols like LoRaWAN or NB-IoT enable long-range communication for battery-powered devices with minimal data throughput. These networks are widely adopted for asset tracking and environmental monitoring across expansive construction sites, minimizing power consumption.
- Bluetooth Mesh:This technology forms local, self-healing networks for device-to-device communication within confined areas.
- Zigbee:Often used for smart building automation, Zigbee offers low-power, short-range wireless connectivity for sensors and controls.
- RFID:Radio-Frequency Identification (RFID) tags provide passive identification and tracking of materials and tools within close proximity.
5G technology is gaining adoption rapidly, driven by the need for high-speed data, while LPWAN maintains a foundational role for widespread sensor deployment.
Use Case:
The maturity of IoT applications varies across construction activities, with some use cases establishing clear value propositions.
- Predictive Maintenance:Predictive maintenance leverages sensor data and analytics to forecast equipment failures, scheduling proactive repairs before breakdowns occur. This application reduces costly downtime and extends asset lifespans, concentrating demand among contractors managing extensive machinery fleets.
- Equipment Management:Equipment management involves real-time tracking of machinery location, utilization, and operational status to optimize asset deployment. Its widespread adoption by general contractors stems from direct cost savings through improved efficiency and reduced theft on project sites.
- Safety Monitoring:This includes geofencing, worker wearables, and environmental hazard detection, mandated by regulations like OSHA in the United States.
- Resource Optimization:IoT solutions help manage material flow, inventory levels, and labor allocation, minimizing waste and improving project timelines.
- Quality Assurance:Sensors monitor concrete curing, structural integrity, and environmental conditions, ensuring compliance with building codes and specifications.
Equipment Management holds a significant market share, while Predictive Maintenance is climbing fastest due to its direct impact on operational costs.
End User Industry:
The adoption of IoT solutions differs significantly across various types of construction industry participants, each with distinct operational needs.
- Infrastructure Developers:Infrastructure developers manage large-scale projects like roads, bridges, and utilities, requiring comprehensive oversight of dispersed assets and vast workforces. They are major adopters of IoT for real-time progress monitoring and asset utilization, driven by the need to control complex logistics and multi-year project timelines.
- General Contracting:General contractors oversee entire construction projects, coordinating various trades and managing overall site operations and project schedules. Their demand for IoT solutions spans equipment tracking, safety monitoring, and resource management, aiming to improve efficiency and reduce project risks across diverse building types.
- Specialized Trade Contractors:These firms focus on specific tasks like electrical, plumbing, or HVAC, using IoT for tool tracking and specialized equipment monitoring.
- Real Estate Developers:They integrate IoT for smart building features and long-term asset value, particularly in residential and commercial property developments.
- Facility Management:IoT extends into post-construction, enabling remote monitoring of building systems and predictive maintenance for operational efficiency.
Infrastructure Developers represent a substantial segment for IoT adoption, with General Contracting also showing a steep expansion trajectory as they integrate diverse solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infrastructure developers globally are concentrating their IoT investments on large-scale projects, seeking advanced monitoring and management solutions. This demand drives regional market expansion, particularly where significant public and private sector construction initiatives are underway. Regulatory frameworks and technological readiness also influence the pace of adoption across diverse geographies.
United States
Demand for real-time data transmission from thousands of sensors on large construction sites drives IoT adoption. OSHA guidelines directly influence the implementation of IoT-based safety monitoring systems for worker protection. Major infrastructure projects across states like California and Texas are early adopters of 5G-enabled IoT solutions.
Germany
The focus on predictive maintenance for heavy machinery and structural integrity monitoring fuels IoT deployment in construction. Europe's GDPR influences how worker location and biometric data are collected by wearables on job sites. Industrial clusters in Bavaria and North Rhine-Westphalia are integrating IoT with advanced building automation systems.
China
Large-scale infrastructure development, including high-speed rail and urban expansion, necessitates comprehensive project oversight through IoT. Government initiatives promoting smart city development encourage the use of connected construction technologies. Major construction hubs in the Yangtze River Delta are leveraging IoT for complex logistics and asset tracking.
India
Extensive public infrastructure investment plans, particularly in roads and urban development, are catalyzing demand for IoT solutions. The national government's "Smart Cities Mission" promotes the integration of digital technologies, including IoT, into new construction. Metropolitan areas like Mumbai and Delhi are seeing increased adoption of asset tracking and equipment management systems.
Brazil
Optimization of asset utilization and reduction of theft on expansive project sites drive the adoption of IoT in construction. Environmental regulations influence the use of IoT for monitoring site conditions and ensuring compliance. Major construction projects in São Paulo and Rio de Janeiro are implementing IoT for enhanced project management.
Global IoT in Construction Market Key Industry Players
Channel-controlling players compete with product-specialist players, creating a tiered market structure. The market exhibits fragmentation among niche solution providers and consolidation among established industrial technology firms. Strategic partnerships for data integration and portfolio diversification into analytics platforms represent dominant competitive moves.
Established industrial technology firms like Siemens Smart Infrastructure occupy a position leveraging their deep building automation expertise for integrated platforms. Honeywell extends its industrial control systems legacy into connected construction applications, providing comprehensive solutions. Pulse IoT Technologies, conversely, sits within the product-specialist tier, offering modular, use-case-specific solutions for equipment tracking and safety monitoring.
| Leading Market Players |
|---|
| WatchBuilt |
| Protechtio |
| Johnson Controls |
| Normal Software |
| InstaDigin |
| Siemens Smart Infrastructure |
| Pulse IoT Technologies |
| Checkton |
| Honeywell |
| Others |
Cost & Logistics Intelligence
Underutilized sensor production capacity in Southeast Asia currently drives aggressive pricing strategies among hardware component suppliers. This oversupply encourages vendors to bundle hardware with software subscriptions to secure recurring revenue streams.
Pricing Analysis
Cost-plus contracts with material cost indexation often govern large-scale IoT solution deployments for infrastructure developers. The dominant pricing model for many modular solutions is subscription-based "Sensing-as-a-Service," lowering initial capital expenditure for contractors. Price differentiation stems from the level of data analytics integration and the extent of after-sales support provided. Pricing softness reflects intense competition among niche solution providers and the commoditization of basic asset trackers. Small to medium-sized contractors exhibit the highest price sensitivity, preferring opex models.
Supply Chain Analysis
Single-source vulnerability for specialized semiconductor chips used in advanced sensors presents a significant supply chain risk. Geographic supply concentration for IoT hardware components primarily centers in China and Southeast Asia for manufacturing and assembly. The market relies on a steady flow of LPWAN modules and connectivity components. Distribution runs through direct sales channels for large infrastructure developers, while channel partners and system integrators serve smaller general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The IoT in construction market presents a significant service-attach opportunity, as advanced analytics platforms and predictive maintenance services are expanding faster than raw hardware sales. This shift allows providers to capture recurring revenue streams beyond initial device deployment.
For Market Incumbents: Harden existing integrated platforms by acquiring niche specialists focused on data integration solutions to counter market fragmentation. Established players like Siemens Smart Infrastructure must leverage their deep building automation expertise to offer comprehensive, unified dashboards. This strategy addresses the threat posed by specialized entrants offering modular, use-case-specific solutions. Investing in advanced analytics capabilities will reinforce their value proposition against commoditized hardware offerings.
For New Entrants and Emerging Players: Underpenetration in emerging markets like Southeast Asia and Latin America offers significant white-space opportunities for new entrants. These regions, with major public infrastructure investment plans, represent a penetrable segment for modular, cost-effective IoT solutions. Targeting small to medium-sized contractors with subscription-based "Sensing-as-a-Service" models lowers entry barriers and accelerates adoption. Focus on specific high-value use cases like predictive maintenance for heavy machinery.
For Investors and Strategic Acquirers: Capital is best deployed toward software-defined solution providers and advanced analytics platforms that can unify disparate IoT data streams. Long-term viability rests on companies capable of creating integrated digital ecosystems and dynamic digital twins for construction projects. Acquisition targets should be specialists in AI-driven predictive maintenance or robust data governance solutions. The signal to watch is the accelerating integration of IoT data with Building Information Modeling (BIM) platforms.
| Strategic Initiative | Industry Significance |
|---|---|
| Launch AI-powered Predictive Maintenance Platform | This initiative allows contractors to shift from reactive repairs to proactive equipment management, significantly reducing asset downtime. |
| Integrate Real-time IoT Data with BIM | Converging sensor data with 3D models creates dynamic digital twins, offering sophisticated simulation and progress tracking. |
| Form Strategic Partnerships with 5G Providers | Collaborations with network operators ensure high-bandwidth, low-latency connectivity essential for large-scale construction sites. |
| Acquire Data Integration Specialist Firms | Consolidating fragmented data streams from multiple IoT vendors into a unified project dashboard improves decision-making. |
| Expand into Emerging Infrastructure Markets | Targeting underdeveloped regions with major public investment plans unlocks substantial new growth frontiers for IoT solutions. |
Research Approach
Desk research of industry reports, company filings, and regulatory publications preceded structured interviews with project managers, construction technology leads, and equipment fleet managers. This primary research was complemented by secondary data from government infrastructure spending reports and technology vendor whitepapers. A rigorous bottom-up and top-down triangulation approach validated all findings.
Assumptions regarding 5G rollout trajectory, regulatory enforcement levels, and construction project scales were varied, while general economic stability was held fixed across the analysis window. The analytical framework modeled growth across product type, technology, use case, end-user industry, and regional infrastructure investment levels. Compound Annual Growth Rates were derived from historical adoption patterns and projected technology integration rates. Planned infrastructure project pipelines served as a key forecast input.
Macroeconomic conditions sit as an overlay; deviation in global interest rates or construction material costs would shift the trajectory. Forecasts reflect assumptions about technology adoption and regulatory stability. Unforeseen shifts in data privacy regulations or rapid technological obsolescence pose specific risk factors. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Big Data in Construction Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
Smart Airport Construction Market