
 Thailand Car Rental Market | 2026-2036
Thailand Car Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Car Rental Market Analytics
Asset-light leasing frameworks is tilting competitive dynamics toward operators who outsource fleet ownership to third-party financiers. Thai Rent A Car leverages its domestic network density to sustain pricing power in provincial airports. Hertz Corporation anchors its presence through partnerships with Thai hospitality chains. Chic Car Rent differentiates via localized customer service protocols that larger multinationals struggle to replicate.
Car rental denotes the short-term commercial provision of motorized passenger vehicles, typically governed by daily or weekly rate structures, collision damage waivers, and fuel policies, serving mobility needs for travelers without fixed-vehicle assets. The primary commercial purpose centers on monetizing fleet utilization across variable demand cycles driven by tourism flows and corporate travel budgets. Tourists dominate transaction volumes while business travelers command higher per-rental yields due to corporate account structures and premium vehicle preferences. Short-term rentals capture peak seasonal demand whereas long-term arrangements generate predictable recurring revenue with lower operational friction. Online booking channels now absorb the majority of reservations, compressing commission costs previously paid to travel agency intermediaries.
Thailand's Department of Land Transport enforces commercial vehicle registration and periodic inspection standards that dictate fleet replacement timelines and maintenance cost structures. The country's central bank monitors consumer credit conditions that influence both corporate fleet financing and tourist discretionary spending on mobility services. Stakeholders must track evolving emissions testing protocols and digital platform licensing requirements that could reshape fleet composition and channel economics.
Market Dynamics
Asset-light leasing frameworks are tilting competitive dynamics toward operators who outsource fleet ownership to third-party financiers, compressing capital requirements while fragmenting operational control across multiple stakeholder layers.
Growth Catalysts
- Bangkok Suvarnabhumi Airport expansion:International tourist arrivals through this hub drive fleet utilization rates upward during peak seasons, creating demand concentration that supports dedicated rental counters and streamlined pickup logistics.
- Department of Land Transport inspection mandates:Periodic commercial vehicle registration standards dictate fleet replacement timelines, accelerating turnover cycles and sustaining demand for newer model acquisitions across the rental pool.
- Digital nomad corridor formation:Phuket and Chiang Mai resort corridors attract extended-stay remote workers who generate recurring weekly rental volumes distinct from traditional tourist patterns.
Market Restraints
- Fleet financing cost volatility:Thailand's central bank monitors consumer credit conditions that directly influence corporate fleet financing spreads and tourist discretionary spending on mobility services.
- Emissions testing protocol uncertainty:Evolving inspection standards for commercial vehicles create compliance timeline ambiguity that delays fleet composition decisions and capital deployment.
- Platform licensing friction:Digital platform licensing requirements reshape channel economics by imposing operational constraints on online booking intermediaries that absorb reservation volume.
Strategic Opportunities
- Provincial airport network penetration:Thai Rent A Car leverages domestic network density to sustain pricing power in underserved provincial airports outside Bangkok's competitive core.
- Hospitality chain integration:Partnerships with Thai hospitality chains enable seamless pickup-dropoff coordination that captures inbound tourist flows before they reach urban rental counters.
- Localized service protocol differentiation:Customer service frameworks adapted to Thai language preferences and cultural expectations create retention advantages that standardized multinational operations struggle to replicate.
Industry Challenges
- Fleet maintenance skill scarcity:Commercial vehicle inspection standards require specialized technician certification that outpaces vocational training pipeline output in secondary cities.
- Legacy reservation system integration:Online booking channel migration demands API connectivity with property management systems used by hospitality partners, creating technical debt in older operator infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Car Rental Market |
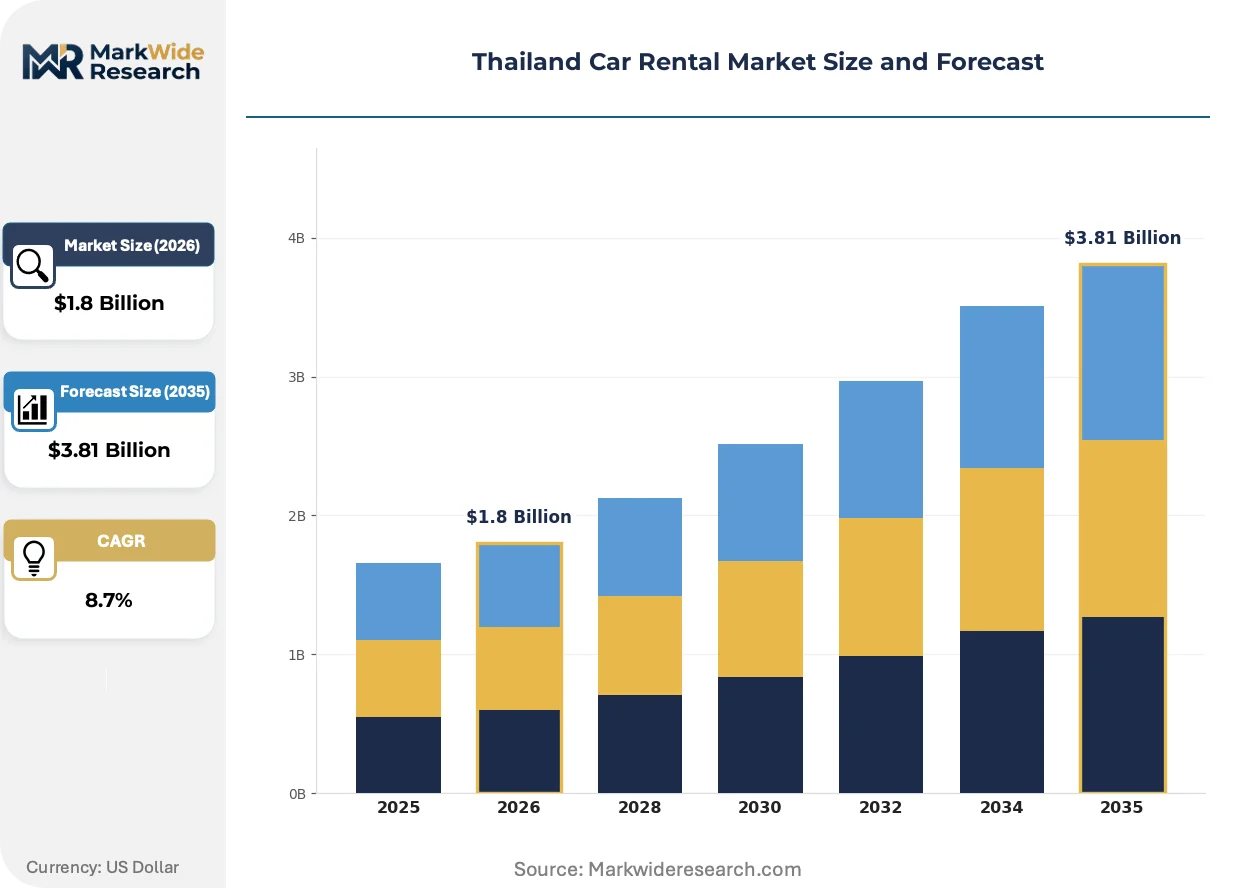
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Customer Type: Tourists, Business Travelers, Locals, Expats Rental Duration: Short-Term, Long-Term, Monthly, Weekly Vehicle Type: Economy, SUV, Luxury, Minivan Booking Channel: Online, Travel Agency, Direct, Phone |
| Companies Covered | Europcar Mobility Group, Thai Rent A Car, Sixt SE, Budget Thailand, Chic Car Rent, Hertz Corporation, Enterprise Holdings, Drive Car Rental, Avis Budget Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Car Rental Market Evolving Landscape
Telematics-enabled fleet management is actively compressing operational blind spots and reshaping how operators match vehicle availability to demand spikes across dispersed pickup locations.
Connected vehicle diagnostics is hybridizing maintenance scheduling by embedding real-time engine performance monitoring into rental fleet operations. Provincial operators with limited service bay capacity adopt these systems fastest. This technology is hybridizing traditional time-based inspection intervals with condition-triggered interventions, reducing unplanned downtime during peak tourist seasons.
Thailand's Department of Land Transport mandates commercial vehicle registration and periodic inspection standards that dictate fleet replacement timelines. These regulations compress depreciation schedules and accelerate capital recovery requirements for rental operators. Domestic fleet managers respond by shortening average holding periods and prioritizing models with proven inspection pass rates.
Digital nomad mobility patterns now dominate extended-stay rental demand in resort corridors, displacing traditional corporate account structures as the primary yield driver. Weekly rate structures replace daily pricing for stays exceeding fourteen days. Phuket and Chiang Mai rental counters witness this behavioral shift most acutely, with pickup volumes clustering around co-living property locations rather than airport terminals.
Thailand Car Rental Market Segmentation
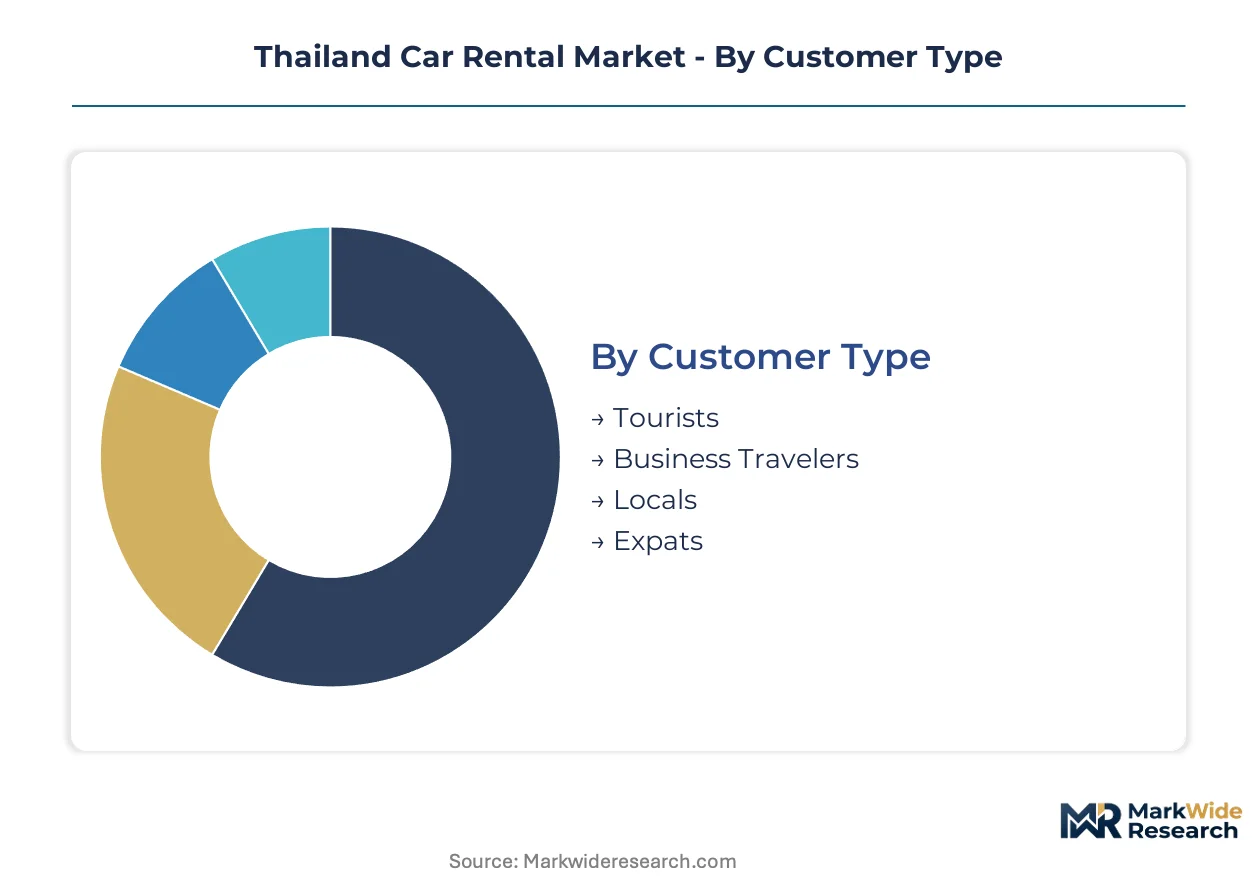
Segmentation in Thailand's car rental market reveals distinct utilization patterns across customer lifecycles and trip purposes. Fleet managers calibrate vehicle acquisition and depreciation schedules differently for each segment based on turnover velocity and yield per rental day.
Customer Type:
Cycle times vary dramatically across customer categories, with some segments turning fleet inventory weekly while others lock vehicles for months.
- Tourists:International arrivals through Bangkok Suvarnabhumi Airport and resort gateways dominate transaction volumes. Peak seasonal surges during November-February compress utilization cycles and strain counter capacity at Phuket and Chiang Mai terminals.
- Business Travelers:Corporate account structures command premium vehicle preferences and guaranteed availability clauses. This segment generates higher per-rental yields despite lower absolute transaction counts.
- Locals:Domestic users accessing replacement vehicles during repair periods or special events. Demand concentrates around urban centers with established service bay networks.
- Expats:Extended-stay foreign residents seeking flexible mobility without ownership commitment. Rental durations stretch across multiple months, reducing operational friction per transaction.
Tourists anchor the volume base while Expats gains share at the steepest rate.
Rental Duration:
Cost tier differentiation separates capital-light operators from those carrying full fleet ownership burdens across holding period structures.
- Short-Term:Daily and weekend rentals capturing impulse demand from airport arrivals. Highest operational friction per dollar of revenue due to frequent vehicle preparation and inspection cycles mandated by Thailand's Department of Land Transport.
- Long-Term:Multi-month arrangements favored by corporate relocations and extended-stay professionals. Predictable recurring revenue streams support leveraged fleet financing structures.
- Monthly:Digital nomad mobility patterns in Phuket and Chiang Mai resort corridors cluster around co-living property locations rather than airport terminals. Weekly rate structures replace daily pricing for stays exceeding fourteen days.
- Weekly:Intermediate duration bridging tourist and long-term demand. Operators optimize fleet allocation by converting excess short-term inventory when daily demand softens.
Short-Term rentals generate the highest transaction velocity while Monthly arrangements expand most quickly.
Vehicle Type:
Application context drives vehicle category selection, with terrain and passenger count requirements shaping fleet composition decisions.
- Economy:Compact sedans and hatchbacks dominate Bangkok urban circulation and budget-conscious tourist segments. Highest fleet turnover rates support accelerated depreciation schedules aligned with inspection mandates.
- SUV:Elevated ride height and luggage capacity attract families and resort corridor travelers. Phuket and Chiang Mai operators maintain disproportionate SUV allocation versus Bangkok-focused competitors.
- Luxury:Premium sedans and executive vehicles serve corporate account tiers and high-yield tourist segments. Lower utilization rates per vehicle are offset by substantially higher daily rates.
- Minivan:Multi-passenger configurations capture group travel demand from inbound tour operators. Seasonal demand spikes during peak tourist windows strain availability.
Economy vehicles anchor the volume base while SUV allocation gains share at the steepest rate.
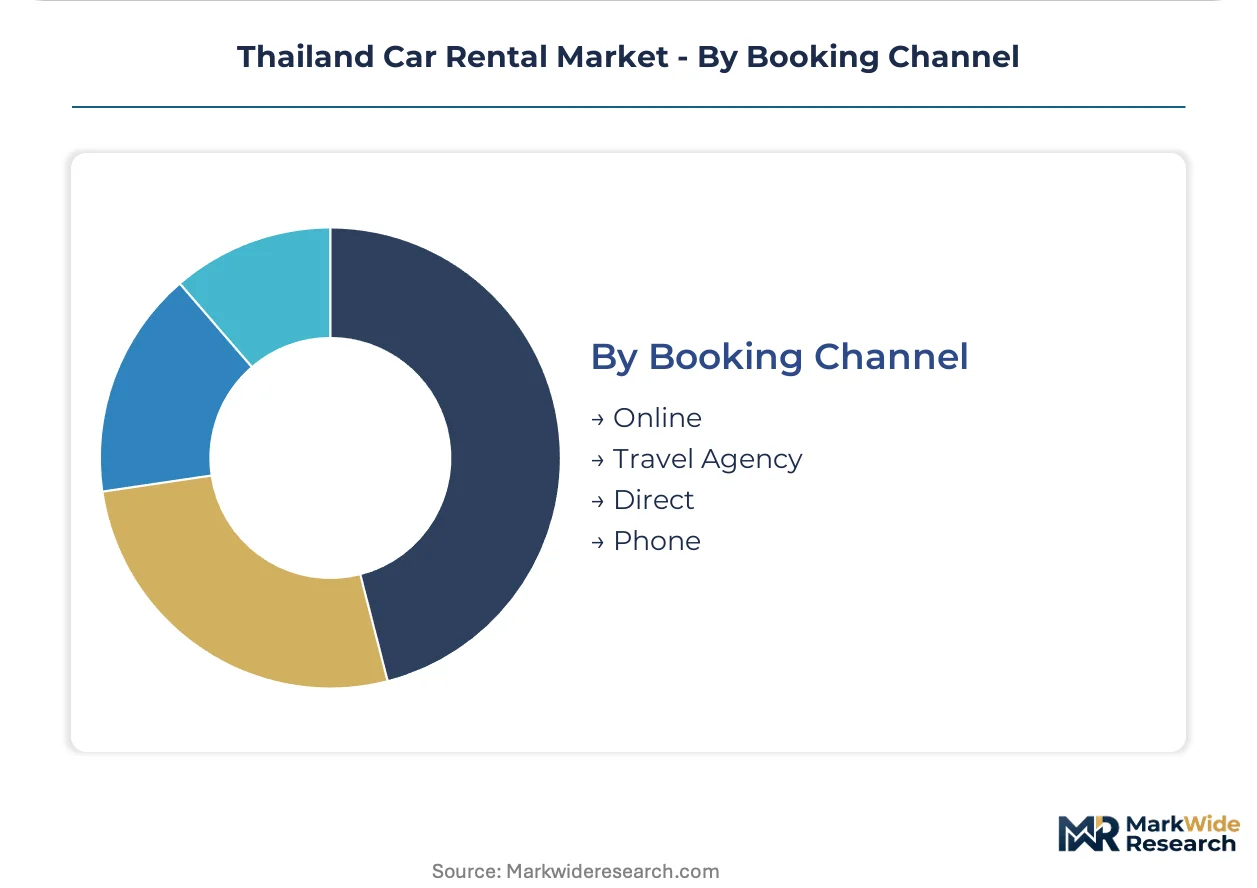
Booking Channel:
Channel economics fragment as digital intermediaries compress commission structures and reshape customer acquisition costs.
- Online:Direct platform reservations and aggregator interfaces now absorb majority booking volume. API connectivity demands create technical debt for operators with legacy reservation infrastructures.
- Travel Agency:Traditional intermediaries retain relevance for package tour operators and corporate travel management. Commission costs exceed digital channels but deliver pre-qualified customer segments.
- Direct:Walk-up counter transactions and repeat customer phone bookings. Highest margin capture but limited scalability beyond established physical presence.
- Phone:Voice-based reservations declining as smartphone penetration shifts preference toward app-based interfaces. Retained primarily for complex multi-vehicle arrangements or customer service escalations.
Online channels anchor the volume base while Direct booking gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok commands premium pricing power over provincial airports, while Phuket and Chiang Mai rental counters capture volume surges from resort corridor demand. Thailand's Department of Land Transport inspection mandates compress fleet replacement cycles differently across sub-regions based on enforcement intensity.
Bangkok Metropolitan Region
Suvarnabhumi Airport international arrivals drive peak-season utilization spikes that strain counter capacity. The Department of Land Transport enforces commercial vehicle registration standards most stringently here, accelerating turnover for rental fleets operating from Don Mueang and Suvarnabhumi terminals. Fleet managers in the capital maintain shorter average holding periods than provincial counterparts.
Phuket
Resort corridor formation attracts digital nomad mobility patterns that displace traditional tourist demand cycles. Weekly rate structures now dominate extended-stay bookings clustered around co-living properties rather than airport terminals. The island's rental operators allocate disproportionate SUV inventory to capture family and group travel segments.
Chiang Mai
Remote worker hubs generate recurring monthly rental volumes distinct from traditional tourism peaks. The Department of Land Transport mandates periodic inspections that shape fleet composition decisions for operators serving the digital nomad corridor. Northern operators face technician certification scarcity that extends maintenance turnaround times.
Pattaya Eastern Seaboard
Weekend impulse demand from Bangkok residents creates utilization volatility distinct from international tourist patterns. Corporate account structures from industrial estates generate predictable midweek demand that stabilizes revenue. Fleet financing spreads here track central bank consumer credit conditions more closely than resort markets.
Provincial Airports
Underserved secondary terminals offer pricing power to operators with domestic network density. Thai Rent A Car leverages established presence in Udon Thani, Khon Kaen, and Hat Yai to capture inbound flows before they reach urban rental counters. Maintenance skill gaps in secondary cities delay inspection compliance timelines.
Thailand Car Rental Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The Thailand car rental market structures around a consolidated international tier, a fragmented domestic operator layer, and emerging asset-light intermediaries. Three archetypes dominate: multinational hospitality-anchored platforms, domestic network-density specialists, and localized service protocol differentiators. Competitive moves concentrate on hospitality chain integration partnerships and telematics-enabled fleet management licensing.
Among multinational platform operators, Europcar Mobility Group and Sixt SE exemplify the hospitality-anchored archetype through established airport counter networks. Thai Rent A Car occupies a position within the domestic network-density tier, leveraging provincial airport penetration that international platforms struggle to replicate. Chic Car Rent represents the localized service protocol differentiator, emphasizing Thai-language customer frameworks that standardized multinational operations cannot easily mirror.
| Leading Market Players |
|---|
| Europcar Mobility Group |
| Thai Rent A Car |
| Sixt SE |
| Budget Thailand |
| Chic Car Rent |
| Hertz Corporation |
| Enterprise Holdings |
| Drive Car Rental |
| Avis Budget Group |
| Others |
Value Network & Pricing Analysis
Regulatory inspection chokepoints at Thailand's Department of Land Transport compress fleet replacement timelines and determine both capital recovery pricing spreads and supply chain configuration across domestic and import sourcing channels. Fleet operators calibrate holding period economics against compliance-driven turnover mandates that reshape vehicle acquisition patterns.
Pricing Analysis
Tourist segment buyers anchor three-tier pricing structure across premium, standard, and economy levels, with daily rate spreads widening during peak seasonal windows at Bangkok Suvarnabhumi and Phuket terminals. Price differentiation stems from vehicle age tier and hospitality partnership certification status, with newer fleet vintages commanding substantial premiums. Cost compression in economy tiers intensifies because asset-light leasing frameworks fragment operational control and compress margin capture. Corporate account travelers exhibit lowest price sensitivity due to guaranteed availability clauses and bundled insurance structures.
Supply Chain Analysis
Extended payment terms from Japanese and South Korean OEM supply-chain finance facilities enable fleet operators to manage working capital through inspection-mandated replacement cycles. Vehicle sourcing concentrates in Thailand, Japan, and South Korea, with domestic assembly plants feeding economy-tier demand and CBU imports serving premium segments. Raw material dependencies span semiconductor components for telematics systems, catalytic converter substrates, and tire rubber feedstocks. Single-source vulnerability sits with specialized diagnostic equipment for Department of Land Transport compliance testing. Distribution runs through airport counter networks, hospitality partner locations, and provincial terminal outposts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's car rental market operates as a defensive-moat story where regulatory entrenchment through Department of Land Transport inspection mandates creates sustainable barriers against asset-light entrants lacking compliance infrastructure.
For Market Incumbents: Build regulatory compliance moats by deepening technician certification pipelines in secondary cities and securing exclusive hospitality chain integration partnerships. Threat from digital platform intermediaries intensifies commission compression and customer disintermediation. Lever vertical integration into captive maintenance facilities to control inspection turnaround times and reduce third-party service dependency. For New Entrants and Emerging Players: Build out white-space penetration in underserved provincial airports at Udon Thani, Khon Kaen, and Hat Yai where network density specialists maintain pricing power. Digital nomad corridor demand in Chiang Mai co-living clusters offers most penetrable segment with monthly rate structures displacing traditional daily pricing. Pursue telematics-enabled fleet management licensing as differentiated go-to-market angle for asset-light market entry. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors domestic network-density specialists with established Department of Land Transport compliance infrastructure. Long-term viability rests on regulatory relationship depth and provincial counter footprint rather than brand recognition. Acquisition target archetype combines hospitality chain partnerships with telematics-enabled maintenance scheduling. Monitor digital platform licensing friction intensity as inflection indicator for channel economics disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Hospitality Chain Integration Partnership | Captures inbound tourist flows before urban rental counter access at Bangkok Suvarnabhumi and Phuket terminals. |
| Telematics Fleet Management Deployment | Compresses operational blind spots and matches vehicle availability to demand spikes across dispersed pickup locations. |
| Provincial Airport Network Expansion | Establishes pricing power in secondary terminals outside Bangkok's competitive core where density advantages accumulate. |
| Technician Certification Pipeline Investment | Addresses maintenance skill scarcity that delays Department of Land Transport inspection compliance in northern and northeastern regions. |
| Digital Platform API Integration | Reduces technical debt from legacy reservation systems and aligns with online booking channel migration patterns. |
Research Methodology
A standing panel of fleet operations directors, hospitality partnership managers, Department of Land Transport compliance officers, and provincial terminal operators provided ongoing calibration throughout the study. Primary interviews with rental counter supervisors and automotive finance specialists combined with secondary validation against Thailand customs vehicle import records, central bank consumer credit condition reports, and tourism authority arrival statistics. Bottom-up fleet size estimates triangulated against top-down market value assessments across the analysis window.
Scenario-bracketing framed demand projections across customer type, rental duration, vehicle category, and booking channel dimensions throughout the forecast period. CAGRs derived from segmented growth trajectory modeling incorporated digital nomad mobility pattern shifts, inspection mandate enforcement intensity variations by region, and hospitality chain partnership expansion rates. Industry-specific inputs included co-living property development pipelines in Phuket and Chiang Mai and telematics adoption curves among provincial operators.
The forecast holds incumbent behavior within observed patterns; aggressive fleet financing moves by multinational platform operators or rapid digital platform licensing liberalization would shift outcomes. Macroeconomic deviation in central bank credit conditions, emissions testing protocol acceleration, or telematics technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transportation Services
United States White Glove Delivery Service Market
Transportation Services
Scandinavia Car Rental Market
Transportation Services
Vehicle Management System Market
Transportation Services
Aerial Lift Rental Services Market
Transportation Services
Airline Passenger Service System Market
Transportation Services
Bird Carriers Market
Transportation Services
Global Moto Taxi Service Market
Transportation Services
India Car Rental Market
Transportation Services
Vacuum Truck Rentals Market
Transportation Services
Indonesia Car Rental Market
Transportation Services
Truck Sharing Market
Transportation Services
Russia Car Rental Market
Transportation Services
Ride-Hailing Service Market
Transportation Services
India Taxi Market
Transportation Services
Brazil Vehicle Rental Market
Transportation Services
Ship Management Software Market